
Market Overview:
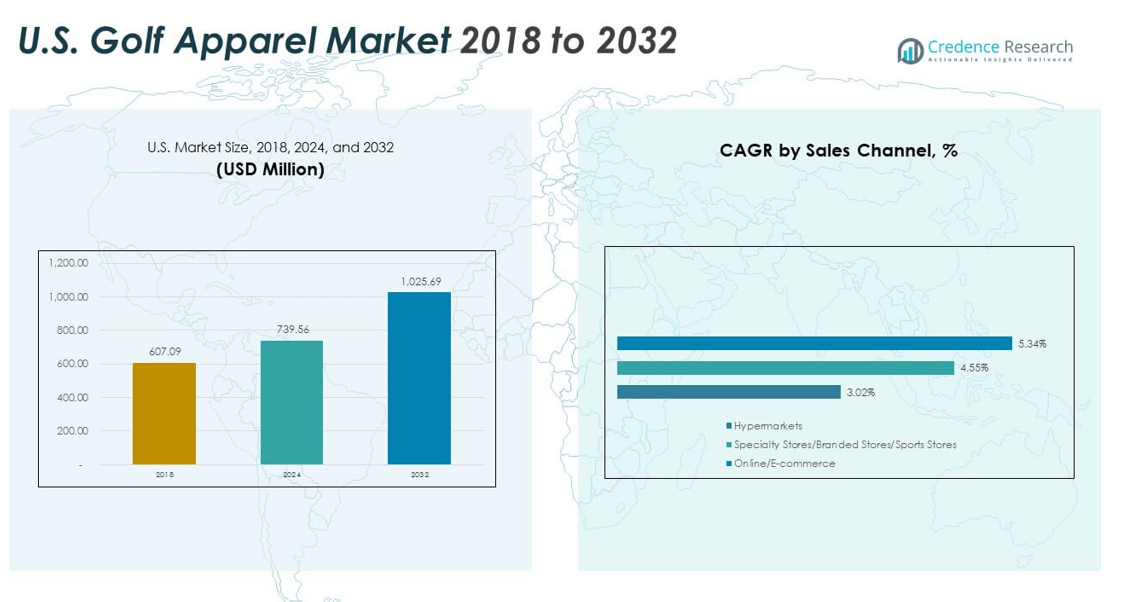
The U.S. Golf Apparel Market size was valued at USD 607.09 million in 2018 to USD 739.56 million in 2024 and is anticipated to reach USD 1,025.69 million by 2032, at a CAGR of 4.16% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Golf Apparel Market Size 2024 | USD 739.56 million |
| U.S. Golf Apparel Market, CAGR | 4.61% |
| U.S. Golf Apparel Market Size 2032 | USD 1,025.69 million |
The market is driven by a growing interest in golf as both a recreational activity and a professional sport, supported by rising participation rates across various age groups. Advancements in fabric technology, such as moisture-wicking and UV-protective materials, are enhancing product appeal. Fashion trends are increasingly influencing golf apparel designs, attracting a younger demographic and encouraging brand collaborations. The expansion of e-commerce platforms is also improving product accessibility and driving consumer engagement.
Regionally, the South leads the U.S. Golf Apparel Market, supported by a favorable climate, extensive golf course networks, and strong tourism-driven demand. The West follows, driven by luxury golf resorts, high-profile tournaments, and a style-conscious consumer base. The Midwest maintains steady growth through a large golfing community and seasonal championship events, while the Northeast benefits from high spending on premium brands despite a shorter playing season. Each region demonstrates distinct consumer preferences shaped by climate, culture, and retail access, creating diverse opportunities for apparel brands across the country
Market Insights:
- The U.S. Golf Apparel Market was valued at USD 739.56 million in 2024 and is projected to reach USD 1,025.69 million by 2032, growing at a CAGR of 4.16%.
- The Golf Apparel Market size was valued at USD 3,367.9 million in 2018 to USD 4,189.0 million in 2024 and is anticipated to reach USD 5,977.2 million by 2032, at a CAGR of 4.61% during the forecast period.
- Rising golf participation among diverse age groups and the influence of professional tournaments are driving consistent demand.
- Advancements in fabric technology, including moisture-wicking and UV protection, enhance performance and boost product appeal.
- High competition and market saturation among established brands create pricing pressures and reduce differentiation.
- Seasonal demand fluctuations and economic downturns impact sales cycles and inventory management.
- The South holds the largest share at 38%, followed by the West at 26%, with the Midwest and Northeast accounting for 19% and 17% respectively.
- Regional consumer preferences vary, with warmer states favoring breathable fabrics and colder regions prioritizing insulated apparel.
Market Drivers:
Rising Golf Participation and Expanding Consumer Base
The U.S. Golf Apparel Market benefits from a steady rise in golf participation across diverse demographics. Younger players are entering the sport, encouraged by inclusive initiatives and social engagement opportunities. It gains further momentum from the growing interest among women golfers, supported by targeted marketing campaigns and apparel designs. Golf’s popularity as a leisure activity and networking platform attracts corporate professionals, expanding the apparel customer base. National tournaments and televised events amplify the sport’s visibility, increasing demand for performance-driven clothing. Seasonal and year-round golfing in various states provides continuous sales opportunities. Apparel brands focus on catering to amateur and professional players alike. This diversified audience fuels consistent revenue growth.
Advancements in Fabric Technology and Performance Features
Technological innovations in textile manufacturing significantly enhance the U.S. Golf Apparel Market. Brands integrate moisture-wicking, UV-protection, and stretchable fabrics to improve player comfort and mobility. Performance-driven materials help regulate temperature, ensuring consistent comfort in varying weather. Consumers value these enhancements, leading to repeat purchases and higher brand loyalty. Collaborations with textile innovators enable apparel producers to stay ahead in quality and functionality. Sustainability-focused materials appeal to environmentally conscious buyers without compromising performance. Lightweight construction and ergonomic tailoring elevate the athletic appeal of the garments. It positions golf apparel as both a sports necessity and a lifestyle product.
- For example, Nike introduced Dri-FIT technology in 1991 as part of its FIT performance line, designed to wick sweat away from the skin to the fabric’s surface for faster evaporation and dryness. Many current Nike golf shirts, such as the Dri-FIT Victory Polo, are made from 100% recycled polyester and feature this moisture-management technology for comfort during play.
Influence of Fashion and Lifestyle Integration
Golf apparel increasingly reflects broader fashion trends, appealing to style-conscious players. The U.S. Golf Apparel Market sees brands merging athletic utility with contemporary design. Fashion-forward patterns, color palettes, and versatile cuts attract younger audiences seeking apparel suitable for both the course and casual settings. Cross-over styles encourage purchases beyond sports usage, widening revenue streams. Social media influencers and celebrity golfers play a strong role in promoting apparel collections. Luxury collaborations introduce premium golf clothing lines to high-spending segments. Retailers focus on seasonal collections to match lifestyle trends. This fusion of style and function broadens market penetration.
- For instance, Adidas has elevated its golf line by merging performance-driven fabrics with fashion-forward silhouettes via collaborations, such as the 2025 partnership with JAY3LLE, which introduced bold designs like pleated skorts and bomber jackets for women.
E-commerce Expansion and Retail Accessibility
The rapid growth of e-commerce significantly influences the U.S. Golf Apparel Market. Online retail platforms offer wide product variety, competitive pricing, and convenient delivery, enhancing customer reach. Direct-to-consumer sales models allow brands to build stronger relationships and gather purchase data for targeted marketing. Integration of virtual fitting tools and AI-based recommendations improves the shopping experience. Multi-channel retail strategies ensure brand presence across online, specialty golf stores, and sports outlets. Exclusive online product launches create urgency and boost sales. Improved logistics and return policies enhance consumer trust. It strengthens the market’s overall accessibility and revenue potential.
Market Trends
Sustainable and Eco-Friendly Apparel Development
A growing shift toward sustainability is reshaping the U.S. Golf Apparel Market. Brands are adopting organic cotton, recycled polyester, and water-efficient production techniques to reduce environmental impact. Eco-friendly packaging complements this commitment, appealing to green-conscious consumers. Certifications and transparency in sourcing enhance trust among buyers. Sustainability messaging becomes a core part of branding strategies, influencing purchase decisions. Partnerships with environmental organizations strengthen brand image and outreach. Innovation in biodegradable fabrics introduces new competitive advantages. The trend creates a balance between performance, style, and environmental responsibility.
Integration of Smart and Wearable Technology
Technological integration is emerging as a defining trend in the U.S. Golf Apparel Market. Wearable sensors embedded in clothing track player performance metrics such as swing speed and posture. Smart fabrics adapt to body temperature and weather conditions, enhancing comfort. Bluetooth-enabled accessories connect apparel to mobile devices for data analysis. Golfers seeking performance improvement are early adopters of such innovations. Collaborations between apparel brands and tech companies accelerate product development. The combination of athletic wear and data-driven insights provides a distinctive value proposition. This fusion enhances both competitive play and recreational enjoyment.
Personalization and Customization Demand
Consumer preference for personalization is growing rapidly in the U.S. Golf Apparel Market. Brands offer customized fits, embroidery, and color selections to meet individual tastes. Golf clubs and corporate groups order bespoke apparel for branding and events. Customization enhances consumer loyalty by creating unique ownership experiences. Digital tools allow customers to visualize designs before purchase, improving satisfaction rates. Limited-edition collections with personalization options generate exclusivity appeal. Professional players endorsing personalized gear inspire adoption across amateur circles. This trend deepens brand-consumer engagement and drives premium pricing.
- For example, Under Armour provides corporate customization services for polos and other apparel, offering sizes from XS to 4XL with options for embroidered or printed branding. Through authorized retailers and online design platforms, customers can upload logos, select products, and create personalized designs for individuals, teams, and corporate groups.
Athleisure Influence on Golf Apparel Designs
The rise of athleisure is impacting the U.S. Golf Apparel Market’s design direction. Golf clothing is now designed for multifunctional use, blending sports performance with everyday wearability. Stretch fabrics, relaxed fits, and modern styling make apparel suitable beyond the course. This versatility attracts non-golfing consumers interested in sports-inspired fashion. Retailers showcase golf apparel alongside lifestyle collections to tap into wider audiences. The athleisure trend reduces the gap between sportswear and casual wear. It creates opportunities for brands to expand into lifestyle apparel markets while maintaining golf-specific performance attributes.
- For example, Adidas’s Ultimate365 Golf line features stretch fabrics and relaxed-fit designs that combine moisture-wicking technologies and water-resistant finishes for seamless performance both on and off the course. Their Primeknit polos elevate comfort and breathability, while the brand’s spikeless golf shoes offer traction and style suited for versatile wear.
Market Challenges Analysis
High Competition and Market Saturation
The U.S. Golf Apparel Market faces intense competition from established brands and emerging labels. Premium and mid-tier players compete for similar consumer segments, creating pricing pressure. High product similarity reduces differentiation, making brand loyalty harder to sustain. Frequent discounting strategies by large retailers erode profit margins. Market saturation in mature segments limits rapid expansion opportunities. The challenge intensifies with international brands entering the U.S. market through e-commerce platforms. Consumer demand for innovation forces continuous investment in R&D. It raises operational costs and compresses profitability for smaller players.
Seasonality and Economic Sensitivity
The U.S. Golf Apparel Market is affected by seasonal demand patterns tied to weather conditions. Harsh winters or prolonged rains in key golfing regions can reduce apparel sales. Economic downturns impact discretionary spending, leading to reduced purchases of non-essential sportswear. Luxury and premium apparel categories are especially vulnerable to consumer spending cuts. Inventory management becomes challenging during fluctuating demand cycles. Seasonal product lines risk overstock or understock issues. Brands dependent on in-person sales face additional hurdles during travel or event restrictions. It emphasizes the importance of diversified retail channels to mitigate these risks.
Market Opportunities
Growth in Emerging Golfer Demographics
An expanding demographic of younger and more diverse golfers presents new opportunities for the U.S. Golf Apparel Market. Outreach programs, school golf initiatives, and urban golfing facilities are encouraging participation. Apparel brands can design collections targeting these new players with modern styles and accessible price points. Collaborations with influencers and digital platforms extend market visibility. Women’s golf continues to grow, creating scope for gender-specific designs. The opportunity lies in building brand loyalty early through targeted campaigns. It allows brands to shape long-term purchasing habits.
Expansion in International Tourism and Golf Resorts
Golf tourism offers a promising growth avenue for the U.S. Golf Apparel Market. Destination resorts and luxury golfing experiences create demand for premium apparel lines. International visitors seek high-quality branded clothing as part of their travel experience. Exclusive collections tied to resort branding can generate significant sales. Events hosted at tourist destinations drive merchandising opportunities. Brands that partner with resorts gain exposure to affluent and global audiences. It strengthens brand positioning while opening new revenue channels.
Market Segmentation Analysis:
By apparel type, the U.S. Golf Apparel Market features diverse product categories catering to performance, comfort, and style. T-shirts hold a strong share due to their versatility, breathability, and use in both casual and professional golfing. Trousers remain essential for formal golfing attire, while shorts and skirts appeal to warmer weather and modern style preferences. Winter wear supports year-round participation in colder regions, incorporating thermal and weather-resistant materials. Footwear serves a critical role in enhancing grip, comfort, and stability, while the ‘others’ category includes accessories that complement overall apparel sales.
- For instance, Galvin Green’s INTERFACE-1 outerwear range is designed as a hybrid solution for golfers, offering windproof and water-repellent polyester with breathable, stretchy construction. Pieces like the Leonard jacket incorporate Thermore® padding for added warmth while maintaining flexibility and comfort in cold, blustery conditions.
By end user, men account for the largest share, supported by their long-standing dominance in golf participation and spending patterns. Women represent a growing segment, driven by increased engagement in the sport and expanding product lines tailored to female golfers. Kids form a niche but steadily expanding category, fueled by youth golf programs, school-level tournaments, and parental investment in early skill development.
- For example, Garb Inc., founded in 1996 as the original junior golf apparel brand, is a leading supplier of children’s golf clothing. The company has been the primary kids’ apparel provider for major events such as the U.S. Open, PGA Championship, and Ryder Cup since 2001, reinforcing its strong presence in youth golf.
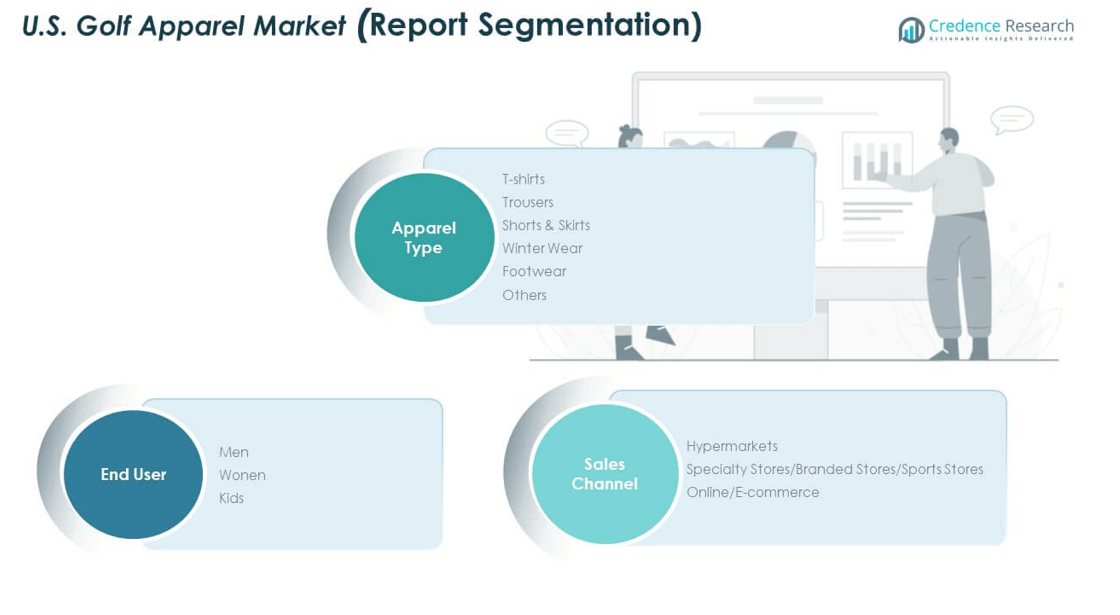
By sales channel, specialty stores, branded outlets, and sports stores lead in value share due to their ability to offer personalized service, premium collections, and exclusive product lines. Hypermarkets maintain steady demand by providing convenience and competitive pricing. Online channels are experiencing rapid growth, driven by ease of access, expanded product variety, and digital marketing campaigns targeting younger and tech-savvy consumers. This diversified distribution structure ensures strong market accessibility across urban, suburban, and regional golfing communities.
Segmentation:
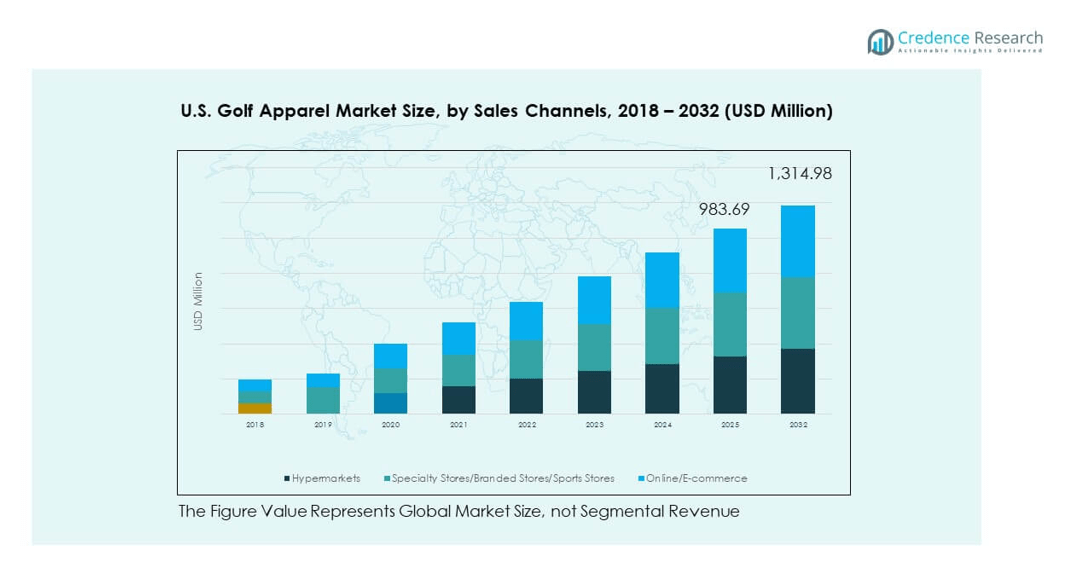
By Apparel Type
- T-shirts
- Trousers
- Shorts & Skirts
- Winter Wear
- Footwear
- Others
By End User
- Men
- Women
- Kids
By Sales Channel
- Hypermarkets
- Specialty Stores/Branded Stores/Sports Stores
- Online/E-commerce
Regional Analysis:
The South region commands the largest share of the U.S. Golf Apparel Market at nearly 38%, driven by its year-round golf-friendly climate and a dense network of courses in states such as Florida, Texas, and Georgia. This region benefits from a high concentration of golf resorts, professional tournaments, and affluent retirement communities that actively participate in the sport. Consumer spending on premium golf apparel is strong, supported by tourism and a steady influx of visiting golfers. Retailers in the South leverage both specialty stores and resort-based outlets to capture demand. Seasonal product variation is minimal, enabling consistent sales throughout the year. It remains the core hub for both domestic and visiting golfers seeking high-quality apparel.
The West accounts for approximately 26% of the market share, supported by diverse golfing landscapes in states like California, Arizona, and Nevada. The region’s blend of luxury golf resorts, celebrity-driven events, and high-profile tournaments boosts apparel sales. Warm climates encourage demand for breathable, moisture-wicking fabrics, while cooler highland areas sustain sales of lightweight winter gear. The West attracts a mix of professional players, tourists, and recreational golfers, creating varied product demand. Retail presence is strong in urban centers and resort destinations, with online sales growing rapidly. It benefits from an image-driven consumer base that values both performance and style.
The Midwest and Northeast collectively hold 36% of the market share, with the Midwest contributing 19% and the Northeast 17%. The Midwest’s large golfing community and hosting of championship events maintain strong seasonal demand for both summer and transitional weather apparel. The Northeast’s market is shaped by a shorter golfing season but higher spending on premium brands, driven by affluent urban consumers in states like New York, Massachusetts, and Pennsylvania. Both regions experience significant seasonal spikes, requiring retailers to manage inventory cycles strategically. Specialty stores and golf clubs serve as primary sales channels, supplemented by e-commerce during off-season months. It relies on aligning product availability with the peak playing season to sustain revenue.
Key Player Analysis:
- Amer Sports
- Roger Cleveland Golf Company Inc
- Golfsmith International Holdings Inc
- Dixon Golf Inc.
- Perry Ellis
- Fila
- Ralph Lauren
- Oxford Golf
- Sunice
- EP NY
- Other Key Players
Competitive Analysis:
The U.S. Golf Apparel Market features a competitive landscape dominated by established global brands and specialized golf apparel companies. Key players such as Amer Sports, Ralph Lauren, Perry Ellis, and Fila leverage strong brand recognition, diverse product portfolios, and strategic endorsements to maintain market leadership. Competition centers on innovation in fabric technology, style integration, and sustainable production. Mid-tier and emerging brands compete by offering cost-effective yet performance-oriented products, targeting niche segments. E-commerce platforms intensify competition by enabling smaller brands to access broader audiences. Retail partnerships, athlete sponsorships, and product customization strengthen brand positioning. It remains a dynamic market where differentiation through quality, design, and marketing drives competitive advantage.
Recent Developments:
- In July 2025, Flag & Anthem, a premium U.S. apparel brand known for its versatile golf collections, entered a strategic partnership with RepSpark. This collaboration aims to streamline wholesale ordering for golf shops, boutiques, resorts, and specialty retailers, enhancing the brand's presence in the golf sector.
- In July 2025, Nike Golf launched a special trio of golf sneakers the Victory Tour 4, Air Zoom Infinity Tour 2, and Air Max 90 Golf in celebration of The Open Championship. The limited-edition footwear features a distinctive white and metallic gold design, honoring the legacy of the championship.
- In May 2025, Amer Sports reached an agreement to acquire the land, building, and machinery of its trusted manufacturing partner Savrom, marking a significant strategic step by bringing Alpine binding production back in-house through the acquisition of a new Romanian facility.
Market Concentration & Characteristics:
The U.S. Golf Apparel Market exhibits moderate to high concentration, with a few leading players capturing significant revenue share. It is characterized by brand-driven competition, seasonal product cycles, and strong influence from professional golf events. Innovation, style diversity, and sustainability commitments are critical to retaining consumer loyalty. The market blends premium, mid-tier, and value segments, supported by both offline specialty retail and rapidly expanding e-commerce channels. Consumer preferences are shaped by performance features, brand endorsements, and fashion alignment with broader lifestyle trends. Strategic marketing tied to tournaments and celebrity golfers enhances brand visibility. It continues to evolve as brands balance functional performance with aesthetic appeal to address a diverse golfing population.
Report Coverage:
The research report offers an in-depth analysis based on Apparel Type, End User and Sales Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Expansion of eco-friendly and recycled material usage will strengthen brand positioning among environmentally conscious consumers.
- Growth in youth and women’s golf participation will broaden the target audience for apparel collections.
- Technological integration in fabrics, such as temperature regulation and enhanced stretch, will improve performance appeal.
- Increased personalization and made-to-order apparel options will drive customer loyalty and premium sales.
- Strategic collaborations with luxury fashion brands will elevate style influence within the sport.
- Rising popularity of golf tourism and resort-based experiences will create opportunities for exclusive apparel lines.
- Enhanced online retail capabilities and virtual try-on tools will improve purchase confidence and reach.
- Seasonal product innovation tailored to regional climates will optimize inventory turnover and sales cycles.
- Greater emphasis on inclusive sizing and adaptive designs will cater to a more diverse golfing population.
- Sponsorship of professional tournaments and player endorsements will continue to boost market visibility and consumer engagement.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Golf Participation Across Demographics
Increasing interest in golf among younger players, women, and diverse age groups is expanding the consumer base for golf apparel, supported by outreach programs and the sport’s growing popularity as a leisure and networking activity.
Advancements in Fabric Technology
Innovations such as moisture-wicking, UV-protective, and stretchable fabrics are enhancing comfort and performance, driving repeat purchases and brand loyalty among both amateur and professional golfers.
Fashion and Lifestyle Integration
The influence of contemporary fashion trends and athleisure is making golf apparel more versatile and appealing to younger, style-conscious consumers, encouraging purchases for both on-course and everyday wear.
E-commerce and Retail Accessibility
The rapid expansion of online retail platforms, direct-to-consumer models, and virtual fitting tools is improving product accessibility, broadening reach, and driving higher engagement, especially among tech-savvy and younger buyers.
Sustainability and Eco-Friendly Initiatives
Growing consumer demand for sustainable and eco-friendly apparel is prompting brands to adopt recycled materials and transparent sourcing, strengthening brand positioning among environmentally conscious golfers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for U.S. Golf Apparel Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the U.S. Golf Apparel Market projected to grow between 2024 and 2032?
What are the primary factors fueling the growth of the U.S. Golf Apparel Market
Who are the leading companies in the U.S. Golf Apparel Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Men
- 1.2.2 Women
- 1.2.3 Kids
- 1.3 By Apparel Type
- 1.3.1 T-shirts
- 1.3.2 Trousers
- 1.3.3 Shorts & Skirts
- 1.3.4 Winter Wear
- 1.3.5 Footwear
- 1.3.6 Others
- 1.4 By Sales Channel
- 1.4.1 Hypermarkets
- 1.4.2 Specialty Stores/Branded Stores/Sports Stores
- 1.4.3 Online/E-commerce
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 739.56 million → 2032: USD 1,025.69 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Golf Apparel Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Golf Apparel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Golf Apparel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Golf Apparel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Golf Apparel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Golf Apparel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Golf Apparel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Golf Apparel Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 739.56 million → 2032: USD 1,025.69 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Golf Apparel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Men
- 12.3.7.2 Women
- 12.3.7.3 Kids
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Apparel Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 T-shirts
- 12.4.7.2 Trousers
- 12.4.7.3 Shorts & Skirts
- 12.4.7.4 Winter Wear
- 12.4.7.5 Footwear
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hypermarkets
- 12.5.7.2 Specialty Stores/Branded Stores/Sports Stores
- 12.5.7.3 Online/E-commerce
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Golf Apparel End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 U.S. Golf Apparel Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 U.S. Golf Apparel Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 U.S. Golf Apparel Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amer Sports
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ralph Lauren
- 18.4 Perry Ellis
- 18.5 Fila
- 18.6 Nike
- 18.7 Adidas
- 18.8 Oxford Golf
- 18.9 Sunice
- 18.10 EP NY
- 18.11 Roger Cleveland Golf Company Inc
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

