
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
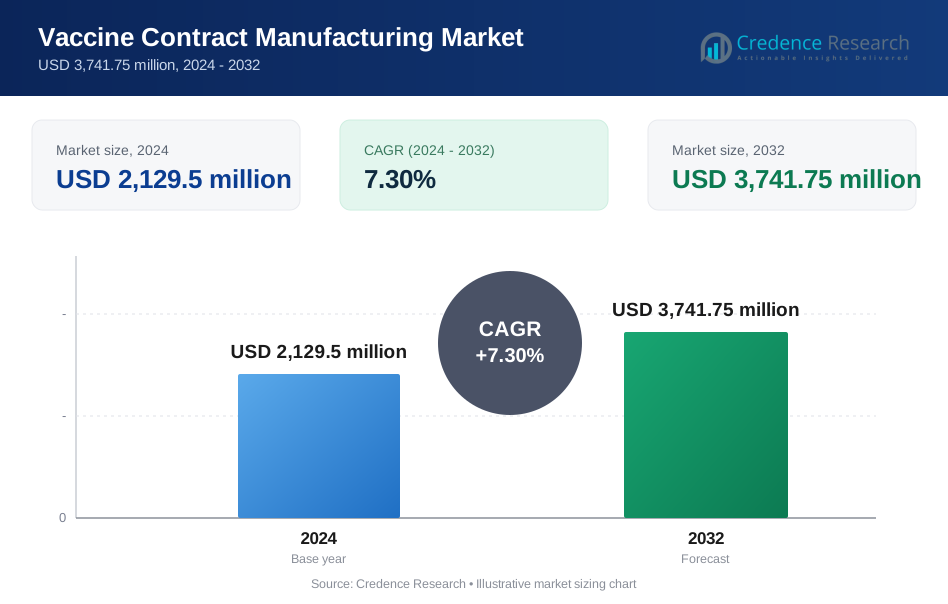
| Vaccine Contract Manufacturing Market Size 2024 | USD 2,129.5 Million |
| Vaccine Contract Manufacturing Market, CAGR | 7.30% |
| Vaccine Contract Manufacturing Market Size 2032 | USD 3,741.75 Million |
Market Overview
The Vaccine Contract Manufacturing Market is projected to grow from USD 2,129.5 million in 2024 to USD 3,741.75 million by 2032, with a compound annual growth rate (CAGR) of 7.30%.
The vaccine contract manufacturing market is driven by the rising demand for vaccines due to increasing prevalence of infectious diseases, advancements in biotechnology, and government initiatives supporting immunization programs. Outsourcing vaccine production to contract manufacturers allows pharmaceutical companies to focus on core activities while reducing costs and expediting time-to-market. Moreover, technological advancements in biologics manufacturing and the growing trend towards personalized vaccines are fueling market growth. The need for rapid and large-scale production during pandemics, such as COVID-19, further highlights the importance of contract manufacturing in ensuring global vaccine availability and supply chain efficiency.
The vaccine contract manufacturing market is geographically dominated by North America and Asia-Pacific, which together account for a significant share of global production. North America, particularly the U.S., leads due to its advanced biotechnology infrastructure and regulatory support, while Asia-Pacific, driven by cost-effective manufacturing in countries like India and China, is rapidly expanding. Key players in this market include Lonza Group AG, Catalent, Inc., Emergent BioSolutions Inc., Fujifilm Holdings Corporation, and Recipharm AB. These companies, along with others like Syngene International and Bavarian Nordic A/S, are driving innovation and large-scale vaccine production to meet global demand.
Market Drivers
Increased Demand for Vaccines
The rising prevalence of infectious diseases, such as COVID-19, influenza, and other emerging pathogens, has significantly driven the demand for vaccines worldwide. As global health threats continue to evolve, the need for effective immunization strategies has intensified. Governments and healthcare organizations are expanding immunization programs to prevent the spread of these diseases, emphasizing vaccination as a critical public health measure. For instance, the CDC’s Partnering for Vaccine Equity (P4VE) program focuses on increasing equity in adult immunization, providing funding and support to national, state, local, and community partners. This surge in vaccine demand is encouraging pharmaceutical companies to scale production, often turning to contract manufacturers to meet this growing requirement efficiently.
Advancements in Vaccine Technology
Technological advancements in vaccine development are further propelling the vaccine contract manufacturing market. The success of mRNA vaccines during the COVID-19 pandemic has revolutionized the field, opening new possibilities for rapid and scalable vaccine production. For instance, microarray patches have the potential to revolutionize accessibility by allowing vaccines to be delivered virtually anywhere without the need for cold storage. Additionally, novel vaccine platforms such as viral vectors and DNA vaccines are gaining momentum, offering innovative approaches to combat various infectious diseases. These advancements not only enhance the efficacy and speed of vaccine development but also drive the need for specialized contract manufacturers capable of handling cutting-edge technologies.
Outsourcing and Cost-Efficiency
Pharmaceutical companies are increasingly outsourcing vaccine production to contract manufacturers to address capacity constraints and enhance cost-efficiency. Many companies lack the infrastructure, expertise, or resources to meet the growing global demand for vaccines. Contract manufacturing organizations (CMOs) provide the necessary capabilities, enabling faster production while reducing operational costs. This approach allows pharmaceutical companies to focus on core research and development activities, while CMOs manage large-scale production and ensure regulatory compliance, further accelerating market growth.
Government Support and Investments
Government support and investments in vaccine development are crucial drivers in the contract manufacturing market. Public-private partnerships are being established to enhance pandemic preparedness and strengthen global health security. Governments are also providing regulatory frameworks and financial incentives to encourage vaccine manufacturing. These measures are designed to ensure the availability of vaccines during critical times, particularly in response to public health emergencies, and to promote equitable access to vaccines across both developed and developing nations.
Market Trends
Increased Focus on mRNA Vaccines and Cold Chain Expansion
The vaccine contract manufacturing market is witnessing a significant focus on mRNA vaccine technology, driven by ongoing advancements in research and development. The success of mRNA vaccines during the COVID-19 pandemic has highlighted their versatility and rapid adaptability, allowing manufacturers to target emerging pathogens with speed and precision. For instance, a recent survey by the World Health Organization (WHO) indicated that mRNA vaccines have shown promising results in clinical trials for various infectious diseases, including influenza and Zika virus. As mRNA technology continues to evolve, it offers immense potential for addressing various infectious diseases, positioning it as a critical component of pandemic preparedness strategies. Additionally, the expansion of cold chain infrastructure is becoming essential to support the global distribution of vaccines, especially to underserved and remote areas. Investments in advanced cold chain technologies, including temperature-controlled packaging and real-time monitoring systems, are improving the safe storage and transportation of vaccines. This infrastructure is crucial for maintaining vaccine efficacy, ensuring that vaccines reach even the most distant regions with minimal spoilage or delays.
Partnerships, Regionalization, and Digitalization for Efficiency and Sustainability
Strategic partnerships and collaborations are playing a pivotal role in accelerating vaccine development and manufacturing. Governments and pharmaceutical companies are forming public-private partnerships to enhance production capacity and respond more effectively to global health challenges. Additionally, collaborations between academic institutions and contract manufacturers are fostering innovation, helping to bring new vaccine technologies to market more rapidly. In parallel, the regionalization of manufacturing is gaining traction as companies seek to diversify their production facilities across different regions. This strategy aims to reduce reliance on centralized hubs, thereby improving supply chain resilience and addressing specific local market needs and regulatory requirements. At the same time, digitalization and automation are transforming vaccine manufacturing processes, leading to increased efficiency and enhanced quality control. The integration of digital tools, such as data analytics and automated systems, is streamlining production workflows and improving compliance efforts. Alongside these advancements, there is a growing emphasis on sustainability, with contract manufacturers adopting green manufacturing practices, including energy-efficient processes and ethical sourcing of materials, to minimize environmental impact.
Market Challenges Analysis
Supply Chain Disruptions and Cost Pressures
Supply chain disruptions present another major challenge for vaccine contract manufacturers, with global events like geopolitical tensions, natural disasters, and economic instability often affecting the availability of raw materials and critical components. These disruptions can lead to production delays, increased costs, and challenges in maintaining consistent supply. For instance, a report by the International Federation of Pharmaceutical Manufacturers & Associations (IFPMA) noted that the COVID-19 pandemic caused significant disruptions in the supply chain, affecting the availability of essential raw materials. Moreover, logistics challenges, particularly in ensuring the safe and timely transportation of vaccines requiring cold chain storage, complicate distribution efforts. Cold chain management is essential for preserving vaccine efficacy, but it adds complexity to global vaccine supply. In addition, manufacturers face intense cost pressures due to competition in the marketplace, which drives down prices and makes it difficult to maintain profitability. Controlling operational costs, including raw materials, labor, and overhead, is vital for long-term success in this highly competitive sector. At the same time, keeping pace with rapid technological advancements in vaccine manufacturing requires significant investments in innovation, presenting both opportunities and risks as companies balance costs with the need to adopt emerging technologies.
Regulatory Hurdles and Capacity Constraints
The vaccine contract manufacturing industry faces significant challenges related to regulatory hurdles and capacity constraints. Adhering to complex regulatory frameworks, such as Good Manufacturing Practices (GMP) and stringent quality control standards, can be both time-consuming and costly for manufacturers. These regulations are critical for ensuring vaccine safety and efficacy, but they require continuous investment in compliance. Additionally, the regulatory landscape is constantly evolving, with new guidelines and rules emerging across different regions. Manufacturers must stay updated on these changes to avoid potential delays or penalties, adding another layer of complexity to operations. Compounding this issue are capacity constraints, particularly during pandemics or outbreaks, which can cause sudden surges in demand that overwhelm existing manufacturing infrastructure. Seasonal fluctuations, such as the increased need for influenza vaccines during specific times of the year, further strain production capacities, requiring companies to manage resources carefully to meet varying demand levels.Top of Form
Market Segmentation Analysis:
By Vaccine Type:
The vaccine contract manufacturing market is segmented by vaccine type, including attenuated, inactivated, subunit-based, toxoid-based, and DNA-based vaccines. Attenuated vaccines, which use weakened forms of pathogens, are widely used due to their long-lasting immunity. Inactivated vaccines, containing killed pathogens, are preferred for their safety, especially in immunocompromised populations. Subunit-based vaccines, using only essential components of pathogens, are gaining traction for their focused immune response and lower risk of side effects. Toxoid-based vaccines, targeting bacterial toxins, play a key role in combating diseases like tetanus and diphtheria. DNA-based vaccines, an emerging segment, offer significant potential for rapid development and production, as seen in recent innovations. Each vaccine type presents distinct manufacturing challenges and demands, influencing the strategies adopted by contract manufacturers to meet varying requirements in terms of production processes, safety, and efficacy.
By Scale of Operation:
The scale of operation in vaccine contract manufacturing is categorized into commercial, clinical, and preclinical segments. Commercial manufacturing dominates the market, as it involves large-scale production to meet global demand for vaccines in both public health programs and private markets. Clinical manufacturing, focused on producing vaccines for trials, plays a crucial role in testing vaccine efficacy and safety before full-scale production. Preclinical manufacturing is vital for early-stage research and development, where small batches of vaccines are produced for laboratory testing. Contract manufacturers must adapt their capabilities to meet the different regulatory, operational, and technological requirements at each stage, ensuring efficient transition from research to mass production while maintaining high standards of quality and compliance throughout the vaccine development lifecycle.
Segments:
Based on Vaccine Type
- Attenuated
- Inactivated
- Subunit-based
- Toxoid-based
- DNA-based
Based on Scale of Operation
- Commercial
- Clinical
- Preclinical
Based on Service
- Fill-finish
- Bulk vaccines
Based on Product Type
- Combination vaccine
- Single vaccine
Based on Application
- Human
- Veterinary
Based on End-user
- Pharmaceutical & biotechnology companies
- Academic and research institutes
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a dominant share of the global vaccine contract manufacturing market, accounting for approximately 40% of the market. This strong presence is driven by the region's advanced healthcare infrastructure and the concentration of leading pharmaceutical and biotechnology companies. The United States, in particular, plays a pivotal role, with substantial investments in research and development and support from government initiatives such as Operation Warp Speed during the COVID-19 pandemic. For instance, the U.S. Department of Health and Human Services announced a new initiative to enhance COVID-19 vaccine availability, particularly for marginalized communities. These factors, combined with a well-established regulatory environment, including stringent FDA standards, ensure that North America remains a key player in vaccine production. The region's focus on technological advancements, such as mRNA vaccine development, and its ability to quickly ramp up manufacturing capacity further solidify its leading position in the market.
Asia-Pacific
Asia-Pacific holds a growing share of the vaccine contract manufacturing market, contributing approximately 30% to the global landscape. The region’s rapid expansion is driven by the large-scale manufacturing capabilities in countries like India and China, which offer cost-effective solutions for vaccine production. Asia-Pacific is increasingly recognized for its ability to meet global vaccine demand, particularly for low- and middle-income countries. Governments in this region are investing heavily in the biotechnology and pharmaceutical sectors, improving infrastructure and fostering innovation in vaccine manufacturing. The rise in contract manufacturing organizations (CMOs) and advancements in cold chain logistics are further enhancing the region’s role in the global supply chain, positioning Asia-Pacific as a critical hub for vaccine production and distribution.
Key Player Analysis
- Curia Global, Inc.
- Bavarian Nordic A/S
- Gedeon Richter (Richter-Helm BioLogics)
- Recipharm AB
- Charles River Laboratories International Inc.
- Syngene International Limited
- Catalent, Inc.
- Goodwin Biotechnology Inc.
- Emergent BioSolutions Inc.
- Cytovance Biologics (Hepalink)
- ICON PLC
- Fujifilm Holdings Corporation
- IDT Biologika GmbH
- Ajinomoto Co., Inc.
- Lonza Group AG
Competitive Analysis
The vaccine contract manufacturing market is characterized by intense competition among leading players, each striving for innovation and efficiency. Lonza Group AG, Catalent, Inc., Emergent BioSolutions Inc., Fujifilm Holdings Corporation, and Recipharm AB are at the forefront, leveraging their advanced technologies and manufacturing capabilities to meet the rising global demand for vaccines. Leading players leverage advanced technologies and robust manufacturing capabilities to meet the increasing global demand for vaccines. Key competitors excel in different areas, such as biologics manufacturing, comprehensive solutions that include delivery technologies, and flexible manufacturing options for diverse vaccine types. Some companies focus on integrating digital solutions to enhance efficiency and quality control, while others expand production capacity through strategic partnerships and investments in new facilities. This competitive landscape drives continuous improvements in quality, scalability, and cost-effectiveness, ultimately benefiting the broader healthcare ecosystem and ensuring timely vaccine availability during public health emergencies.
Recent Developments
- In August 2024, Africa CDC entered into a strategic agreement with Bavarian Nordic to increase the production of Mpox vaccine in Africa.
- In July 2024, AstraZeneca announced to invest USD 254 million at its Cambridge facility to expand its vaccine manufacturing capability.
- In May 2024, BioNTech received USD 145 million from CEPI to expand its mRNA vaccine production capacity.
- In June 2023, FUJIFILM Corporation announced an opening of its commercial office in Tokyo. The facility aimed to provide enhanced sales and customer support services for contract development and manufacturing services for biologics and advanced therapies to Asia-based pharmaceutical and biotechnology companies
- In December 2023, Ajinomoto Co., Inc. has recently acquired All Forge Biologics Holdings, LLC shares. The facility was aimed to accelerate production capability for manufacturing and development of biologics. This expansion is expected to foster growth and innovation in Japan
Market Concentration & Characteristics
The vaccine contract manufacturing market exhibits a moderate level of concentration, with several key players dominating the landscape while allowing room for smaller firms to contribute. This market is characterized by significant investment in advanced technologies and research, fostering innovation in vaccine production processes. Major manufacturers leverage economies of scale, enabling them to optimize production efficiency and reduce costs, which is crucial given the increasing demand for vaccines, especially during pandemics. Additionally, the market is marked by a diverse range of services, from preclinical development to large-scale commercial production, catering to various vaccine types, including mRNA, subunit, and inactivated vaccines. Regulatory compliance and stringent quality control standards further shape the market dynamics, requiring manufacturers to maintain high operational standards. As global health challenges evolve, the market remains agile, adapting to emerging technologies and fluctuating demand while ensuring the timely availability of safe and effective vaccines.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Vaccine Type, Scale of Operation, Service, Product Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for vaccine contract manufacturing is expected to increase significantly due to rising global health concerns and the potential for future pandemics.
- Continued advancements in mRNA technology will drive innovation in vaccine development and production processes.
- Companies will focus on expanding their cold chain logistics to ensure the safe distribution of vaccines to remote and underserved regions.
- Increased investments in automation and digitalization will enhance manufacturing efficiency and quality control.
- Collaborative partnerships between public and private sectors will play a crucial role in accelerating vaccine research and development.
- The regulatory landscape will continue to evolve, requiring manufacturers to stay compliant with new guidelines and standards.
- Emerging markets in Asia-Pacific and Africa will present significant growth opportunities for vaccine contract manufacturers.
- Sustainability initiatives will gain traction, leading manufacturers to adopt greener practices and reduce environmental impact.
- The need for personalized vaccines and advanced therapies will prompt manufacturers to diversify their production capabilities.
- Strategic mergers and acquisitions will likely shape the competitive landscape, enabling companies to expand their technological expertise and market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Vaccine Contract Manufacturing market?
What factors are driving the growth of the Vaccine Contract Manufacturing market?
What are the key segments within the Vaccine Contract Manufacturing market?
What are some challenges faced by the Vaccine Contract Manufacturing market?
Who are the major players in the Vaccine Contract Manufacturing market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Vaccine Contract Manufacturing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Vaccine Contract Manufacturing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,129.5 million → 2032: USD 3,741.75 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Vaccine Contract Manufacturing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Vaccine Contract Manufacturing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Vaccine Contract Manufacturing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Vaccine Contract Manufacturing Market Drivers
- 3.3 Vaccine Contract Manufacturing Market Restraints & Challenges
- 3.4 Vaccine Contract Manufacturing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Vaccine Contract Manufacturing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Vaccine Contract Manufacturing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Vaccine Contract Manufacturing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Vaccine Contract Manufacturing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Vaccine Contract Manufacturing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Vaccine Contract Manufacturing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Vaccine Contract Manufacturing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Vaccine Contract Manufacturing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Vaccine Contract Manufacturing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Vaccine Contract Manufacturing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Vaccine Contract Manufacturing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Vaccine Contract Manufacturing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Vaccine Contract Manufacturing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Vaccine Contract Manufacturing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Vaccine Contract Manufacturing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Vaccine Contract Manufacturing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Vaccine Contract Manufacturing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Vaccine Contract Manufacturing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Vaccine Contract Manufacturing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
