
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Cryogenic Equipment Market Size 2024 | USD 22,365 Million |
| Canada Data Center UPS Market, CAGR | 7.3% |
| Canada Data Center UPS Market Size 2032 | USD 39,298 Million |
Market Overview
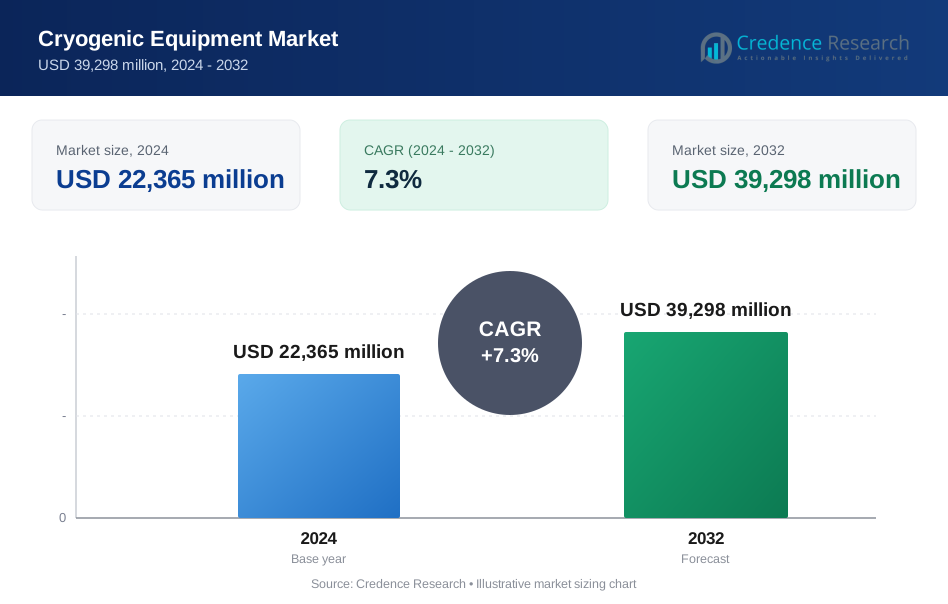
The global Cryogenic Equipment Market is projected to grow from USD 22,365 million in 2024 to USD 39,298 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.3%.
The cryogenic equipment market is driven by rising demand for liquefied natural gas (LNG) and increasing investments in the healthcare sector, particularly in medical gases and cryopreservation. Expanding applications across industries, including energy, aerospace, and electronics, also fuel growth, as these sectors require efficient, low-temperature solutions for storage and transportation. Technological advancements that enhance energy efficiency and reduce operational costs further support market expansion. Additionally, the trend toward environmental sustainability drives innovation in cryogenic equipment, as industries seek eco-friendly solutions to meet stringent emissions regulations and reduce their carbon footprint.
The cryogenic equipment market sees significant demand across key regions, with North America and Asia-Pacific emerging as prominent players due to high industrial activity and investments in energy and healthcare sectors. In North America, the demand for LNG infrastructure and advanced medical applications drives growth, while Asia-Pacific's expanding energy sector and industrialization fuel market expansion. Key players in the industry include Linde plc, Chart Industries Inc., Air Liquide SA, and Nikkiso Co. Ltd., alongside regional leaders such as INOX India Limited and Wessington Cryogenics, who contribute to technological advancements and cater to diverse regional needs in the cryogenics sector.
Market Drivers
Energy Sector: Driving Cryogenic Equipment Demand
The energy sector plays a pivotal role in the demand for cryogenic equipment, primarily due to the rise in liquefied natural gas (LNG) production as a cleaner energy source. For instance, the International Energy Agency (IEA) reports that LNG production has significantly increased as countries seek low-emission fuel alternatives. LNG’s growing importance as a low-emission fuel has led to increased demand for cryogenic systems for its liquefaction, storage, and transportation. Additionally, cryogenic technologies improve energy efficiency across power plants and industrial processes by using cryogenic air separation units (ASUs) to produce high-purity gases, enhancing combustion and operational efficiency. This dual application in energy generation and gas purification supports the market’s steady expansion.
Healthcare and Life Sciences: Expanding Cryogenic Applications
In healthcare and life sciences, cryogenic equipment is indispensable, particularly for medical research and storage. For instance, the World Health Organization (WHO) highlights the critical role of cryogenic storage systems in preserving biological samples, including stem cells, tissues, and DNA, which are essential for research and therapeutic applications. Additionally, cryogenic technologies support medical procedures such as cryotherapy and cryosurgery, both of which utilize low temperatures to treat conditions ranging from skin disorders to certain cancers. As medical research and treatment innovations continue to expand, the demand for cryogenic systems in healthcare is expected to grow significantly.
Industrial Applications: Diverse Uses Boost Market Growth
Cryogenic equipment is vital in various industrial applications, from metallurgy to food processing and electronics. In metallurgy, cryogenic treatments enhance metal properties, such as hardness and toughness, making materials more durable. The food industry relies on cryogenic freezing to preserve food quality and extend shelf life, an increasingly important factor for global food distribution. Furthermore, cryogenic cooling plays a crucial role in high-performance computing and quantum computing, which require extreme temperatures for optimal operation, adding to the market’s growth across diverse industries.
Emerging Technologies and Government Support
Emerging technologies are also spurring the demand for cryogenic equipment. Superconductivity, achievable only at cryogenic temperatures, has applications in energy transmission, medical imaging, and even high-speed transportation. The space sector’s use of cryogenic fuels in rocket propulsion highlights another crucial application in advanced fields. Additional factors include ongoing technological advancements that improve the efficiency and cost-effectiveness of cryogenic equipment, and increasing government investments in cryogenic research and development to support energy security and sustainability goals. These trends underscore the broadening scope and potential of the cryogenic equipment market.
Market Trends
Rising Demand for LNG and Infrastructure Development
The global shift towards cleaner energy sources has positioned liquefied natural gas (LNG) as a preferred alternative to traditional fossil fuels, significantly driving demand for cryogenic equipment. For instance, the International Energy Agency (IEA) highlights that LNG is a strategic fuel source for countries aiming to reduce emissions. LNG is not only a lower-emission energy solution but also plays a key role in the energy transition efforts of both developed and emerging economies. Rapidly industrializing regions, particularly China and India, are accelerating LNG adoption to meet their growing energy needs sustainably. This surging demand is paralleled by substantial investments in LNG infrastructure worldwide, including the development of advanced liquefaction plants, expansive storage tanks, and specialized transportation vessels designed to handle cryogenic temperatures. Each of these infrastructure components relies on cryogenic technology to maintain LNG’s extremely low temperatures, ensuring safe storage and efficient transportation. As the demand for LNG infrastructure grows, so too does the demand for innovative cryogenic systems capable of supporting this burgeoning sector, positioning LNG as a central growth driver in the cryogenic equipment market.
Advancements in Healthcare, Industrial Applications, and Emerging Technologies
The healthcare and life sciences sectors contribute significantly to cryogenic equipment demand, particularly in medical research and specialized procedures. Cryogenic storage is essential for preserving biological samples, including stem cells, tissues, and DNA, which supports advanced research and therapeutic developments. Additionally, cryogenic technologies are integral to medical procedures such as cryotherapy and cryosurgery, which use low temperatures for targeted treatments. In parallel, industrial applications of cryogenic equipment are expanding across metallurgy, food processing, and electronics. Metallurgical applications use cryogenic treatments to enhance metal durability and machinability, making them suitable for high-stress industrial uses. In the food industry, cryogenic freezing helps preserve product quality and extends shelf life, addressing consumer demands for freshness in global markets. Electronics, particularly high-performance and quantum computing, rely on cryogenic cooling to achieve operational stability at extreme speeds. Moreover, advancements in emerging technologies, such as superconductivity and space exploration, highlight new avenues for cryogenic applications. Superconductivity, achievable only at cryogenic temperatures, has transformative potential in energy transmission and medical imaging, while space programs depend on cryogenic fuels for rocket propulsion. These technological advancements, coupled with innovations like miniaturized, portable cryogenic systems, expand the utility of cryogenic equipment across sectors and signal a robust future for the market.
Market Challenges Analysis
High Costs and Complex Operational Requirements
The cryogenic equipment market faces significant challenges related to high initial capital requirements and operational complexities. Setting up cryogenic systems demands a substantial upfront investment due to the specialized technology, high-quality materials, and stringent safety features required to handle extremely low temperatures. This expense can be prohibitive for smaller businesses or firms in developing regions, limiting market accessibility. Moreover, cryogenic equipment involves complex operational protocols and requires skilled personnel for both daily operations and maintenance. Operating these systems calls for specialized expertise to prevent potential malfunctions, which can lead to added expenses due to higher operational costs and, occasionally, equipment downtime. Additionally, the high energy consumption associated with cryogenic processes especially during liquefaction and storage further inflates operational costs, adding an economic burden for companies striving to control energy expenses. This substantial energy use also raises environmental concerns, as companies are pressured to balance operational needs with sustainable practices. Collectively, these factors underscore the financial and technical demands placed on market players, impacting the broader adoption and accessibility of cryogenic equipment.
Safety Risks, Material Challenges, and Regulatory Compliance
Safety and regulatory requirements add another layer of complexity for the cryogenic equipment market. Handling cryogenic fluids entails serious safety risks, as extreme cold can cause severe injuries like frostbite, and gases such as nitrogen pose asphyxiation risks in confined spaces. To mitigate these hazards, companies must adhere to strict safety protocols and provide comprehensive training for operators, which can increase costs and time investments. For instance, the British Cryogenics Council reports that an average of 20 deaths occur annually in Europe due to oxygen depletion atmospheres caused by cryogenic fluids. Additionally, cryogenic environments are notoriously harsh on materials, as they must withstand both extreme cold and high pressures, necessitating specialized materials that can be expensive to develop and source. This material challenge complicates the supply chain, particularly when geopolitical or economic disruptions impact the availability of essential components. Compliance with stringent regulatory standards for safety and environmental impact further intensifies these challenges, as regulatory requirements vary globally and often demand rigorous adherence to safety and emissions protocols. Furthermore, while technological advancements have improved certain aspects of cryogenic equipment, limitations remain in achieving ultra-low temperatures and enhancing efficiency, leaving companies with ongoing innovation hurdles. Together, these safety, material, and regulatory challenges demand continuous investment in compliance, operational excellence, and research, emphasizing the intricate balance required to succeed in the cryogenic equipment market.
Market Segmentation Analysis:
By Equipment:
The cryogenic equipment market is segmented by equipment type, each playing a crucial role in managing low-temperature applications. Tanks hold significant market share due to their importance in the safe storage of cryogenic substances, especially for industrial gases like LNG and medical gases. Valves are another critical component, designed to withstand extremely low temperatures and control the flow of cryogenic fluids with precision. Vaporizers are essential for converting cryogenic liquids into gas form, which is necessary in applications requiring controlled gas release, such as in healthcare and energy sectors. Pumps, meanwhile, facilitate the movement of cryogenic fluids under high pressure, enabling efficient transport and handling across industrial facilities. The “Other Equipment” category encompasses specialized devices tailored to unique cryogenic applications, further diversifying market offerings. Together, these equipment types cater to varied industrial needs, highlighting the comprehensive approach required to manage cryogenic systems effectively across sectors like energy, healthcare, and food processing.
By Cryogen:
The market segmentation by cryogen type reflects the wide range of applications that different gases support. Nitrogen is widely used across industries for its inert properties, with applications in food preservation, electronics cooling, and medical storage. Oxygen is essential in healthcare for medical applications, as well as in industries like metalworking, where high-purity oxygen improves combustion efficiency. Argon is valued in welding and metal processing for its protective shielding properties. Liquefied natural gas (LNG) plays a pivotal role in the energy sector as a clean fuel alternative, driving demand for cryogenic storage and transportation solutions. Hydrogen, an emerging fuel in sustainable energy, demands specialized cryogenic equipment for safe storage and handling. Other cryogens, including specialty gases, further extend the market’s scope to applications in space exploration and high-performance computing. This segmentation illustrates the versatility of cryogenic equipment in handling various gases, each tailored to meet the unique demands of its respective industry.
Segments:
Based on Equipment:
- Tanks
- Valves
- Vaporizers
- Pumps
- Other Equipments
Based on Cryogen:
- Nitrogen
- Oxygen
- Argon
- LNG
- Hydrogen
- Other Cryogens
Based on End-user industry:
- Metallurgy
- Energy & power
- Chemical
- Electronics
- Transportation
- Other End-user Industries
Based on Application:
- CASU
- Non-CASU
Based on System type:
- Storage System
- Handling System
- Supply System
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a commanding 35% share of the global cryogenic equipment market, supported by extensive applications across the energy, healthcare, and aerospace sectors. This region leads due to strong demand for liquefied natural gas (LNG) as a cleaner energy source, which requires significant cryogenic infrastructure. The United States, a key market within the region, is heavily investing in expanding LNG production and export capabilities, thereby fueling demand for cryogenic storage tanks, valves, and other equipment. Additionally, North America’s well-established healthcare sector relies on cryogenic technologies for preserving biological samples and supporting advanced medical procedures, further supporting market growth. North America’s focus on technological innovation and increasing research funding for advanced cryogenic materials are expected to strengthen its position as a major market player.
Asia-Pacific
The Asia-Pacific region holds approximately 30% of the global cryogenic equipment market, driven by rapid industrialization, increasing energy demands, and a growing focus on clean energy initiatives. China and India, in particular, are leading investments in LNG infrastructure as they aim to reduce carbon emissions and transition to sustainable energy sources, positioning Asia-Pacific as a key player in the cryogenic equipment industry. Government investments in energy infrastructure, coupled with rising healthcare needs, are further fueling demand for cryogenic solutions in this region. The combination of industrial growth, a focus on clean energy, and healthcare sector expansion is accelerating Asia-Pacific’s market share, solidifying its role as one of the fastest-growing regions in the cryogenic equipment market.
Key Player Analysis
- Linde plc
- Chart Industries Inc.
- Air Liquide SA
- Nikkiso Co. Ltd.
- INOX India Limited
- Cryolor SA
- Standex International
- Herose GmbH
- Wessington Cryogenics
- Braunschweiger Flammenfilter GmbH
Competitive Analysis
The cryogenic equipment market is highly competitive, with key players continuously innovating to strengthen their market position. Linde plc, Chart Industries Inc., Air Liquide SA, Nikkiso Co. Ltd., INOX India Limited, Standex International, Herose GmbH, Wessington Cryogenics, Braunschweiger Flammenfilter GmbH are prominent companies driving market growth. Companies in this sector are increasingly adopting advanced technologies, improving the efficiency and reliability of cryogenic systems. Key players focus on diversifying their product offerings, including storage tanks, pumps, valves, and vaporizers, to cater to a wide range of industries such as energy, healthcare, and food processing. Additionally, increasing investments in research and development are driving the development of more energy-efficient and cost-effective cryogenic solutions. Market participants are also expanding their geographical reach through strategic partnerships, mergers, and acquisitions, ensuring their presence in emerging markets with growing industrial and energy demands. The competitive landscape is also shaped by the growing focus on sustainability, with companies striving to align their offerings with global environmental goals.
Recent Developments
- In May 2024, Linde plc, a global operator in industrial gases and engineering, announced a landmark agreement to supply industrial gases to the world's first large-scale green steel plant, H2 Green Steel located in Boden, Sweden. The green steel plant, which aims to produce steel using renewable energy sources, represents a significant step forward in the transition to a low carbon economy. Furthermore, Linde's advanced gas technologies will play a crucial role in supporting the plant's operations, contributing to a more sustainable future for the steel industry.
- In July 2023, Chart Industries opened a second facility at Alabama. This plant is expected to fabricate the largest shop-built cryogenic tanks ever manufactured globally 70% larger than the previous model to begin in the first quarter 2024. The tanks manufactured at this site will be used as propellant storage solutions in the aerospace industry, hydrogen and LNG storage solutions in the marine industry and many other processes and technologies adopted in the sciences and decarbonization industries.
- In June 2023, INOX India Limited built an LNG facility in Tamil Nadu, which comprises 2 x 113 KL LNG tanks, regas system with a capacity of 5,000 SCMH @ 22 Bar pressure and associated equipment was supplied by INOXCVA on a turnkey basis in a record time.
- In April 2023, Linde signed an agreement with Evonik, a leading specialty chemicals company, to supply green hydrogen in Singapore. According to the agreement, Linde will build, own, and operate a nine-megawatt alkaline electrolyzer plant on Jurong Island, Singapore. The plant will produce green hydrogen, which Evonik will use to manufacture methionine, an essential component in animal feed.
- In March 2023, Air Products and Chemicals, Inc. and Shaanxi LNG Reserves & Logistics Company signed an agreement to supply its proprietary liquefied natural gas (LNG) process technology and equipment to Technip Energies for the Xi'An LNG Emergency Reserve & Peak Regulation Project with Shaanxi LNG Reserves & Logistics Company Ltd., in ShaanXi Province, China.
Market Concentration & Characteristics
The cryogenic equipment market is characterized by moderate to high concentration, with a few major players dominating the industry while numerous smaller players operate in niche segments. Leading companies focus on developing advanced cryogenic technologies, offering a range of products such as tanks, pumps, valves, and vaporizers for various industries including energy, healthcare, and manufacturing. The market is highly capital-intensive, requiring significant investments in R&D, infrastructure, and specialized materials to produce reliable and efficient equipment. Technological innovation is a key factor driving competition, as companies strive to develop more energy-efficient solutions and meet evolving customer needs. The market also exhibits regional variations, with major players focusing on expanding their presence in high-demand regions such as North America, Asia-Pacific, and Europe. Additionally, the increasing adoption of liquefied natural gas (LNG) and advancements in medical cryogenics are contributing to market growth and shaping the competitive landscape.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Equipment, Cryogen, End-user industry, Application, System type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for cryogenic equipment is expected to grow as the global focus on cleaner energy sources, such as LNG and hydrogen, intensifies.
- Advancements in cryogenic technology will lead to more efficient, cost-effective, and energy-saving equipment.
- The increasing use of cryogenic solutions in medical applications, particularly for cryosurgery and stem cell storage, will drive market growth.
- Rising industrialization and energy demands in emerging markets like Asia-Pacific will significantly boost the need for cryogenic systems.
- Technological advancements in superconductivity and quantum computing will increase the demand for cryogenic cooling systems.
- Cryogenic storage and transport solutions will see growth due to the expanding global LNG infrastructure.
- Stringent environmental regulations will push the market toward more sustainable and eco-friendly cryogenic technologies.
- Growing government support for clean energy projects will foster the adoption of cryogenic technologies in energy sectors worldwide.
- The increasing focus on reducing carbon emissions will create new opportunities for cryogenic systems in hydrogen storage and transport.
- Future developments in cryogenic systems are likely to include miniaturization, making these solutions more portable and accessible for various industries.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Cryogenic Equipment Market?
What factors are driving the growth of the Cryogenic Equipment Market?
What are the key segments within the Cryogenic Equipment Market?
What are some challenges faced by the Cryogenic Equipment Market?
Who are the major players in the Cryogenic Equipment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cryogenic Equipment Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cryogenic Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 22,365 million → 2032: USD 39,298 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cryogenic Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cryogenic Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cryogenic Equipment Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cryogenic Equipment Market Drivers
- 3.3 Cryogenic Equipment Market Restraints & Challenges
- 3.4 Cryogenic Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cryogenic Equipment Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cryogenic Equipment Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cryogenic Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cryogenic Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Cryogenic Equipment Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Cryogenic Equipment. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cryogenic Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cryogenic Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Cryogenic Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cryogenic Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Cryogenic Equipment
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cryogenic Equipment Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Cryogenic Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cryogenic Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cryogenic Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cryogenic Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cryogenic Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cryogenic Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cryogenic Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
