
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Veterinary CT Systems Market Size 2024 | USD 225 million |
| Veterinary CT Systems Market, CAGR | 11.8% |
| Veterinary CT Systems Market Size 2032 | USD 549 million |
Market Overview:
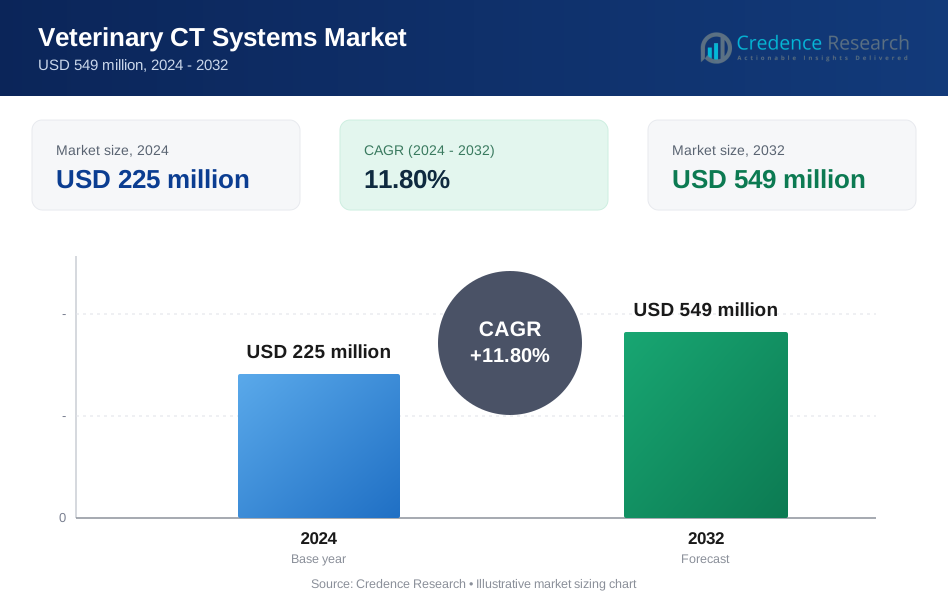
Veterinary CT Systems Market size was valued at USD 225 million in 2024 and is anticipated to reach USD 549 million by 2032, at a CAGR of 11.8% during the forecast period (2024-2032).
The growing prevalence of complex health conditions in companion and livestock animals is a major driver for the veterinary CT systems market. These systems offer non-invasive and high-resolution imaging, enabling veterinarians to diagnose internal injuries, orthopedic conditions, and tumors with greater precision. The increased awareness of pet health and the humanization of pets have led to a surge in demand for sophisticated imaging tools similar to those used in human medicine. Furthermore, government and private funding for veterinary research, alongside collaborations between veterinary institutions and imaging technology firms, are enhancing the accessibility and affordability of CT systems in veterinary settings. Mobile CT units and compact designs are also gaining popularity, particularly in small and mid-sized veterinary practices. The integration of artificial intelligence (AI) in imaging interpretation is also improving diagnostic accuracy and workflow efficiency. In addition, the growing number of veterinary specialists trained in radiology is expanding the utilization of CT systems across diverse clinical scenarios.
Regionally, North America leads the global veterinary CT systems market, accounting for a significant share due to its advanced veterinary infrastructure, high pet ownership rates, and greater awareness of pet health. Europe follows closely, supported by well-established animal welfare regulations and increasing demand for precision diagnostics in veterinary medicine. The Asia-Pacific region is expected to witness the fastest growth during the forecast period, driven by rising income levels, expanding pet populations, and increasing investments in animal healthcare across countries like China, Japan, and India. Additionally, the presence of emerging veterinary diagnostic companies and growing collaborations with international imaging firms are fostering market expansion in this region. Government-led animal health initiatives and subsidies in developing economies are also encouraging adoption of CT systems in public and private veterinary settings.
Market Insights:
- The Veterinary CT Systems Market was valued at USD 225 million in 2024 and is anticipated to reach USD 549 million by 2032, growing at a strong CAGR of 11.8% during the forecast period due to rising demand for advanced animal diagnostics.
- Growing prevalence of chronic and infectious diseases in companion and livestock animals is increasing the demand for high-resolution imaging, prompting veterinary clinics to adopt CT systems for accurate and early diagnosis.
- Continuous advancements such as artificial intelligence, compact scanner designs, and low-radiation imaging are improving diagnostic precision and workflow efficiency, making CT systems more suitable for a range of veterinary applications.
- Rising investments in veterinary infrastructure, including clinics, specialty hospitals, and mobile units, are expanding the reach of CT systems, especially in underserved and rural areas with limited diagnostic access.
- The increasing adoption of pet insurance and supportive regulatory policies are helping offset the cost of advanced imaging, making CT scans more accessible and encouraging clinics to upgrade their diagnostic capabilities.
- High acquisition and maintenance costs, coupled with the need for skilled radiologists, remain significant barriers, especially for small to mid-sized veterinary practices operating with limited financial and human resources.
- North America holds the largest share of the global market at 42%, followed by Europe at 29%, while Asia Pacific, with a 20% share, is expected to witness the fastest growth driven by expanding pet populations and improved veterinary services.
Market Drivers:
Rising Prevalence of Animal Diseases and Demand for Advanced Diagnostics
The Veterinary CT SystemsMarket experiences robust growth due to the increasing prevalence of chronic and infectious diseases among companion and livestock animals. Veterinarians require advanced imaging solutions to accurately diagnose complex conditions, driving the adoption of CT systems. Pet owners are more aware of animal health, prompting them to seek comprehensive diagnostic services. The market benefits from the growing trend of pet humanization, which leads to higher spending on veterinary care. CT imaging enables early disease detection, improving treatment outcomes. It supports veterinarians in making informed clinical decisions, thereby enhancing the standard of care.
Technological Advancements in Veterinary Imaging Equipment
Continuous innovation in imaging technology propels the Veterinary CT SystemsMarket forward. Manufacturers introduce compact, high-resolution, and faster CT scanners specifically designed for veterinary applications. These systems offer improved image quality, reduced scan times, and lower radiation exposure, making them suitable for a wide range of animal sizes and species. Integration of artificial intelligence and advanced software enhances diagnostic accuracy and workflow efficiency. It allows veterinary professionals to handle complex cases with greater confidence. The availability of user-friendly interfaces and automated features further streamlines operations in veterinary clinics and hospitals.
- For instance, the Canon Aquilion ONE/GENESIS Edition CT scanner at the Queen Mother Hospital for Animals can complete a full-body scan (thorax and abdomen) in 10 seconds and reconstruct images at a rate of 80 per second, compared to the previous 42 seconds and 6.5 per second, respectively.
Growing Investment in Veterinary Healthcare Infrastructure
Expansion of veterinary clinics, hospitals, and specialty centers fuels demand within the Veterinary CT SystemsMarket. Governments and private organizations invest in upgrading healthcare infrastructure to support advanced diagnostic capabilities. It enables wider access to state-of-the-art imaging technologies in both urban and rural settings. The market witnesses increased funding for research and development, facilitating the introduction of innovative CT systems. Veterinary institutions prioritize the acquisition of modern equipment to stay competitive and deliver superior patient care. These investments strengthen the overall ecosystem for veterinary diagnostics.
- For example, GoodVets operates 22 care centers across 11 U.S. metropolitan areas as of December 2024, with strategic investment from General Atlantic supporting further expansion into New York City, Los Angeles, and Dallas.
Increasing Adoption of Pet Insurance and Supportive Regulatory Framework
The Veterinary CT SystemsMarket benefits from rising adoption of pet insurance, which covers advanced diagnostic procedures, including CT scans. Insurance providers recognize the value of early and accurate diagnosis in reducing long-term treatment costs. Favorable regulatory policies support the approval and use of veterinary imaging devices, ensuring safety and efficacy. It encourages more clinics to integrate CT systems into their diagnostic repertoire. The market gains from educational initiatives that promote the importance of advanced imaging in veterinary medicine. This environment fosters sustained growth and innovation in the sector.
Market Trends:
Integration of Artificial Intelligence and Cloud-Based Solutions in Veterinary Imaging
The Veterinary CT SystemsMarket observes a marked shift toward the integration of artificial intelligence (AI) and cloud-based technologies. AI-driven software enhances image interpretation, automates routine tasks, and supports faster, more accurate diagnoses. Cloud platforms enable remote access to imaging data, facilitating collaboration among veterinary specialists and improving case management. It allows clinics to store and share large volumes of imaging data securely, ensuring continuity of care. The adoption of these digital solutions streamlines workflow and reduces operational bottlenecks. Veterinary professionals increasingly rely on these technologies to deliver timely and precise diagnostic services.
- For instance, the Vetscan Imagyst system was validated in a study of 108 equine fecal samples, where its AI algorithm provided diagnostic results for strongyles and Parascaris spp. that were strongly concordant with those of expert parasitologists, demonstrating consistent and reliable performance in clinical settings.
Expansion of Point-of-Care and Mobile CT Systems for Veterinary Practice
A significant trend in the Veterinary CT SystemsMarket is the growing availability of point-of-care and mobile CT systems. These compact and portable devices bring advanced imaging capabilities directly to veterinary clinics, emergency settings, and even field environments. It enhances diagnostic flexibility, allowing veterinarians to perform immediate scans without referring patients to specialized centers. The market responds to the demand for rapid, on-site diagnostics, especially for critical and large animal cases. Manufacturers focus on developing lightweight, user-friendly systems that maintain high image quality. This trend supports improved patient outcomes and increases access to advanced imaging across diverse veterinary practices.
- For instance, the Xoran vTRON CT scanner provides instant 3D images at the point-of-care with a total scan time of less than one minute, enabling real-time review and rapid clinical decision-making.
Market Challenges Analysis:
High Cost of Equipment and Limited Affordability Among Veterinary Practices
The Veterinary CT SystemsMarket faces significant challenges due to the high cost of acquiring and maintaining advanced imaging equipment. Many small and mid-sized veterinary clinics struggle to justify the investment, which limits widespread adoption. It creates a barrier for practices in rural or underserved regions, where resources remain constrained. The need for specialized infrastructure and trained personnel further increases operational expenses. Clinics often prioritize essential services over advanced diagnostics, slowing market penetration. This financial hurdle restricts the accessibility of CT systems to a select group of well-funded institutions.
- For instance, the MyVet CT D system by Nuon Imaging weighs 140 kg and is designed for point-of-care mobility, offering a more affordable and space-efficient solution compared to traditional CT systems.
Regulatory Hurdles and Technical Complexity in Implementation
Complex regulatory requirements and the technical sophistication of CT systems present ongoing challenges in the Veterinary CT SystemsMarket. Navigating approval processes for new devices can delay product launches and increase compliance costs for manufacturers. It demands continuous updates to meet evolving safety and efficacy standards. Veterinary professionals require extensive training to operate and interpret CT imaging, which adds to the implementation burden. The risk of operational errors or misdiagnosis remains a concern without adequate expertise. These factors collectively slow the integration of CT technology into mainstream veterinary practice.
Market Opportunities:
Expansion into Emerging Markets and Untapped Geographic Regions
The Veterinary CT SystemsMarket holds significant opportunities in emerging markets and underserved geographic regions. Rising pet ownership and increasing awareness of animal health drive demand for advanced diagnostic solutions in these areas. It enables manufacturers to introduce cost-effective and portable CT systems tailored to local needs. Partnerships with regional distributors and veterinary organizations can accelerate market entry and adoption. Government initiatives to improve veterinary healthcare infrastructure further support growth. These strategies help bridge the gap in access to modern imaging technologies across diverse global markets.
Development of Specialized CT Solutions and Custom Applications
Innovation in specialized CT systems and custom applications presents new avenues for growth in the Veterinary CT SystemsMarket. Manufacturers can design equipment for specific animal species or clinical indications, addressing unique diagnostic challenges. It allows veterinary professionals to deliver targeted care and improve patient outcomes. Collaboration with research institutions and veterinary schools can foster the development of novel imaging protocols. The market benefits from growing demand for minimally invasive diagnostics and precision medicine. These advancements position CT technology as an essential tool in modern veterinary practice.
Market Segmentation Analysis:
By Product Type
The Veterinary CT Systems Market includes stationary and portable CT systems. Stationary CT systems account for the dominant share due to their extensive use in large veterinary hospitals and diagnostic centers. These systems deliver superior image quality and support high-volume scanning. Portable CT systems are increasingly adopted in small and mid-sized clinics. Their mobility, ease of installation, and lower upfront cost make them attractive for point-of-care diagnostics.
- For instance, VetCAT portable CT provides table-side 3D imaging, enabling on-the-spot diagnostics and reducing delays in patient care.
By Animal Type
The market is segmented into small companion animals, large animals, and others. Small companion animals represent the largest segment. Higher rates of pet ownership, growing awareness of pet wellness, and willingness to invest in premium veterinary care support this dominance. Large animals, including horses and livestock, contribute steadily to market growth. Demand in this segment is fueled by the need for accurate diagnostics in equine sports medicine and livestock management.
- For instance, the Bruker MALDI Biotyper® system can identify over 4,200 species from 704 bacterial and fungal genera in minutes using proteomic fingerprinting, enhancing rapid and accurate pathogen detection across a wide range of animal species.
By Imaging Technique
Based on imaging technique, the market includes fan-beam CT and cone-beam CT systems. Fan-beam CT leads the market due to its reliability in producing detailed cross-sectional images, making it ideal for abdominal, thoracic, and neurological evaluations. Cone-beam CT is emerging rapidly in dental, orthopedic, and head region diagnostics. It provides faster image acquisition and minimizes radiation exposure, making it suitable for routine imaging in sensitive cases.
Segmentations:
By Product Type
- Stationary CT Systems
- Portable CT Systems
By Animal Type
- Small Companion Animals
- Large Animals
- Others
By Imaging Technique
- Fan-Beam CT
- Cone-Beam CT
By End-User
- Veterinary Hospitals
- Veterinary Clinics
- Academic and Research Institutes
- Mobile Veterinary Units
By Application
- Neurology
- Oncology
- Orthopedics
- Dentistry
- Traumatology
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Leads with Advanced Infrastructure and High Veterinary Expenditure
North America holds 42% share of the Veterinary CT SystemsMarket, making it the largest regional contributor. The United States drives much of the regional demand, with well-established veterinary hospitals and specialty clinics investing in state-of-the-art imaging technologies. It benefits from high per capita spending on pet care and a strong culture of animal welfare. Favorable reimbursement policies and widespread pet insurance coverage further support market growth. The presence of leading manufacturers and ongoing research initiatives accelerates the adoption of innovative CT systems. These factors collectively reinforce North America’s leadership in the market.
Europe Benefits from Strong Regulatory Frameworks and Growing Companion Animal Population
Europe accounts for 29% share of the Veterinary CT SystemsMarket, reflecting its strong position in the global landscape. Countries such as Germany, the United Kingdom, and France demonstrate high demand for advanced veterinary diagnostics. It is driven by increasing awareness of animal health and a strong network of veterinary clinics and hospitals. Supportive government policies and funding for veterinary research encourage the uptake of CT systems. The region also benefits from collaborations between academic institutions and industry players, fostering technological advancements. These dynamics position Europe as a key contributor to global market expansion.
Asia Pacific Emerges as a High-Growth Region with Expanding Veterinary Services
Asia Pacific holds 20% share of the Veterinary CT SystemsMarket, marking it as a rapidly expanding region. Countries like China, Japan, and Australia experience increasing pet adoption and heightened demand for quality veterinary care. It creates opportunities for market players to introduce affordable and portable CT solutions tailored to local needs. Government efforts to modernize veterinary healthcare infrastructure further stimulate market growth. The region faces challenges related to limited awareness and uneven access, but ongoing investments in education and technology help bridge these gaps. These trends underscore Asia Pacific’s growing significance in the global market landscape.
Key Player Analysis:
- Koninklijke Philips N.V
- Asto CT LLC
- Animage
- Hitachi
- Animage
- Epica Medical Innovation
- MinFound Medical Systems
- Siemens
- GE Healthcare
Competitive Analysis:
The Veterinary CT Systems Market features a competitive landscape driven by innovation, strategic partnerships, and a growing focus on specialized veterinary diagnostics. Leading players include Canon Medical Systems, GE HealthCare, Siemens Healthineers, Epica Animal Health, and Animage LLC. These companies invest in developing compact, high-resolution, and AI-integrated CT systems tailored for veterinary use. It prioritizes technological advancements that reduce scan time, minimize radiation exposure, and improve image clarity across a range of animal sizes. Firms actively expand their distribution networks and offer flexible financing models to increase adoption among mid-sized clinics and mobile units. Collaborations with veterinary hospitals and academic institutions support research-based product development. Companies also compete on service quality, technical support, and user-friendly system interfaces. The Veterinary CT Systems Market continues to attract new entrants focusing on cost-effective and portable solutions, further intensifying competition and encouraging continuous product refinement across the global market.
Recent Developments:
- In May 2025, Epica International announced a strategic service partnership with Catalyst MedTech to enhance service and support for its imaging systems in the U.S., aiming to reduce downtime and improve customer satisfaction across both human and veterinary divisions.
- In February 2025, GE HealthCare launched several innovations at ECR 2025, including the Freelium MRI magnet (uses <1% helium), Revolution Vibe CT (advanced cardiac imaging), and new AI-powered ultrasound and SPECT/CT systems.
- In January 2025, GE HealthCare extended its partnership with ESR as a platinum supporter for ECR 2025, focusing on precision care and showcasing over 40 AI-enabled innovations.
Market Concentration & Characteristics:
The Veterinary CT Systems Market is moderately concentrated, with a few established players dominating global sales through advanced product offerings and strong distribution networks. It features high entry barriers due to the capital-intensive nature of manufacturing, regulatory compliance requirements, and the need for specialized technical expertise. The market favors companies with robust R&D capabilities and established relationships with veterinary institutions. Demand centers around high-performance, user-friendly systems that offer accurate diagnostics for a wide range of animal species. It shows a clear preference for systems that integrate artificial intelligence, reduce scan times, and ensure patient safety. Customization for clinic size, animal type, and clinical application remains a key differentiator. The Veterinary CT Systems Market reflects steady growth, supported by evolving clinical practices and increasing investments in veterinary healthcare infrastructure.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Animal Type, Imaging Technique, End-User, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Expanding integration of artificial intelligence will enhance diagnostic accuracy and streamline image interpretation workflows for veterinarians.
- Development of compact, portable CT systems will increase access to advanced imaging in rural clinics and field environments.
- Innovations that reduce radiation exposure will promote safer imaging practices and support frequent scanning protocols.
- Manufacturers will focus on multispecies adaptability, designing systems capable of accommodating diverse animal sizes and anatomical requirements.
- Growing use of CT imaging in specialized veterinary fields—neurology, oncology, dentistry, and orthopedics—will drive clinical demand.
- Increased peer-to-peer training and certification for veterinary radiologists will raise adoption rates and confidence in CT diagnostics.
- Introduction of flexible financing and leasing options will lower financial barriers for small- and mid-sized veterinary practices.
- Collaborations between imaging companies and veterinary educational institutions will fuel research and product refinement.
- Expansion into emerging markets, supported by targeted marketing and government animal health initiatives, will broaden global reach.
- Continuous emphasis on user-friendly interface design will improve technician efficiency and reduce training time.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Veterinary CT Systems Market?
What are the key segments within the Veterinary CT Systems Market?
What are some challenges faced by the Veterinary CT Systems Market?
Who are the major players in the Veterinary CT Systems Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Veterinary CT Systems Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Veterinary CT Systems Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 225 million → 2032: USD 549 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Veterinary CT Systems Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Veterinary CT Systems Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Veterinary CT Systems Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Veterinary CT Systems Market Drivers
- 3.3 Veterinary CT Systems Market Restraints & Challenges
- 3.4 Veterinary CT Systems Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Veterinary CT Systems Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Veterinary CT Systems Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Veterinary CT Systems category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Veterinary CT Systems Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Veterinary CT Systems Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Veterinary CT Systems market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Veterinary CT Systems Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Veterinary CT Systems Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Veterinary CT Systems Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Veterinary CT Systems (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Veterinary CT Systems Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Veterinary CT Systems Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Veterinary CT Systems Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Veterinary CT Systems Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Veterinary CT Systems Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Veterinary CT Systems Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Veterinary CT Systems Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Veterinary CT Systems Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Veterinary CT Systems Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
