
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
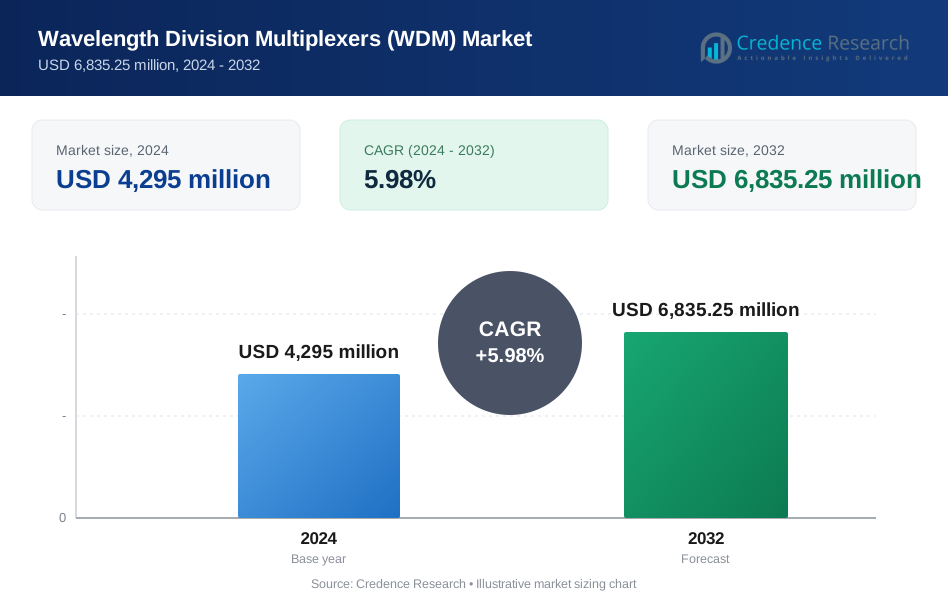
| Wavelength Division Multiplexers (WDM) Market Size 2024 | USD 4,295 Million |
| Wavelength Division Multiplexers (WDM) Market, CAGR | 5.98% |
| Wavelength Division Multiplexers (WDM) Market Size 2032 | USD 6,835.25 Million |
Market Overview
The global Wavelength Division Multiplexers (WDM) Market is projected to grow from USD 4,295 million in 2024 to USD 6,835.25 million by 2032, registering a compound annual growth rate (CAGR) of 5.98%.
The Wavelength Division Multiplexers (WDM) market is driven by the increasing demand for high-speed data transmission and efficient bandwidth utilization in telecommunications and data centers. The proliferation of cloud computing and the Internet of Things (IoT) further fuel the need for advanced optical networking solutions. Additionally, technological advancements in WDM technologies, such as higher channel counts and improved integration with existing infrastructure, enhance performance and reliability. As network operators seek to expand capacity while minimizing costs, the adoption of WDM systems continues to rise, fostering market growth and innovation in the optical communication sector.
The geographical analysis of the Wavelength Division Multiplexers (WDM) market reveals significant growth in regions such as North America and Asia-Pacific, which together hold a substantial market share. North America, driven by the increasing demand for high-speed internet and advancements in telecommunications, is home to key players like Cisco Systems Inc. and Ciena Corporation. Meanwhile, the Asia-Pacific region, characterized by rapid technological advancements and a growing number of data centers, features prominent companies such as Huawei Technologies and ZTE. These players are essential in shaping the competitive landscape and driving innovation within the WDM market.
Market Drivers
Need for Higher Bandwidth and Network Capacity
The advent of 5G and beyond presents a compelling need for higher bandwidth to support high-speed data transfers and low latency. For instance, 5G networks aim to achieve peak data rates of up to 20 Gbps and user-experienced data rates of 100 Mbps, with target latencies as low as 1 ms. Next-generation wireless networks are designed to accommodate a multitude of devices and applications, significantly elevating bandwidth requirements. As data centers continue to expand to handle the growing data traffic, ensuring low latency becomes critical. The need for enhanced network capacity drives the adoption of WDM technology, as it provides an efficient solution for managing increased data flows.
Advancements in WDM Technology
Recent advancements in WDM technology, such as coherent optical transmission, are enabling higher data rates and longer transmission distances, making it ideal for long-haul networks. For instance, the integration of Software-Defined Networking (SDN) into WDM systems enhances network flexibility and automation, allowing for more efficient resource allocation and improved management of network traffic. This synergy allows for more efficient resource allocation and improved management of network traffic, paving the way for innovative applications in various sectors, including telemedicine and financial services. High-bandwidth WDM networks are essential for remote healthcare services like teleconsultations and securely transmitting large volumes of data for financial institutions.
Cost-Effective Network Upgrades
Wavelength Division Multiplexer technology enables network operators to maximize the capacity of existing fiber optic infrastructure without incurring the high costs associated with new fiber deployments. By leveraging WDM, operators can upgrade their networks cost-effectively while enhancing performance. Moreover, WDM systems contribute to energy efficiency by reducing power consumption, resulting in lower operational costs. These cost-effective upgrades make WDM an attractive option for network providers aiming to optimize their infrastructure.
Explosive Growth in Data Traffic
The rapid proliferation of Internet of Things (IoT) devices is generating massive amounts of data that require efficient transmission. As these devices become increasingly integral to everyday life, the demand for reliable connectivity intensifies. Additionally, cloud computing has transformed data centers into hubs that necessitate high-speed connectivity to manage the escalating workload effectively. Coupled with this is the surging popularity of high-definition video streaming services like Netflix and YouTube, which demand significant bandwidth. Together, these factors contribute to an explosive growth in data traffic, propelling the Wavelength Division Multiplexers (WDM) market forward.
Market Trends
Increasing Demand for High-Speed Data Transmission
The demand for high-speed data transmission is soaring, driven primarily by the rollout of 5G networks and the anticipation of 6G technologies, which require massive bandwidth to support high-speed data transfer and low latency. As these next-generation wireless networks become a reality, they promise to revolutionize communication by accommodating more devices and applications than ever before. In parallel, data center interconnect (DCI) has become a critical focus for organizations seeking to enhance their operational efficiency; Wavelength Division Multiplexers (WDM) play a vital role in establishing high-speed connections between data centers, ensuring efficient data exchange. Moreover, the growing adoption of cloud computing is driving the need for high-capacity networks that can facilitate seamless data transfer between various data centers. As organizations increasingly rely on cloud services, the underlying infrastructure must adapt to support this burgeoning demand, further propelling the market for WDM technology.
Advancements in Coherent Optical Transmission and Green Data Centers
Advancements in coherent optical transmission technology are revolutionizing the capabilities of optical networks. This innovative approach enables significantly higher data rates per wavelength, making it particularly suited for long-haul networks that require robust data transmission over extended distances. For instance, recent advancements in digital coherent optical transmission technology have enabled high-speed and high-capacity transmission, compact and low-power devices, and software-based autonomous control. Additionally, coherent optical transmission extends the reach of optical networks, effectively reducing the need for frequent network upgrades and minimizing maintenance requirements. Coupled with this technological progress is the integration of Software-Defined Networking (SDN), which enhances network agility. SDN facilitates dynamic network configuration and optimization, rendering WDM networks more flexible and responsive to fluctuating traffic patterns. By automating network management tasks, SDN not only streamlines operations but also contributes to reduced operational costs. Sustainability is another critical consideration in the evolution of WDM technology, particularly as organizations strive to develop green data centers. WDM systems significantly reduce power consumption, helping data centers meet their sustainability goals. Furthermore, this technology allows for the efficient utilization of existing fiber infrastructure, minimizing the need for additional fiber deployments and thereby conserving resources. Emerging applications, such as the Internet of Things (IoT) and Artificial Intelligence (AI) and Machine Learning (ML), further exemplify the need for high-bandwidth networks, as these innovations generate substantial data traffic that must be efficiently transmitted to enable real-time processing and decision-making.
Market Challenges Analysis
Nonlinear Effects and Their Impact on Signal Quality
One of the significant challenges faced by Wavelength Division Multiplexers (WDM) is the nonlinear effects that can adversely affect signal quality and system capacity. For instance, a study by the Vellore Institute of Technology highlighted that Four-Wave Mixing (FWM) is a prominent nonlinear phenomenon where multiple wavelengths interfere with one another, leading to degradation in signal quality and limiting the overall capacity of the system. Additionally, dispersion poses a critical issue in long-distance transmission, as it causes signal distortion that can significantly diminish transmission quality. This issue is compounded by Polarization Mode Dispersion (PMD), which further leads to signal degradation, particularly in long-haul networks. The combined effects of these nonlinear challenges underscore the need for advanced modulation techniques and Digital Signal Processing (DSP) to improve spectral efficiency and mitigate the impact of distortion on signal integrity.
Cost, Complexity, and Infrastructure Limitations
Another pressing challenge in deploying WDM technology is the high initial investment required, particularly for large-scale networks. The expense associated with implementing these systems can deter organizations from adopting WDM solutions, especially small to medium-sized enterprises. Moreover, the complexity of network management adds another layer of difficulty; managing WDM networks necessitates specialized expertise and sophisticated tools to ensure optimal performance. Additionally, interoperability issues can arise due to vendor lock-in, where different vendors employ proprietary technologies, making it challenging to integrate equipment from multiple sources. Compliance with industry standards is vital for ensuring interoperability and facilitating future upgrades, yet navigating these standards can be cumbersome. Power consumption is also a significant concern, particularly with WDM systems that use coherent detection. These systems can consume considerable amounts of power, leading to increased operational costs and necessitating efficient cooling solutions to maintain optimal performance and reliability. Furthermore, issues surrounding fiber availability and cost can impede deployment; in certain regions, the fiber infrastructure may be limited or expensive to establish. Maintaining fiber networks is another costly and time-consuming endeavor, further complicating the landscape for WDM technology.
Market Segmentation Analysis:
By Multiplexer Type:
The Wavelength Division Multiplexers (WDM) market can be segmented based on multiplexer types, which include Coarse Wavelength Division Multiplexer (CWDM) and Dense Wavelength Division Multiplexer (DWDM). CWDM is designed to support a lower number of channels and wider channel spacing, making it suitable for applications where cost efficiency is paramount. Its lower complexity allows for easier implementation in less demanding environments, such as regional networks. On the other hand, DWDM offers higher channel capacity with tighter channel spacing, facilitating the transmission of large volumes of data over long distances. This capability makes DWDM the preferred choice for high-capacity backbone networks, especially in telecommunications and data center interconnects.
By Vertical:
The market can also be segmented by verticals, including IT & Telecoms, Healthcare, Manufacturing, and Financial Services. The IT and telecommunications sector drives the demand for WDM technologies due to the increasing need for bandwidth in data centers and cloud computing environments. In healthcare, WDM supports high-bandwidth applications such as telemedicine and remote diagnostics, enhancing patient care. The manufacturing and financial services sectors leverage WDM technology to ensure secure and efficient data transmission, enabling real-time analytics and improving operational efficiency. These diverse applications underscore the integral role of WDM technology across various industries.
Segments:
Based on Multiplexer Type:
- Coarse Wavelength Division Multiplexer (CWDM)
- Dense Wavelength Division Multiplexer (DWDM)
Based on Vertical:
- IT & Telecoms
- Healthcare
- Manufacturing
- Financial Services
- Other
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North American region holds a significant share of the Wavelength Division Multiplexers (WDM) market, accounting for approximately 35%. This dominance is driven by the rapid expansion of telecommunications infrastructure and the increasing demand for high-speed internet services. The proliferation of data centers and the advent of cloud computing in the region have further propelled the adoption of WDM technologies. Major players in North America, such as Cisco Systems and Ciena Corporation, are investing heavily in advanced WDM solutions to meet the growing bandwidth requirements. Additionally, the region's focus on technological innovation and the implementation of next-generation networks, including 5G, are expected to boost market growth in the coming years.
Asia-Pacific
In contrast, the Asia-Pacific region is emerging as a robust contender in the WDM market, projected to capture around 30% market share. This growth can be attributed to the rapid digital transformation occurring in countries like China, India, and Japan. The increasing number of internet users, coupled with the rise of IoT devices, is creating an insatiable demand for high-capacity data transmission. Furthermore, government initiatives aimed at enhancing digital infrastructure and fostering connectivity are driving the adoption of WDM technologies across various sectors. As telecommunications companies invest in upgrading their networks to support growing data traffic, the Asia-Pacific region is poised for substantial growth in the WDM market, fostering competitive dynamics among regional and global players.
Key Player Analysis
- Cisco Systems Inc.
- Huawei Technologies
- ZTE
- Ciena Corporation
- Alcatel-Lucent
- Infinera Corporation
- Fujitsu Ltd.
- ADVA Optical Networking SE
- ADTRAN Inc.
- Aliathon Technology Ltd.
Competitive Analysis
The competitive landscape of the Wavelength Division Multiplexers (WDM) market is characterized by the presence of several leading players, including Alcatel-Lucent, Ciena Corporation, Fujitsu Ltd., Huawei Technologies, ZTE, Cisco Systems Inc., Infinera Corporation, ADVA Optical Networking SE, Aliathon Technology Ltd., and ADTRAN Inc. These companies are heavily investing in research and development to enhance their WDM technologies, focusing on increasing bandwidth capacity and reducing operational costs. Their strategies involve forming strategic partnerships and acquiring emerging tech firms to broaden their product offerings. With the growing demand for high-speed data transmission and low-latency networks, these key players are poised to capture a significant market share. Moreover, the ongoing advancements in coherent optical transmission and software-defined networking are expected to further intensify competition, as companies strive to deliver innovative solutions that meet the evolving needs of various industries, including IT, telecommunications, and healthcare.
Recent Developments
- In 2022, Alcatel-Lucent developed the OmniAccessâ Stellar Asset Tracking solution, which offers new customizable push-button alerts and an AI/ML-powered real-time location algorithm for environments that require improved accuracy compared with standard tools.
- In 2022, Ciena Corporation, JP Morgan Chase, and Toshiba demonstrated the viability of a first-of-its-kind Quantum Key Distribution (QKD) network for metropolitan areas.
- In 2022, Huawei Technologies revealed the Net-Generation Data Centre Facility and unveiled PowerPOD 3.0, a brand new power supply system in Dongguan, China.
Market Concentration & Characteristics
The market concentration of Wavelength Division Multiplexers (WDM) is characterized by a mix of established players and emerging companies, creating a competitive landscape that fosters innovation and growth. Leading firms, such as Alcatel-Lucent, Ciena Corporation, and Huawei Technologies, dominate the market, collectively holding a significant share due to their advanced technology offerings and extensive distribution networks. These companies invest heavily in research and development to enhance the efficiency and capacity of their WDM systems, focusing on solutions that address the increasing demand for high-speed data transmission. Furthermore, the market exhibits a trend towards strategic partnerships and collaborations, allowing companies to leverage each other's strengths and expand their technological capabilities. The presence of numerous regional and niche players also adds diversity to the market, enabling specialized solutions tailored to specific industry needs. As a result, the WDM market remains dynamic, with continuous advancements and competitive strategies driving its evolution.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Multiplexer Type, Vertical and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for Wavelength Division Multiplexers (WDM) is expected to rise significantly due to increasing internet bandwidth requirements and the proliferation of data centers.
- Advancements in optical fiber technology will enhance WDM's efficiency, enabling higher data transmission rates and longer distances.
- The adoption of 5G networks will drive the need for WDM solutions to support increased data traffic and improve network performance.
- Integration of WDM with existing network infrastructure will become more common, facilitating seamless upgrades and improved operational efficiency.
- The growth of cloud computing services will propel the WDM market as businesses seek efficient data transfer and management solutions.
- Ongoing research and development in photonic technologies will lead to more compact and cost-effective WDM devices.
- The emergence of smart cities will require robust WDM solutions to manage the vast amount of data generated by IoT devices.
- Increased investment in telecommunications infrastructure across developing regions will create new opportunities for WDM technology deployment.
- Enhanced cybersecurity measures will be integrated with WDM systems to protect data transmission against emerging threats.
- The market will witness a trend towards the development of intelligent WDM systems that can autonomously optimize network performance and resource allocation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Wavelength Division Multiplexers (WDM) market?
What factors are driving the growth of the Wavelength Division Multiplexers (WDM) market?
What are the key segments within the Wavelength Division Multiplexers (WDM) market?
What are some challenges faced by the Wavelength Division Multiplexers (WDM) market?
Who are the major players in the Wavelength Division Multiplexers (WDM) market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Wavelength Division Multiplexers (WDM) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Wavelength Division Multiplexers (WDM) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,295 million → 2032: USD 6,835.25 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Wavelength Division Multiplexers (WDM) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Wavelength Division Multiplexers (WDM) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Wavelength Division Multiplexers (WDM) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Wavelength Division Multiplexers (WDM) Market Drivers
- 3.3 Wavelength Division Multiplexers (WDM) Market Restraints & Challenges
- 3.4 Wavelength Division Multiplexers (WDM) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Wavelength Division Multiplexers (WDM) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Wavelength Division Multiplexers (WDM) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Wavelength Division Multiplexers (WDM) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Wavelength Division Multiplexers (WDM) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Wavelength Division Multiplexers (WDM) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Wavelength Division Multiplexers (WDM) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Wavelength Division Multiplexers (WDM) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Wavelength Division Multiplexers (WDM) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Wavelength Division Multiplexers (WDM) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Wavelength Division Multiplexers (WDM) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Wavelength Division Multiplexers (WDM) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Wavelength Division Multiplexers (WDM) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Wavelength Division Multiplexers (WDM) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Wavelength Division Multiplexers (WDM) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Wavelength Division Multiplexers (WDM) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Wavelength Division Multiplexers (WDM) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Wavelength Division Multiplexers (WDM) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Wavelength Division Multiplexers (WDM) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Wavelength Division Multiplexers (WDM) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
