
Zollinger-Ellison Syndrome (ZES) Treatment Market Overview:
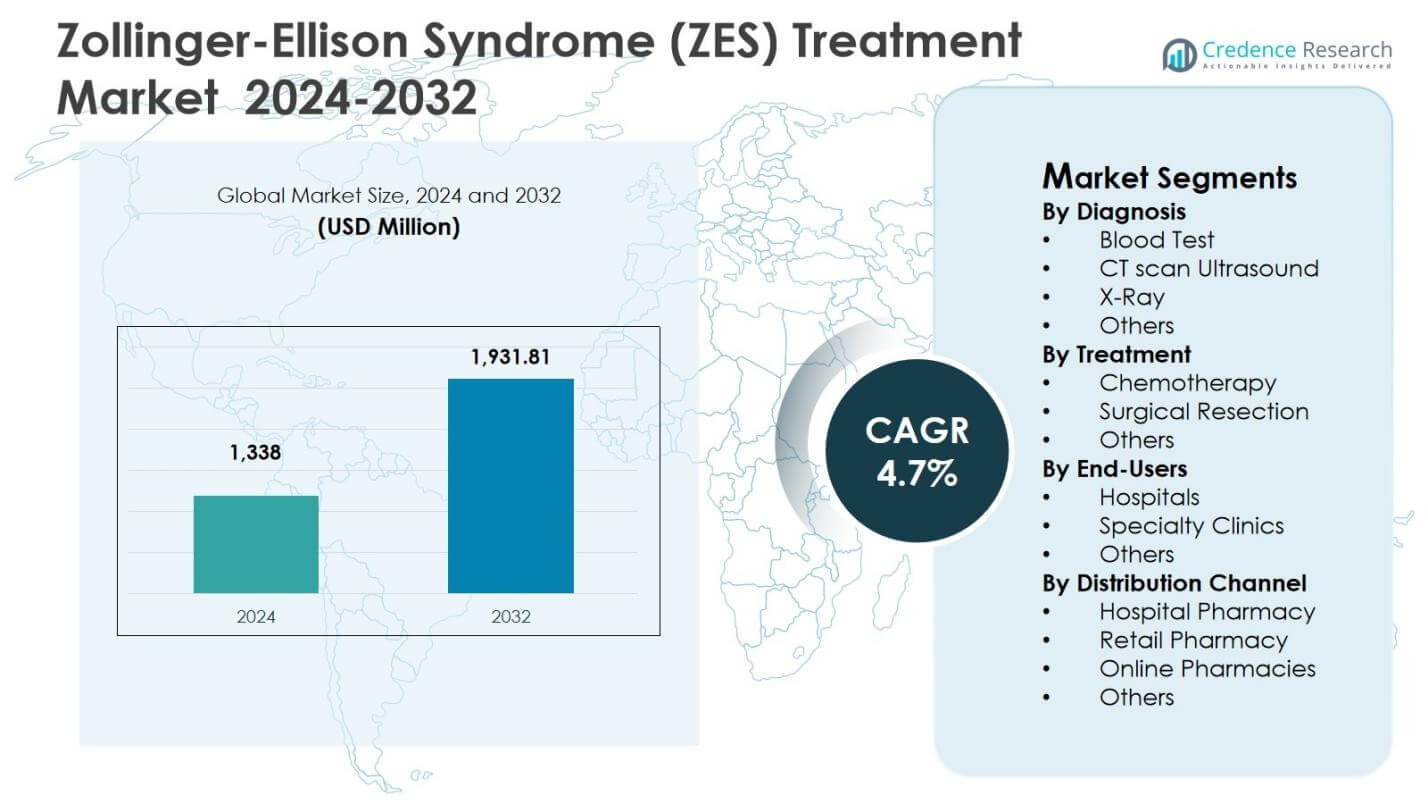
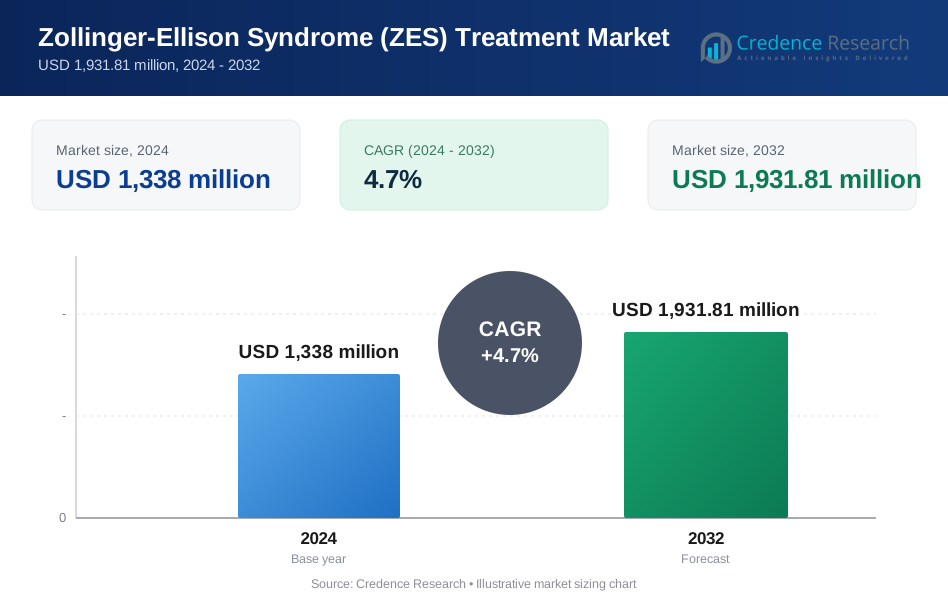
Zollinger-Ellison Syndrome (ZES) Treatment Market size was valued at USD 1,338 million in 2024 and is anticipated to reach USD 1,931.81 million by 2032, growing at a CAGR of 4.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Zollinger-Ellison Syndrome (ZES) Treatment Market Size 2024 | USD 1,338 million |
| Zollinger-Ellison Syndrome (ZES) Treatment Market, CAGR | 4.7% |
| Zollinger-Ellison Syndrome (ZES) Treatment Market Size 2032 | USD 1,931.81 million |
Zollinger-Ellison Syndrome (ZES) Treatment Market Insights
- Market growth is driven by rising prevalence of neuroendocrine tumors, increasing diagnosis of MEN1-associated ZES, improved physician awareness, and growing adoption of advanced diagnostic imaging and laboratory testing.
- Ongoing trends include wider use of targeted and combination therapies, increasing reliance on long-term pharmacological management, and growing preference for minimally invasive surgical resection in localized cases, with surgical resection holding a 38.9% segment share in 2024.
- Market restraints include high diagnostic and treatment costs, limited reimbursement for rare diseases, and delayed diagnosis due to non-specific gastrointestinal symptoms, which continue to impact timely treatment initiation.
- Regionally, North America led with a 41.8% share in 2024, followed by Europe at 29.6% and Asia Pacific at 18.9%, while hospitals dominated end users with a 52.8% share due to advanced infrastructure and multidisciplinary care availability.
Zollinger-Ellison Syndrome (ZES) Treatment Market Segmentation Analysis:
By Diagnosis:
The Zollinger-Ellison Syndrome (ZES) Treatment Market, by diagnosis, is led by Blood Tests, which accounted for 41.6% market share in 2024. Blood tests dominate due to their high sensitivity in detecting elevated gastrin levels, early disease confirmation, and widespread availability across healthcare settings. Physicians prefer fasting serum gastrin tests as the first-line diagnostic tool, supporting faster clinical decision-making. CT scans and ultrasound held 27.3% share, driven by tumor localization needs, while X-ray and other diagnostic modalities collectively represented 31.1%, supported by confirmatory imaging and follow-up assessments in complex ZES cases.
- For instance, Mayo Clinic employs fasting serum gastrin blood tests as the initial step to identify elevated levels suggestive of pancreatic or duodenal tumors in ZES patients.
By Treatment:
By treatment type, Surgical Resection emerged as the dominant sub-segment, capturing 38.9% of the market share in 2024, driven by its curative potential in localized gastrinomas and improved surgical outcomes. Increasing early diagnosis rates and advancements in minimally invasive surgical techniques continue to strengthen this segment. Chemotherapy accounted for 34.7% share, supported by its use in metastatic or inoperable cases, particularly neuroendocrine tumors. Other treatment options, including proton pump inhibitors and targeted therapies, contributed 26.4%, benefiting from long-term symptom management and improved patient quality of life.
- For instance, in a metastatic gastrinoma case treated with S-1 chemotherapy plus octreotide, a 53-year-old woman's pancreatic tumor and liver metastases regressed after 6 months, achieving partial response and over 8 years of progression-free survival without serious adverse events.
By End-Users:
The end-user segment is dominated by Hospitals, which held 52.8% of the Zollinger-Ellison Syndrome (ZES) Treatment Market share in 2024, supported by advanced diagnostic infrastructure, multidisciplinary care teams, and higher surgical volumes. Hospitals serve as primary centers for complex ZES diagnosis, imaging, and surgical interventions. Specialty Clinics accounted for 31.5% share, driven by growing referrals to gastroenterology and oncology centers with focused expertise. Other end-users, including research institutes and ambulatory centers, represented 15.7%, supported by follow-up care and specialized treatment monitoring.
Key Growth Drivers
Increasing Prevalence of Neuroendocrine Tumors and ZES
The Zollinger-Ellison Syndrome (ZES) Treatment Market is strongly driven by the rising prevalence of neuroendocrine tumors, which represent the primary underlying cause of ZES. Improved physician awareness and enhanced screening for recurrent or treatment-resistant peptic ulcer disease have significantly increased diagnosis rates. Early identification enables timely surgical and pharmacological intervention, improving patient outcomes. In addition, the growing incidence of multiple endocrine neoplasia type 1 (MEN1) has expanded the addressable patient population. These factors collectively support sustained demand for effective ZES diagnostics and therapeutic solutions.
- For instance, in MEN1/ZES patients, ZES onset occurred 10 years earlier than in sporadic cases, with diagnosis delayed 3-5 years from symptom start, highlighting the need for heightened screening in this group.
Advancements in Diagnostic and Imaging Technologies
Continuous advancements in diagnostic imaging and laboratory testing are accelerating growth in the Zollinger-Ellison Syndrome (ZES) Treatment Market. High-resolution CT imaging, endoscopic ultrasound, and sensitive gastrin assays improve tumor localization and disease staging accuracy. These advancements reduce diagnostic delays and support informed treatment planning. The integration of advanced diagnostic tools within hospital and specialty clinic settings has increased clinician confidence in early intervention strategies. As diagnostic precision improves, demand for surgical, chemotherapeutic, and long-term medical management options continues to rise.
- For instance, Ga-68 DOTATATE PET/CT demonstrated 93% sensitivity and 96% specificity in a ZES case, revealing intense uptake in gastric and duodenal neuroendocrine tumors plus metastases.
Expansion of Specialized Treatment Infrastructure
The expanding availability of specialized healthcare infrastructure plays a critical role in driving the Zollinger-Ellison Syndrome (ZES) Treatment Market. Growth in tertiary care hospitals and dedicated gastroenterology and oncology centers has enhanced access to advanced treatment modalities. Multidisciplinary care models enable comprehensive disease management, combining surgical, medical, and hormonal therapies. Furthermore, increased healthcare investments and improved reimbursement frameworks in developing regions are improving patient access to specialized care, supporting steady market expansion.
Key Trends & Opportunities
Emergence of Targeted and Combination Therapy Approaches
The development of targeted and combination therapies represents a key trend in the Zollinger-Ellison Syndrome (ZES) Treatment Market. Pharmaceutical research increasingly focuses on tumor-specific pathways and hormone regulation mechanisms to improve therapeutic efficacy. Combination regimens integrating proton pump inhibitors with chemotherapy or targeted agents enhance symptom control and disease progression management. These treatment strategies provide improved outcomes for patients with advanced or metastatic disease. Ongoing clinical research continues to expand therapeutic pipelines, creating long-term growth opportunities for drug developers.
- For instance, Novartis's everolimus, an mTOR inhibitor, targets advanced neuroendocrine tumors associated with ZES gastrinomas. Clinical trials demonstrated it extended progression-free survival from 4.6 months to 11.0 months compared to placebo.
Shift Toward Personalized Care in Specialty Clinics
A growing shift toward personalized care delivery is creating new opportunities in the Zollinger-Ellison Syndrome (ZES) Treatment Market. Specialty clinics increasingly tailor treatment strategies based on tumor characteristics, disease severity, and patient comorbidities. This approach improves therapeutic effectiveness and patient adherence while reducing unnecessary interventions. Specialty centers also play a vital role in long-term disease monitoring and follow-up care. As referral networks expand and patient preference shifts toward specialized treatment settings, market adoption of advanced ZES therapies continues to strengthen.
- For instance, Cleveland Clinic customizes surgery for ZES patients by evaluating gastrinoma size and spread via imaging, opting for procedures like Whipple surgery or enucleation to match disease severity and comorbidities, followed by lifelong PPI therapy.
Key Challenges
High Cost Burden of Diagnosis and Treatment
High diagnostic and treatment costs remain a significant challenge in the Zollinger-Ellison Syndrome (ZES) Treatment Market. Advanced imaging procedures, surgical interventions, and prolonged pharmacological therapy create substantial financial burdens for patients and healthcare providers. Limited reimbursement coverage for rare disease treatments further restricts access, particularly in cost-sensitive regions. These economic constraints can delay diagnosis and treatment initiation, negatively affecting clinical outcomes. Addressing cost barriers is essential to improving market accessibility and treatment adoption.
Low Awareness and Delayed Disease Identification
Limited awareness and delayed diagnosis continue to hinder growth in the Zollinger-Ellison Syndrome (ZES) Treatment Market. The disease often presents with non-specific gastrointestinal symptoms, leading to frequent misdiagnosis in early stages. Inadequate awareness among primary care physicians and limited access to specialized diagnostic facilities prolong diagnostic timelines. Delayed identification reduces the effectiveness of curative treatment options such as surgical resection. Strengthening education initiatives and improving referral pathways are critical to overcoming this challenge and supporting timely disease management.
Regional Analysis
North America
The Zollinger-Ellison Syndrome (ZES) Treatment Market in North America accounted for 41.8% market share in 2024, driven by advanced healthcare infrastructure, high awareness of rare gastrointestinal disorders, and strong access to specialized diagnostics. The United States leads regional growth due to early adoption of advanced imaging, high surgical intervention rates, and availability of long-term pharmacological therapies. Strong presence of major pharmaceutical companies and specialized gastroenterology centers further supports treatment adoption. Favorable reimbursement policies and increased screening for neuroendocrine tumors continue to strengthen North America’s leadership in the ZES treatment landscape.
Europe
Europe represented 29.6% of the Zollinger-Ellison Syndrome (ZES) Treatment Market share in 2024, supported by well-established healthcare systems and growing diagnosis rates across Western and Central Europe. Countries such as Germany, France, and the U.K. drive demand due to strong clinical expertise in rare endocrine disorders. Increased adoption of standardized diagnostic protocols and access to surgical and chemotherapeutic treatments enhance patient outcomes. Government-backed healthcare coverage and rising investments in neuroendocrine tumor research further support market growth, positioning Europe as the second-largest regional contributor.
Asia Pacific
Asia Pacific captured 18.9% market share in 2024 in the Zollinger-Ellison Syndrome (ZES) Treatment Market, driven by expanding healthcare infrastructure and improving access to specialized diagnostics. Countries such as China, Japan, and India are witnessing rising diagnosis rates due to better physician awareness and increased availability of advanced imaging technologies. Growing healthcare expenditure and expansion of tertiary care hospitals support treatment adoption. Although diagnosis rates remain lower than developed regions, increasing investments in rare disease management and improving referral networks are accelerating regional market growth.
Latin America
Latin America accounted for 5.6% of the Zollinger-Ellison Syndrome (ZES) Treatment Market share in 2024, supported by gradual improvements in healthcare access and diagnostic capabilities. Brazil and Mexico lead regional demand due to expanding hospital infrastructure and growing availability of specialized gastroenterology services. Increased adoption of proton pump inhibitors and chemotherapy for symptom management supports market activity. However, limited awareness and delayed diagnosis restrict faster growth. Ongoing healthcare reforms and increased investment in specialized care are expected to support steady market development across the region.
Middle East & Africa
The Middle East & Africa held 4.1% market share in 2024 in the Zollinger-Ellison Syndrome (ZES) Treatment Market, reflecting limited disease awareness and restricted access to advanced diagnostics. The Gulf Cooperation Council countries drive regional demand due to better healthcare infrastructure and availability of specialized hospitals. In contrast, many African countries face challenges related to late diagnosis and limited treatment access. Growing government investments in healthcare modernization and expansion of tertiary care facilities are gradually improving diagnostic and treatment capabilities, supporting incremental regional market growth.
Zollinger-Ellison Syndrome (ZES) Treatment Market Segmentations:
By Diagnosis
- Blood Test
- CT scan Ultrasound
- X-Ray
- Others
By Treatment
- Chemotherapy
- Surgical Resection
- Others
By End-Users
- Hospitals
- Specialty Clinics
- Others
By Distribution Channel
- Hospital Pharmacy
- Retail Pharmacy
- Online Pharmacies
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Zollinger-Ellison Syndrome (ZES) Treatment Market is shaped by the presence of key players including Pfizer Inc., Novartis AG, F. Hoffmann-La Roche Ltd, Sanofi, Johnson & Johnson Services, Inc., Bristol Myers Squibb Company, Bayer AG, Teva Pharmaceutical Industries Ltd., and GSK Plc. These companies focus on strengthening their portfolios through branded and generic proton pump inhibitors, oncology therapeutics, and supportive treatment solutions for neuroendocrine tumors. Market participants emphasize lifecycle management strategies, formulation improvements, and expanded indications to maintain market position. Strategic collaborations with research institutes and oncology centers support clinical development and pipeline expansion. In addition, players are investing in geographic expansion and improved distribution networks to increase treatment accessibility in emerging markets. Strong regulatory expertise and well-established manufacturing capabilities enable leading companies to sustain product availability and pricing competitiveness, reinforcing their position in the evolving ZES treatment landscape.
Key Player Analysis
- Sanofi (France)
- Pfizer Inc. (U.S.)
- Novartis AG (Switzerland)
- Johnson & Johnson Services, Inc. (India)
- Bayer AG (Germany)
- Teva Pharmaceutical Industries Ltd.
- GSK Plc. (U.K.)
- Bristol Myers Squibb Company (U.S.)
- F. Hoffmann-La Roche Ltd (Switzerland)
- Mylan N.V. (U.S.)
Recent Developments
- In November 2025, VKT Pharma received FDA approval for reformulated ranitidine tablets, indicated for Zollinger-Ellison Syndrome among other acid-related conditions.
- In December 2024, Baxter International Inc. launched Pantoprazole Sodium in 0.9% Sodium Chloride Injection for treating Zollinger-Ellison Syndrome, expanding its treatment portfolio for acid-related conditions.
- In October 2024, Teva Pharmaceuticals launched the first FDA-approved generic octreotide LAR (long-acting release) product in the U.S., a somatostatin analog used in managing neuroendocrine tumors including those associated with Zollinger-Ellison Syndrome, providing a lower-cost alternative to brand Sandostatin LAR.
Report Coverage
The research report offers an in-depth analysis based on Diagnosis, Treatment, Distribution Channel, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Zollinger-Ellison Syndrome (ZES) Treatment Market will continue to expand due to rising diagnosis of neuroendocrine tumors and improved clinical awareness.
- Advancements in diagnostic imaging and biomarker testing will support earlier detection and timely treatment initiation.
- Surgical resection will remain a critical treatment option for localized disease, supported by improved minimally invasive techniques.
- Long-term pharmacological management will sustain demand for proton pump inhibitors and adjunctive therapies.
- Targeted therapies and combination treatment approaches will gain wider adoption for advanced and metastatic cases.
- Specialty clinics will play a growing role in personalized treatment planning and long-term disease monitoring.
- Increased investment in rare disease research will strengthen therapeutic pipelines and clinical trial activity.
- Expanding healthcare infrastructure in emerging regions will improve access to specialized ZES treatment.
- Strategic collaborations between pharmaceutical companies and research institutions will accelerate innovation.
- Regulatory support for orphan and rare disease therapies will enhance market stability and long-term growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of Neuroendocrine Tumors and ZES
The rising incidence of neuroendocrine tumors, which are the primary cause of Zollinger-Ellison Syndrome, is expanding the patient pool and driving demand for both diagnostic and therapeutic solutions. Improved physician awareness and screening for MEN1-associated ZES further support early diagnosis and intervention.
Advancements in Diagnostic and Imaging Technologies
Continuous improvements in high-resolution imaging, endoscopic ultrasound, and sensitive gastrin assays are enabling earlier and more accurate detection of ZES. These advancements reduce diagnostic delays and facilitate timely, targeted treatment planning.
Expansion of Specialized Treatment Infrastructure
Growth in tertiary care hospitals and specialty gastroenterology and oncology clinics is enhancing access to advanced surgical and pharmacological treatments. Multidisciplinary care models and increased healthcare investments, especially in emerging regions, are supporting broader market adoption.
Emergence of Targeted and Combination Therapy Approaches
Pharmaceutical innovation is leading to the development of targeted therapies and combination regimens that improve outcomes for advanced or metastatic ZES cases. These new treatment options are expanding the therapeutic pipeline and creating long-term growth opportunities.
Shift Toward Personalized Care in Specialty Clinics
The trend toward individualized treatment strategies based on tumor characteristics and patient comorbidities is improving therapeutic effectiveness and patient adherence. Specialty clinics are increasingly central to long-term disease monitoring and tailored care, driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Zollinger-Ellison Syndrome (ZES) Treatment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Zollinger-Ellison Syndrome (ZES) Treatment Market projected to grow between 2024 and 2032?
Which Zollinger-Ellison Syndrome (ZES) Treatment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Zollinger-Ellison Syndrome (ZES) Treatment Market?
Who are the leading companies in the Zollinger-Ellison Syndrome (ZES) Treatment Market?
Which region commanded the largest share of the Zollinger-Ellison Syndrome (ZES) Treatment Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Diagnosis
- 1.2.1 Blood Test
- 1.2.2 CT scan Ultrasound
- 1.2.3 X-Ray
- 1.2.4 Others
- 1.3 By End-Users
- 1.3.1 Hospitals
- 1.3.2 Specialty Clinics
- 1.3.3 Others
- 1.4 By Treatment
- 1.4.1 Chemotherapy
- 1.4.2 Surgical Resection
- 1.4.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,338 million → 2032: USD 1,931.81 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Zollinger-Ellison Syndrome (ZES) Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Zollinger-Ellison Syndrome (ZES) Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Zollinger-Ellison Syndrome (ZES) Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Zollinger-Ellison Syndrome (ZES) Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Zollinger-Ellison Syndrome (ZES) Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Zollinger-Ellison Syndrome (ZES) Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Zollinger-Ellison Syndrome (ZES) Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Zollinger-Ellison Syndrome (ZES) Treatment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,338 million → 2032: USD 1,931.81 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Zollinger-Ellison Syndrome (ZES) Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Diagnosis - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Blood Test
- 12.3.7.2 CT scan Ultrasound
- 12.3.7.3 X-Ray
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Users - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Specialty Clinics
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Treatment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Chemotherapy
- 12.5.7.2 Surgical Resection
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Zollinger-Ellison Syndrome (ZES) Treatment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Zollinger-Ellison Syndrome (ZES) Treatment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Zollinger-Ellison Syndrome (ZES) Treatment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Zollinger-Ellison Syndrome (ZES) Treatment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sanofi
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Pfizer Inc.
- 18.4 Novartis AG
- 18.5 Johnson & Johnson Services, Inc.
- 18.6 Bayer AG
- 18.7 Teva Pharmaceutical Industries Ltd.
- 18.8 GSK Plc.
- 18.9 Bristol Myers Squibb Company
- 18.10 F. Hoffmann-La Roche Ltd
- 18.11 Mylan N.V.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

