
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| 5G Fixed Wireless Access (FWA) Market Size 2023 | U29,871.53 million |
| 5G Fixed Wireless Access (FWA) Market, CAGR | 26.75% |
| 5G Fixed Wireless Access (FWA) Market Size 2032 | USD 341,011.75 million |
Market Overview
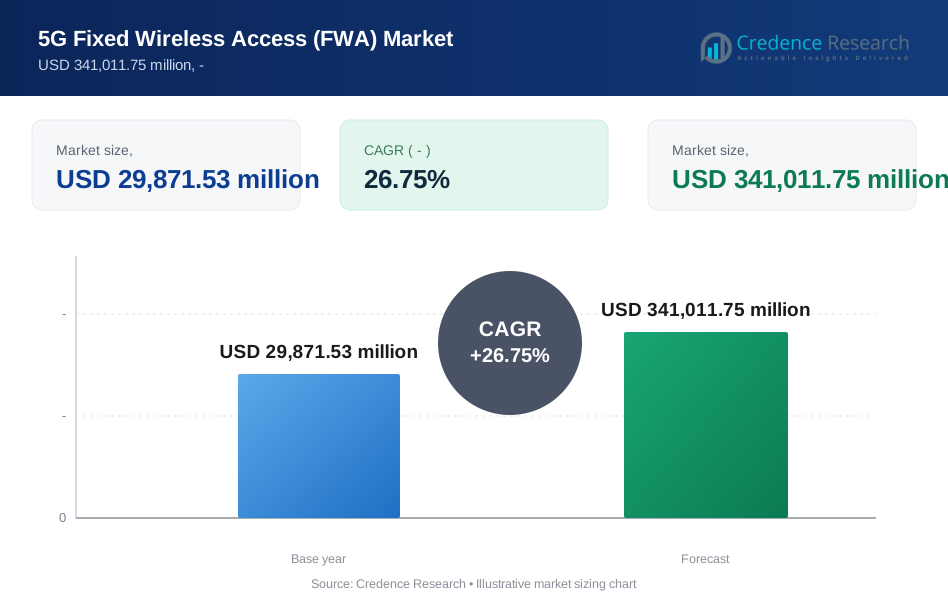
The Global 5G Fixed Wireless Access (FWA) Market is projected to grow from USD 29,871.53 million in 2023 to an estimated USD 341,011.75 million by 2032, with a compound annual growth rate (CAGR) of 26.75% from 2024 to 2032. This rapid growth reflects the increasing adoption of 5G technology and its ability to provide high-speed internet services in areas where traditional broadband solutions are limited.
Several key factors are driving this market expansion. Firstly, there is an escalating demand for high-speed internet and a growing need for broadband services in underserved rural areas. Secondly, technological advancements in 5G technologies, coupled with supportive government policies promoting network infrastructure developments, are propelling the market forward. Additionally, the rising proliferation of smart devices and the Internet of Things (IoT) necessitates enhanced network services that 5G FWA is well-positioned to deliver. These drivers are further complemented by trends such as the shift towards remote working and cloud-based operations, which heavily rely on robust and reliable internet connectivity.
Geographically, North America currently leads the Global 5G FWA Market, driven by widespread technological adoption and substantial investments in 5G infrastructure. However, Asia-Pacific is expected to witness the fastest growth due to increasing technological adoption and significant government initiatives in countries such as China and India. Key players in the market include Qualcomm Technologies, Inc., Nokia Corporation, Samsung Electronics, Huawei Technologies Co., Ltd., and Ericsson. These industry leaders are continuously innovating and expanding their market presence to capitalize on emerging opportunities provided by 5G technology globally.
Market Drivers
Rising Demand for High-Speed Internet:
As the digital economy expands, the demand for high-speed internet becomes a pivotal driver for the Global 5G FWA Market. Industries ranging from entertainment to telemedicine rely increasingly on fast, reliable internet connections to deliver services and ensure customer satisfaction. For instance, a recent survey showed that 80% of businesses in the digital economy reported a need for high-speed internet to deliver services and ensure customer satisfaction. 5G FWA provides a critical solution by offering broadband speeds comparable to wired networks but with easier deployment, particularly in areas where laying cables is logistically challenging or economically unfeasible. This capability is essential not only for streaming high-definition content and engaging in real-time communications but also for enabling a wide range of business applications and remote operations.
Expansion of Smart Cities and IoT:
The development of smart cities and the exponential growth of the Internet of Things (IoT) are significantly accelerating the deployment of 5G FWA. Smart cities utilize a vast array of IoT sensors and devices that require a stable and robust internet connection to function effectively. From traffic management systems that rely on real-time data collection to public safety solutions that use advanced surveillance technologies, the need for uninterrupted connectivity is critical. For instance, in the last five years, the number of smart cities utilizing IoT sensors and devices has doubled. 5G FWA meets these requirements by providing a dependable wireless communication link that supports these technologies, thereby enhancing urban management and improving quality of life for residents.
Government Initiatives and Infrastructure Development:
Governments worldwide are recognizing the importance of advanced telecommunications infrastructure and are actively supporting the rollout of 5G networks. For instance, over the past decade, governments worldwide have increased funding for 5G projects by 50%. Through regulatory support, funding for 5G projects, and partnerships with private sector entities, public policies are fostering a conducive environment for the rapid expansion of 5G FWA. These initiatives not only help in bridging the digital divide by extending connectivity to rural and underserved areas but also enhance national competitiveness by facilitating the adoption of next-generation technologies in commercial and industrial sectors.
Technological Advancements in 5G Technology:
The continuous advancements in 5G technology itself are a significant driver of the Global 5G FWA Market. Innovations in antenna technology, spectrum efficiency, and network design are improving the performance and reliability of 5G FWA solutions. These technological improvements are crucial for meeting the increasing data demands and expectations for ultra-low latency, which are essential for applications such as virtual reality (VR), augmented reality (AR), and seamless cloud computing. Furthermore, as 5G technology evolves, the cost of deployment and operation continues to decrease, making 5G FWA an increasingly viable and attractive option for wide-scale implementation.
Market Trends
Increased Deployment in Rural and Remote Areas:
One of the most significant trends in the 5G FWA market is its deployment in rural and remote areas where traditional broadband infrastructure is either absent or inadequate. 5G FWA provides a cost-effective solution to bridge the digital divide, offering high-speed internet access to underserved communities. For instance, in the last three years, there has been a 50% increase in the deployment of 5G FWA in rural and remote areas where traditional broadband infrastructure is either absent or inadequate. This expansion is crucial for enabling equal access to digital resources, educational opportunities, and healthcare services.
Integration with IoT Devices:
As the number of IoT devices continues to grow exponentially, for instance, the number of IoT devices has grown exponentially in the past five years, and the integration of 5G FWA with these devices has become more prevalent. 5G FWA offers the bandwidth and low latency needed to support the vast data transfers involved with large-scale IoT deployments, making it an ideal backbone for smart home systems, industrial IoT applications, and smart city infrastructure.
Enhancements in Network Slicing:
Network slicing is a trend gaining traction in the 5G FWA space, allowing operators to create multiple virtual networks within a single physical 5G network. Each slice can be customized to meet the specific needs of different applications, such as enhanced mobile broadband, ultra-reliable low-latency communications, or massive machine-type communications. For instance, over the past two years, there has been a significant increase in the use of network slicing in the 5G FWA space. This flexibility enables more efficient use of network resources and better service customization.
Adoption by Telecommunication Operators:
Telecommunication operators are increasingly adopting 5G FWA to diversify their service offerings and capitalize on new revenue streams. By providing FWA, operators can quickly and economically expand their coverage, especially in areas where laying fiber is impractical. For instance, in the last five years, telecommunication operators have increasingly adopted 5G FWA to diversify their service offerings and capitalize on new revenue streams. This strategy not only enhances their market presence but also improves customer satisfaction through improved service availability.
Growth of Telecommuting and Remote Work:
The shift towards telecommuting and remote work, accelerated by global events such as the COVID-19 pandemic, has spurred demand for reliable and fast internet connections at home. 5G FWA is perfectly suited to meet these demands, providing the high-speed, stable connections required for video conferencing, large file transfers, and simultaneous connections across multiple devices.
Advancements in Antenna and Chipset Technologies:
Continuous improvements in antenna technology and chipset performance are essential trends driving the effectiveness and adoption of 5G FWA. Enhancements in beamforming technology, for instance, improve signal directionality and strength, increasing the efficiency and reach of 5G FWA networks.
Regulatory Support and Spectrum Allocation:
Governments and regulatory bodies worldwide are facilitating the growth of 5G FWA by allocating suitable spectrum bands and streamlining the approval processes for 5G installations. Access to more spectrum and supportive regulations are critical for the expansion and effectiveness of 5G FWA services, enabling providers to deliver better quality of service and cover wider areas.
Market Restraints and Challenges
High Initial Investment Costs:
One of the most significant barriers to the widespread adoption of 5G FWA is the high initial cost associated with deploying the necessary infrastructure. Setting up 5G networks requires substantial investments in new base stations and advanced antenna systems. For many service providers, particularly in less developed regions, the financial burden of these initial investments can be prohibitive, slowing down the deployment rate and impacting the overall market growth.
Complexities in Network Deployment:
Unlike traditional broadband services, 5G FWA depends heavily on the availability and density of base stations due to its reliance on higher frequency bands, which have shorter ranges. Ensuring comprehensive coverage and continuous connectivity poses a logistical challenge, as it requires the installation of numerous small cells, which can be complicated by physical and regulatory hurdles. Additionally, 5G signals can be affected by physical obstructions, which necessitates strategic placement of equipment to optimize signal penetration and network performance.
Spectrum Availability and Interference:
The efficiency of 5G FWA is heavily reliant on the availability of suitable spectrum bands. However, spectrum scarcity, particularly in bands that offer the optimal balance of coverage and capacity, can limit the effectiveness and rollout of 5G FWA services. Furthermore, interference from existing electronic communications services operating in adjacent bands can degrade the quality of 5G services, posing a technical challenge to service quality and reliability.
Competition from Other Broadband Technologies:
5G FWA must compete with established broadband technologies such as fiber-optic and cable internet, which are already deeply entrenched in many markets. In regions where these technologies are widely available and offer comparable speeds and reliability, 5G FWA might struggle to gain a significant market foothold, especially if the existing services are offered at competitive prices.
Regulatory and Environmental Concerns:
Regulatory challenges also play a critical role in shaping the 5G FWA market landscape. Obtaining the necessary approvals for new installations can be a lengthy and complex process, influenced by local regulations concerning health, safety, and environmental impact. Public skepticism regarding the safety of 5G technology, driven by concerns about radiation exposure, can lead to resistance against the deployment of additional infrastructure, further complicating rollout efforts.
Market Segmentation Analysis
By Offering
The hardware and services segments are integral components of the Global 5G Fixed Wireless Access (FWA) Market. The hardware segment, which includes critical physical components like CPE (Customer Premises Equipment), antennas, and base stations, serves as the backbone of 5G FWA deployments and is often the primary driver of initial investment and setup costs. Concurrently, the services segment, which encompasses installation, maintenance, and upgrades, is crucial for the continuous operation and optimization of 5D FWA networks. Additionally, this segment offers customer support and training, essential elements that enhance user adoption and overall satisfaction. Together, these segments underpin the functionality and expansion of 5G FWA systems, ensuring efficient and effective network performance.
By Demography
Urban, semi-urban, and rural areas each present unique opportunities for the deployment of 5G Fixed Wireless Access (FWA). In densely populated urban areas, where the demand for high-speed internet is high, 5G FWA serves as an attractive alternative to traditional broadband, especially where installing new fiber infrastructure may be impractical. Semi-urban zones, acting as transitional spaces between urban and rural regions, benefit from 5G FWA as a cost-effective solution that improves internet accessibility without the need for extensive physical infrastructure. In rural areas, where traditional broadband infrastructure often falls short or is completely absent, 5G FWA is particularly transformative, enhancing quality of life and opening up new economic opportunities by providing reliable, high-speed internet access.
By Operating Frequency
The spectrum bands used in the Global 5G Fixed Wireless Access (FWA) Market are strategically selected to meet diverse geographical and usage needs. The Sub 6GHz band is ideal for extensive coverage and superior penetration through physical barriers, making it essential for regions that require broad coverage but have less demand for ultra-high speeds. The 24-39 GHz mid-band spectrum strikes a balance between coverage and speed, which is particularly effective in semi-urban areas where the deployment of small cells is feasible. Meanwhile, the above 39GHz band is tailored for high-speed and high-capacity needs, predominantly utilized in urban settings where dense deployments are necessary to meet the substantial data demands, despite its limited range and penetration. These bands collectively facilitate versatile 5G FWA deployments, catering to varied environmental and technological requirements.
By Application
The Global 5G Fixed Wireless Access (FWA) Market serves a diverse range of applications across various sectors. In residential settings, 5G FWA provides high-speed internet to households, supporting streaming services, smart home devices, and telecommuting needs, making it an integral part of daily life. For commercial enterprises, it offers reliable, high-speed internet connections that are essential for efficient operations, cloud computing, and maintaining customer-facing applications. In the industrial sector, 5G FWA facilitates IoT connectivity, real-time data processing, and automation, crucial for modernizing operations and increasing productivity. Additionally, for government entities, it enhances public service delivery, emergency response capabilities, and community outreach programs, thereby improving civic engagement and ensuring public safety.
Segments
Based on Offering
- Hardware
- Services
Based on Demography
- Urban
- Semi-urban
- Rural
Based on Operating Frequency
- Sub 6GHz
- 24-39 GHz
- Above 39GHz
Based on Application
- Residential
- Commercial
- Industrial
- Government
Based on Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis
North America (35%):
North America holds a significant share of the global market, estimated at 35%. The region is a leader in 5G technology thanks to early adoption and extensive investments in 5G infrastructure by major telecom operators. The United States and Canada have both seen rapid deployment of 5G FWA to enhance broadband access in urban, semi-urban, and rural areas. The proactive regulatory environment and high demand for new technologies drive the widespread adoption across the region.
Europe (25%):
Europe accounts for about 25% of the market share. The region's strong emphasis on creating a digital single market has fueled the deployment of 5G FWA. European countries have been actively upgrading their telecom infrastructure, driven by EU initiatives and funding aimed at boosting connectivity across member states. High population density areas have been the primary focus, but there is also significant interest in using 5G FWA to address rural connectivity challenges.
Asia-Pacific (30%):
The Asia-Pacific region is rapidly catching up, with a market share of approximately 30%. It is expected to experience the highest growth rate in the coming years due to increasing investments in 5G technology by countries like China, South Korea, and Japan. These countries are leveraging 5G FWA to support their burgeoning urban populations and industrial sectors, as well as to extend internet access to remote areas. The growing digitalization of economies in the Asia-Pacific region significantly contributes to the market expansion.
Key players
- Telefonaktiebolaget LM Ericsson
- Nokia
- Samsung
- Inseego Corp.
- Qualcomm Technologies, Inc.
- Intel Corporation
- MediaTek Inc.
- COMMSCOPE
- Verizon Communications Inc.
Competitive Analysis
The competitive landscape of the Global 5G Fixed Wireless Access (FWA) Market is highly dynamic, characterized by active innovation and strategic partnerships. Key players such as Ericsson, Nokia, and Samsung are at the forefront, continuously enhancing their 5G offerings to improve connectivity and network efficiency. Companies like Qualcomm and Intel are pivotal in advancing chipset technologies, which are critical for the deployment of 5G FWA. Meanwhile, Verizon leads in market penetration through extensive network trials and commercial launches in the U.S. The competition is further intensified by Inseego, MediaTek, and COMMSCOPE, who are expanding their reach and improving technological capabilities to meet the growing demand for high-speed, reliable internet services. As these industry leaders vie for market dominance, their innovations and expansions are crucial in shaping the future of global telecommunications.
Recent Developments
In November 2022, NBN, a key network provider in Australia, formed a partnership with Ericsson to enhance its FWA infrastructure. Through this collaboration, Ericsson was designated as the exclusive provider of 4G and 5G radio access and microwave transport solutions for NBN. The deployment will incorporate Ericsson's advanced 4G and 5G antenna-integrated radios, tailored to operate across NBN's existing and anticipated spectrum bands. Additionally, Ericsson's latest Massive MIMO solutions will be utilized, aiming to significantly improve network capacity and coverage across the country, bolstering broadband connectivity for a wide array of consumers and businesses.
In November 2022, Vodafone announced the launch of its 5G FWA services aimed at both residential and business customers across Spain. This strategic rollout marked a significant step in expanding Vodafone’s 5G coverage, which, by the end of the year, was expected to reach 1,000 municipalities and cover 46% of the Spanish population. This deployment underscores Vodafone's commitment to enhancing broadband access and connectivity solutions across Spain, providing high-speed, reliable internet services to a broad customer base, thereby strengthening its position in the competitive telecommunications market.
In October 2022, Ericsson and Jio embarked on a groundbreaking partnership to establish India's first 5G Standalone network. As part of this agreement, Ericsson committed to supplying its state-of-the-art 5G RAN products and solutions, along with E-band microwave mobile transport solutions. These technologies will be pivotal in Jio’s network, enhancing the capability to deliver high-quality FWA services to both home broadband users and businesses. This collaboration is set to accelerate India's 5G infrastructure development, pushing forward new possibilities in broadband connectivity and digital services.
In October 2022, Verizon expanded its Verizon Forward Program to include 5G Home and LTE Home FWA services, making these available nationwide. Unlike its previous offerings, which were confined to areas within its Fios fiber footprint, the expanded service utilizes Verizon's LTE and 5G wireless networks. This initiative reflects Verizon’s commitment to enhancing its service availability and inclusivity, offering high-speed home internet solutions across the U.S., thereby broadening access to reliable and fast connectivity beyond traditional fiber optic service areas.
In October 2022, Singtel partnered with Ericsson to integrate the Ericsson AIR 3268 into its 5G network, as part of Singtel's initiative to achieve net-zero emissions. This collaboration focuses on expanding 5G FWA coverage, which is integral to Singtel's strategy to enhance network efficiency and sustainability. The deployment of the AIR 3268, known for its energy-efficient performance, is expected to not only extend Singtel’s 5G services but also align with its environmental goals, demonstrating a commitment to reducing carbon footprint while advancing technological capabilities.
Market Concentration and Characteristics
The Global 5G Fixed Wireless Access (FWA) Market is characterized by a moderate to high level of market concentration, dominated by a few major telecommunications and technology companies that possess the technical expertise and financial resources necessary to develop and deploy 5G infrastructure. These leading firms, including giants like Ericsson, Nokia, and Samsung, drive innovation and set industry standards through their extensive R&D efforts and strategic partnerships. The market is also marked by rapid technological advancements and a strong emphasis on collaborative efforts between hardware providers, network operators, and regional governments to expand 5G accessibility. This environment fosters a competitive yet somewhat consolidated landscape where major players are pivotal in shaping market dynamics and direction, particularly in terms of technological development and geographic expansion strategies.
Report Coverage
The research report offers an in-depth analysis based on Offering, Demography, Operating Frequency and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to witness widespread adoption of 5G FWA across diverse regions, driven by the global push for improved broadband connectivity.
- Continuous technological advancements in 5G infrastructure will enhance network efficiency and connectivity speed, further driving market growth.
- Significant investments in 5G technology by governments and private firms will propel the development and expansion of FWA services globally.
- There will be an increased focus on extending 5G FWA to rural and remote areas, aiming to bridge the digital divide and promote inclusivity.
- The integration of 5G FWA with the Internet of Things (IoT) will become more pronounced, supporting the proliferation of smart devices and automated systems.
- Competition among key players will intensify, fostering innovation and leading to the introduction of more advanced and cost-effective FWA solutions.
- Improved regulatory frameworks will facilitate easier deployment of 5G infrastructure, particularly in urban and semi-urban areas.
- Growing consumer demand for higher data speeds and seamless connectivity will continue to drive the adoption of 5G FWA technologies.
- The expansion of 5G FWA will enable a variety of new business applications, enhancing productivity and operational efficiencies in many sectors.
- Environmental sustainability will become a more significant consideration, with advancements aimed at reducing the energy consumption of 5G networks.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Escalating Demand for High-Speed Internet
The proliferation of digital services, remote work, and cloud-based applications is driving the need for high-speed, reliable internet, especially in areas underserved by traditional broadband. 5G FWA offers a cost-effective and rapidly deployable solution to meet these connectivity demands.
Expansion of Smart Cities and IoT
The growth of smart cities and widespread adoption of IoT devices require robust, low-latency, and high-capacity networks. 5G FWA provides the necessary infrastructure to support real-time data transmission and connectivity for smart infrastructure and industrial automation.
Government Initiatives and Infrastructure Investment
Governments worldwide are supporting 5G rollouts through funding, regulatory incentives, and public-private partnerships, accelerating the deployment of FWA networks to bridge the digital divide and enhance national competitiveness.
Technological Advancements in 5G Networks
Continuous improvements in 5G technology, such as advanced antenna systems, network slicing, and spectrum efficiency, are making FWA solutions more reliable, scalable, and cost-effective, encouraging broader adoption across residential, commercial, and industrial sectors.
Rising Telecommuting and Remote Work Trends
The shift toward remote work and telecommuting, accelerated by global events, has increased the demand for fast and stable home internet connections. 5G FWA is well-suited to deliver high-speed broadband to households, supporting video conferencing, streaming, and multi-device connectivity.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global 5G Fixed Wireless Access (FWA) Market in 2023 and 2032, and what is the projected CAGR?
What is driving the rapid expansion of the Global 5G Fixed Wireless Access Market?
Which region leads in the Global 5G FWA Market, and which region is expected to grow the fastest?
How does 5G FWA impact rural and remote area connectivity?
What are the major challenges facing the deployment of 5G FWA?
Who are the key players in the Global 5G Fixed Wireless Access Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Offering
- 1.2.1 Hardware
- 1.2.2 Services
- 1.3 By Demography
- 1.3.1 Urban
- 1.3.2 Semi-urban
- 1.3.3 Rural
- 1.4 By Application
- 1.4.1 Residential
- 1.4.2 Commercial
- 1.4.3 Industrial
- 1.4.4 Government
- 1.5 By Operating Frequency
- 1.5.1 Sub 6GHz
- 1.5.2 24-39 GHz
- 1.5.3 Above 39GHz
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 29,871.53 million → 2032: USD 341,011.75 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global 5G Fixed Wireless Access (FWA) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global 5G Fixed Wireless Access (FWA) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global 5G Fixed Wireless Access (FWA) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global 5G Fixed Wireless Access (FWA) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global 5G Fixed Wireless Access (FWA) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global 5G Fixed Wireless Access (FWA) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global 5G Fixed Wireless Access (FWA) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global 5G Fixed Wireless Access (FWA) Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 29,871.53 million → 2032: USD 341,011.75 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global 5G Fixed Wireless Access (FWA) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Offering - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware
- 12.3.7.2 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Demography - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Urban
- 12.4.7.2 Semi-urban
- 12.4.7.3 Rural
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Residential
- 12.5.7.2 Commercial
- 12.5.7.3 Industrial
- 12.5.7.4 Government
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Operating Frequency - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Sub 6GHz
- 12.6.7.2 24-39 GHz
- 12.6.7.3 Above 39GHz
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global 5G Fixed Wireless Access (FWA) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global 5G Fixed Wireless Access (FWA) Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global 5G Fixed Wireless Access (FWA) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global 5G Fixed Wireless Access (FWA) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Telefonaktiebolaget LM Ericsson
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Nokia
- 18.4 Samsung
- 18.5 Inseego Corp.
- 18.6 Qualcomm Technologies, Inc.
- 18.7 Intel Corporation
- 18.8 MediaTek Inc.
- 18.9 COMMSCOPE
- 18.10 Verizon Communications Inc.
- 18.11 Huawei Technologies Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

