
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
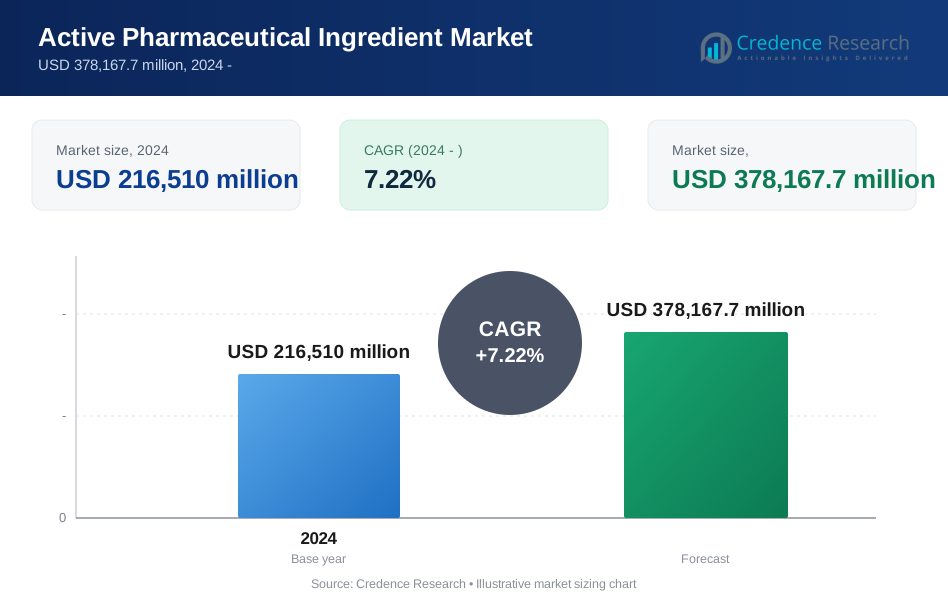
| Active Pharmaceutical Ingredient (API) Market Size 2024 | USD 216,510 Million |
| Active Pharmaceutical Ingredient (API) Market, CAGR | 7.22% |
| Active Pharmaceutical Ingredient (API) Market Size 2032 | USD 378,167.7 Million |
Market Overview:
The Active Pharmaceutical Ingredient (API) Market is anticipated to grow significantly, expanding from USD 216,510 million in 2024 to approximately USD 378,167.7 million by 2032, with a CAGR of 7.22% over the forecast period. This growth reflects increasing demand for high-quality APIs across therapeutic areas, driven by rising global healthcare needs, the growth of chronic diseases, and advances in personalized medicine. APIs, which are the biologically active components of medications, are essential in ensuring drug efficacy and safety, leading to strong demand in pharmaceutical manufacturing. The market includes synthetic, biotech, and chemical-based APIs, each meeting distinct therapeutic needs and addressing various treatment requirements.
Key drivers of market growth include the expanding prevalence of chronic and lifestyle-related diseases such as diabetes, cardiovascular conditions, and cancer. Additionally, rising government support and healthcare spending, especially in emerging economies, are promoting the development and accessibility of advanced therapies. Technological advancements in API manufacturing, such as high-potency APIs (HPAPIs) for targeted therapies and innovations in biotech APIs, are also driving market expansion. Regulatory agencies worldwide are increasingly stringent on drug quality and safety standards, prompting pharmaceutical companies to ensure the high quality and purity of their API production.
Regionally, North America holds a significant share of the API market, led by the United States, which benefits from a robust pharmaceutical industry, high R&D investment, and a strong focus on innovative therapies. Europe follows closely, driven by advanced healthcare infrastructure, a strong regulatory framework, and high demand for specialty drugs. The Asia-Pacific region is projected to see the fastest growth, supported by expanding manufacturing capabilities in countries like India and China, government incentives, and increasing healthcare access. Latin America, the Middle East, and Africa are also showing steady growth, as governments in these regions enhance healthcare spending and infrastructure, making API manufacturing and importation more feasible and accessible.
Market Drivers:
Rising Prevalence of Chronic Diseases:
The increasing prevalence of chronic diseases, including diabetes, cardiovascular disorders, and cancer, is a major driver in the Active Pharmaceutical Ingredient (API) Market. These conditions require continuous medication, often supported by high-quality APIs to ensure efficacy. For instance, the World Health Organization reported in 2023 that cardiovascular diseases account for nearly 17.9 million deaths each year globally, underscoring the need for reliable and effective pharmaceuticals. This demand is pushing pharmaceutical companies to prioritize API development and production for long-term treatment options.
Growth in Biologics and Targeted Therapies:
The surge in biologics and targeted therapies, particularly for personalized medicine, has intensified the demand for specialized APIs. Biotech-based APIs, used in monoclonal antibodies and immunotherapies, are now essential in treating conditions like autoimmune diseases and cancers. Companies like Pfizer and Roche are investing in high-potency APIs (HPAPIs) to support these innovative therapies. For example, in 2022, Roche increased its production of biotech APIs for targeted cancer treatments, reflecting the growing shift toward precision medicine and demand for advanced API manufacturing.
Advancements in API Manufacturing Technologies:
Technological advancements in API production, including continuous manufacturing and green chemistry, are transforming the efficiency and sustainability of the API industry. Continuous manufacturing allows for uninterrupted production, improving both yield and quality control. For instance, the U.S. Food and Drug Administration (FDA) supported API production innovations with grants for continuous manufacturing technologies in 2023, emphasizing efficiency, cost reduction, and reduced environmental impact. These advancements are making API manufacturing more flexible and scalable, particularly in developed markets with strong regulatory requirements.
Regulatory Support and Stringent Quality Standards:
Regulatory bodies worldwide are implementing stricter quality standards, promoting the adoption of high-quality and pure APIs. In the United States, the FDA’s focus on Good Manufacturing Practices (GMP) ensures quality and safety, particularly for critical therapies. The European Medicines Agency (EMA) enforces similar standards in Europe, driving API producers to meet stringent requirements. Governments in emerging markets are also enhancing regulatory oversight. For example, India’s Pharmaceutical Export Promotion Council (Pharmexcil) launched quality initiatives in 2023 to support API export standards, further driving API quality improvements globally.
Market Trends:
Increasing Outsourcing of API Manufacturing:
A growing trend in the API market is the outsourcing of production to contract manufacturing organizations (CMOs) and contract development and manufacturing organizations (CDMOs). This allows pharmaceutical companies to streamline operations, reduce costs, and focus on core competencies like R&D and marketing. For instance, in 2023, Pfizer expanded its CMO partnerships in Asia to support its API production for high-demand therapies. Outsourcing also provides access to specialized manufacturing technologies and regulatory compliance expertise, particularly beneficial for companies developing complex APIs.
Rise of Sustainable and Green Chemistry Practices:
Environmental sustainability is a significant trend in API manufacturing, with companies adopting green chemistry practices to reduce waste and emissions. Many manufacturers are shifting to eco-friendly solvents and energy-efficient production processes. For instance, AstraZeneca announced its commitment to reducing its environmental impact by implementing green chemistry principles across its API production lines. This approach aligns with global efforts to promote sustainable industrial practices, as regulatory bodies increasingly encourage pharmaceutical companies to prioritize environmental responsibility.
Emphasis on High-Potency APIs (HPAPIs) for Specialized Therapies:
The demand for high-potency APIs (HPAPIs), essential in cancer treatments and immunotherapies, is rising as pharmaceutical companies invest in specialized therapies. HPAPIs require stringent containment and specialized manufacturing due to their potent effects at low doses. Companies like Novartis and Eli Lilly are expanding HPAPI production to support the growing demand for precision medicine. For example, Novartis invested in advanced containment facilities in 2023 to meet the increasing need for these potent compounds, reflecting the pharmaceutical industry’s commitment to innovative and targeted therapies.
Integration of Digital and Automation Technologies:
Digitalization and automation are transforming API production, enhancing efficiency, precision, and traceability. Technologies like machine learning, real-time data monitoring, and robotic process automation (RPA) are now widely adopted to optimize manufacturing workflows. For instance, Sanofi introduced a data-driven API production system in 2022, enabling real-time monitoring and predictive maintenance to improve operational efficiency. These digital advancements reduce errors, ensure product quality, and support compliance with strict regulatory standards, positioning companies for long-term operational sustainability in a competitive market.
Market Challenges Analysis:
High Production Costs and Price Pressure:
One of the primary challenges in the Active Pharmaceutical Ingredient (API) Market is the high cost associated with API production, especially for complex and high-potency APIs (HPAPIs). API manufacturing requires stringent quality controls, specialized facilities, and containment measures, driving up costs. Additionally, increasing competition and regulatory demands add to financial pressures, particularly for companies in developed markets. This is compounded by pricing pressures from healthcare systems and insurers, which seek to control drug costs and often push for lower API prices, impacting manufacturers’ profit margins.
Stringent Regulatory Compliance and Quality Standards:
API manufacturers face strict regulatory requirements, particularly regarding quality, safety, and environmental impact. Regulatory bodies like the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) enforce comprehensive Good Manufacturing Practices (GMP) that require advanced quality control systems and regular audits. Compliance with these regulations is costly and time-consuming, especially for companies aiming to enter multiple markets with differing standards. For example, the FDA’s heightened focus on GMP compliance has led to more frequent inspections and greater scrutiny, increasing operational complexity for API manufacturers.
Dependence on Raw Material Supply Chains:
The API market is highly dependent on a global supply chain for raw materials, with a significant portion sourced from countries like China and India. Any disruptions, such as political tensions, trade restrictions, or pandemic-related shutdowns, can severely impact API production and lead to delays in drug manufacturing. In 2022, the Pharmaceutical Export Promotion Council (Pharmexcil) in India highlighted raw material supply as a critical risk for the API sector, emphasizing the need for supply chain diversification to mitigate vulnerabilities.
Environmental and Waste Management Challenges:
Environmental regulations surrounding waste disposal and emissions are becoming increasingly stringent, posing challenges for API manufacturers. The production of certain APIs generates hazardous waste and emissions, requiring specialized waste treatment facilities and processes. Compliance with environmental regulations, enforced by bodies like the U.S. Environmental Protection Agency (EPA), adds to operational costs. Additionally, meeting these standards often requires investment in sustainable technologies, which may be out of reach for smaller companies, creating barriers to entry and limiting the ability of API manufacturers to scale operations sustainably.
Market Segmentation Analysis:
By Type
The Active Pharmaceutical Ingredient (API) Market is segmented by type into synthetic and biotech APIs. Synthetic APIs, derived through chemical synthesis, currently dominate the market due to their versatility and well-established production processes. These APIs are widely used across therapeutic areas such as cardiovascular and respiratory drugs. Biotech APIs, which include high-potency APIs and biologics, are rapidly gaining traction, particularly in the oncology and immunology fields. Driven by advancements in biotechnology and rising demand for personalized medicine, biotech APIs represent a significant growth segment as they enable targeted and efficient therapies.
By Technology
The market is segmented by technology into traditional and high-potency API (HPAPI) production. Traditional API production includes conventional chemical synthesis, while HPAPI production involves specialized processes with stringent containment protocols. HPAPIs are increasingly used in cancer treatments and other targeted therapies, and their manufacturing requires advanced facilities and high safety standards due to their potency. Companies are investing heavily in HPAPI production, reflecting the growing need for precise, targeted therapies in modern healthcare.
By End User
End users of APIs include pharmaceutical companies, biotechnology firms, and contract manufacturing organizations (CMOs). Pharmaceutical companies represent the largest segment, as they require APIs for both branded and generic drug production. Biotechnology firms, however, are emerging as substantial end users, with increased focus on developing innovative biologics and biosimilars. CMOs also play a significant role, providing outsourced API production services that help companies reduce manufacturing costs and scale production, catering to both large pharmaceutical enterprises and smaller biotech firms seeking efficient, compliant production solutions.
Segmentations:
By Business Mode:
- Captive API
- Merchant API
By Synthesis Type:
- Synthetic
- Biotech
By Application:
- Cardiology
- Pulmonology
- Oncology
- Ophthalmology
- Neurology
- Orthopaedic
- Other
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a substantial share of the Active Pharmaceutical Ingredient (API) Market, accounting for approximately 35% of the global market. This dominance is driven by a robust pharmaceutical sector, high R&D investments, and advanced manufacturing capabilities, particularly in the United States. The U.S. market benefits from strong regulatory oversight by the Food and Drug Administration (FDA), which enforces rigorous standards for API quality and safety, fostering a market where high-quality APIs are prioritized. Furthermore, the demand for specialty drugs, biologics, and high-potency APIs (HPAPIs) continues to rise in North America, with companies investing heavily in innovative therapies for chronic diseases, cancer, and personalized medicine. Canada also contributes significantly to the region’s API market share, benefiting from government support for biotech development and pharmaceutical research.
Europe
Europe represents approximately 27% of the global API market, driven by a well-established healthcare infrastructure and stringent regulatory standards set by the European Medicines Agency (EMA). Key players in Germany, France, and the United Kingdom lead the region with advanced API manufacturing facilities, focusing heavily on sustainable practices and high-quality production. The region has also seen an increase in demand for biotech APIs due to the rise of personalized medicine and the prevalence of chronic diseases. In addition, Europe’s focus on environmentally sustainable production aligns with global trends, as companies prioritize green chemistry practices to meet regulatory demands for lower emissions and waste reduction. The region's strong emphasis on compliance with Good Manufacturing Practices (GMP) and other quality standards further supports market growth.
Asia-Pacific
The Asia-Pacific region is anticipated to experience the fastest growth in the API market, holding around 25% of the market share. Countries like China and India are key contributors, benefiting from large-scale manufacturing capabilities and cost-effective production. China, one of the world’s largest producers of APIs, supports a wide range of pharmaceutical manufacturing needs globally. India, known for its strong API export capabilities, is expanding its manufacturing base with government incentives and investments to reduce dependence on imports. Both countries are also enhancing regulatory frameworks to meet international standards, with the Indian government’s recent initiatives to improve quality and compliance through the Pharmaceutical Export Promotion Council (Pharmexcil) contributing to the region’s growth. Japan and South Korea also support the API market, particularly in advanced biotech and specialty APIs, driven by high healthcare standards and robust R&D infrastructure.
Latin America, Middle East, and Africa
LAMEA holds approximately 13% of the global API market, with countries like Brazil and Mexico contributing significantly in Latin America due to expanding pharmaceutical sectors and increasing healthcare spending. The Middle East, particularly the United Arab Emirates and Saudi Arabia, is focusing on healthcare infrastructure improvements and local API production to reduce import dependence. In Africa, the market remains smaller but has potential, as governments and international agencies increase investments in healthcare access and pharmaceutical production capabilities. However, regulatory challenges and limited infrastructure continue to be barriers in the region. As healthcare access improves, LAMEA is expected to become a growing market for APIs, especially for generic and essential drugs.
Key Player Analysis:
- Teva Pharmaceutical Industries Ltd.
- Pfizer Inc.
- Novartis International AG
- Sun Pharmaceutical Industries Ltd.
- Boehringer Ingelheim GmbH
- Merck & Co., Inc.
- Aurobindo Pharma
- Sanofi S.A.
- BASF SE
- Mylan N.V.
Competitive Analysis:
The Active Pharmaceutical Ingredient (API) Market is highly competitive, with established pharmaceutical and chemical companies vying for market share through advanced manufacturing capabilities, extensive product portfolios, and strong global distribution networks. Leading players like Pfizer, Novartis, and Merck & Co. leverage significant R&D investment and specialized technologies to produce high-quality APIs, including high-potency and biotech APIs, which support the growing demand for complex and targeted therapies. Competition is further intensified by cost pressures and stringent regulatory standards, as companies work to maintain compliance with Good Manufacturing Practices (GMP) and environmental guidelines across regions. Emerging players from Asia, particularly India and China, have gained ground through cost-efficient production, capturing a growing portion of global API supply. The competitive landscape is shaped by continuous innovation, strategic partnerships, and ongoing investments in technology, quality, and sustainability to meet the rising global demand for high-quality APIs in an evolving healthcare landscape.
Recent Developments:
- Sanofi launched an ambitious pipeline transformation in 2023, focusing on a 50% increase in Phase 3 studies by 2025 and targeting 25 new drug read-outs and up to 19 regulatory submissions over the next two years. This expansion includes significant investment in API development for blockbuster immunology assets and aims to solidify Sanofi’s leadership in immunology and neuroinflammation, supporting its commitment to serve more patients with innovative therapies.
- Pfizer in 2022 reinforced its commitment to advanced API production through partnerships to leverage artificial intelligence in drug discovery and manufacturing, enhancing efficiency and precision in its API pipeline. This initiative supports Pfizer’s strategic focus on increasing production scalability and quality control, ensuring a robust supply of APIs to meet the rising demand for complex therapies.
- Merck KGaA entered two strategic AI-driven drug discovery collaborations in 2023 with BenevolentAI and Exscientia, focusing on API innovation in oncology, neurology, and immunology. These partnerships aim to accelerate the discovery and development of first-in-class drug candidates, enhancing Merck’s API capabilities and aligning with the growing emphasis on precision medicine.
- Sanofi expanded its collaboration with Exscientia in 2022, adding 15 new drug programs with a focus on AI-driven target identification and lead optimization. This collaboration supports Sanofi’s R&D pipeline for APIs targeting metabolic, oncological, and inflammatory conditions, with an estimated value of up to $5.2 billion if all candidates advance successfully.
Market Concentration & Characteristics:
The Active Pharmaceutical Ingredient (API) Market is moderately concentrated, with several leading pharmaceutical and biotech companies holding substantial market shares due to their advanced R&D capabilities, large production facilities, and compliance with strict regulatory standards. Key players like Pfizer, Novartis, and Merck & Co. dominate the market, particularly in high-potency and biologic APIs, driven by the demand for specialized therapies and precision medicine. High entry barriers, including regulatory requirements, high production costs, and sophisticated technology needs, limit the entry of smaller players, favoring established firms with the resources to meet global standards. Meanwhile, cost-effective production hubs in Asia, especially in China and India, serve as essential suppliers, supporting global demand through contract manufacturing. This competitive landscape pushes companies to innovate in sustainable and efficient manufacturing practices, including green chemistry and digitalized production, while maintaining stringent quality control to remain competitive in a complex and growing market.
Report Coverage:
The research report offers an in-depth analysis based on Business Mode, Synthesis Type, Application, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for high-potency APIs (HPAPIs) will continue to grow as targeted therapies, especially in oncology, gain prominence.
- Biotech APIs, including monoclonal antibodies and gene therapies, will see increased adoption with advancements in biologics.
- Outsourcing of API manufacturing to contract development and manufacturing organizations (CDMOs) will rise, supporting cost efficiency and scalability for pharmaceutical companies.
- Green chemistry practices will become a priority, as companies adopt eco-friendly processes to meet stringent environmental regulations.
- Digital and automated manufacturing technologies will enhance efficiency, quality control, and regulatory compliance in API production.
- Growth in personalized medicine will drive demand for specialized APIs, particularly those used in rare disease treatments.
- Asia-Pacific will strengthen its role as a key API manufacturing hub, driven by cost advantages and expanding infrastructure in China and India.
- Regulatory standards will tighten, pushing manufacturers to maintain high-quality production and adopt Good Manufacturing Practices (GMP).
- Strategic partnerships and collaborations will increase as companies innovate in API development and scale production capabilities.
- Expanding healthcare infrastructure in emerging markets will boost API demand for essential and generic medicines, addressing broader healthcare needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Active Pharmaceutical Ingredient Market?
What factors are driving the growth of the Active Pharmaceutical Ingredient Market?
What are some challenges faced by the Active Pharmaceutical Ingredient Market?
Who are the major players in the Active Pharmaceutical Ingredient Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Active Pharmaceutical Ingredient Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Active Pharmaceutical Ingredient Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 216,510 million → forecast year: USD 378,167.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Active Pharmaceutical Ingredient Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Active Pharmaceutical Ingredient Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Active Pharmaceutical Ingredient Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Active Pharmaceutical Ingredient Market Drivers
- 3.3 Active Pharmaceutical Ingredient Market Restraints & Challenges
- 3.4 Active Pharmaceutical Ingredient Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Active Pharmaceutical Ingredient Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Active Pharmaceutical Ingredient Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Active Pharmaceutical Ingredient category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Active Pharmaceutical Ingredient Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Active Pharmaceutical Ingredient Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Active Pharmaceutical Ingredient market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Active Pharmaceutical Ingredient Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Active Pharmaceutical Ingredient Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Active Pharmaceutical Ingredient Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Active Pharmaceutical Ingredient (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Active Pharmaceutical Ingredient Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Active Pharmaceutical Ingredient Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Active Pharmaceutical Ingredient Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Active Pharmaceutical Ingredient Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Active Pharmaceutical Ingredient Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Active Pharmaceutical Ingredient Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Active Pharmaceutical Ingredient Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Active Pharmaceutical Ingredient Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Active Pharmaceutical Ingredient Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
