
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aerospace Riveting Equipment Market Size 2024 | USD 1,700 million |
| Aerospace Riveting Equipment Market, CAGR | 5.2% |
| Aerospace Riveting Equipment Market Size 2032 | USD 84.76 million |
Market Overview
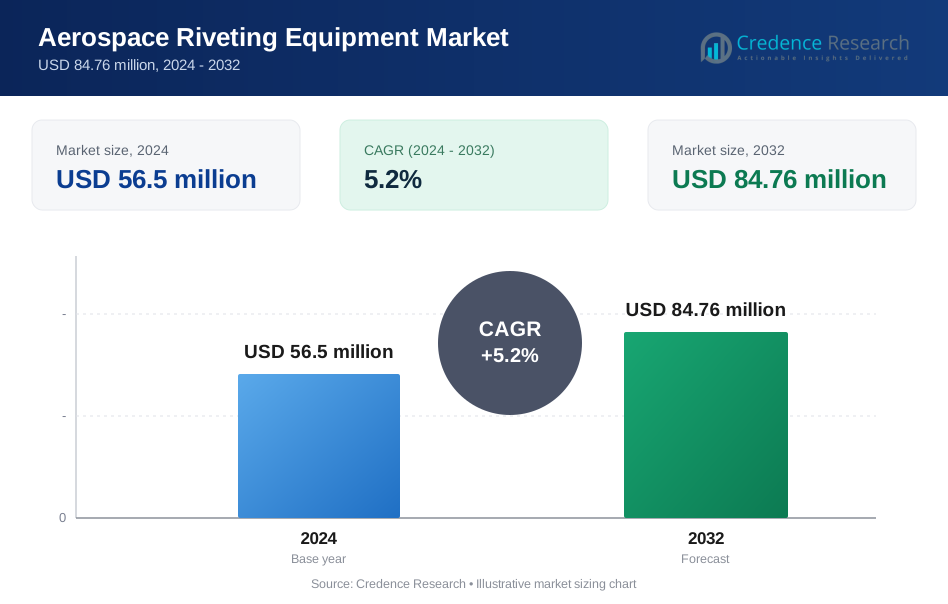
The aerospace riveting equipment market is projected to grow from USD 56.5 million in 2024 to USD 84.76 million by 2032, with a compound annual growth rate (CAGR) of 5.2%.
The aerospace riveting equipment market is driven by the increasing demand for lightweight, fuel-efficient materials in the aerospace industry, pushing manufacturers to adopt advanced riveting technologies for enhanced performance and structural integrity. The growing adoption of automation and additive manufacturing is further fueling market growth, as these technologies offer greater precision, customization, and cost-efficiency in producing fasteners and tooling. Additionally, the rise in aircraft production and the focus on aircraft maintenance, repair, and overhaul (MRO) services contribute to the need for reliable riveting solutions. Trends such as the development of battery-powered riveting tools and the integration of smart technologies, like intuitive user interfaces and brushless motors, are shaping the market landscape. As aerospace companies prioritize operational efficiency and sustainability, the demand for innovative, high-strength riveting equipment continues to increase, with a focus on reducing weight, improving joint strength, and enhancing overall durability. These factors are expected to drive consistent market growth over the forecast period.
The aerospace riveting equipment market is experiencing growth across various regions, with North America leading the market, holding a 38% share in 2024 due to the presence of major aerospace manufacturers. Europe follows with a 30% market share, driven by key players like Airbus and Rolls-Royce. The Asia-Pacific region, accounting for 18% of the market, is expanding rapidly due to rising investments in aerospace manufacturing and defense sectors, particularly in China and India. The Rest of the World, including Latin America, the Middle East, and Africa, contributes 14%, with emerging growth in regions like the UAE and Brazil. Key players such as Northrop Grumman, Henrob, Lockheed Martin, Boeing Commercial Airplanes, Eaton Aerospace, Huck Aerospace, PSM Aerospace, GESIPA Aerospace, Cherry Aerospace, Airbus Helicopters, and Avdel are instrumental in driving technological advancements and market development across these regions.
Market Insights
- The aerospace riveting equipment market is projected to grow from USD 56.5 million in 2024 to USD 84.76 million by 2032, with a CAGR of 5.2%.
- Increasing demand for lightweight, fuel-efficient materials in aerospace manufacturing is driving the need for advanced riveting technologies.
- Adoption of automation and additive manufacturing enhances precision, customization, and cost-efficiency in producing fasteners and tooling.
- Growing aircraft production and MRO services create continued demand for high-quality riveting equipment.
- Technological advancements, including battery-powered riveting tools and brushless motors, are shaping the market with improved performance.
- The market is expanding across regions, with North America holding 38% market share in 2024, followed by Europe with 30%, and Asia-Pacific with 18%.
- Key players such as Northrop Grumman, Henrob, Lockheed Martin, Boeing Commercial Airplanes, Eaton Aerospace, Huck Aerospace, PSM Aerospace, GESIPA Aerospace, Cherry Aerospace, Airbus Helicopters, and Avdel are driving technological innovation and market growth.
Market Drivers
Increasing Demand for Lightweight Materials
The growing emphasis on fuel efficiency in the aerospace industry has spurred the demand for lightweight materials, such as advanced composites and high-strength alloys, in aircraft production. Aerospace manufacturers are focused on reducing overall weight to enhance fuel efficiency, leading to the need for specialized riveting equipment. Rivets play a crucial role in ensuring the structural integrity of these materials, and advancements in riveting technologies are directly aligned with the industry's drive toward lighter, more efficient aircraft designs. For instance, riveting equipment developed by Triumph Group is designed to handle high-strength materials, ensuring the structural integrity of lightweight composites and alloys used in aircraft production. The adoption of lightweight riveting equipment that can handle high-strength materials is thus a key market driver.
Growing Aircraft Production and Fleet Maintenance
The rise in global air travel has led to increased aircraft production, further driving the demand for reliable and efficient riveting solutions. Manufacturers require advanced riveting equipment for the assembly of both commercial and military aircraft. Additionally, the need for maintenance, repair, and overhaul (MRO) services for existing fleets adds to the demand for riveting tools. For instance, riveting solutions provided by Atlas Copco are essential for the assembly and maintenance of both commercial and military aircraft, ensuring precision fastening solutions in MRO operations. As older aircraft are refurbished and updated with newer, lighter materials, the market for aerospace riveting equipment grows in parallel, driven by the continuous need for precision fastening solutions in MRO operations.
Technological Advancements in Riveting Equipment
Technological innovations are a significant driver in the aerospace riveting equipment market. The integration of automation and the development of battery-powered, brushless motor tools are transforming the industry. These advancements offer improved precision, faster operation, and greater durability, which are essential for aerospace applications. For instance, Stanley Black & Decker has developed battery-powered, brushless motor riveting tools that offer improved precision and faster operation for aerospace applications. Riveting equipment manufacturers are increasingly adopting automation and smart technologies, such as intuitive user interfaces and robotic systems, to meet the growing demands of the aerospace sector, resulting in better efficiency and reduced production costs.
Expansion of Additive Manufacturing in Aerospace
Additive manufacturing, or 3D printing, is making significant inroads in the aerospace sector by enabling the production of custom-designed fasteners and components. This technology allows for greater flexibility and cost-efficiency, especially in the production of small-batch, high-performance parts. For instance, 3D Systems Corporation integrates additive manufacturing with traditional riveting methods to produce lightweight, highly durable rivets tailored to specific aerospace applications. The integration of additive manufacturing with traditional riveting methods enhances design flexibility and the ability to produce lightweight, highly durable rivets tailored to specific applications. As additive manufacturing becomes more prevalent, it creates new opportunities for the aerospace riveting equipment market.
Market Trends
Increasing Use of Battery-Powered Tools
A key trend in the aerospace riveting equipment market is the growing adoption of battery-powered riveting tools. These tools are favored for their portability, ease of use, and the ability to operate in areas where access to electrical outlets may be limited. The development of tools with powerful brushless motors and long-lasting batteries has enhanced their efficiency, making them ideal for aerospace applications. For instance, battery-powered riveting tools developed by Stanley Black & Decker feature powerful brushless motors and long-lasting batteries, making them highly efficient for aerospace applications. As manufacturers focus on reducing operational downtime and increasing productivity, the demand for battery-powered riveting solutions continues to rise, driving innovation in this sector.
Integration of Automation and Robotics
Automation and robotics are transforming the aerospace riveting process. Manufacturers are increasingly integrating automated systems to streamline production, reduce human error, and improve the precision of riveting applications. Robotic riveting systems can perform high-precision tasks at higher speeds, which is crucial for the fast-paced demands of aircraft assembly. For instance, robotic riveting systems developed by KUKA Robotics can perform high-precision tasks at higher speeds, enhancing the efficiency and precision of aircraft assembly processes. Additionally, these automated systems can handle complex geometries and materials, offering increased flexibility. This trend aligns with the industry’s push for more efficient, high-quality manufacturing processes in aerospace production.
Advancements in Smart Technologies
The incorporation of smart technologies into aerospace riveting equipment is another notable trend. Tools with intuitive user interfaces, sensors, and real-time data monitoring are becoming more common. These innovations allow operators to track performance metrics, ensuring quality control and improving maintenance schedules. For instance, smart riveting tools developed by Atlas Copco feature intuitive user interfaces and real-time data monitoring, allowing operators to track performance metrics and ensure quality control. Smart technologies also enable greater customization of riveting equipment for specific applications, providing manufacturers with more adaptable and efficient tools. As digitalization continues to reshape industries, smart riveting tools are becoming a vital component of modern aerospace production.
Focus on Sustainable and Eco-Friendly Solutions
As the aerospace industry becomes more environmentally conscious, there is an increasing focus on sustainable and eco-friendly solutions in riveting equipment. Manufacturers are exploring materials and technologies that reduce waste and energy consumption. For instance, Triumph Group is developing more efficient, energy-saving riveting tools and processes that reduce waste and energy consumption, aligning with broader industry goals to reduce carbon footprints and minimize environmental impact. This trend aligns with broader industry goals to reduce carbon footprints and minimize environmental impact, further driving the demand for innovative, sustainable riveting solutions in the aerospace sector.
Market Challenges Analysis
High Initial Investment and Maintenance Costs
A significant challenge in the aerospace riveting equipment market is the high initial investment required for advanced tools and automated systems. Technologies such as robotic riveting systems, battery-powered tools, and automated riveting solutions are essential for maintaining precision, efficiency, and competitiveness in the aerospace sector. However, these advanced systems come with a substantial upfront cost, which can be a financial burden, particularly for smaller manufacturers or companies in developing regions. For large-scale aerospace manufacturers, the initial investment is often justified by long-term operational savings and productivity gains. However, smaller players may struggle to justify the costs due to budget constraints or limited resources. In addition, the ongoing maintenance and servicing of these high-tech systems can add significant operational costs. Regular maintenance, software updates, and component replacements are essential to ensure consistent performance and minimize downtime, creating an ongoing financial commitment. These high costs often make it difficult for smaller manufacturers to upgrade their systems or stay competitive, ultimately limiting their market participation.
Complex Regulatory Standards and Quality Control
The aerospace industry is highly regulated, with stringent standards for safety, durability, and performance. Manufacturers of riveting equipment must adhere to rigorous certification processes to ensure that their tools meet the required quality and regulatory standards. Compliance with international and local regulations adds complexity to the development process, as each market may have specific requirements that must be met before a product can be sold or used. This regulatory landscape can delay time-to-market for new technologies and innovations, as manufacturers must allocate considerable resources for testing, validation, and certifications. In addition, the need for impeccable quality control in riveting processes is paramount. Even the smallest defect in a rivet can lead to catastrophic failures, making quality control systems and inspections critical to maintaining safety standards. The constant need for high-level testing and adherence to strict guidelines creates additional pressure on manufacturers to continually improve their product offerings while managing the complexities of compliance, which often results in higher costs and extended development timelines.
Market Opportunities
The aerospace riveting equipment market presents significant opportunities driven by the increasing demand for advanced and lightweight materials in the aerospace industry. As aircraft manufacturers focus on improving fuel efficiency, there is a growing need for specialized riveting solutions that can handle high-strength alloys and composite materials. This trend opens opportunities for the development of innovative riveting tools designed to ensure structural integrity while reducing weight. Manufacturers are increasingly investing in research and development to create equipment capable of handling the specific demands of these new materials, offering high-performance solutions that cater to the evolving needs of the aerospace sector. Moreover, as the aviation industry continues to experience growth, there will be an ongoing demand for precision fastening solutions for both new aircraft production and the maintenance, repair, and overhaul (MRO) of existing fleets, further expanding the market potential for advanced riveting equipment.
Another opportunity lies in the growing adoption of automation and smart technologies within aerospace riveting equipment. As manufacturers strive for higher productivity and reduced operational costs, automation and robotics are becoming key drivers in production facilities. Riveting equipment that integrates robotic systems, intuitive user interfaces, and real-time data monitoring offers improved precision, faster operation, and greater efficiency. The expansion of additive manufacturing (3D printing) in the aerospace sector also creates new opportunities for customized riveting solutions tailored to specific designs and applications. This growing trend toward automated and customizable solutions positions the market for continued growth. Companies that can innovate and provide high-tech, cost-efficient riveting equipment will be well-positioned to capture new market share, particularly in emerging markets and smaller manufacturing sectors looking to adopt the latest technologies.
Market Segmentation Analysis:
By Rivet Type
The aerospace riveting equipment market can be segmented by rivet type, including blind rivets, solid rivets, and tubular rivets. Blind rivets are widely used due to their ability to be installed in tight spaces and are ideal for lightweight materials. Solid rivets are preferred for high-strength applications, while tubular rivets are commonly used in applications where extra strength is required. The demand for each rivet type depends on specific aerospace requirements and material specifications.
By Equipment Type
Aerospace riveting equipment is also segmented by equipment type, including manual riveting tools, pneumatic riveting tools, and robotic systems. Manual tools are cost-effective and suitable for small-scale operations. Pneumatic tools provide enhanced efficiency and precision, making them ideal for larger production volumes. Robotic riveting systems offer automation, improving consistency and reducing labor costs in high-demand environments. The selection depends on production volume and complexity.
By Mobility
The aerospace riveting equipment market is segmented by mobility, categorized into stationary and portable tools. Stationary riveting tools are typically used in assembly lines for high-volume production, offering greater precision and stability. Portable tools, such as battery-powered riveters, are preferred in MRO operations or on-site maintenance due to their flexibility and ease of use. The mobility segment is driven by the specific needs of the production environment.
Segments:
Based on Rivet Type
- Blind Rivet
- Semi- Tubular Rivet
- Solid Rivet
- Other Rivet Types
Based on Equipment Type
- Hydraulic Riveting Equipment
- Pneumatic Riveting Equipment
- Electric Riveting Equipment
Based on Mobility
- Fixed Equipment
- Portable Equipment
Based on Technology
- Automated Riveting Equipment
- Manual Riveting Equipment
Based on End Use
- Original Equipment Manufacturers (OEM)
- Maintenance, Repair, & Overhaul (MRO)
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest market share in the aerospace riveting equipment market, with a projected market share of 38% in 2024. The dominance of this region is driven by the presence of major aerospace manufacturers, such as Boeing, Lockheed Martin, and Raytheon Technologies, alongside an advanced aerospace supply chain. Additionally, the region is home to numerous aerospace MRO (maintenance, repair, and overhaul) facilities, further fueling demand for riveting equipment. With ongoing investments in technological advancements, such as automation and robotics, the demand for high-precision riveting tools in aircraft production and maintenance continues to grow. The U.S. government’s significant investments in defense and aerospace manufacturing also contribute to the region's leading position in the global market.
Europe
Europe is another key region in the aerospace riveting equipment market, accounting for a market share of 30% in 2024. The presence of key aerospace companies, such as Airbus and Rolls-Royce, drives demand for advanced riveting technologies in the region. Europe’s focus on sustainability in aviation, with initiatives like the "Clean Sky" program, has led to an increased need for lightweight materials and innovative riveting solutions. The demand for high-quality, durable riveting equipment is further heightened by the region's stringent regulatory standards. Additionally, the growth in aerospace MRO activities across countries like Germany, France, and the UK supports the continuous need for riveting equipment, particularly in the commercial aviation sector.
Asia-Pacific
The Asia-Pacific region is experiencing rapid growth in the aerospace riveting equipment market, with a projected market share of 18% in 2024. This growth can be attributed to the increasing investments in aerospace infrastructure, particularly in countries like China and India, which are expanding their aerospace manufacturing and maintenance capabilities. The rising middle-class population and the increasing demand for air travel are contributing to the increased production of aircraft in the region. Moreover, Asia-Pacific’s growing defense sector, particularly in countries such as India and Japan, is pushing the demand for advanced riveting solutions. The region's expanding manufacturing sector and the shift towards automation and robotics are expected to further drive market growth.
Rest of the World
The Rest of the World, including Latin America, the Middle East, and Africa, holds a smaller market share of 14% in 2024. However, these regions are witnessing gradual growth due to increasing air travel, defense sector investments, and a rise in aerospace manufacturing. The Middle East, particularly the United Arab Emirates, is a growing hub for aerospace manufacturing and MRO services, contributing to the demand for advanced riveting equipment. Similarly, Latin America’s increasing aerospace activity and rising demand for aircraft are expected to create opportunities for market growth in this segment.
Key Player Analysis
- Northrop Grumman
- Henrob
- Lockheed Martin
- Boeing Commercial Airplanes
- Eaton Aerospace
- Huck Aerospace
- PSM Aerospace
- GESIPA Aerospace
- Cherry Aerospace
- Airbus Helicopters
- Avdel
Competitive Analysis
The aerospace riveting equipment market is highly competitive, with leading players like Northrop Grumman, Henrob, Lockheed Martin, Boeing Commercial Airplanes, Eaton Aerospace, Huck Aerospace, PSM Aerospace, GESIPA Aerospace, Cherry Aerospace, Airbus Helicopters, and Avdel driving innovation and market growth. These companies are focused on advancing technology, offering high-quality and precision riveting solutions for the aerospace industry. Key strategies include investment in automation and robotics to improve efficiency and precision in aircraft assembly and maintenance. For instance, Boeing Commercial Airplanes has invested significantly in automation and robotics to enhance the efficiency and precision of their riveting processes. Additionally, the emphasis on lightweight materials and fuel-efficient designs is prompting players to develop specialized riveting tools capable of handling high-strength alloys and composite materials. With the rising demand for customization and flexibility, several manufacturers are adopting additive manufacturing techniques to produce tailored riveting solutions. Furthermore, companies are focusing on expanding their product offerings, strengthening their global presence, and meeting stringent regulatory standards to maintain a competitive edge. The market is expected to remain dynamic as technological advancements continue to shape industry trends.
Recent Developments
- In October 2023, Bosch Power Tools announced the release of 17 new power tools as part of their growing CORE18V platform, featuring innovations in cutting solutions, saw accessories, concrete and masonry solutions, rotary hammers, fastening and driving solutions, rivet solutions, and batteries and starter kits.
- In September 2023, Stanley Engineered Fastening (SEF) (US) announced plans to invest in additive manufacturing technologies to produce customized fasteners and tooling for aerospace applications, offering greater design flexibility and potentially lighter components.
- In October 2023, GESIPA launched the GBS 1000, a new battery-powered, semi-automatic blind rivet setter for lightweight and medium-duty applications, featuring a brushless motor, ergonomic design, and intuitive user interface.
- In January 2024, Rivit Srl, an Italian industrial fastener specialist, introduced a new line of battery-powered riveting tools designed for setting blind rivets and rivet nuts of various sizes and materials, featuring powerful brushless motors and long-lasting batteries to meet the needs of both professionals and DIYers.
- In April 2024, JRP, a specialized riveting brand, expanded its assortment of blind rivets, rivet nuts, and tooling to over 1,200 lines. The addition of closed-body rivet nuts offers manufacturers options for sealed ends to prevent water ingress, and two new rivet nut setting tools were introduced for setting JK nuts.
- In July 2023, Cherry Aerospace (US) unveiled a new type of lightweight rivet that enhances joint strength and fatigue resistance for aircraft structures, aligning with the industry's push for fuel-efficient materials and designs.
- In October 2023, Stanley Black and Decker brand DEWALT launched two new cordless, brushless rivet tools for fastening aluminum, steel, and stainless steel blind rivets.
Market Concentration & Characteristics
The aerospace riveting equipment market exhibits moderate to high concentration, with a few key players dominating the landscape. Major companies, including Northrop Grumman, Lockheed Martin, Boeing Commercial Airplanes, and Eaton Aerospace, lead in market share and technological advancements. These firms focus on offering high-performance riveting solutions, including automated systems, battery-powered tools, and advanced materials, to meet the increasing demands for lightweight, fuel-efficient aerospace designs. The market is characterized by continuous innovation, driven by the need for precision, durability, and compliance with stringent industry standards. Manufacturers are investing heavily in research and development to enhance product offerings, ensuring they can handle new materials such as advanced composites and high-strength alloys. Moreover, there is a growing emphasis on automation and robotics to improve manufacturing efficiency and reduce costs. While large players dominate, the market also accommodates niche players specializing in specific riveting solutions for aerospace applications.
Report Coverage
The research report offers an in-depth analysis based on Rivet Type, Equipment Type, Mobility, Technology, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The aerospace riveting equipment market is expected to experience steady growth, driven by increasing demand for lightweight, fuel-efficient materials in aircraft manufacturing.
- Technological advancements, including automation and additive manufacturing, will continue to enhance precision and cost-efficiency in riveting processes.
- Rising global air travel and increased aircraft production will contribute to the growing demand for advanced riveting equipment.
- The shift towards battery-powered riveting tools and smart technologies, such as brushless motors and intuitive interfaces, will shape the market landscape.
- Continued focus on sustainability and fuel efficiency in the aerospace industry will lead to further innovations in riveting equipment to reduce aircraft weight.
- Expansion in emerging markets like Asia-Pacific, particularly China and India, will drive new growth opportunities for aerospace riveting equipment suppliers.
- The market will see a rising demand for automation in both production and maintenance, pushing manufacturers to adopt robotic riveting systems.
- Maintenance, repair, and overhaul (MRO) services will continue to be a significant market driver, fueling the need for reliable and efficient riveting solutions.
- As aerospace manufacturers prioritize operational efficiency, there will be a growing need for highly durable and versatile riveting tools.
- Key players will focus on expanding their product portfolios, offering more specialized solutions to cater to a wider range of aerospace applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Aerospace Riveting Equipment Market?
What are the key segments within the Aerospace Riveting Equipment Market?
What are some challenges faced by the Aerospace Riveting Equipment Market?
Who are the major players in the Aerospace Riveting Equipment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Aerospace Riveting Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Aerospace Riveting Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 56.5 million → 2032: USD 84.76 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Aerospace Riveting Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Aerospace Riveting Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Aerospace Riveting Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Aerospace Riveting Equipment Market Drivers
- 3.3 Aerospace Riveting Equipment Market Restraints & Challenges
- 3.4 Aerospace Riveting Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Aerospace Riveting Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Aerospace Riveting Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Aerospace Riveting Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Aerospace Riveting Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Aerospace Riveting Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Aerospace Riveting Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Aerospace Riveting Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Aerospace Riveting Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Aerospace Riveting Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Aerospace Riveting Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Aerospace Riveting Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Aerospace Riveting Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Aerospace Riveting Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Aerospace Riveting Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Aerospace Riveting Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Aerospace Riveting Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Aerospace Riveting Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Aerospace Riveting Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Aerospace Riveting Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
