
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aluminum Alloys for Aerospace Market Size 2024 | USD 2,500 Million |
| Aluminum Alloys for Aerospace Market, CAGR | 5.9% |
| Aluminum Alloys for Aerospace Market Size 2032 | USD 3,955 Million |
Market Overview:
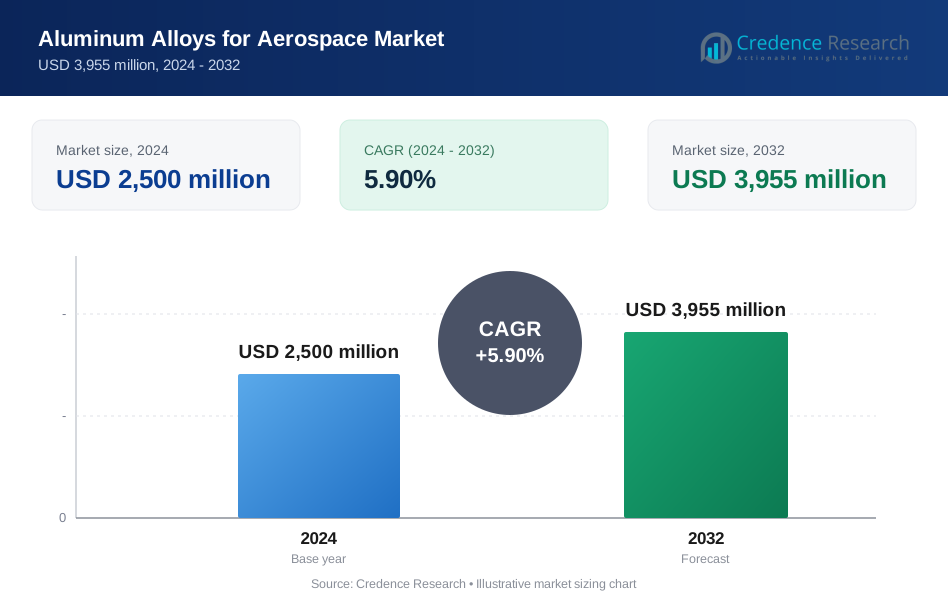
The Aluminum Alloys for Aerospace Market is projected to grow from USD 2,500 million in 2024 to USD 3,955 million by 2032, registering a CAGR of 5.9% during the forecast period.
The Aluminum Alloys for Aerospace Market growth is driven by the increasing demand for lightweight and high-strength materials in the aerospace industry to improve fuel efficiency and reduce emissions. Aluminum alloys offer excellent strength-to-weight ratios, corrosion resistance, and machinability, making them ideal for aircraft structural components and engine parts. The rising production of commercial and military aircraft, coupled with advancements in alloy composition and manufacturing techniques, further fuels market expansion. Additionally, stringent regulations on carbon emissions and the growing focus on sustainable aviation practices drive the adoption of aluminum alloys over heavier metals. Trends indicate a shift toward the development of advanced aluminum-lithium alloys and the integration of additive manufacturing processes to enhance material performance and reduce production costs. Furthermore, collaborations between aerospace manufacturers and material suppliers aim to innovate and tailor alloys for specific aerospace applications, strengthening market momentum and technological progress.
The Aluminum Alloys for Aerospace Market spans key regions including North America, Europe, and Asia-Pacific, each contributing significantly to global demand. North America leads with 35% market share, driven by its advanced aerospace manufacturing and strong defense sector. Europe holds 28%, supported by established commercial and military aerospace industries and stringent environmental regulations. Asia-Pacific commands 25% and exhibits rapid growth fueled by expanding commercial aircraft production, rising air travel, and increased defense spending. Other regions contribute the remaining market share with emerging aerospace activities. Leading players such as Alcoa Corporation, Constellium N.V., Kaiser Aluminum Corporation, Arconic Inc., and Novelis Inc. operate across these regions, leveraging regional strengths and customer bases. These companies focus on innovation, strategic partnerships, and expanding production to capture growing opportunities in diverse aerospace markets worldwide.
Market Insights:
- The Aluminum Alloys for Aerospace Market is projected to grow from USD 2,500 million in 2024 to USD 3,955 million by 2032, registering a CAGR of 5.9% during the forecast period.
- Growth is driven by rising demand for lightweight, high-strength materials to improve fuel efficiency and reduce emissions in the aerospace industry.
- Aluminum alloys provide excellent strength-to-weight ratios, corrosion resistance, and machinability, making them ideal for structural and engine components.
- Increasing production of commercial and military aircraft, combined with advancements in alloy composition and manufacturing techniques, fuels market expansion.
- Regulatory pressure on carbon emissions and the focus on sustainable aviation encourage the adoption of aluminum alloys over heavier metals.
- The market experiences a shift toward advanced aluminum-lithium alloys and integration of additive manufacturing processes to enhance material performance and reduce costs.
- Key regions include North America (35% market share), Europe (28%), and Asia-Pacific (25%), supported by major players like Alcoa Corporation, Constellium N.V., Kaiser Aluminum Corporation, and Arconic Inc.
Market Drivers:
Rising Demand for Lightweight and High-Strength Materials:
The Aluminum Alloys for Aerospace Market experiences strong growth due to the increasing need for lightweight yet durable materials in aircraft manufacturing. Airlines and manufacturers seek to reduce aircraft weight to improve fuel efficiency and lower operational costs. Aluminum alloys provide an optimal balance between strength and weight, making them essential for structural components and engine parts. The material’s high strength-to-weight ratio contributes to enhanced aircraft performance and safety. Its corrosion resistance also extends the lifespan of aerospace components, reducing maintenance requirements.
For instance, Boeing’s 787 Dreamliner incorporates advanced aluminum alloys alongside composites, resulting in significant weight reduction and improved fuel efficiency compared to earlier models.Expansion of Commercial and Military Aircraft Production:
Growth in both commercial and defense aviation sectors fuels the Aluminum Alloys for Aerospace Market significantly. Increasing global air travel stimulates the production of new commercial aircraft, which rely heavily on advanced aluminum alloys for manufacturing. On the military side, modernization programs and procurement of new fighter jets and transport aircraft boost demand. It enables manufacturers to meet stringent specifications for durability, weight, and performance. The rising investment in aerospace infrastructure worldwide supports steady market expansion. This growth trend positions aluminum alloys as a critical material choice across various aerospace platforms.
- For instance, the Boeing 787 Dreamliner uses 20% aluminum by weight, including high-strength alloys like 7075, for critical structures such as wing and tail leading edges, demonstrating the continued reliance on aluminum alloys even in advanced composite-rich designs.
Technological Advancements in Alloy Development and Manufacturing:
The Aluminum Alloys for Aerospace Market benefits from continuous innovations in alloy composition and processing techniques. Research focuses on developing aluminum-lithium alloys that offer superior mechanical properties and weight reduction. Manufacturers implement advanced fabrication methods, including additive manufacturing and precision casting, to optimize material use and reduce waste. These technological improvements enhance the performance of aerospace components and allow customization for specific applications. It also helps lower production costs and shortens manufacturing cycles.
Stringent Environmental and Regulatory Standards:
Regulatory pressure to reduce aviation emissions drives the demand for aluminum alloys in aerospace manufacturing. Governments worldwide enforce strict fuel efficiency and emission norms that require aircraft weight reduction. Aluminum alloys contribute to meeting these regulations by enabling lighter aircraft structures without compromising safety. The market benefits from policies encouraging sustainable aviation and the use of recyclable materials. Aerospace companies increasingly adopt aluminum alloys to comply with environmental standards and improve their sustainability profiles.
Market Trends:
Adoption of Advanced Aluminum-Lithium Alloys:
The Aluminum Alloys for Aerospace Market shows a clear trend toward the adoption of advanced aluminum-lithium alloys due to their enhanced strength and reduced weight. These alloys improve fuel efficiency and aircraft performance by decreasing the overall mass without compromising structural integrity. Manufacturers increasingly prefer these materials for critical components such as fuselage, wings, and landing gear. It allows aerospace companies to meet growing demands for lighter, more durable aircraft. The development of new alloy formulations focuses on improving fatigue resistance and corrosion protection.
- For instance, the fuselage of the Airbus A220 (formerly Bombardier CSeries) is built using a new generation of aluminum-lithium alloys, making the aircraft approximately 8 tons lighter than comparable models and allowing the fuselage to remain in service for 12 years before major overhaul, double that of conventional aluminum structures.
Integration of Additive Manufacturing Techniques:
The market experiences growing integration of additive manufacturing, or 3D printing, to produce complex aluminum alloy aerospace parts. This technology enables precise control over component geometry, weight, and material distribution, which traditional manufacturing methods cannot achieve easily. It shortens production cycles and reduces material waste, leading to cost savings. The Aluminum Alloys for Aerospace Market benefits from this shift through increased flexibility in design and rapid prototyping capabilities. Manufacturers use additive processes to produce lightweight structural parts and customized components.
- For instance, HRL Laboratories, with NASA as the first customer, developed the aluminum alloy powder 7A77 for aerospace applications, enabling the production of high-strength, 3D-printed aluminum parts that were previously unachievable with standard alloys.
Focus on Sustainability and Recyclability:
Sustainability gains importance in the Aluminum Alloys for Aerospace Market as aerospace companies prioritize eco-friendly materials and processes. Aluminum alloys offer excellent recyclability, reducing environmental impact and supporting circular economy principles. The market moves toward using recycled aluminum without sacrificing quality or performance. Manufacturers invest in closed-loop recycling systems to minimize waste and lower production costs. It aligns with global efforts to reduce carbon footprints and comply with environmental regulations. The increased demand for sustainable materials encourages further improvements in alloy design and recycling technologies.
Collaborations and Strategic Partnerships:
Strategic collaborations between aerospace manufacturers, material suppliers, and research institutions drive innovation in the Aluminum Alloys for Aerospace Market. These partnerships focus on developing new alloys, improving manufacturing processes, and enhancing material performance. Joint ventures accelerate the commercialization of cutting-edge technologies such as lightweight composites combined with aluminum alloys. It allows industry players to share expertise and resources to tackle complex challenges. These collaborations also facilitate faster adoption of advanced materials in aerospace applications. The trend strengthens market competitiveness and supports sustainable growth.
Market Challenges Analysis:
High Production Costs and Complex Manufacturing Processes:
The Aluminum Alloys for Aerospace Market faces challenges due to the high costs associated with producing advanced aluminum alloys. Specialized raw materials and precise alloying elements increase material expenses. It requires sophisticated manufacturing techniques, such as heat treatment and additive manufacturing, which demand significant investment in equipment and skilled labor. These factors raise overall production costs and can limit adoption, especially among smaller aerospace manufacturers. Controlling quality and consistency during alloy production remains complex, requiring rigorous testing and process optimization. The market must balance cost pressures while maintaining the high performance and safety standards demanded by aerospace applications.
- For instance, Arconic Inc. supplies advanced aluminum alloys for aircraft structures that require specialized heat treatment and precision machining, leading to higher capital investment and operating costs for aerospace manufacturers.
Competition from Alternative Lightweight Materials:
The market encounters increasing competition from alternative lightweight materials like composites and titanium alloys. These materials offer comparable or superior strength-to-weight ratios and corrosion resistance in certain aerospace applications. It challenges aluminum alloys to continually improve their mechanical properties and reduce weight to remain competitive. The integration of composites into aircraft structures limits the share of aluminum alloys in specific components. Moreover, the development of hybrid materials combining aluminum with composites adds complexity to material selection and manufacturing processes. The Aluminum Alloys for Aerospace Market must innovate to retain relevance amid evolving material preferences in the aerospace industry.
Market Opportunities:
Expansion into Emerging Aerospace Markets and Increased Aircraft Production:
The Aluminum Alloys for Aerospace Market presents significant opportunities due to the rapid growth of emerging aerospace markets in regions such as Asia-Pacific and the Middle East. Rising air travel demand and government investments in aerospace infrastructure drive new aircraft production in these areas. It enables manufacturers to expand their customer base and increase material supply contracts. The growing preference for fuel-efficient and lightweight aircraft creates further demand for advanced aluminum alloys. Collaborating with regional aerospace manufacturers can unlock new business avenues. This expansion supports market growth by addressing the needs of fast-developing aviation hubs and diverse aerospace segments.
Advancements in Material Science and Manufacturing Technologies:
Innovations in alloy development and manufacturing technologies offer substantial growth potential for the Aluminum Alloys for Aerospace Market. Research focused on aluminum-lithium alloys and other high-performance variants improves strength, weight reduction, and corrosion resistance. It opens possibilities for application in next-generation aircraft designs. The adoption of additive manufacturing and automation reduces production lead times and costs while enhancing precision. These technological advances allow customization of alloys to meet specific aerospace requirements. The market can capitalize on these opportunities by investing in research partnerships and scaling advanced manufacturing capabilities. This progress supports the ongoing evolution of aerospace materials toward higher efficiency and sustainability.
Market Segmentation Analysis:
By Alloy Type
The Aluminum Alloys for Aerospace Market divides into several alloy types, including the 2000, 5000, 6000, and 7000 series, along with other specialized alloys. The 7000 series, known for its high strength and toughness, holds a significant share due to its use in critical aerospace structures. The 6000 series offers good corrosion resistance and machinability, making it suitable for various components. The 2000 series provides excellent fatigue resistance and is preferred for structural applications requiring durability. The 5000 series balances strength and corrosion resistance, used in less demanding aerospace parts. Manufacturers continuously refine these alloys to meet evolving aerospace standards. It drives innovation in alloy compositions to enhance performance and reduce weight.
By Application
The market segments by application into commercial aircraft, military aircraft, business and general aviation, and other aerospace sectors. Commercial aircraft dominate demand for aluminum alloys, driven by increasing air travel and fleet expansion worldwide. Military aircraft require high-performance alloys for durability and safety under extreme conditions. Business and general aviation demand lightweight alloys to improve efficiency and reduce operational costs. It supports diverse aerospace needs through tailored material solutions. The variety of applications stimulates ongoing development of alloys optimized for specific performance criteria and operating environments.
By End-Use
Segmenting by end-use includes structural components, engine components, and other applications within aerospace manufacturing. Structural components represent the largest segment, where aluminum alloys provide the necessary strength and weight advantages for airframes, wings, and fuselage parts. Engine components require alloys that withstand high temperatures and mechanical stress. The market also serves various other aerospace parts, including landing gear and interior components. It focuses on delivering materials that meet rigorous safety and performance standards. This segmentation reflects the comprehensive role aluminum alloys play across aerospace manufacturing processes.
Segments:
Based on Alloy Type
- 2000 Series
- 5000 Series
- 6000 Series
- 7000 Series
- Others
Based on Application
- Commercial Aircraft
- Military Aircraft
- Business & General Aviation
- Others
Based on End-Use
- Structural Components
- Engine Components
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the Aluminum Alloys for Aerospace Market, accounting for 35% of the global market. The region benefits from a well-established aerospace manufacturing industry and advanced technological capabilities. Major aircraft manufacturers and defense contractors drive demand for high-performance aluminum alloys. It supports extensive research and development efforts focused on developing new alloys and manufacturing techniques. Strong government investments in aerospace and defense programs further boost the market. The presence of leading material suppliers and aerospace component manufacturers strengthens regional dominance. North America continues to lead due to innovation and a robust aerospace ecosystem.
Europe
Europe commands a 28% share of the Aluminum Alloys for Aerospace Market, driven by its large commercial and military aerospace sectors. The region houses key aircraft manufacturers and component suppliers that demand advanced aluminum alloys for lightweight and durable aircraft parts. Stringent environmental regulations push manufacturers to adopt fuel-efficient materials, boosting alloy adoption. It benefits from collaborations between aerospace firms and research institutions to enhance material performance. Europe’s focus on sustainability encourages recycling and the use of eco-friendly materials. Investment in aerospace infrastructure and modernization programs maintains steady market growth. Europe remains a critical region due to its mature aerospace industry and innovation capacity.
Asia-Pacific
The Asia-Pacific region holds 25% of the Aluminum Alloys for Aerospace Market and shows rapid growth potential. Rising air passenger traffic and expanding commercial aircraft production drive demand for aerospace materials. Governments invest heavily in developing aerospace hubs and manufacturing capabilities. It attracts global aerospace companies seeking cost-effective production and new market opportunities. The growing presence of low-cost carriers and regional airlines further supports alloy consumption. Increasing defense spending in countries like China and India stimulates military aerospace demand. Asia-Pacific’s expanding aerospace industry positions it as a vital growth engine for the market.
Key Player Analysis:
- Novelis Inc.
- Arconic Inc.
- Kaiser Aluminum Corporation
- Alcoa Corporation
- VSMPO-AVISMA Corporation
- AMAG Austria Metall AG
- Rio Tinto Alcan Inc.
- UACJ Corporation
- Norsk Hydro ASA
- Constellium N.V.
- KUMZ (Kamensk-Uralsky Metallurgical Works)
- Aleris Corporation
Competitive Analysis:
The Aluminum Alloys for Aerospace Market features a competitive landscape dominated by established global players such as Alcoa Corporation, Constellium N.V., Kaiser Aluminum Corporation, and Arconic Inc. These companies focus on product innovation, advanced alloy development, and strategic partnerships to maintain market leadership. It invests heavily in research and development to enhance alloy strength, corrosion resistance, and weight reduction. Market players compete by expanding manufacturing capacities and improving supply chain efficiency to meet rising aerospace demands. Several companies pursue mergers and acquisitions to broaden their product portfolios and geographical reach. Emerging players also contribute by offering specialized alloys tailored to specific aerospace applications. The competitive environment drives continuous technological advancement and cost optimization, positioning the Aluminum Alloys for Aerospace Market for sustained growth. Increasing demand for lightweight and high-performance materials further intensifies competition, pushing companies to adopt sustainable manufacturing practices and digital technologies to enhance product quality and operational efficiency.
Recent Developments:
- In April 2025, AMAG launched two new long-life alloys under the AL4®ever product family, focusing on a lower CO2 footprint while maintaining high performance, directly supporting the sustainability goals of the aviation industry.
- In December 2024, Rio Tinto announced a partnership to explore the development of Finland’s first low-carbon aluminum facility, leveraging its AP60 smelting technology.
- In March 2025, Hydro committed $156 million to build a new aluminum wire facility at its Karmoy smelter in Norway, aiming to supply high-quality aluminum wire for European infrastructure, supporting sectors including aerospace with advanced, low-carbon aluminum products.
Market Concentration & Characteristics:
The Aluminum Alloys for Aerospace Market exhibits a moderately concentrated structure, dominated by several key global players who hold significant market shares through advanced technological capabilities and extensive production capacities. Companies focus on continuous innovation in alloy development, quality enhancement, and strategic partnerships to strengthen their competitive positions. It faces high entry barriers due to the need for specialized manufacturing processes, strict regulatory compliance, and significant capital investment. The market characteristics include a strong emphasis on research and development to meet evolving aerospace standards and sustainability goals. Leading players prioritize expanding their geographic presence and optimizing supply chains to serve the growing aerospace demand effectively. This dynamic ensures steady growth while maintaining high product quality and performance standards. The Railway Service System Market shares similar traits of concentrated competition driven by technological advancement and regulatory requirements, reflecting industry-wide trends in complex, high-value sectors.
Report Coverage:
The research report offers an in-depth analysis based on Alloy Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Advanced aluminum-lithium alloys will gain wider use, enhancing aircraft strength while reducing overall weight.
- Additive manufacturing adoption will grow, enabling complex aluminum aerospace parts with improved precision and efficiency.
- Lightweight material demand will rise to help manufacturers meet increasingly strict fuel efficiency and emission standards.
- Aerospace manufacturers and suppliers will collaborate more closely to drive innovation and develop tailored aluminum alloys.
- Sustainable production and aluminum recycling will become priorities to reduce environmental impact across aerospace industries.
- Asia-Pacific’s expanding aerospace sector will present significant growth opportunities for aluminum alloy manufacturers.
- Technological improvements will lower manufacturing costs while increasing the quality and performance of aluminum alloys.
- Aluminum alloys will increasingly integrate with composites to create stronger, lighter, and more efficient aircraft structures.
- Customized alloy development will address specific aerospace application needs, improving material performance and durability.
- Companies will boost research and development investments to maintain competitiveness in the evolving aerospace materials market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Lightweight, High-Strength Materials
Aerospace manufacturers are increasingly adopting aluminum alloys due to their excellent strength-to-weight ratio, which helps reduce aircraft weight, improve fuel efficiency, and lower emissions, meeting both economic and regulatory requirements.
Expansion of Commercial and Military Aircraft Production
Rising global air travel and defense modernization programs are driving the production of new aircraft, which rely heavily on advanced aluminum alloys for structural and engine components, thus boosting market demand.
Technological Advancements in Alloy Development
Continuous innovation in alloy composition, such as the development of aluminum-lithium alloys and integration of additive manufacturing, is enhancing material performance, reducing production costs, and enabling more complex aerospace applications.
Stringent Environmental and Regulatory Standards
Tighter regulations on carbon emissions and sustainability in aviation are pushing manufacturers to use recyclable, lightweight aluminum alloys over heavier or less eco-friendly materials, accelerating market growth.
Collaborations and Strategic Partnerships
Partnerships between aerospace OEMs and material suppliers are fostering the development of customized alloys and advanced manufacturing processes, enabling tailored solutions for evolving aerospace requirements and expanding market opportunities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Aluminum Alloys for Aerospace Market?
What factors are driving the growth of the Aluminum Alloys for Aerospace Market?
What are the key segments within the Aluminum Alloys for Aerospace Market?
What are some challenges faced by the Aluminum Alloys for Aerospace Market?
Who are the major players in the Aluminum Alloys for Aerospace Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Structural Components
- 1.2.2 Engine Components
- 1.2.3 Others
- 1.3 By Alloy Type
- 1.3.1 2000 Series
- 1.3.2 5000 Series
- 1.3.3 6000 Series
- 1.3.4 7000 Series
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Commercial Aircraft
- 1.4.2 Military Aircraft
- 1.4.3 Business & General Aviation
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,500 million → 2032: USD 3,955 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aluminum Alloys for Aerospace Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aluminum Alloys for Aerospace Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aluminum Alloys for Aerospace Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aluminum Alloys for Aerospace Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aluminum Alloys for Aerospace Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aluminum Alloys for Aerospace Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aluminum Alloys for Aerospace Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aluminum Alloys for Aerospace Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,500 million → 2032: USD 3,955 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aluminum Alloys for Aerospace Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Structural Components
- 12.3.7.2 Engine Components
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Alloy Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 2000 Series
- 12.4.7.2 5000 Series
- 12.4.7.3 6000 Series
- 12.4.7.4 7000 Series
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Commercial Aircraft
- 12.5.7.2 Military Aircraft
- 12.5.7.3 Business & General Aviation
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aluminum Alloys for Aerospace End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aluminum Alloys for Aerospace Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aluminum Alloys for Aerospace Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aluminum Alloys for Aerospace Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Alcoa Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Constellium N.V.
- 18.4 Kaiser Aluminum Corporation
- 18.5 Arconic Inc.
- 18.6 Novelis Inc.
- 18.7 AMAG Austria Metall AG
- 18.8 Rio Tinto Alcan Inc.
- 18.9 UACJ Corporation
- 18.10 Norsk Hydro ASA
- 18.11 Aleris Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

