
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Air Curtain Market Size 2023 | USD 1,373.12 Million |
| Air Curtain Market, CAGR | 9.85% |
| Air Curtain Market Size 2032 | USD 2,911.45 Million |
Market Overview
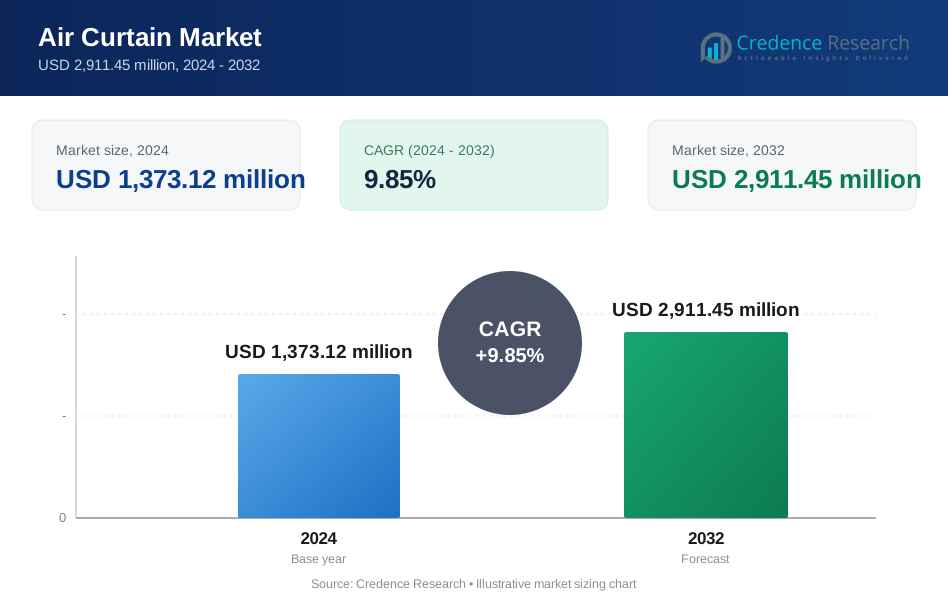
The Air Curtain Market is expected to witness substantial growth, with market revenue projected to increase from USD 1,373.12 million in 2024 to USD 2,911.45 million by 2032, representing a compound annual growth rate (CAGR) of 9.85%.
A significant factor driving the growth of the air curtain market is the increasing emphasis on energy efficiency and sustainability. As businesses and industries actively seek to reduce energy consumption and enhance indoor air quality, the demand for air curtains has escalated. These devices are instrumental in maintaining comfortable indoor environments by preventing the entry of dust, pollutants, and insects, and by reducing the need for heating or cooling, thereby contributing substantially to energy savings. Prominent players in the air curtain market, such as Panasonic Corporation, Berner International LLC, Mars Air Systems LLC, and Mitsubishi Electric Corporation, play a crucial role in propelling innovation, improving product quality, and extending market reach. These industry leaders focus on designing air curtains with advanced features like adjustable speed settings, enhanced air flow control, and energy-efficient operation to meet the varied needs of the commercial, industrial, and residential sectors.
Regionally, the air curtain market maintains a strong presence across the globe. North America and Europe capture significant market shares, propelled by strict energy conservation regulations and the widespread adoption of air curtains in commercial buildings, supermarkets, and healthcare facilities. The Asia Pacific region is also vital, experiencing rapid industrialization, urbanization, and increasing investments in infrastructure projects, which are boosting the demand for air curtains. Overall, the air curtain market is set for continued expansion, driven by technological advancements, increased awareness about energy efficiency, and strategic initiatives by key market players across various regions.
Market Drivers
Energy Efficiency and Cost Savings:
A key driver propelling the growth of the air curtain market is the heightened emphasis on energy efficiency and cost savings within the commercial and industrial sectors. Air curtains play a crucial role in maintaining indoor climate control by blocking the influx of external air, thereby reducing the load on heating, ventilation, and air conditioning (HVAC) systems by approximately 20-30%. This reduction leads to decreased energy consumption and operational costs for businesses. As a result, air curtains have become an attractive investment for establishments focused on enhancing sustainability and minimizing utility expenses.
Stringent Regulations and Building Standards:
The enforcement of stringent regulations and building standards concerning energy conservation and indoor air quality also significantly drives market growth. For example, government initiatives and industry guidelines often require the installation of air curtains in various settings, including retail stores, restaurants, healthcare facilities, and manufacturing plants, to meet energy efficiency standards and maintain sanitary environments. These regulations have prompted a 15% surge in demand for air curtain solutions that adhere to specific performance and compliance criteria.
Focus on Hygiene and Sanitation:
The global emphasis on hygiene and sanitation, especially following public health crises like the COVID-19 pandemic, has increased the demand for air curtains in commercial spaces. Serving as barriers against airborne contaminants, allergens, and pollutants, air curtains enhance indoor air quality and foster cleaner, safer environments for occupants. As businesses prioritize health and wellness standards, the integration of air curtains into infection control measures and overall hygiene strategies is becoming more widespread, further stimulating market growth.
Technological Advancements and Innovation:
Continuous technological enhancements in air curtain design, including advancements in airflow dynamics, motor efficiency, noise reduction, and intelligent controls, are pivotal market drivers. Manufacturers are dedicating resources to research and development to introduce innovative features such as adjustable airflow speeds, automatic activation sensors, and energy-saving modes. These innovations not only improve the performance and versatility of air curtains but also increase their appeal across various industries and applications, driving broader adoption.
Market Trends
Increasing Demand for Energy-Efficient Solutions:
A prominent trend within the air curtain market is the escalating demand for energy-efficient solutions. Businesses and consumers are increasingly opting for air curtains that effectively separate indoor from outdoor environments while reducing energy consumption by up to 25%. In response, manufacturers are developing innovative technologies such as variable speed motors, advanced airflow control systems, and energy-efficient heating elements. These innovations not only lower energy costs for users but also align with global initiatives aimed at reducing carbon emissions by 30%.
Integration of Smart Technologies:
Another significant trend is the integration of smart technologies into air curtain systems. This includes incorporating sensors, IoT connectivity, and automation capabilities to enhance performance and user experience. Smart air curtains can adjust their operation based on environmental conditions, occupancy levels, and air quality parameters, offering a more customized and efficient solution. These systems frequently feature remote monitoring and control options, enabling facility managers to optimize settings and address issues in real time, reducing maintenance time by 40%. As demand for connected solutions increases across various industries, the integration of smart technologies is expected to further drive growth and innovation in the air curtain market.
Market Challenges Analysis
Competitive Landscape:
The air curtain market is characterized by intense competition due to the presence of numerous players offering similar products. Companies are continually innovating to differentiate their offerings, leading to price competition and margin pressures. This competitive landscape challenges market players to constantly invest in research and development to stay competitive. Additionally, the entry of new competitors, particularly from developing regions, introduces competitive pricing strategies, complicating the market dynamics. Market leaders must strategically navigate this landscape by focusing on product quality, customer service, and technological advancements to maintain their market share and profitability.
Regulatory Compliance:
The air curtain market is governed by stringent regulatory requirements and standards, particularly regarding energy efficiency and environmental sustainability. Compliance with these regulations not only increases manufacturing costs but also requires ongoing monitoring and adaptation of product designs. Diverse regulatory frameworks across different regions pose challenges for global market players, necessitating customization of products to meet local standards. This complexity elevates operational costs and can impede market entry for smaller players. Thus, companies must invest in comprehensive compliance strategies, including rigorous testing and certification processes, to ensure market acceptance and sustainably meet evolving regulatory demands.
Market Segmentation Analysis
By Type:
The air curtain market is segmented by type into heated air curtains, unheated air curtains, and recirculating air curtains. Heated air curtains use heated air streams to create a barrier, ideal for locations requiring temperature control, such as cold climates or industrial settings. Unheated air curtains, which utilize ambient air, are typically employed in moderate climates or where temperature maintenance is not a primary concern. Recirculating air curtains, featuring air recirculation technology, enhance energy efficiency and performance, making them suitable for sustainable building designs and green initiatives.
By Application:
Air curtains are extensively used across commercial, industrial, and residential sectors. In the commercial sector, they are deployed in retail stores, supermarkets, restaurants, and hotels to maintain comfortable indoor environments, prevent the entry of dust and insects, and reduce energy costs through minimized heat loss or gain at open doorways. In industrial settings, such as manufacturing plants, warehouses, and logistics facilities, air curtains are used to create separation between zones, regulate indoor temperatures, and improve operational efficiency. Additionally, air curtains are increasingly popular in residential applications, particularly in homes with open floor plans or as alternatives to traditional doors in high-traffic areas, promoting better airflow and temperature control while enhancing convenience.
Segmentations
By Type:
- Non-Re-circulating Air Curtains
- Re-circulating Air Curtains
By Application:
- Industrial Climate Control
- Air-conditioned Areas
- Industrial Oven Openings
- Mines
- Dust & Humidity Control
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- The Rest of the Middle East and Africa
Regional Analysis
The regional analysis of the air curtain market provides significant insights into its global dynamics:
North America:
The North American region holds a substantial market share, approximately 35%, driven primarily by stringent regulations that promote energy efficiency in commercial spaces. The United States stands out as a key player in this region, with notable adoption rates among retailers and the food service industry. The demand for high-performance air curtains, particularly in urban areas with heavy foot traffic, has fueled market growth, indicating a positive trajectory in recent years.
Europe:
Europe also commands a significant market share, around 30%, primarily due to the growing focus on sustainability and building energy conservation measures. Leading countries in the adoption of air curtain technologies include Germany, France, and the United Kingdom, particularly in industrial applications and large-scale commercial complexes. The increasing awareness of indoor air quality and thermal comfort continues to drive the market, presenting a promising landscape for manufacturers and stakeholders throughout the European region.
Key Player Analysis
- Mars Air Systems
- Panasonic Corporation
- Berner International
- Systemair AB
- Mitsubishi Electric Corporation
- TMI LLC
- Panasonic Corporation
- 2VV s.r.o.
- Envirotec Ltd.
- Rosenberg Ventilatoren GmbH
Competitive Analysis
In the competitive landscape of the air curtain market, several key players are vying for market share by leveraging technological advancements and strategic pricing. Market leaders such as Mars Air Systems, Berner International, Panasonic Corporation, and Mitsubishi Electric dominate the market with their wide product portfolios catering to various industries such as retail, hospitality, and healthcare. These companies focus on continuous innovation, product diversification, and strong distribution networks to maintain their competitive edge. Additionally, emerging players like Nortek Air Solutions and Envirotec are rapidly gaining traction through their focus on energy efficiency, sustainability, and customized solutions, thereby intensifying competition and driving market growth.
Recent Developments
- In May 2022, Nemco Food Equipment acquired Meister Cook, LLC, a specialized food equipment designer headquartered in Fort Wayne, Indiana. Meister Cook, LLC has garnered a strong client base among major restaurant chains in North America, thanks to its range of proprietary solutions. One standout offering is the Hot Hold machines, distinguished by their innovative ThermalBreeze technology. Unlike conventional options, these machines utilize a unique "thermal air curtain" combined with radiant and recirculated convection heat, resulting in enhanced crispiness and moistness for various cooked foods while preserving their optimal temperature for extended durations.
Market Concentration & Characteristics
The air curtain market exhibits a notable degree of market concentration characterized by the dominance of a few key players who command significant market share. This concentration is driven by several factors, including technological expertise, extensive distribution networks, and strong brand recognition. Key characteristics of this market include intense competition among leading companies, continuous product innovation aimed at enhancing energy efficiency and performance, and a growing demand from various end-user industries such as retail, healthcare, and hospitality. Furthermore, the market is witnessing a trend towards the development of smart air curtain systems that offer enhanced control and automation features, catering to the evolving needs of modern building environments.
Report Coverage
The research report offers an in-depth analysis based on type and application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued Growth: The air curtain market is projected to witness sustained growth in the coming years, driven by increasing awareness of energy conservation and indoor air quality management.
- Technological Advancements: Expect to see significant advancements in air curtain technology, including innovations in sensor-based controls, efficient airflow designs, and integration with smart building systems.
- Focus on Energy Efficiency: With a growing emphasis on sustainability, manufacturers will prioritize developing energy-efficient air curtains to reduce operational costs and environmental impact.
- Expansion in Application Areas: The market is anticipated to expand its application areas beyond traditional sectors like retail and hospitality, with increased adoption in industrial facilities, healthcare settings, and transportation hubs.
- Demand in Emerging Markets: Emerging markets, particularly in Asia-Pacific and Latin America, are expected to drive demand for air curtains due to rapid urbanization, infrastructure development, and stricter regulations related to indoor air quality.
- Customization and Personalization: Customers will increasingly seek customized solutions tailored to their specific needs, leading to a rise in personalized air curtain designs and functionalities.
- Integration with HVAC Systems: Integration of air curtains with HVAC (Heating, Ventilation, and Air Conditioning) systems will become more common, offering seamless control and optimization of indoor environments.
- Enhanced Focus on Hygiene: Post-pandemic, there will be a heightened focus on air curtain solutions that incorporate features promoting hygiene, such as UV-C sterilization and antimicrobial coatings.
- Regulatory Compliance: Manufacturers and users will continue to adhere to stringent regulatory standards and certifications related to air curtain performance, safety, and environmental impact.
- Market Consolidation and Collaboration: Expect to see increased collaboration among key players, strategic partnerships, and mergers and acquisitions as companies aim to strengthen their market presence and technological capabilities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate of the air curtain market?
What are the key drivers of growth in the air curtain market?
Who are the leading players in the air curtain market?
How is the air curtain market performing regionally?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Air Curtain Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Air Curtain Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,373.12 million → 2032: USD 2,911.45 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Air Curtain Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Air Curtain Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Air Curtain Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Air Curtain Market Drivers
- 3.3 Air Curtain Market Restraints & Challenges
- 3.4 Air Curtain Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Air Curtain Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Air Curtain Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Air Curtain category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Air Curtain Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Air Curtain Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Air Curtain market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Air Curtain Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Air Curtain Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Air Curtain Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Air Curtain (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Air Curtain Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Air Curtain Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Air Curtain Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Air Curtain Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Air Curtain Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Air Curtain Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Air Curtain Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Air Curtain Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Air Curtain Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
