
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
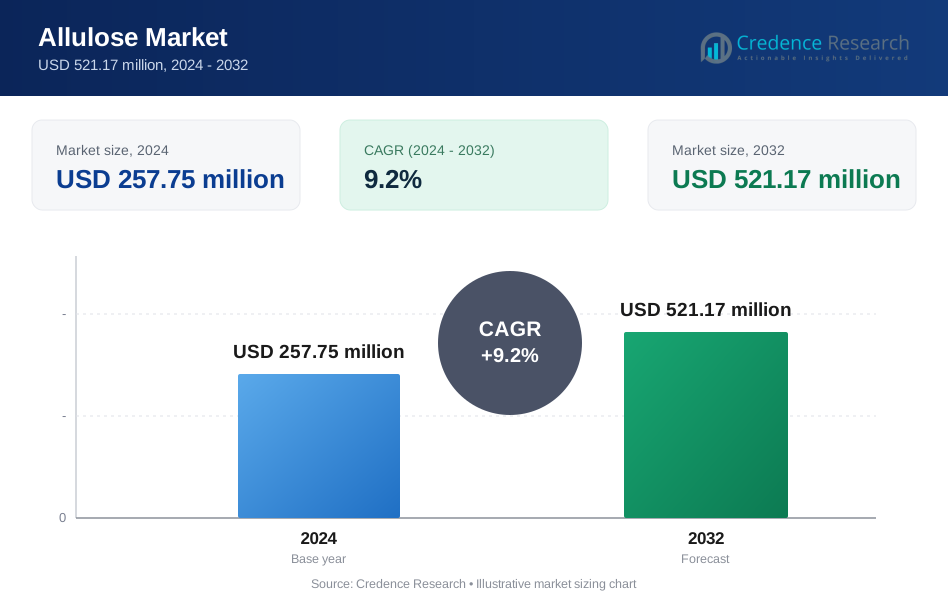
| Allulose Market Size 2024 | USD 257.75 Million |
| Allulose Market, CAGR | 9.2% |
| Allulose Market Size 2032 | USD 521.17 Million |
Market Overview:
The Allulose Market is projected to grow from USD 257.75 million in 2024 to an estimated USD 521.17 million by 2032, with a compound annual growth rate (CAGR) of 9.2% from 2024 to 2032.
The allulose market is primarily driven by the growing global emphasis on health and wellness, particularly amid rising cases of obesity, diabetes, and other lifestyle-related diseases. As a low-calorie sweetener with approximately 70% of the sweetness of sucrose but only 10% of its calories, allulose is gaining widespread popularity among health-conscious consumers. Its ability to mimic the texture and taste of sugar while offering minimal impact on blood glucose levels has made it a preferred choice in food and beverage formulations. Key industries such as bakery, confectionery, and beverages are incorporating allulose to meet the increasing demand for sugar-free and low-calorie alternatives. Regulatory support has further accelerated market growth, with agencies like the FDA approving allulose as a safe ingredient and excluding it from "total sugars" and "added sugars" labels in the United States. Furthermore, advancements in production technologies, including enzymatic conversion and microbial fermentation, are enhancing cost-effectiveness and scaling up production capacities, encouraging widespread adoption. These factors collectively position allulose as a pivotal ingredient in the global shift toward healthier diets.
North America continues to dominate the global allulose market, underpinned by a strong emphasis on health-conscious lifestyles, widespread consumer awareness, and favorable regulatory policies. The United States, the leading contributor, benefits from high adoption rates of low-calorie sweeteners in diverse applications, including ready-to-eat snacks, beverages, and dairy products. Europe is also witnessing steady growth, driven by increasing health awareness, stringent sugar reduction policies, and advancements in product formulations. The Asia-Pacific region, however, is emerging as the fastest-growing market, fueled by rapid urbanization, a burgeoning middle-class population, and increasing consumer focus on wellness and nutrition. Markets in China, Japan, and South Korea are particularly robust, supported by a growing preference for functional and healthy food options. In contrast, Latin America and the Middle East & Africa are at a nascent stage but exhibit strong potential due to increasing investments in food and beverage industries, rising disposable incomes, and a gradual shift toward healthier eating habits. These regions are expected to contribute significantly to the market’s expansion in the coming years.
Market Drivers:
Rising Health Awareness and Prevalence of Lifestyle Diseases:
The increasing prevalence of lifestyle diseases such as diabetes, obesity, and cardiovascular disorders is a primary driver for the allulose market. As consumers grow more health-conscious, there is a noticeable shift toward adopting healthier dietary options. Allulose, with its low-calorie profile and minimal impact on blood sugar levels, offers a viable alternative to traditional sweeteners and sugar. For instance, Tate & Lyle's DOLCIA PRIMA® Allulose provides about 90% fewer calories than sucrose and does not raise blood glucose or insulin levels. Its ability to replicate the sweetness and functional properties of sucrose without the associated calories has positioned it as an ideal choice for health-conscious consumers. This trend is further supported by growing awareness campaigns by health organizations and governments emphasizing the benefits of reducing sugar intake
Regulatory Support and Labeling Advantages:
Supportive regulatory frameworks have significantly bolstered the growth of the allulose market. In markets such as the United States, the Food and Drug Administration (FDA) has recognized allulose as safe for consumption and excluded it from the "added sugars" and "total sugars" sections of nutritional labels. This regulatory advantage has encouraged manufacturers to incorporate allulose into their product formulations, allowing them to offer healthier alternatives without compromising on sweetness. Similarly, global regulatory bodies in Europe and Asia-Pacific are increasingly aligning their policies with the growing demand for sugar reduction, further driving market expansion.
Expanding Applications Across the Food and Beverage Industry:
Allulose's versatility is another key factor driving its market growth. Its ability to replicate sugar’s taste, texture, and functional properties makes it a highly desirable ingredient across various food and beverage applications. Industries such as bakery, confectionery, dairy, and beverages have embraced allulose to meet consumer demand for low-calorie, low-glycemic products. Additionally, its suitability for keto, vegan, and diabetic-friendly diets has widened its appeal among niche consumer segments. The increasing penetration of allulose in ready-to-eat snacks, protein bars, and low-calorie beverages further highlights its importance as a key ingredient in modern food formulations.
Technological Advancements and Cost-Efficient Production:
Technological advancements in the production of allulose are making it more cost-effective and accessible, driving its widespread adoption. Innovations in enzymatic conversion processes and microbial fermentation methods have significantly improved yield efficiency while reducing production costs. For instance, advancements in D-allulose 3-epimerase immobilization techniques have enhanced enzyme stability and reusability, making production more efficient. These advancements have enabled manufacturers to scale up production to meet the growing global demand. Additionally, ongoing research into sustainable production methods is aligning with broader consumer trends favoring environmentally friendly practices. The increasing availability of allulose at competitive prices has incentivized its adoption, not only among large-scale manufacturers but also among small and medium-sized enterprises in the food and beverage sector
Market Trends:
Increasing Demand for Low-Calorie Sweeteners:
The demand for low-calorie sweeteners has surged globally as consumers become more health-conscious and prioritize reducing sugar intake without sacrificing sweetness. This trend is particularly strong in regions such as North America and Europe, where regulatory bodies and public health campaigns have emphasized sugar reduction to combat rising obesity rates. Allulose stands out among alternative sweeteners due to its natural occurrence and similarity to sucrose in taste and texture, enabling its incorporation into mainstream food and beverage products. In recent years, the market has witnessed a shift from synthetic sweeteners to natural and plant-based alternatives, driving sustained interest in allulose as a preferred option.
Focus on Clean Label and Natural Ingredients:
A growing preference for clean-label products has shaped consumer choices in the food and beverage industry, significantly impacting the allulose market. Shoppers increasingly demand transparency in product labeling, seeking items with natural ingredients and minimal processing. As a naturally occurring rare sugar found in fruits such as figs and raisins, allulose aligns perfectly with these consumer expectations. Manufacturers are leveraging this trend to highlight allulose's natural origins, which has contributed to its adoption across premium and health-focused product lines. For instance, according to Ingredion, "Allulose can replace sugar 1-1 with the guidance of approved use levels. To give an example, one can take x% sugar out in a recipe and put x% allulose instead with similar characteristics to the sugar counterpart". The clean-label trend is particularly pronounced in Asia-Pacific markets, where consumer scrutiny of artificial ingredients has intensified in recent years.
Expansion in Plant-Based and Functional Foods:
The rise of plant-based and functional foods has emerged as a key trend influencing the allulose market. Consumers seeking products that cater to vegan, ketogenic, and diabetic-friendly diets have increasingly turned to allulose for its compatibility with these lifestyles. Manufacturers are incorporating allulose into plant-based protein bars, dairy alternatives, and functional beverages to appeal to this growing demographic. For example, Magic Spoon, known for its zero sugar, low carb, high protein cereal, uses "allulose, which is a natural sugar, [to] create a sweetness that is neither artificial nor sharp". In addition, its prebiotic properties, which may support gut health, have drawn attention from companies looking to market health-enhancing food and beverage products. This expansion into functional food categories highlights the growing versatility of allulose in meeting diverse dietary needs.
Growth of E-Commerce and Direct-to-Consumer Channels:
The rise of e-commerce and direct-to-consumer sales channels has played a crucial role in broadening the availability of allulose products. Online platforms have become an essential avenue for distributing specialty and health-focused products, enabling consumers to access a variety of allulose-based items from anywhere. This trend has been particularly influential in emerging markets, where traditional retail infrastructure is still developing. Small and medium-sized brands have leveraged e-commerce platforms to introduce innovative allulose-based products, further diversifying the market. The global shift toward online shopping is expected to accelerate the visibility and adoption of allulose among health-conscious consumers, particularly in regions with rising internet penetration rates.
Market Restraints and Challenges:
High Production Costs and Limited Availability:
One of the primary challenges in the allulose market is its high production cost compared to traditional sweeteners like sucrose or high-fructose corn syrup. The process of extracting and refining allulose, often through enzymatic conversion of fructose, is complex and resource-intensive, leading to higher manufacturing expenses. This cost factor limits its widespread adoption, especially in price-sensitive markets where affordability is a key consideration. Additionally, the natural occurrence of allulose in limited quantities in foods such as figs and raisins adds to its scarcity, further driving up costs and restricting its availability.
Regulatory and Labeling Constraints in Emerging Markets:
While regulatory support has been a significant driver in developed markets like the United States, the lack of clear regulatory frameworks in certain regions poses a challenge for the global expansion of the allulose market. In some countries, allulose is yet to receive approval as a food ingredient, hindering its adoption in local markets. Inconsistent labeling requirements across regions also create complications for manufacturers, who must navigate varying compliance standards to ensure product acceptance. These regulatory barriers slow the market's growth potential and create uncertainty for manufacturers looking to expand internationally.
Consumer Awareness and Misconceptions:
Despite growing demand for low-calorie and sugar-free alternatives, a lack of widespread consumer awareness about allulose remains a restraint. Many consumers are unfamiliar with the benefits of allulose or confuse it with artificial sweeteners, which may have negative perceptions due to health concerns. Overcoming these misconceptions requires significant investment in marketing and education campaigns, which can be cost-prohibitive for smaller manufacturers. Building trust and familiarity among consumers is critical to driving adoption but remains a challenge for the industry.
Market Segmentation Analysis:
The allulose market is segmented based on product type and application, catering to a wide array of industries and consumer needs.
By product type, the market includes powder, liquid, and crystal forms of allulose. The powder segment dominates the market due to its versatility, ease of handling, and suitability for applications such as bakery, confectionery, and table-top sweeteners. Liquid allulose is gaining traction in beverages and sauces due to its seamless integration into liquid formulations, while the crystal segment is emerging for use in premium and specialty products requiring texture and granularity.
By application, the food sector represents the largest share, with significant contributions from sub-segments like bakery and confectionery, dairy and frozen desserts, and sauces and dressings. The bakery and confectionery industry leverages allulose for its low-calorie properties and ability to replicate the sweetness and texture of sugar, while dairy products and frozen desserts benefit from its compatibility with low-fat and low-sugar formulations. Table-top sweeteners have also emerged as a growing segment due to increasing consumer demand for convenient sugar alternatives. In the beverages category, allulose is widely used in energy drinks, soft drinks, and flavored waters, aligning with consumer demand for sugar-free and low-calorie beverages. The pharmaceutical industry is also exploring allulose for its potential applications in formulating diabetic-friendly and low-glycemic medications. These diverse applications highlight the market's broad scope and its ability to adapt to evolving consumer preferences across multiple industries.
Segmentation:
By Product
- Powder
- Liquid
- Crystal
By Application
- Food
- Bakery & confectionary
- Table-top sweetener
- Dairy and frozen desserts
- Sauces and dressings
- Ice Creams and Desserts
- Beverages
- Pharmaceuticals
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The allulose market exhibits diverse growth patterns across regions, driven by varying levels of consumer awareness, regulatory support, and industry adoption. North America holds the largest market share, accounting for approximately 35% of the global market. The region's dominance is fueled by robust consumer demand for low-calorie sweeteners and strong regulatory support. The United States is a major contributor, where the Food and Drug Administration (FDA) has approved allulose for use in various food and beverage products and excluded it from "added sugars" labeling. This regulatory advantage has encouraged manufacturers to develop innovative allulose-based products, catering to health-conscious consumers and driving regional market expansion.
Europe represents the second-largest market, contributing about 25% of the global share. The region's growth is underpinned by rising consumer awareness of the health risks associated with excessive sugar consumption and increasing demand for clean-label and natural products. Countries such as Germany, the United Kingdom, and France are leading adopters, with significant uptake in the bakery, confectionery, and dairy industries. However, the region faces challenges related to slower regulatory approvals, which may limit the pace of market growth compared to North America.
The Asia-Pacific region is emerging as the fastest-growing market, accounting for nearly 20% of the global share. Rapid urbanization, rising disposable incomes, and increasing health awareness in countries like China, Japan, and South Korea are driving demand for low-calorie sweeteners. Japan has been at the forefront of allulose adoption, given its long-standing focus on health and wellness. Additionally, the growing popularity of functional and plant-based foods in the region further accelerates market expansion. The Asia-Pacific market is expected to witness a robust CAGR during the forecast period, supported by investments in food technology and favorable government policies promoting healthier dietary choices.
Latin America and the Middle East & Africa collectively account for approximately 20% of the global market. These regions are in the nascent stages of adoption but are gaining momentum due to growing investments in the food and beverage sector and rising health awareness. Brazil and South Africa are notable contributors, with increasing demand for low-calorie products among urban populations.
Key Player Analysis:
- Anderson Advanced Ingredients.
- Apura Ingredients
- Bonumose LLC
- CJ Cheil Jedang
- Heartland Food Products Group
- Icon Foods,
- Ingredion Inc
- Matsutani Chemical Industry Co. Ltd.
- Samyang Corporation
- Tate & Lyle
Competitive Analysis:
The allulose market is highly competitive, with key players focusing on innovation, strategic partnerships, and production efficiency to gain a competitive edge. Leading companies such as Tate & Lyle PLC, Ingredion Incorporated, and Matsutani Chemical Industry Co., Ltd. dominate the market through their extensive product portfolios and advanced production technologies. These players leverage their strong distribution networks and regulatory approvals to expand their presence in established and emerging markets. Smaller and regional manufacturers are also entering the market, driven by the increasing demand for natural, low-calorie sweeteners. Many companies are investing in research and development to improve production processes and reduce costs, making allulose more accessible to diverse industries. Collaborations with food and beverage companies to develop customized formulations further enhance market competition. This dynamic landscape underscores the importance of innovation, scalability, and regulatory compliance as critical factors for sustained success in the allulose market.
Recent Developments:
- In March 2024, Scotty's Everyday launched AllSweet, a natural sweetener derived from a blend of allulose and monk fruit. Positioned as a zero-calorie, low-glycemic index alternative, AllSweet caters to health-conscious consumers seeking to reduce sugar intake while preserving the taste and texture of their favorite foods and beverages. The product’s launch aligns with the growing demand for natural, low-calorie sweeteners amid increasing awareness of the health risks associated with high sugar consumption.
- In November 2023, Tate & Lyle Sugars expanded its product portfolio by introducing a sucralose-based sweetener with reduced calorie content. This innovation meets consumer demands for easy use, good solubility, and sugar-like texture, offering a practical alternative for health-focused consumers.
- In October 2023, researchers at the University of California, in collaboration with the Mars Advanced Research Institute, announced the development of a more efficient production method for allulose. This innovation is expected to reduce production costs, potentially increasing the accessibility and affordability of allulose in the global market.
- In July 2023, Apura Ingredients launched a suite of ten novel products, including low- and no-calorie sweeteners and denatured flavor modulators tailored for the beverage industry. This expansion highlights the growing application of innovative sweeteners across diverse market segments.
- In April 2023, Daesang, a leading food ingredient company, introduced a low-calorie sweetener based on allulose. This rare sugar, naturally occurring in trace amounts in some fruits, has 90% fewer calories than regular sugar and does not raise blood sugar levels. Daesang’s product is targeted at food and beverage manufacturers seeking healthier sweetening options for diabetic-friendly and reduced-calorie formulations.
Market Concentration & Characteristics:
The allulose market is moderately concentrated, with a mix of prominent global players and emerging regional manufacturers contributing to its growth. Leading companies such as Tate & Lyle PLC, Ingredion Incorporated, and Matsutani Chemical Industry Co., Ltd. dominate the market due to their advanced production capabilities, extensive distribution networks, and regulatory approvals in key regions. These players leverage technological innovations to enhance production efficiency and reduce costs, strengthening their competitive position. The market is characterized by rapid innovation, driven by increasing demand for low-calorie, natural sweeteners. Smaller manufacturers are entering the market, focusing on niche applications and cost-effective production methods to challenge established players. Collaboration between manufacturers and food and beverage companies is common, aiming to develop customized formulations. Despite regulatory and cost barriers in some regions, the market exhibits significant growth potential, fueled by rising consumer awareness and expanding applications across diverse industries.
Report Coverage:
The research report offers an in-depth analysis based on product type and application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising consumer preference for low-calorie and natural sweeteners is expected to drive substantial demand for allulose.
- Innovations in production methods will lower costs and enhance scalability, broadening market accessibility.
- Increasing regulatory approvals in emerging markets will create new growth opportunities for manufacturers.
- Growing health awareness due to obesity and diabetes will push food and beverage companies to adopt allulose in healthier product formulations.
- Online retail channels are anticipated to boost the availability and visibility of allulose-based products globally.
- Rapid urbanization and rising health consciousness in Asia-Pacific and Latin America will accelerate adoption in these regions.
- Expanding use in functional foods and beverages, including sports nutrition and gut health products, will diversify market applications.
- Market competition will intensify as new players focus on niche applications and cost-efficient production processes.
- Emphasis on eco-friendly production practices will align the market with global sustainability trends.
- Strategic collaborations between ingredient manufacturers and food companies will accelerate the development of innovative applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the allulose market?
What is driving the growth of the allulose market?
Which region dominates the allulose market?
What are the challenges faced by the allulose market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Allulose Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Allulose Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 257.75 million → 2032: USD 521.17 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Allulose Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Allulose Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Allulose Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Allulose Market Drivers
- 3.3 Allulose Market Restraints & Challenges
- 3.4 Allulose Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Allulose Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Allulose Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Allulose category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Allulose Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Allulose Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Allulose market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Allulose Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Allulose Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Allulose Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Allulose (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Allulose Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Allulose Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Allulose Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Allulose Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Allulose Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Allulose Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Allulose Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Allulose Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Allulose Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
