
Market Overview
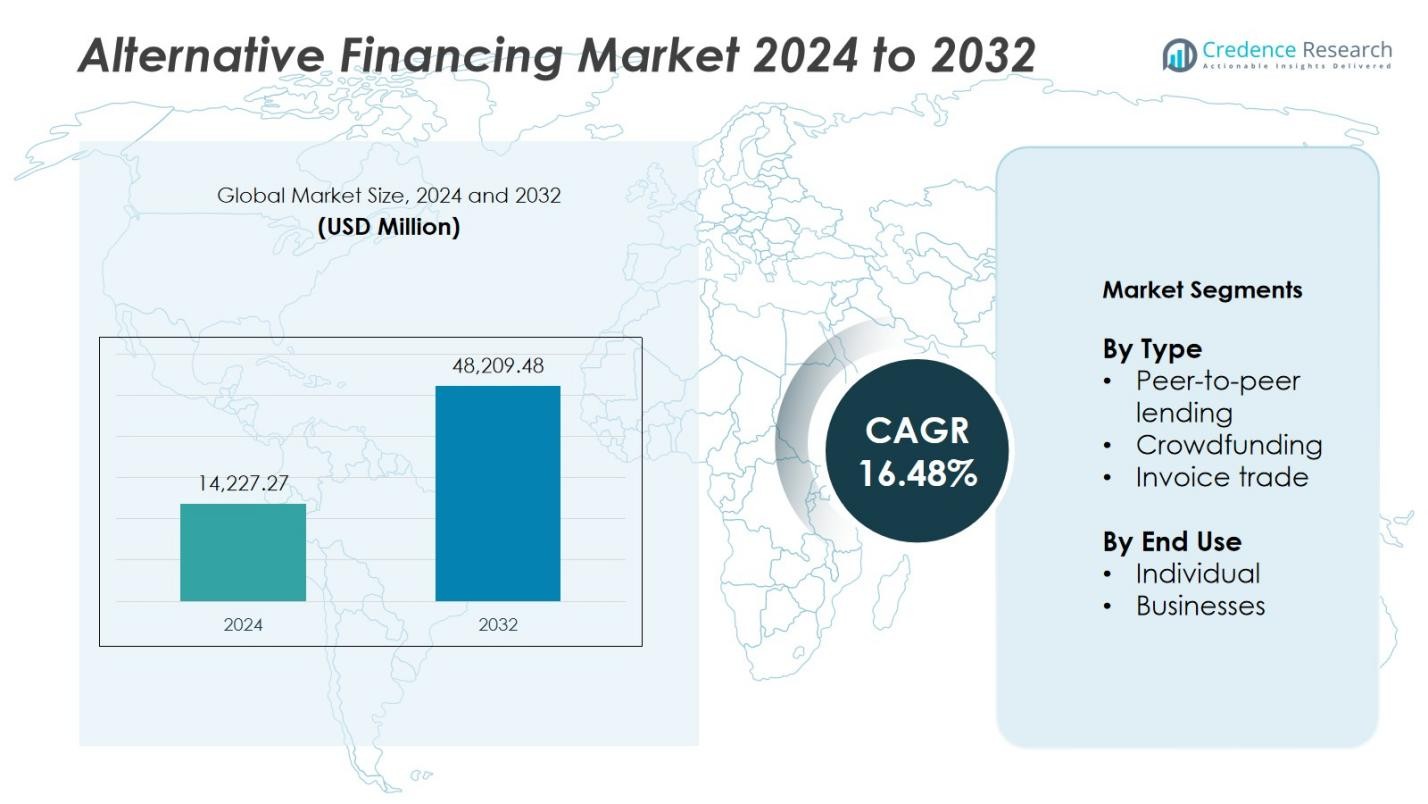
The Global Alternative Financing Market size was valued at USD 14,227.27 million in 2024 and is anticipated to reach USD 48,209.48 million by 2032, growing at a CAGR of 16.48% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Alpha Lipoic Acid Market Size 2024 | USD 14,227.27 Million |
| Alpha Lipoic Acid Market, CAGR | 16.48% |
| Alpha Lipoic Acid Market Size 2032 | USD 48,209.48 Million |
The Alternative Financing Market is led by major players including Kiva Microfunds, Funding Circle, Prosper Funding LLC, LendingCrowd, Credoc, GoFundMe, LendingClub, Borrowers First, Finastra, and Kickstarter. These companies focus on expanding digital lending, crowdfunding, and peer-to-peer platforms through advanced technologies like AI, blockchain, and data analytics. Strategic collaborations with banks and fintech startups strengthen their market presence and improve accessibility for SMEs and individuals. North America emerged as the leading region with a 37% market share in 2024, supported by strong fintech infrastructure, regulatory support, and high digital adoption, followed by Europe and the rapidly growing Asia-Pacific region.
Market Insights
- The Alternative Financing Market was valued at USD 14,227.27 million in 2024 and is projected to reach USD 48,209.48 million by 2032, growing at a CAGR of 16.48%.
- Rising demand for quick, flexible, and low-cost funding options among individuals and SMEs drives market growth globally.
- Technological advancements in AI, blockchain, and digital lending platforms enhance transparency and efficiency, boosting adoption across sectors.
- The market is moderately competitive, with players like Kiva Microfunds, Funding Circle, and LendingClub focusing on platform innovation and partnerships.
- North America leads with a 37% share, followed by Europe at 28% and Asia-Pacific at 24%; peer-to-peer lending holds the dominant 52% segment share due to its accessibility and low-cost financing benefits.
Market Segmentation Analysis:
By Type
The alternative financing market is segmented into peer-to-peer (P2P) lending, crowdfunding, and invoice trade. Peer-to-peer lending dominated the market in 2024 with a share of 52%, driven by increasing consumer preference for fast, accessible, and lower-cost borrowing options. P2P platforms enable direct connections between lenders and borrowers, reducing reliance on traditional banks. Crowdfunding follows with a rising share due to startup funding demand, while invoice trade continues to expand among small enterprises seeking improved cash flow and liquidity management.
For instance, Oculus VR raised $2.4 million on Kickstarter in 2012, ultimately leading to its acquisition by Meta in 2014.
By End Use
Based on end use, the market is categorized into individuals and businesses. The business segment accounted for the largest share of 61% in 2024, supported by the growing need for alternative funding sources among startups and small to medium-sized enterprises (SMEs). Businesses increasingly turn to digital financing platforms for working capital, expansion, and invoice factoring. The individual segment, holding the remaining share, is growing steadily due to rising adoption of P2P lending and crowdfunding for personal loans, education, and creative ventures.
For instance, Biz2Credit, a technology-driven lending platform, supports small businesses by providing tailored funding options through its Biz2X platform, which is also adopted by major financial institutions like HSBC.
Key Growth Drivers
Rising Demand for Accessible Financing Solutions
The growing limitations of traditional banking systems have fueled the need for faster and more flexible financing options. Alternative financing platforms, such as P2P lending and crowdfunding, offer quick loan approvals and minimal documentation, attracting individuals and SMEs. Increasing internet penetration and smartphone use further enable easy access to these platforms. This accessibility, coupled with lower interest rates and transparent digital interfaces, drives adoption among underserved borrowers, making alternative financing a preferred choice for diverse funding needs worldwide.
For instance, Prosper, a US-based P2P lending platform, approves around 70% of loan applications, offering borrowers flexible loan terms and faster approvals compared to traditional banks.
Growth of Small and Medium Enterprises (SMEs)
SMEs increasingly rely on alternative financing to overcome limited credit availability from conventional lenders. Digital lending and invoice trading platforms help businesses access capital efficiently, supporting operational liquidity and growth initiatives. Governments in emerging markets are promoting SME financing through fintech collaborations and digital transformation policies. As a result, alternative financing platforms are expanding their customer base, offering customized products for small enterprises. This trend continues to strengthen market growth by addressing the unmet credit demands of the global SME sector.
For instance, India's invoice discounting platforms like KredX have helped numerous SMEs access working capital without waiting for client payments, improving cash flow management.
Technological Integration and Fintech Expansion
Technological innovation is a core growth driver in the alternative financing market. The integration of artificial intelligence, blockchain, and advanced data analytics has streamlined credit assessment, risk management, and fraud detection. Fintech companies leverage these technologies to enhance transparency and build investor trust. Additionally, digital identity verification and automated lending systems improve efficiency and security. This technology-driven evolution not only reduces operational costs but also promotes financial inclusion, attracting both investors and borrowers to alternative financing platforms.
Key Trends and Opportunities
Emergence of Hybrid Financing Models
A growing trend in the alternative financing market is the rise of hybrid models combining P2P lending, crowdfunding, and traditional finance. These models offer diversified funding sources and greater risk control for investors. Businesses increasingly adopt hybrid systems to access both equity and debt capital through digital platforms. The combination of fintech and institutional partnerships creates new opportunities for cross-sector investments, expanding reach in developing regions and enhancing the market’s overall resilience and scalability.
For instance, the collaboration between ICICI Bank and fintech Paytm in India led to the launch of "Paytm-ICICI Bank Postpaid," which combines digital credit with traditional banking services to provide flexible financing options.
Expansion Across Emerging Economies
Emerging economies represent a major growth opportunity for alternative financing platforms. Countries in Asia-Pacific, Latin America, and Africa are witnessing rapid fintech adoption due to digital infrastructure improvements and supportive regulations. Rising smartphone penetration and government-backed financial inclusion programs encourage individuals and SMEs to explore nontraditional funding options. The growing awareness of digital credit solutions and cross-border investment platforms is expected to further accelerate market expansion in these high-potential regions.
For instance, in Latin America, Brazil's instant payment system, Pix, saw 77% consumer adoption in 2023, helping fuel widespread digital payment use.
Key Challenges
Regulatory Uncertainty and Compliance Risks
Varying regulations across regions remain a major challenge for the alternative financing market. The absence of uniform policies for P2P lending, crowdfunding, and digital credit platforms increases compliance complexities. Frequent changes in government rules regarding consumer protection, interest caps, and data privacy can restrict operations and delay platform approvals. Companies must continuously adapt to evolving standards, increasing legal costs and operational risks. These regulatory inconsistencies hinder market expansion, particularly for new entrants seeking cross-border growth opportunities.
Data Security and Fraud Concerns
With increased digitization, cybersecurity and fraud prevention have become critical concerns. Alternative financing platforms handle vast amounts of sensitive financial data, making them potential targets for cyberattacks and identity theft. Insufficient encryption or weak verification systems can lead to financial losses and damage consumer trust. Maintaining data integrity through robust cybersecurity frameworks and AI-based monitoring systems is essential. Failure to ensure data protection can undermine investor confidence and limit the market’s long-term credibility and growth potential.
Regional Analysis
North America
North America dominated the alternative financing market in 2024 with a market share of 37%, driven by strong fintech adoption and favorable regulatory frameworks. The U.S. leads the region due to high digital penetration, growing SME financing needs, and investor confidence in peer-to-peer lending and crowdfunding platforms. Canada also shows notable growth, supported by supportive policies and rising venture capital participation. The region’s mature financial ecosystem, coupled with advanced data analytics and blockchain integration, enhances transparency and trust, positioning North America as a key global hub for alternative lending innovation.
Europe
Europe held a market share of 28% in the alternative financing market in 2024, supported by widespread fintech integration and transparent regulatory policies. The United Kingdom remains the largest market, driven by high adoption of P2P lending and crowdfunding platforms. Germany and France also contribute significantly through SME-focused credit platforms and government-backed digital finance initiatives. Strong investor participation and growing awareness of nonbank financing models support the region’s expansion. The emphasis on sustainable and ethical investment models further enhances Europe’s competitiveness in the global alternative financing landscape.
Asia-Pacific
Asia-Pacific accounted for a market share of 24% in 2024 and is expected to register the fastest growth through 2032. Rapid digitalization, increasing smartphone use, and the rise of fintech startups in China, India, and Southeast Asia fuel this momentum. Governments across the region are promoting financial inclusion and encouraging digital lending frameworks. SMEs are increasingly leveraging crowdfunding and invoice trading for operational liquidity. Expanding online payment ecosystems, along with strong investor interest in emerging markets, strengthens Asia-Pacific’s position as a high-growth region in the alternative financing industry.
Latin America
Latin America captured a market share of 6% in 2024, driven by rising fintech innovation and unmet credit demand among small businesses. Brazil and Mexico are key markets benefiting from improving regulatory clarity and increasing consumer trust in digital platforms. Alternative financing models are filling the credit gap left by traditional banking institutions, particularly in the SME segment. Mobile-based lending and micro-investment solutions are gaining popularity, supporting regional financial inclusion. As digital adoption accelerates, Latin America presents growing opportunities for cross-border collaborations and new platform expansions.
Middle East & Africa
The Middle East and Africa region held a market share of 5% in 2024, with growth driven by fintech startups and government-led digital transformation programs. The United Arab Emirates and South Africa are emerging as regional leaders due to supportive fintech ecosystems and investment-friendly regulations. Alternative financing platforms are addressing gaps in SME and consumer lending, especially where traditional credit systems remain underdeveloped. Increasing mobile connectivity, coupled with expanding blockchain-based financial solutions, is expected to accelerate market growth across the region over the forecast period.
Market Segmentations:
By Type
- Peer-to-peer lending
- Crowdfunding
- Invoice trade
By End Use
- Individual
- Businesses
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Alternative Financing Market features key players such as Kiva Microfunds, Funding Circle, Prosper Funding LLC, LendingCrowd, Credoc, GoFundMe, LendingClub, Borrowers First, Finastra, and Kickstarter. These companies compete through technological innovation, product diversification, and platform scalability to capture a growing global customer base. Leading firms focus on improving digital lending platforms using AI and blockchain to enhance transparency, credit scoring, and fraud detection. Strategic partnerships with financial institutions and fintech startups are expanding market presence and accessibility across regions. Moreover, increased investor participation and government support for digital finance are intensifying competition. Players are also emphasizing sustainable and inclusive financing models to attract both retail and institutional investors, reinforcing their leadership in a rapidly evolving financial ecosystem.
Key Player Analysis
- Borrowers First
- Credoc
- Finastra
- Funding Circle
- GoFundMe
- Kickstarter
- Kiva Microfunds
- LendingClub
- LendingCrowd
- Prosper Funding LLC
Recent Developments
- In July 2025, Länsförsäkringar Bank agreed to acquire Stockholm-based savings marketplace SAVR, adding more than 100,000 digital investors to its Nordic footprint.
- In June 2025, Ant International announced plans to seek stablecoin-issuer licenses in Hong Kong and Singapore once each jurisdiction’s new framework is enacted, signaling a regional digital asset expansion.
- In October 2024, Upstart introduced the T-Prime lending program for borrowers with credit scores above 720, partnering with 14 lenders to deliver AI-driven approvals at competitive prime rates.
- In March 2024, Viva.com rolled out its Merchant Advance revenue-based lending package in Belgium, Germany, the Netherlands, and Spain, using acquiring data to prescore for automated repayments.
Report Coverage
The research report offers an in-depth analysis based on Type, End Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The alternative financing market will expand rapidly with rising global fintech adoption.
- Peer-to-peer lending platforms will continue to dominate due to ease of access and lower borrowing costs.
- Crowdfunding will gain traction as startups and creative ventures seek flexible capital sources.
- Integration of AI, blockchain, and big data will enhance risk assessment and transparency.
- SMEs will remain the primary beneficiaries of alternative financing solutions worldwide
- Emerging markets in Asia-Pacific and Latin America will drive the next growth phase.
- Regulatory frameworks will become more standardized to support cross-border digital lending.
- Institutional investors will increase participation, boosting liquidity across lending platforms.
- Sustainable and ethical financing models will attract environmentally conscious investors.
- Partnerships between fintech firms and traditional banks will strengthen hybrid financing ecosystems.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Alternative Financing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Alternative Financing Market projected to grow between 2025 and 2032?
Which Alternative Financing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Alternative Financing Market?
Who are the leading companies in the Alternative Financing Market?
Which region commanded the largest share of the Alternative Financing Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 14,227.27 million → 2032: USD 48,209.48 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Alternative Financing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Alternative Financing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Alternative Financing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Alternative Financing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Alternative Financing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Alternative Financing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Alternative Financing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Alternative Financing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 14,227.27 million → 2032: USD 48,209.48 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Alternative Financing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Alternative Financing Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Alternative Financing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Alternative Financing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

