
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
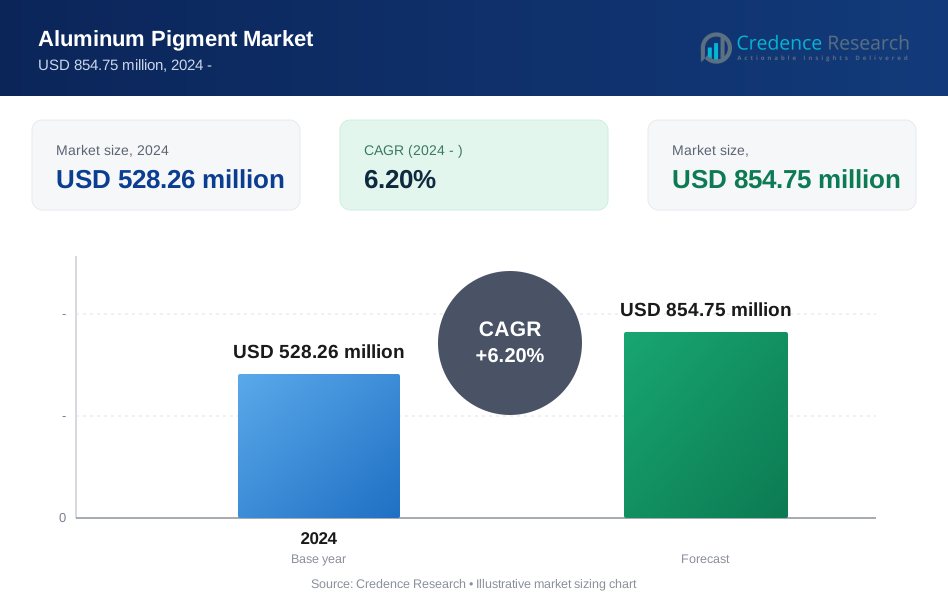
| Aluminium pigment market Size 2024 | USD 528.26 million |
| Aluminium pigment market, CAGR | 6.2% |
| Aluminium pigment market Size 2032 | USD 854.75 million |
Market Overview:
The global aluminium pigment market is projected to grow from USD 528.26 million in 2024 to USD 854.75 million by 2032, representing a compound annual growth rate (CAGR) of 6.2% during the forecast period. Aluminum pigments are known for their metallic finish and are widely used in various industries for coatings, printing inks, and plastics. The increased demand for visually appealing, durable finishes in automotive and construction sectors is expected to drive significant market growth. With rising applications across multiple industries, the market is positioned for steady expansion in the coming years.
Key drivers propelling the aluminum pigment market include a growing demand for specialty pigments in the automotive and construction industries, where metallic pigments offer enhanced aesthetic and protective properties. The automotive industry, in particular, utilizes aluminum pigments to create metallic effects that improve vehicle aesthetics and durability. Additionally, innovations in eco-friendly pigments and waterborne coatings are enhancing the market appeal of aluminum pigments, aligning with increased regulatory focus on environmental sustainability. The demand for UV-cured coatings is also increasing, as these coatings improve pigment durability in various outdoor applications.
Regionally, the Asia-Pacific region holds a dominant share, largely due to rapid industrialization, urbanization, and automotive production in countries such as China, India, and Japan. North America is also a significant market, driven by high demand in the automotive and construction industries, as well as advancements in pigment technology. Europe follows closely, with a strong focus on eco-friendly and sustainable pigment solutions, particularly in Germany and France. Meanwhile, the Middle East and Africa are expected to see gradual growth, propelled by construction developments and an increasing demand for premium coatings. This regional diversification underscores the global appeal and varied applications of aluminum pigments across industries and markets.
Market Drivers:
Growing Demand in the Automotive Industry:
The automotive industry is a primary driver of the aluminum pigment market due to the increasing demand for metallic finishes that enhance vehicle aesthetics and durability. Aluminum pigments, known for their reflective properties, create visually appealing metallic effects widely used in vehicle coatings. For instance, a 2023 report by the International Organization of Motor Vehicle Manufacturers (OICA) noted that over 85% of newly manufactured vehicles in North America featured metallic coatings. The trend toward using durable, high-quality finishes is expected to drive consistent demand for aluminum pigments in the automotive sector.
Rising Use in Construction and Architectural Applications:
Aluminum pigments are increasingly utilized in construction and architectural applications, where they provide both aesthetic and protective qualities to building exteriors and interiors. These pigments enhance coatings by improving UV resistance and adding metallic effects that are popular in modern architectural designs. According to a survey by the American Institute of Architects (AIA) in 2022, approximately 40% of new commercial constructions in the U.S. included metallic finishes, driven by the desire for both functional and aesthetic benefits. This shift is promoting the use of aluminum pigments in various architectural applications.
Increased Demand for Eco-Friendly and Waterborne Coatings:
As environmental regulations tighten, the demand for eco-friendly and waterborne coatings is growing, encouraging the development of aluminum pigments compatible with these coatings. Waterborne coatings, known for their lower volatile organic compound (VOC) emissions, are gaining popularity in sectors prioritizing sustainability. For example, BASF’s 2022 sustainability report highlighted a 25% increase in sales of eco-friendly pigment solutions, including aluminum-based pigments, in response to rising regulatory standards. Government incentives for environmentally friendly construction materials further boost this trend.
Advancements in Printing Inks and Packaging:
The packaging and printing industries also drive demand for aluminum pigments, especially with the increasing use of metallic inks for premium product packaging. Aluminum pigments are popular in packaging for consumer goods, where they enhance shelf appeal and product visibility. A 2023 industry report by the Flexible Packaging Association indicated that over 50% of packaging designs incorporate metallic inks, driven by consumer preference for eye-catching visuals. This demand for high-quality printing inks in packaging is expected to stimulate further growth in the aluminum pigment market.
Market Trends:
Increasing Preference for Metallic Aesthetic Finishes:
A notable trend in the aluminum pigment market is the growing preference for metallic finishes across consumer goods, automotive, and construction sectors. Metallic aesthetics add visual appeal and perceived quality, especially in consumer-facing industries. For instance, a 2023 survey by the European Coatings Association revealed that over 60% of packaging companies now use metallic pigments to enhance product shelf appeal, especially for premium products. This trend aligns with consumer expectations for visually attractive products, reinforcing the demand for aluminum pigments in various industries.
Adoption of High-Performance and Heat-Resistant Pigments:
Another trend is the development of high-performance aluminum pigments that offer superior heat resistance, making them suitable for applications in harsh environments. This is particularly beneficial for industries like automotive and construction, where materials are often exposed to extreme conditions. For instance, Merck KGaA introduced a line of heat-resistant aluminum pigments, which increased the lifespan of coatings in industrial applications by 20%. Such innovations are meeting the demand for durable, high-performance pigments that maintain their aesthetic and functional properties over time.
Shift Toward Environmentally Friendly Manufacturing Processes:
In line with sustainability goals, aluminum pigment manufacturers are increasingly adopting eco-friendly production methods. This includes reducing VOC emissions and using sustainable raw materials. The U.S. Environmental Protection Agency (EPA) reported in 2023 that about 30% of pigment manufacturers had adopted waterborne and low-VOC technologies in response to regulatory pressures and corporate sustainability goals. Companies like BASF have made significant investments in “green” production facilities, indicating a market-wide shift toward sustainable manufacturing.
Advancements in Nanotechnology for Improved Pigment Performance:
Nanotechnology advancements are also shaping the aluminum pigment market by enhancing pigment quality, adhesion, and reflective properties at a smaller particle size. Nanoparticle aluminum pigments provide improved dispersion, which creates a smoother metallic finish and enhances the coating’s durability. For example, the National Nanotechnology Initiative in the U.S. reported that, by 2023, approximately 40% of new aluminum pigments incorporated nano-level advancements, resulting in improved application performance. The use of nanotechnology is expected to continue growing as companies seek to develop innovative pigments with enhanced optical and mechanical properties.
Market Challenges Analysis:
High Production Costs and Raw Material Price Volatility:
The aluminum pigment market faces high production costs and volatility in raw material prices, which impact manufacturers’ profitability and pricing strategies. Aluminum, a primary raw material, is subject to price fluctuations due to market supply and demand dynamics, trade policies, and energy costs associated with its extraction. According to the U.S. Geological Survey, global aluminum prices saw an increase of nearly 15% in 2023, driven by supply chain disruptions and rising energy costs. Such fluctuations create financial uncertainties for manufacturers, limiting consistent pricing strategies and affecting market stability.
Stringent Environmental Regulations:
Stringent environmental regulations on VOC emissions and hazardous waste management create compliance challenges for aluminum pigment manufacturers. Many traditional pigment manufacturing processes involve solvents and chemicals that release volatile organic compounds (VOCs), posing environmental and health risks. The U.S. Environmental Protection Agency (EPA) has mandated that pigment producers comply with low-VOC standards, while the European Union’s REACH regulations impose strict guidelines on chemical usage. Meeting these regulatory requirements often requires investment in greener technologies, which can be costly and technically challenging, especially for smaller manufacturers.
Limited Adoption in Emerging Markets:
Despite growth potential, adoption of aluminum pigments remains limited in emerging markets, where traditional pigments are often preferred for their lower cost. Lack of awareness and insufficient access to advanced coating technologies further hinder market expansion in these regions. For example, a report from the Asia-Pacific Economic Cooperation (APEC) in 2022 highlighted that while aluminum pigments have potential in emerging markets, high initial costs and limited technical expertise continue to restrict growth.
Technical Challenges with Specialized Applications:
Aluminum pigments can present challenges in specialized applications, such as in certain high-temperature or corrosive environments where pigment stability is critical. Additionally, technical difficulties in achieving consistent dispersion in coatings and achieving uniform metallic effects limit their use in applications requiring high-performance finishes. This technical complexity can lead to inconsistent results, impacting product reliability and ultimately limiting adoption in industries like aerospace and high-end manufacturing.
Market Segmentation Analysis:
By Type
The aluminum pigment market is segmented by type into leafing and non-leafing pigments. Leafing pigments, which float on the surface of coatings to create highly reflective effects, are widely used in decorative and automotive applications. Non-leafing pigments, which disperse within coatings, are favored in industrial applications for durability and corrosion resistance. The choice between leafing and non-leafing types often depends on the desired appearance and performance in different environments, such as automotive finishes or industrial coatings.
By Technology
By technology, the market includes powder, paste, and vacuum metallized pigment (VMP) technologies. Powder pigments are valued for their stability and ease of handling in industrial applications, while paste forms are more common in automotive coatings for their ability to produce high gloss finishes. Vacuum metallized pigments represent an advanced technology offering ultra-thin, highly reflective aluminum layers, primarily used in premium coatings and packaging for a luxurious metallic effect. Innovations in these technologies focus on enhancing pigment dispersion and reducing VOC emissions.
By End User
End users in the aluminum pigment market span automotive, construction, packaging, and printing industries. The automotive sector leads in demand, utilizing aluminum pigments to achieve durable metallic finishes. The construction industry is also a significant user, employing aluminum pigments for architectural coatings that add both visual appeal and protection to surfaces. Additionally, the packaging and printing sectors utilize these pigments to create premium, attention-grabbing finishes, particularly for high-end consumer goods. This diverse end-user base underscores aluminum pigments’ versatility across industries requiring both functional and aesthetic attributes.
Segmentations:
By Type
- Leafing
- Non-Leafing
By Form
- Paste
- Pellet
- Powder
- Flakes
By Application
- Paints and Coatings
- Printing Inks
- Plastics
- Others
Regional
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a leading share in the global aluminum pigment market, accounting for around 35% of the total market share. This dominance is driven by high demand in the automotive, packaging, and construction industries. The United States is the primary contributor, supported by advanced technological capabilities and significant investments in the development of eco-friendly pigments. The automotive industry, in particular, relies on aluminum pigments for high-quality, durable metallic finishes. Additionally, increasing regulatory emphasis on low-VOC coatings has encouraged the adoption of environmentally friendly aluminum pigments across various industries. Canada also contributes significantly, particularly within the construction sector, where aluminum pigments are valued for their weather-resistant qualities in architectural coatings.
Asia-Pacific
The Asia-Pacific region is expected to demonstrate the fastest growth, holding approximately 30% of the market share. This rapid expansion is driven by increased industrialization, urbanization, and automotive production in countries like China, India, and Japan. China, as the largest market in the region, is a major consumer of aluminum pigments, particularly in the automotive and construction sectors, which are experiencing strong growth due to urban development and infrastructure projects. India’s burgeoning packaging industry is also creating demand for aluminum pigments, especially in food and consumer goods packaging that benefits from the aesthetic appeal of metallic finishes. Japan remains a significant market, particularly in high-tech industries and automotive manufacturing, where high-performance pigments are essential for premium finishes.
Europe
Europe accounts for around 25% of the aluminum pigment market share, with robust demand from the automotive and construction industries. Countries like Germany, France, and the United Kingdom lead in aluminum pigment consumption, supported by strong automotive manufacturing and architectural advancements. European Union regulations on sustainability and low-emission coatings further drive demand for eco-friendly aluminum pigments. Germany, a leading automotive producer, utilizes aluminum pigments extensively for car finishes. Additionally, the construction industry in Europe incorporates these pigments to enhance both aesthetic and functional attributes in coatings, such as corrosion resistance and UV protection.
Latin America, Middle East, and Africa
Latin America, the Middle East, and Africa collectively hold the remaining 10% of the global aluminum pigment market. Latin America, led by Brazil and Mexico, is experiencing gradual growth due to the expanding automotive and construction sectors. Demand in the Middle East is driven by the construction boom, especially in the Gulf Cooperation Council (GCC) countries, where aluminum pigments are used in architectural coatings for high-rise buildings and infrastructure projects. Africa’s market is smaller but is expected to grow steadily with increasing urbanization and industrialization. Although market penetration is lower due to economic constraints, ongoing investments in infrastructure and construction are expected to stimulate gradual growth in aluminum pigment demand across these regions.
Key Player Analysis:
- BASF SE
- Altana AG
- Silberline Manufacturing Co., Inc.
- Sun Chemical Corporation
- Carl Schlenk AG
- Metaflake Ltd.
- Toyal America, Inc.
- Zhangqiu Metallic Pigment Co., Ltd.
- Carlfors Bruk AB
- Asahi Kasei Corporation
Competitive Analysis:
The aluminum pigment market is competitive, with major players focusing on innovation, product quality, and environmentally friendly offerings to maintain their market positions. Companies like BASF SE, Altana AG, and Silberline Manufacturing Co., Inc. lead the market with advanced technologies in metallic pigments for various applications, including automotive, construction, and packaging. These leaders invest significantly in R&D to develop low-VOC and eco-friendly products, catering to the rising regulatory demand for sustainable pigments. Sun Chemical Corporation and Carl Schlenk AG also hold strong positions by expanding their product portfolios to include high-performance aluminum pigments optimized for UV-cured and waterborne coatings. Strategic partnerships and acquisitions are common as companies seek to expand their geographic reach and technological capabilities. Regional players like Zhangqiu Metallic Pigment Co., Ltd. in Asia focus on cost-effective solutions, intensifying competition in price-sensitive markets. This competitive landscape is shaped by continuous innovation to meet evolving industry standards.
Recent Developments:
- ALTANA AG expanded its effect pigments division through the acquisition of Silberline in 2024. This strategic move strengthens ALTANA’s ECKART division and enhances its presence in North America and Asia, enabling the company to better serve customers in automotive coatings, printing inks, and plastics sectors with advanced aluminum pigment solutions.
- Sun Chemical (a subsidiary of DIC Corporation) completed the acquisition of BASF’s global pigments business, BASF Colors & Effects, in 2023. This acquisition expanded Sun Chemical’s pigment offerings and enhanced its position in specialty applications, including coatings, electronics, and plastics. The integration has allowed Sun Chemical to broaden its pigment portfolio, particularly in effect and functional pigments.
- Carl Schlenk AG recently launched a new range of high-performance aluminum pigments aimed at increasing durability in challenging environments, particularly in industrial and automotive applications. This line focuses on providing enhanced heat resistance and improved environmental compliance, aligning with current market demands for high-quality, sustainable pigments.
- Silberline Manufacturing Co., Inc. introduced a series of environmentally friendly aluminum pigments in 2023. These pigments are designed for use in low-VOC and waterborne applications, meeting regulatory demands for reduced environmental impact while maintaining high-performance qualities in coatings and packaging solutions.
Market Concentration & Characteristics:
The aluminum pigment market is moderately concentrated, with a few leading players, such as BASF SE, ALTANA AG, Sun Chemical, and Silberline, commanding significant shares due to their advanced technological capabilities and extensive product offerings. This concentration is characterized by continuous innovation, focusing on sustainable and environmentally friendly products in response to regulatory requirements and rising consumer demand for eco-friendly solutions. High entry barriers exist due to the substantial capital investment needed in R&D and compliance with strict environmental regulations. Major players are also expanding their global footprint through strategic acquisitions and partnerships to enhance their technological capabilities and geographical reach. Additionally, as consumer preferences shift towards premium metallic finishes in automotive, packaging, and construction, the demand for specialized aluminum pigments continues to grow, reinforcing the market's focus on high-quality, sustainable, and performance-enhancing solutions.
Report Coverage:
The research report offers an in-depth analysis based on Type, Form, Application, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The aluminum pigment market is expected to grow steadily, driven by rising demand for high-quality metallic finishes in automotive and consumer goods sectors.
- Increased environmental regulations will encourage the development and adoption of low-VOC and eco-friendly aluminum pigments.
- Demand for waterborne and sustainable coatings will drive innovation in aluminum pigments, focusing on improved dispersion and durability in green formulations.
- The growing popularity of UV-cured coatings, especially in automotive and industrial applications, will further enhance the market as aluminum pigments offer enhanced durability and aesthetic appeal.
- Advancements in nanotechnology are likely to produce finer, more stable aluminum pigments that enhance both performance and application versatility.
- The Asia-Pacific region is anticipated to see the fastest growth, spurred by industrial expansion, urbanization, and increased automotive production.
- Strategic acquisitions by key players will likely consolidate market share and expand technological capabilities, particularly in North America and Asia.
- The shift towards digital and flexible packaging will increase demand for metallic inks and pigments to provide eye-catching designs and premium effects.
- Innovations in heat-resistant pigments will cater to high-performance applications in sectors like aerospace and automotive.
- Increased focus on 3D printing technologies could open new applications for aluminum pigments, especially in industrial manufacturing and decorative materials.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Aluminum Pigment Market?
What factors are driving the growth of the Aluminum Pigment Market?
What are some challenges faced by the Aluminum Pigment Market?
Who are the major players in the Aluminum Pigment Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Aluminum Pigment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Aluminum Pigment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 528.26 million → forecast year: USD 854.75 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Aluminum Pigment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Aluminum Pigment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Aluminum Pigment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Aluminum Pigment Market Drivers
- 3.3 Aluminum Pigment Market Restraints & Challenges
- 3.4 Aluminum Pigment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Aluminum Pigment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Aluminum Pigment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Aluminum Pigment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Aluminum Pigment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Aluminum Pigment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Aluminum Pigment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Aluminum Pigment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Aluminum Pigment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Aluminum Pigment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Aluminum Pigment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Aluminum Pigment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Aluminum Pigment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Aluminum Pigment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Aluminum Pigment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Aluminum Pigment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Aluminum Pigment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Aluminum Pigment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Aluminum Pigment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Aluminum Pigment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
