
Market Overview:
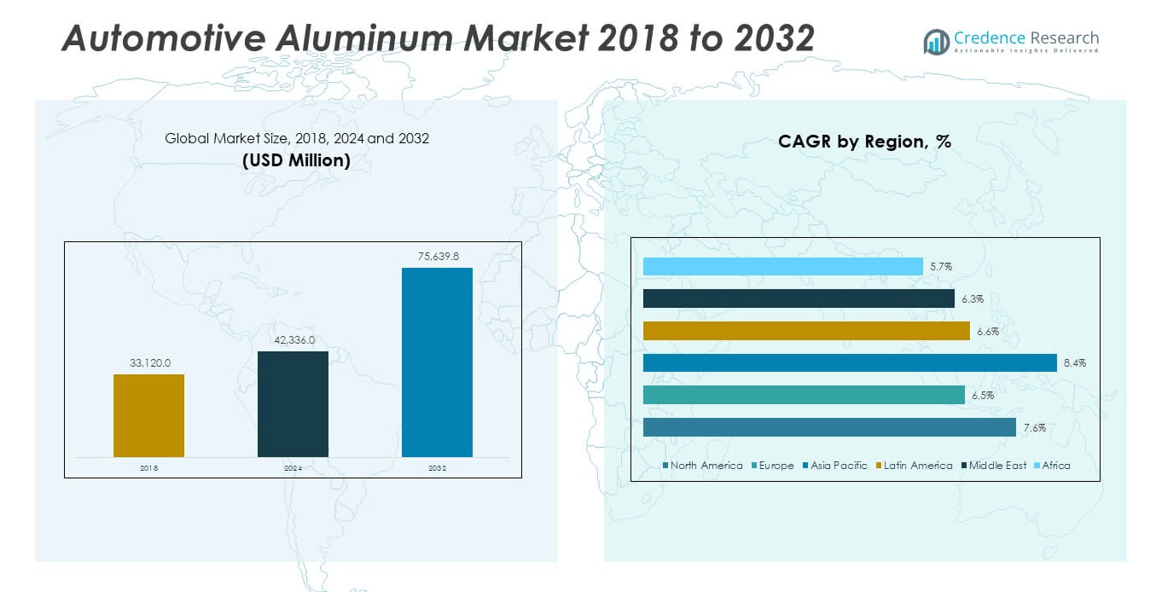
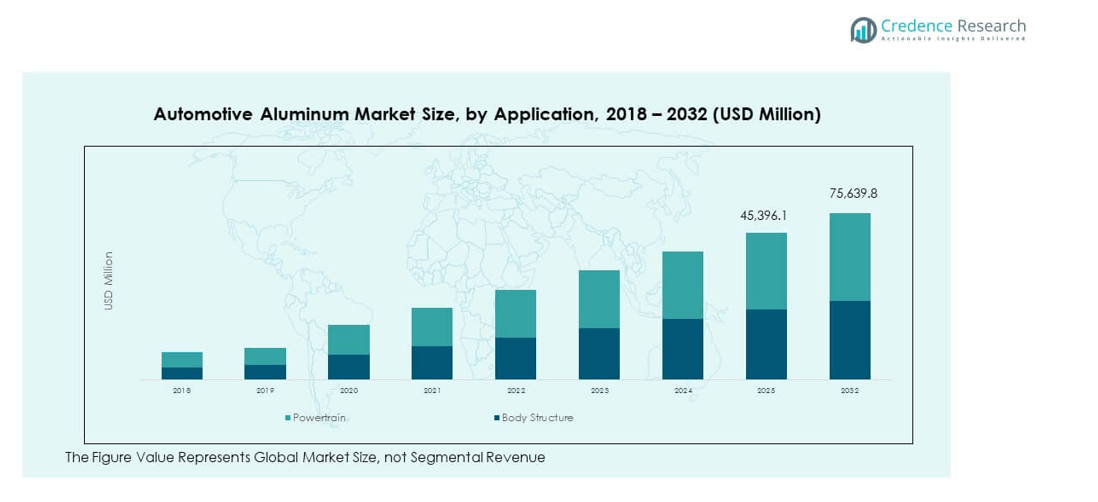
The Global Automotive Aluminum Market size was valued at USD 33,120.0 million in 2018 to USD 42,336.0 million in 2024 and is anticipated to reach USD 75,639.8 million by 2032, at a CAGR of 7.60% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Aluminum Market Size 2024 | USD 42,336.0 million |
| Automotive Aluminum Market, CAGR | 7.60% |
| Automotive Aluminum Marke Size 2032 | USD 75,639.8 million |
The market grows with increasing demand for lightweight materials that enhance fuel efficiency and support emission reduction targets in the automotive sector. Rising adoption of electric vehicles, where lightweight structures extend driving range and battery efficiency, also drives aluminum usage. Automakers increasingly rely on aluminum for body panels, structural components, and engine parts to balance performance with sustainability. Advancements in recycling technologies further strengthen the market by ensuring supply chain resilience and lowering production costs, aligning with global environmental regulations and consumer preference for greener mobility.
Geographically, North America and Europe lead the market due to stringent fuel efficiency norms, established automotive industries, and high adoption of electric vehicles. Asia Pacific emerges as the fastest-growing region, driven by expanding automotive production in China, India, and Japan along with rising consumer demand for efficient vehicles. Latin America and the Middle East & Africa present steady growth opportunities, supported by gradual industrial development and investments in sustainable transport solutions. This regional distribution reflects the global shift toward lightweighting strategies and the strong role of aluminum in shaping the future of automotive manufacturing.
Market Insights:
- The Global Automotive Aluminum Market was valued at USD 33,120.0 million in 2018, reached USD 42,336.0 million in 2024, and is projected to hit USD 75,639.8 million by 2032, growing at a CAGR of 7.60%.
- Strong demand for lightweight vehicles drives market growth, as aluminum helps improve fuel efficiency, performance, and compliance with emission norms.
- Rising adoption of electric vehicles accelerates aluminum use in battery casings, structural frameworks, and lightweight components to extend driving range.
- High production costs and raw material price volatility restrain widespread adoption, impacting profit margins and supply chain stability.
- Technical challenges in forming, welding, and recycling aluminum limit its seamless integration into large-scale automotive manufacturing.
- North America and Europe lead due to strict fuel efficiency regulations and advanced automotive industries, while Asia Pacific emerges as the fastest-growing region.
- Emerging markets such as India, Southeast Asia, and Latin America present strong growth potential with rising vehicle production and supportive sustainability policies.
Market Drivers:
Rising Demand for Lightweight Vehicles to Enhance Fuel Efficiency and Performance:
The Global Automotive Aluminum Market benefits significantly from the rising demand for lightweight materials to improve vehicle efficiency and performance. Automakers face strict emission norms and fuel economy standards, pushing them to substitute traditional steel with aluminum in key components. It supports reduced vehicle weight, leading to higher mileage, faster acceleration, and better handling. Aluminum is increasingly applied in body panels, chassis, and engine parts to balance safety and performance. Governments across regions mandate lower emissions, compelling automakers to adopt lighter materials. Electric vehicle manufacturers integrate aluminum to extend driving range and optimize battery performance. Consumer preference for efficient and sustainable vehicles further accelerates adoption. The rising focus on energy efficiency strengthens aluminum’s role as a strategic material for automotive innovation.
- For instance, Ford reduced the weight of its F-150 pickup by nearly 700 pounds in its 2015 redesign by replacing steel with a military-grade aluminum alloy, increasing fuel efficiency by about 20%.
Expanding Electric Vehicle Production and Adoption Worldwide:
The rapid expansion of electric vehicle (EV) production remains a powerful driver for the Global Automotive Aluminum Market. EV manufacturers prioritize lightweight design to counter heavy battery packs and improve driving range. It creates strong demand for aluminum in structural frameworks, battery casings, and thermal management systems. Growing investments in EV manufacturing capacity across major economies further amplify this requirement. Incentives from governments, including tax benefits and subsidies, support EV adoption, expanding the scope of aluminum integration. Automakers focus on modular and scalable EV platforms, which use aluminum for flexibility and efficiency. Rising consumer interest in sustainable mobility strengthens demand for lightweight materials. The acceleration of EV adoption underpins long-term market expansion for automotive aluminum.
- For instance, Tesla’s Model S uses an all-aluminum body and chassis, helping deliver an EPA-estimated range of up to 405 miles per charge, compared to steel-based EV architectures that result in shorter ranges.
Stringent Emission Regulations and Environmental Policies:
Government policies targeting carbon neutrality and emission reductions provide significant momentum to the Global Automotive Aluminum Market. Regulators in North America, Europe, and Asia enforce strict fleet-wide fuel economy and emission standards. It compels automakers to replace heavy materials with aluminum in high-volume vehicle production. Policies promoting recycling and sustainability further encourage aluminum adoption due to its recyclability and lower carbon footprint. Automakers respond to consumer and regulatory expectations by designing vehicles that align with green standards. Global initiatives on climate change and decarbonization strengthen the case for aluminum in vehicles. The versatility of aluminum in reducing energy consumption during manufacturing also supports compliance efforts. Environmental policies remain a primary growth catalyst for the market.
Advancements in Automotive Manufacturing Technologies:
Technological innovations in vehicle manufacturing provide a strong boost to the Global Automotive Aluminum Market. Automakers integrate advanced casting, extrusion, and rolling technologies to expand aluminum applications across diverse components. It enables cost-effective production of complex vehicle structures with enhanced durability and precision. The use of high-strength aluminum alloys supports the shift toward lighter yet safer vehicles. Modern manufacturing methods reduce waste and improve material efficiency, aligning with sustainability targets. Digital manufacturing and automation further streamline aluminum processing, making it viable for large-scale adoption. Collaborations between automakers and material suppliers drive innovations in alloy development. Continuous advancements ensure that aluminum remains competitive compared to other lightweight alternatives. The combination of efficiency and innovation strengthens market expansion globally.
Market Trends:
Increasing Integration of Recycled Aluminum in Automotive Applications:
Sustainability pressures and cost-efficiency drive a notable trend in the Global Automotive Aluminum Market: increased adoption of recycled aluminum. Automakers leverage the recyclability of aluminum to reduce production costs while meeting environmental regulations. It supports a circular economy approach that minimizes dependence on primary raw materials. Recycled aluminum requires less energy during processing, aligning with carbon reduction targets. Car manufacturers now integrate secondary aluminum into vehicle frames, panels, and structural parts without compromising performance. Strong growth in aluminum recycling infrastructure enhances this trend globally. Strategic collaborations between recyclers and automakers improve closed-loop supply chains. The widespread emphasis on recycling is reshaping material sourcing strategies across the automotive sector.
- For instance, Audi’s “Aluminium Closed Loop” project at its Neckarsulm plant enabled reuse of 150,000 metric tons of aluminum scrap in 2022, reducing CO₂ emissions by about 165,000 tons.
Adoption of Multi-Material Vehicle Design Strategies:
Automakers are embracing multi-material design strategies as a key trend in the Global Automotive Aluminum Market. Vehicles now combine aluminum with advanced composites, magnesium, and high-strength steels to achieve optimal weight reduction and durability. It supports automakers in designing structures that balance cost, performance, and safety. Multi-material architectures enable tailored use of aluminum in areas requiring high stiffness and crash protection. Advancements in joining technologies make these combinations increasingly feasible in mass production. Automakers pursue modular platforms that integrate aluminum seamlessly with other materials. The flexibility of aluminum supports hybrid design frameworks that meet consumer and regulatory demands. This trend highlights the industry’s shift toward diversified material strategies.
- For instance, BMW’s 7 Series incorporates a mix of aluminum, carbon-fiber-reinforced plastic, and ultra-high-strength steel in its body-in-white, reducing overall body weight by up to 130 kg while maintaining crash safety standards.
Growing Focus on Advanced Alloys and High-Performance Applications:
Another significant trend involves the development and adoption of advanced aluminum alloys in the Global Automotive Aluminum Market. Automakers demand materials with higher strength-to-weight ratios to replace heavier metals in performance-critical areas. It has led to rising R&D investments in heat-treatable alloys and corrosion-resistant grades. These alloys enable manufacturers to extend aluminum use to engines, suspension systems, and crash-resistant structures. Improved formability and weldability expand opportunities for application in large vehicle segments. Aerospace-inspired alloys are increasingly adapted for automotive use to meet rising performance requirements. The versatility of these alloys enhances overall vehicle design and durability. The trend underscores aluminum’s evolving role as a high-performance automotive material.
Expanding Role of Aluminum in Autonomous and Connected Vehicles:
The integration of aluminum into autonomous and connected vehicle platforms emerges as an innovative trend in the Global Automotive Aluminum Market. It plays a crucial role in housing sensors, cameras, and radar systems without adding excessive weight. Lightweight structures support the additional power requirements of connected vehicle technologies. Aluminum’s thermal management properties improve battery efficiency and electronics cooling. Automakers explore its use in smart chassis systems that integrate autonomous driving features. Aluminum also supports design flexibility for advanced body-in-white architectures. The increasing adoption of connected technologies accelerates demand for materials that combine strength, durability, and lightweight characteristics. This trend positions aluminum as a strategic enabler of next-generation vehicle technologies.
Market Challenges Analysis:
High Production Costs and Price Volatility of Raw Materials:
The Global Automotive Aluminum Market faces notable challenges related to high production costs and raw material price volatility. Aluminum production requires significant energy inputs, making it vulnerable to fluctuations in energy prices. It creates cost uncertainties for automakers who rely heavily on aluminum integration. Global supply chain disruptions, including geopolitical tensions and trade restrictions, exacerbate these cost challenges. Automakers also face competition for aluminum from industries such as aerospace and construction. Fluctuating raw material prices often result in inconsistent profit margins for automotive manufacturers. Limited access to high-quality bauxite and alumina further complicates supply chains. These factors collectively pose barriers to widespread cost-effective adoption of aluminum.
Technical Barriers and Compatibility Issues in Manufacturing Processes:
Automakers also encounter technical challenges that restrict the smooth adoption of aluminum in the Global Automotive Aluminum Market. Forming and joining aluminum with other materials often requires specialized technologies, increasing manufacturing complexity. It raises production costs and demands significant investment in new equipment and training. Welding and bonding challenges sometimes limit aluminum’s application in critical vehicle parts. Automakers must balance aluminum’s lightweight benefits with potential trade-offs in structural strength. Recycling aluminum without losing quality also presents technological hurdles. Inconsistent standards across regions add to production inefficiencies. These challenges slow down full-scale integration of aluminum in vehicle manufacturing despite its potential advantages.
Market Opportunities:
Rising Demand for Electric Mobility and Sustainable Vehicle Solutions:
The Global Automotive Aluminum Market holds significant opportunities from the rising global demand for electric mobility. EV manufacturers increasingly adopt aluminum to offset battery weight and extend driving range. It enables designs that enhance performance, energy efficiency, and safety in electric and hybrid vehicles. Growing investments in sustainable transport infrastructure further strengthen this opportunity. Automakers aiming to align with sustainability targets view aluminum as a critical enabler. Consumer preference for eco-friendly vehicles supports this momentum across developed and emerging markets. Expansion of EV charging networks complements this opportunity by boosting EV adoption. The integration of aluminum in EV platforms positions the market for robust growth.
Technological Advancements and Emerging Markets Expansion:
Technological innovation and emerging market growth create strong opportunities in the Global Automotive Aluminum Market. Advanced alloys, extrusion methods, and digital manufacturing solutions improve cost efficiency and design flexibility. It allows automakers to expand aluminum applications across vehicle types, from luxury sedans to commercial trucks. Emerging markets such as India, Southeast Asia, and Latin America present growth prospects driven by rising automotive demand. Governments in these regions promote sustainable practices, encouraging automakers to adopt lightweight materials. Partnerships with local suppliers further enhance supply chain strength and regional competitiveness. The rising focus on autonomous and connected vehicles creates new avenues for aluminum applications. This combination of innovation and regional expansion strengthens long-term opportunities for the market.
Market Segmentation Analysis:
By Aluminum Type
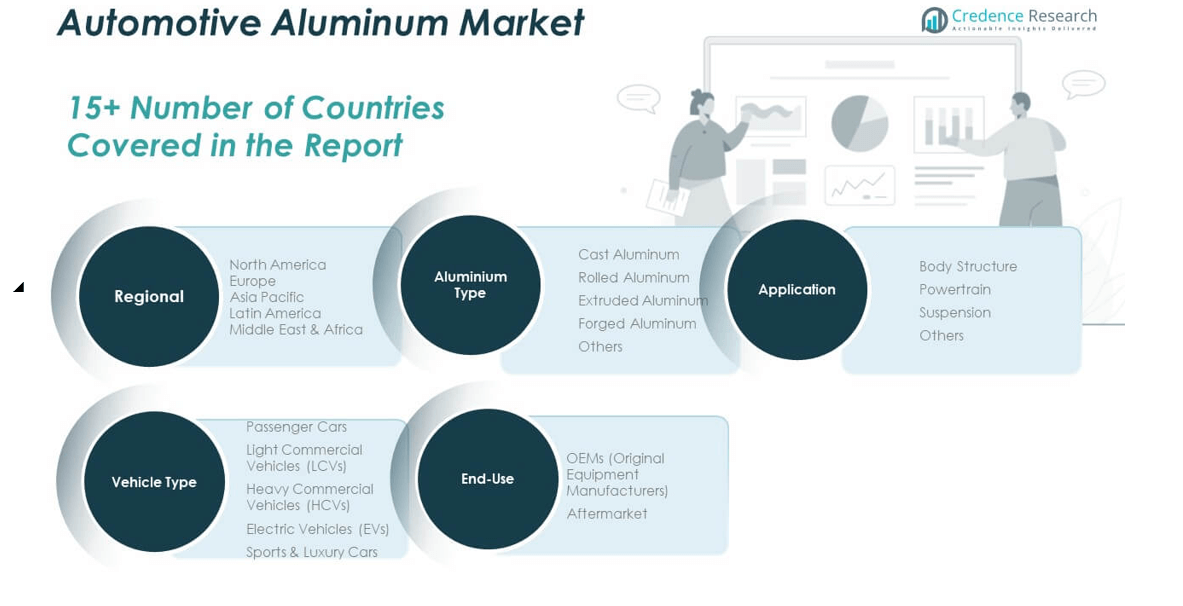
The Global Automotive Aluminum Market shows strong adoption across cast, rolled, extruded, forged, and other specialty types. Cast aluminum dominates with extensive use in engine blocks, cylinder heads, and transmission cases. Rolled aluminum gains momentum in body panels and closures, driven by the need for lightweight designs. Extruded aluminum supports applications such as roof rails, crash management systems, and bumpers. Forged aluminum remains vital for high-stress parts like wheels and suspension arms, while other alloys serve niche applications requiring specific strength-to-weight ratios.
- For instance, Jaguar Land Rover applied 3,500 tons of rolled aluminum per week for body panels in its XE sedan production, achieving a 75 kg reduction compared to a conventional steel body.
By Application
Body structure represents the leading segment, supported by demand for lightweight panels, doors, hoods, and crash-resistant frames. Powertrain applications sustain significant consumption for housings, pistons, and transmission components. Suspension systems benefit from aluminum integration to reduce weight and enhance durability. Other applications, including heat exchangers, interior trims, and thermal management components, contribute steadily to overall demand.
- For instance, General Motors reduced the weight of the Chevrolet Malibu’s suspension system by 26 pounds through the use of aluminum control arms and cross-members, improving handling and efficiency.
By End-Use
OEMs account for the largest share, driven by automakers focusing on lightweighting strategies to meet emission standards and improve efficiency. Aftermarket players also hold relevance, supported by demand for replacement parts, custom modifications, and performance-oriented upgrades.
By Vehicle Type
Passenger cars lead the segment, reflecting rising consumer demand for fuel-efficient and premium vehicles. Light commercial vehicles integrate aluminum to optimize payload and reduce operating costs. Heavy commercial vehicles rely on aluminum for structural strength and compliance with fuel regulations. Electric vehicles represent the fastest-growing category, with usage in battery enclosures, chassis, and lightweight body structures. Sports and luxury cars emphasize aluminum for performance, aesthetics, and safety benefits.
Segmentation:
By Aluminum Type
- Cast Aluminum
- Rolled Aluminum
- Extruded Aluminum
- Forged Aluminum
- Others
By Application
- Body Structure
- Powertrain
- Suspension
- Others
By End-Use
- OEMs (Original Equipment Manufacturers)
- Aftermarket
By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles (LCVs)
- Heavy Commercial Vehicles (HCVs)
- Electric Vehicles (EVs)
- Sports & Luxury Cars
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Global Automotive Aluminum Market size was valued at USD 9,406.1 million in 2018 to USD 11,836.9 million in 2024 and is anticipated to reach USD 21,105.6 million by 2032, at a CAGR of 7.6% during the forecast period. North America holds around 23% market share, supported by strong demand from OEMs and premium vehicle manufacturers. The region benefits from regulatory pressure to reduce vehicle emissions, which accelerates adoption of lightweight aluminum. The U.S. leads production and consumption, with high penetration of aluminum in body structures, wheels, and powertrain components. Canada emphasizes lightweight materials in electric vehicle manufacturing, while Mexico’s automotive hubs contribute through cost-efficient manufacturing. It continues to invest in R&D for advanced alloys and recycling facilities. Market players focus on forging partnerships with automakers to ensure supply security. Strong infrastructure and advanced manufacturing capabilities keep North America a competitive hub.
Europe
The Europe Global Automotive Aluminum Market size was valued at USD 6,425.3 million in 2018 to USD 7,780.2 million in 2024 and is anticipated to reach USD 12,840.0 million by 2032, at a CAGR of 6.5% during the forecast period. Europe commands about 15% market share, shaped by stringent CO₂ emission norms and sustainability targets. Germany dominates with robust automotive production and high adoption of aluminum in body structures and powertrain systems. France, Italy, and the UK reinforce demand with luxury and sports car manufacturing. It benefits from recycling initiatives that align with EU environmental policies. The region shows strong preference for rolled and extruded aluminum in lightweight body panels. Automakers expand usage in hybrid and electric models to optimize efficiency. European suppliers also drive innovation in forging technologies. The market outlook remains steady, driven by sustainability policies and advanced engineering expertise.
Asia Pacific
The Asia Pacific Global Automotive Aluminum Market size was valued at USD 13,049.3 million in 2018 to USD 17,139.5 million in 2024 and is anticipated to reach USD 32,557.7 million by 2032, at a CAGR of 8.4% during the forecast period. Asia Pacific dominates with nearly 41% market share, led by China, Japan, India, and South Korea. China spearheads demand due to its vast EV production and strong government incentives for lightweighting. Japan and South Korea focus on advanced alloys and high-performance vehicle applications. India shows rapid growth with expanding automotive manufacturing hubs and increasing penetration of aluminum in passenger cars and LCVs. The region witnesses substantial adoption of aluminum in EV battery enclosures, body panels, and chassis components. It benefits from cost-competitive production and strong supply chain ecosystems. Rising investments in recycling infrastructure enhance sustainability. Asia Pacific remains the key driver of global volume expansion.
Latin America
The Latin America Global Automotive Aluminum Market size was valued at USD 2,179.3 million in 2018 to USD 2,759.9 million in 2024 and is anticipated to reach USD 4,589.8 million by 2032, at a CAGR of 6.6% during the forecast period. Latin America accounts for about 7% market share, supported by Brazil, Mexico, and Argentina. Brazil leads with steady growth in automotive manufacturing and aluminum integration in commercial vehicles. Mexico complements the region through exports and growing aftermarket demand. It emphasizes lightweight solutions to balance fuel economy with rising vehicle production. Demand for rolled and extruded aluminum rises with expanding passenger car sales. OEM collaborations with global suppliers strengthen supply availability. The aftermarket also contributes significantly with replacement and customized parts. The region maintains gradual adoption, supported by industrial expansion and government-backed sustainability programs.
Middle East
The Middle East Global Automotive Aluminum Market size was valued at USD 1,357.9 million in 2018 to USD 1,633.9 million in 2024 and is anticipated to reach USD 2,655.4 million by 2032, at a CAGR of 6.3% during the forecast period. The Middle East holds around 4% market share, influenced by regional investments in EV adoption and luxury cars. GCC countries, particularly the UAE and Saudi Arabia, drive consumption with growing automotive assembly and premium vehicle imports. It benefits from aluminum integration in high-performance vehicles suited to regional preferences. Turkey shows strong industrial capacity for automotive component production. The region emphasizes aluminum use in electric and hybrid vehicles to align with sustainability goals. Market growth is supported by infrastructure expansion and government-led diversification programs. Regional suppliers invest in processing facilities to strengthen competitiveness. The Middle East maintains stable growth supported by luxury and performance-driven demand.
Africa
The Africa Global Automotive Aluminum Market size was valued at USD 702.1 million in 2018 to USD 1,185.6 million in 2024 and is anticipated to reach USD 1,891.2 million by 2032, at a CAGR of 5.7% during the forecast period. Africa represents about 3% market share, with South Africa leading due to its established automotive base. Egypt and Morocco emerge as secondary hubs with growing manufacturing capabilities. It continues to expand demand through lightweight adoption in passenger and commercial vehicles. Aluminum penetration remains lower compared to developed regions but shows rising growth with expanding vehicle ownership. The aftermarket supports a significant portion of demand for replacement and customization. Local governments promote investment in auto manufacturing clusters, strengthening adoption. Rising focus on sustainability gradually encourages aluminum recycling initiatives. Africa reflects steady but moderate growth in the global market landscape.
Key Player Analysis:
- Constellium N. V.
- AMG Advanced Metallurgical Group
- Martinrea Honsel Germany GmbH
- UACJ Corporation
- Norsk Hydro ASA
- Bodine Aluminum, Inc.
- Aleris
- Federal-Mogul Holding Corporation
- Consolidated Metco, Inc.
- Dana Holding Corporation
- Farinia Group; Dynacast
- Aluminium Bahrain (Alba)
- Granges Innovative Aluminum Engineering
- Kaiser Aluminum
- Gibbs Die Casting Corporation
- Endurance Technologies Limited
- Ryobi Ltd.
Competitive Analysis:
The Global Automotive Aluminum Market is characterized by strong competition among leading producers such as Constellium N.V., Norsk Hydro ASA, UACJ Corporation, and Kaiser Aluminum. It is defined by continuous investments in product innovation, lightweight alloys, and recycling technologies to meet sustainability targets and regulatory standards. Companies expand their presence through mergers, acquisitions, and strategic partnerships with automakers to strengthen supply security. It emphasizes value-added aluminum solutions for body structures, powertrain, and electric vehicle components. Global players compete on cost efficiency, production capacity, and technological advancements. Regional manufacturers focus on niche applications and localized supply networks. The market demonstrates a balanced mix of established leaders and emerging players, with innovation in alloys and advanced processing methods driving competitive differentiation.
Recent Developments:
- In July 2025, Constellium N.V. announced the completion of its FlexCAR project, a pioneering modular vehicle architecture utilizing HSA6™ high-strength aluminum alloys with recycled content. This was developed in collaboration with ARENA2036, Mercedes-Benz, Siemens, and Bosch, aiming to support both battery electric and hydrogen fuel cell vehicles. Notably, the project included deployment of digital fingerprint technology for tracking aluminum component performance in Mercedes-Benz test vehicles, marking a significant step in digital innovation and sustainability for automotive structures.
- In April 2025, AMG Advanced Metallurgical Group approved a $15 million capital investment to establish an aluminothermic production facility in New Castle, Pennsylvania, to manufacture chrome metal-a critical material for various industrial alloys. The facility is expected to be operational in the first quarter of 2026 and signals AMG's commitment to strengthening the domestic supply of essential metals for advanced manufacturing, including those supporting automotive aluminum alloys in the United States.
Market Concentration & Characteristics:
The Global Automotive Aluminum Market exhibits moderate to high concentration, with a few multinational corporations holding significant market share. It is driven by technological advancements, strategic mergers, and expansion of recycling capabilities. Entry barriers remain high due to capital-intensive production and strict regulatory standards. Regional players contribute to competitive diversity by serving local demand and aftermarket needs. The market shows strong alignment with sustainability trends, emphasizing low-carbon and recyclable aluminum products. Competitive intensity is reinforced by growing EV production, where suppliers compete to deliver advanced alloys and lightweight solutions at scale.
Report Coverage:
The research report offers an in-depth analysis based on Aluminum Type, Application, End-Use, and Vehicle Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption of aluminum-intensive designs will accelerate as automakers pursue lightweighting strategies to meet emission and efficiency targets.
- Growing electric vehicle production will expand demand for aluminum in battery enclosures, chassis structures, and crash-resistant body frames.
- Advances in alloy technology will enhance strength-to-weight ratios, enabling broader use in structural and high-performance applications.
- Recycling innovations will strengthen circular economy practices, improving cost efficiency and aligning with sustainability goals.
- Increasing regulatory focus on fuel economy and carbon reduction will drive higher integration of aluminum in passenger and commercial vehicles.
- OEM collaborations with material suppliers will intensify to secure stable supply chains and ensure consistent quality standards.
- Expansion of aftermarket customization will support aluminum demand in replacement parts and performance enhancements.
- Integration with smart manufacturing and Industry 4.0 practices will boost production efficiency and reduce waste in aluminum processing.
- Global investments in automotive R&D will prioritize lightweight materials, positioning aluminum as a core enabler of innovation.
- Regional shifts in vehicle production, particularly in Asia-Pacific, will reshape supply dynamics and influence long-term growth strategies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Lightweighting for Fuel Efficiency and Emission Compliance
Automakers are increasingly substituting steel with aluminum in vehicle structures to reduce weight, which directly improves fuel efficiency and helps meet stringent global emission regulations. This trend is reinforced by government mandates and consumer demand for more efficient vehicles.
Expansion of Electric Vehicle Production
The rapid growth of electric vehicle manufacturing is driving demand for automotive aluminum, as lightweight materials are essential to offset battery weight and extend driving range. Aluminum is widely used in EV battery enclosures, chassis, and structural components, making it a critical material for next-generation vehicles.
Stringent Environmental and Recycling Regulations
Global policies targeting carbon neutrality and circular economy practices are pushing automakers to adopt recyclable materials like aluminum. The high recyclability of aluminum supports sustainability goals, reduces production costs, and aligns with regulatory requirements for greener automotive manufacturing.
Advancements in Aluminum Alloy and Manufacturing Technologies
Innovations in high-strength aluminum alloys and advanced processing methods such as casting, extrusion, and digital manufacturing are expanding the range of automotive applications. These advancements enable the production of complex, durable, and lightweight vehicle components at scale, supporting broader market adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Automotive Aluminum Market?
What factors are driving the growth of the Automotive Aluminum Market?
How does aluminum benefit electric vehicle production?
What challenges does the Automotive Aluminum Market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 OEMs (Original Equipment Manufacturers)
- 1.2.2 Aftermarket
- 1.3 By Application
- 1.3.1 Body Structure
- 1.3.2 Powertrain
- 1.3.3 Suspension
- 1.3.4 Others
- 1.4 By Vehicle Type
- 1.4.1 Passenger Cars
- 1.4.2 Light Commercial Vehicles (LCVs)
- 1.4.3 Heavy Commercial Vehicles (HCVs)
- 1.4.4 Electric Vehicles (EVs)
- 1.4.5 Sports & Luxury Cars
- 1.5 By Aluminum Type
- 1.5.1 Cast Aluminum
- 1.5.2 Rolled Aluminum
- 1.5.3 Extruded Aluminum
- 1.5.4 Forged Aluminum
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 42,336.0 million → 2032: USD 75,639.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Aluminum Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Aluminum Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Aluminum Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Aluminum Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Aluminum Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Aluminum Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Aluminum Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Aluminum Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 42,336.0 million → 2032: USD 75,639.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Aluminum Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 OEMs (Original Equipment Manufacturers)
- 12.3.7.2 Aftermarket
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Body Structure
- 12.4.7.2 Powertrain
- 12.4.7.3 Suspension
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Passenger Cars
- 12.5.7.2 Light Commercial Vehicles (LCVs)
- 12.5.7.3 Heavy Commercial Vehicles (HCVs)
- 12.5.7.4 Electric Vehicles (EVs)
- 12.5.7.5 Sports & Luxury Cars
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Aluminum Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Cast Aluminum
- 12.6.7.2 Rolled Aluminum
- 12.6.7.3 Extruded Aluminum
- 12.6.7.4 Forged Aluminum
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Aluminum End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Automotive Aluminum Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Automotive Aluminum Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Automotive Aluminum Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Constellium N.V.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Norsk Hydro ASA
- 18.4 UACJ Corporation
- 18.5 Kaiser Aluminum
- 18.6 AMG Advanced Metallurgical Group
- 18.7 Martinrea Honsel Germany GmbH
- 18.8 Aleris
- 18.9 Bodine Aluminum, Inc.
- 18.10 Federal-Mogul Holding Corporation
- 18.11 Endurance Technologies Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

