
Market Overview
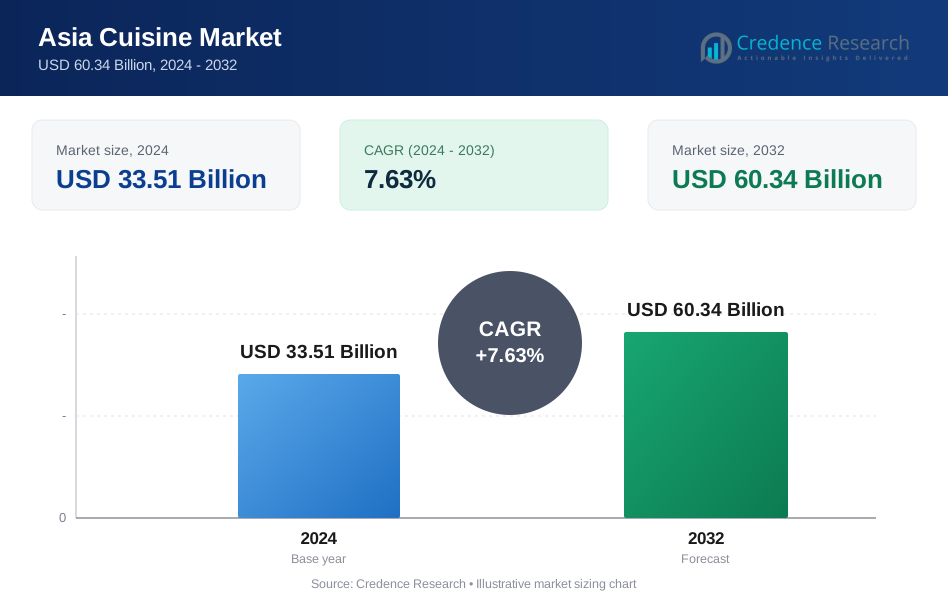
The Asia Cuisine Market size was valued at USD 33.51 Billion in 2024 and is anticipated to reach USD 60.34 Billion by 2032, at a CAGR of 7.63% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Asia Cuisine Market Size 2024 | USD 33.51 Billion |
| Asia Cuisine Market, CAGR | 7.63% |
| Asia Cuisine Market Size 2032 | USD 60.34 Billion |
Asia Cuisine Market benefits from the presence of major players such as General Mills, Mondelez International, Pei Wei Asian Diner, P.F. Chang’s India, Nestlé, Benihana, Nobu, Gyu‑Kaku and H Mart. The largest regional contributor is Asia‑Pacific, which held a market share of 46 % in 2024. Robust demand across populous countries like China, India and Japan underpins the region’s dominance. Leading companies leverage strong distribution networks, restaurant presence, and diverse product portfolios to capture demand - spanning ready‑to‑eat meals, sauces, frozen foods, and dine‑in/fusion experiences. Their broad geographical reach and deep penetration in Asia‑Pacific positions them to capitalize on rising urbanization, shifting consumer preferences, and accelerating dining-out and home‑cooking trends across the region.

Market Insights
- The Asia Cuisine Market size was valued at USD 33.51 Billion in 2024 and is projected to reach USD 60.34 Billion by 2032, growing at a CAGR of 7.63% during the forecast period.
- The market is driven by increasing consumer demand for authentic Asian food, a growing inclination toward plant-based and healthy Asian options, and the expanding reach of online food delivery platforms.
- A significant trend is the shift toward plant-based dishes, with health-conscious consumers demanding vegan and gluten-free Asian options, alongside a rise in ready-to-eat meal consumption.
- Key players such as General Mills, Mondelez, Pei Wei, and P.F. Chang’s India are driving market growth through innovation, geographic expansion, and diversified product offerings in retail and foodservice.
- The North Asia region holds the largest market share of 77%, followed by South East Asia at 28.54%, with rising demand across regions supporting global market growth.
Market Segmentation Analysis:
By Form:
The Fresh segment holds the dominant share in the Asia Cuisine Market, capturing 48.3% of the total market share in 2024. The increasing preference for fresh, natural, and minimally processed ingredients drives this dominance, particularly in home cooking and restaurants. Fresh ingredients are integral to the authenticity and flavor profile of Asian cuisines, contributing to their high demand. The Frozen sub-segment follows with a 34.2% share, driven by convenience and longer shelf life, while the Dried segment holds a 17.5% share, popular for its cost-effectiveness and long shelf life in catering and household cooking.
- For instance, Thai Union supplies fresh seafood products known for high quality and freshness, favored in premium Asian cuisine.
By Application:
The Restaurants segment leads the Asia Cuisine Market with a market share of 40.6% in 2024. This dominance is fueled by the growing demand for diverse and authentic Asian dishes in both local and international restaurants. Delivery and Takeaway follows with a 30.8% share, driven by the increasing trend of online food orders, especially among urban consumers. The Catering Services segment holds a 15.2% share, reflecting the strong demand for Asian cuisine in large-scale events, while the Household segment makes up 13.4% as consumers increasingly prepare Asian dishes at home.
- For instance, Sodexo collaborated with chefs in Singapore and Malaysia for Oma-Kaki, exclusive Asian fusion menus like those from Damian D'Silva.
By Distribution Channel:
The Online distribution channel dominates the Asia Cuisine Market with a 58.9% share in 2024, reflecting the rapid growth of e-commerce and food delivery platforms in the region. Convenience, variety, and easy access to Asian ingredients via online platforms are key drivers. The Offline segment, which includes supermarkets, local grocery stores, and specialty markets, holds a 41.1% share. While online shopping gains momentum, offline distribution remains significant due to consumer trust and the physical experience of selecting products, particularly in rural and traditional markets.
Key Growth Drivers
Increasing Consumer Demand for Authenticity
One of the major growth drivers for the Asia Cuisine Market is the rising consumer demand for authentic, traditional Asian food. As consumers seek more diverse culinary experiences, the demand for genuine and culturally significant dishes has grown. This trend is especially prominent in regions outside Asia, where people are increasingly interested in exploring Asian cuisines through restaurants and retail products. The desire for authentic ingredients, recipes, and flavors continues to fuel the market’s expansion as consumers prioritize quality and authenticity in their food choices.
- For instance, Kikkoman's naturally brewed soy sauce, produced via traditional Japanese fermentation and exported globally since post-WWII, now available in over 100 countries to enhance authentic Asian and Western dishes alike.
Growing Popularity of Asian Cuisine Globally
The increasing global popularity of Asian cuisine, including Chinese, Japanese, Thai, and Indian, is a significant driver of market growth. The rise of international food chains, restaurants, and ready-to-eat products is helping drive this trend. As consumers become more exposed to Asian food culture through media, travel, and global migration, they are incorporating these cuisines into their daily lives. The diverse flavor profiles and health-conscious options such as plant-based and gluten-free offerings in Asian cuisine further fuel the sector’s expansion worldwide.
- For instance, Nissin Foods, well-known for instant noodles, is a major global player with innovation and expanded retail availability worldwide, fueling demand in urban and semi-urban markets.
Expansion of Online Food Delivery Platforms
The rapid expansion of online food delivery platforms has provided a major boost to the Asia Cuisine Market. With the growing use of mobile apps and websites, consumers can easily access a wide range of Asian dishes at their convenience. The shift towards digital ordering and delivery has been accelerated by the COVID-19 pandemic, which led to a greater reliance on delivery services. This trend is expected to continue growing as foodservice providers and grocery retailers increasingly adopt digital channels to cater to evolving consumer preferences for convenience and variety.
Key Trends & Opportunities
Rise of Plant-Based and Health-Conscious Offerings
A prominent trend within the Asia Cuisine Market is the shift towards plant-based and health-conscious dishes. As global interest in veganism, vegetarianism, and plant-based diets grows, there is an increasing demand for Asian cuisines that align with these dietary preferences. Asian cuisines naturally offer a wide variety of plant-based options, such as tofu, tempeh, and vegetable stir-fries, which can be adapted to cater to health-conscious consumers. The rise in awareness of sustainable and healthy eating habits presents a substantial opportunity for the market to innovate and expand its offerings.
- For instance, OmniFoods launched OmniPork, a plant-based pork alternative made from non-GMO soy, pea protein, shiitake mushrooms, and rice, designed for Asian staples like luncheon meat and mince used in traditional dishes.
Growing Demand for Ready-to-Eat and Convenience Foods
The demand for ready-to-eat and convenience foods is another significant opportunity in the Asia Cuisine Market. As urban lifestyles become busier, consumers are seeking quick, convenient meal options that do not compromise on taste or quality. Ready-to-eat meals, such as Asian noodle boxes, dumplings, and rice dishes, are becoming increasingly popular. The market can capitalize on this trend by offering authentic, easy-to-prepare meals that cater to working professionals, busy families, and younger generations looking for quick yet flavorful meal solutions.
- For instance, Nestlé has expanded its range of frozen Asian meals, offering a variety of ready-to-eat dishes that cater to busy consumers.
Key Challenges
Supply Chain and Ingredient Sourcing Issues
A major challenge facing the Asia Cuisine Market is the complexity of sourcing authentic ingredients and managing supply chains. As Asian cuisines rely heavily on specific, often regionally sourced ingredients, ensuring a steady, cost-effective supply can be difficult. The global supply chain disruptions, coupled with fluctuating import/export regulations, have further compounded these challenges. Inconsistent availability of high-quality ingredients can affect product quality and authenticity, potentially limiting the growth of the market, especially for global brands that rely on specific Asian ingredients to maintain their offerings.
Cultural and Regional Variation in Taste Preferences
Another challenge is the vast cultural and regional variation in taste preferences within Asia itself. What is popular in one country or region may not resonate in another, making it difficult for companies to standardize their offerings across diverse markets. Additionally, introducing Asian cuisines into non-Asian markets often requires significant adaptation to local taste preferences. Balancing authenticity with local flavors, while maintaining brand consistency and product quality, can be a complex task, especially for businesses looking to expand globally.
Regional Analysis
North Asia
North Asia, including China, Japan, and South Korea, holds a dominant market share in the Asia Cuisine Market, accounting for 38.77% in 2024. The region benefits from strong culinary traditions, large consumer bases, and robust foodservice industries. China, in particular, has a rich history of regional cuisine, driving significant demand for both traditional and modern food offerings. Japan's growing preference for fusion dishes and South Korea’s increasing interest in international flavors further contributes to the region’s dominance. The sector is expected to continue expanding, supported by evolving consumer preferences and strong culinary export growth.
Southeast Asia
Southeast Asia, comprising countries like Thailand, Vietnam, Malaysia, and Indonesia, captures 28.54% of the Asia Cuisine Market. The region’s diverse culinary heritage and rapidly growing middle class drive the demand for both local and international cuisines. Thai, Vietnamese, and Indonesian cuisines are especially popular, with increased regional tourism and global exports. As consumer preferences lean toward healthier and more diverse food options, the market is witnessing a surge in both traditional food consumption and global cuisine adoption. The dynamic food culture and expanding foodservice networks make Southeast Asia a key market for Asia's cuisine sector.
South Asia
South Asia, including India, Pakistan, and Bangladesh, represents 21.32% of the Asia Cuisine Market. This region’s large population and diverse culinary landscape significantly contribute to its market share. Indian cuisine, known for its rich spices and variety, continues to drive domestic demand and export opportunities. In Pakistan and Bangladesh, traditional cuisines are widely consumed, with increasing urbanization and middle-class growth fueling demand for new food trends. The growing popularity of packaged and ready-to-eat meals, as well as international food chains, is expected to further boost the region's market in the coming years.
Central Asia
Central Asia holds a smaller share of 6.88% in the Asia Cuisine Market but is experiencing steady growth. Countries like Kazakhstan, Uzbekistan, and Turkmenistan have a long-standing history of nomadic food traditions, with dishes based on meat, dairy, and grains. The rise of urbanization and a more globalized food culture is increasing demand for both traditional and international cuisines. As these economies modernize and foodservice industries grow, there is an increasing shift towards diverse and fusion cuisines. This trend is expected to continue as local food preferences evolve and consumer choices expand.
Western Asia
Western Asia, which includes the Middle East and regions like Turkey, Saudi Arabia, and the UAE, represents 4.49% of the Asia Cuisine Market. Middle Eastern cuisine, with its emphasis on spices, meats, and grains, enjoys a high demand both regionally and globally. The growing expatriate populations, urbanization, and increasing tourism in countries like the UAE and Saudi Arabia contribute to a more diverse food culture. The rise in the foodservice industry, particularly in urban centers, is further propelling the consumption of international and fusion cuisines, alongside traditional Middle Eastern foods.
Market Segmentations:
By Form
- Fresh
- Frozen
- Dried
By Application
- Household
- Catering Services
- Restaurants
- Delivery and takeaway
- Others
By Distribution Channel
- Online
- Offline
By Geography
- North Asia
- Southeast Asia
- South Asia
- Central Asia
- Western Asia
Competitive Landscape
The competitive landscape of the Asia Cuisine Market is shaped by key players such as General Mills, Mondelez International, Pei Wei Asian Diner, P.F. Chang’s India, Nestlé, Benihana, Nobu, Gyu-Kaku, and H Mart. These companies dominate the market across both foodservice and retail sectors. Packaged food giants like General Mills and Mondelez leverage their global distribution networks to offer Asian-inspired products, including sauces, noodles, and ready-to-eat meals. In the restaurant industry, brands like Pei Wei, P.F. Chang’s, and Benihana drive growth through their diverse menu offerings and expanding presence in international markets. Moreover, fast-casual chains such as Gyu-Kaku and Nobu appeal to consumers seeking a fusion of authentic and innovative Asian cuisine. The competitive dynamics revolve around innovation, geographic expansion, and product diversification, aiming to cater to a growing global appetite for Asian food experiences.
Key Player Analysis
- Nobu
- Pei Wei Asian Diner
- P.F. Chang’s India
- Benihana
- H Mart
- Gyu-Kaku
- General Mills
- AppleBee's
- Mondelez International
- Nestle
Recent Developments
- In October 2025, Nobu Hospitality announced a partnership with United Real Estate Company (URC) and Dhaliliyah Company to launch its first luxury serviced‑residences and restaurant in Kuwait.
- In September 2025, P.F. Chang’s opened another new outlet in Borivali (Sky City Mall), its seventh in India, reinforcing its expansion strategy in high‑potential urban centers.
- In October 2024, Nestlé introduced two frozen‑meals brands Mings and Tapatío targeting Asian and Mexican cuisines to meet growing demand for convenient ethnic meals
Report Coverage
The research report offers an in-depth analysis based on Form, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Asia Cuisine Market will continue to grow as global interest in authentic and fusion Asian dishes increases.
- Rising consumer demand for plant-based and health-conscious Asian food options will drive market innovation.
- E-commerce and online food delivery platforms will remain key drivers for convenience-based purchasing of Asian cuisine products.
- The expansion of fast-casual and quick-service Asian restaurants will further boost market growth.
- Regional variations in taste preferences will present opportunities for personalized and localized product offerings.
- Continued urbanization and increasing disposable incomes in emerging markets will contribute to greater consumption of Asian cuisine.
- Technological advancements in food production and distribution will enhance the availability and shelf life of Asian food products.
- Increased focus on sustainability and ethical sourcing will influence product development and consumer choices.
- The growing trend of multicultural dining experiences will fuel the adoption of Asian cuisines in non-Asian regions.
- Rising health awareness will encourage demand for low-sodium, gluten-free, and other specialty Asian food products.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Consumer Demand for Authenticity
Consumers are seeking genuine and culturally significant Asian dishes, driving demand for authentic ingredients and traditional recipes both in Asia and globally. This trend is especially strong in restaurants and retail, where authenticity is a key differentiator.
Expansion of Online Food Delivery Platforms
The rapid growth of e-commerce and food delivery apps has made Asian cuisine more accessible, fueling market expansion by enabling convenient ordering and delivery of a wide range of Asian dishes and ingredients.
Rising Popularity of Plant-Based and Health-Conscious Offerings
Health-conscious consumers are increasingly opting for vegan, vegetarian, and gluten-free Asian options, prompting innovation and new product launches that cater to these dietary preferences and expanding the market’s reach.
Globalization and Culinary Tourism
Exposure to Asian cuisines through travel, media, and migration has increased global appetite for Asian food, encouraging international restaurant chains and packaged food brands to expand their Asian offerings.
Urbanization and Changing Lifestyles
Growing urban populations and busier lifestyles in Asia and worldwide are boosting demand for ready-to-eat, convenient Asian meals, supporting growth in both retail and foodservice segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Asia Cuisine Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Asia Cuisine Market projected to grow between 2025 and 2032?
Which is the leading region of the market for Asia Cuisine?
What are the key drivers for the growth of the Asia Cuisine market?
What are the primary factors fueling the growth of the Asia Cuisine Market?
Who are the leading companies in the Asia Cuisine Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Fresh
- 1.2.2 Frozen
- 1.2.3 Dried
- 1.3 By Application
- 1.3.1 Household
- 1.3.2 Catering Services
- 1.3.3 Restaurants
- 1.3.4 Delivery and Takeaway
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 33.51 Billion → 2032: USD 60.34 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Asia Cuisine Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Asia Cuisine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Asia Cuisine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Asia Cuisine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Asia Cuisine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Asia Cuisine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Asia Cuisine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Asia Cuisine Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 33.51 Billion → 2032: USD 60.34 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Asia Cuisine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fresh
- 12.3.7.2 Frozen
- 12.3.7.3 Dried
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Household
- 12.4.7.2 Catering Services
- 12.4.7.3 Restaurants
- 12.4.7.4 Delivery and Takeaway
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Asia Cuisine End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Asia Cuisine Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Asia Cuisine Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Asia Cuisine Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 General Mills
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mondelez International
- 18.4 Pei Wei Asian Diner
- 18.5 P.F. Chang’s India
- 18.6 Nestlé
- 18.7 Benihana
- 18.8 Nobu
- 18.9 Gyu-Kaku
- 18.10 H Mart
- 18.11 Applebee's
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

