
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
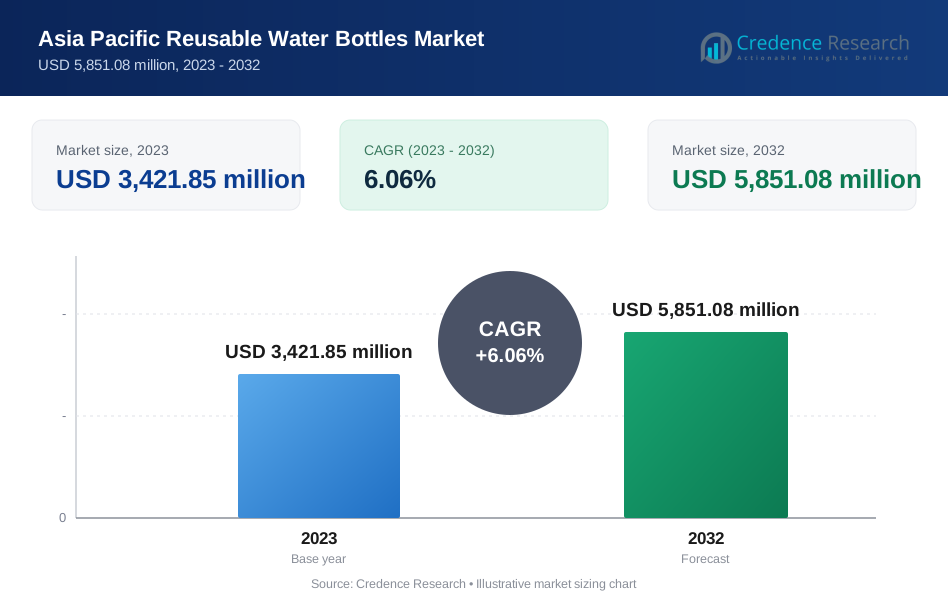
| Asia Pacific Reusable Water Bottles Market Size 2023 | USD 3,421.85 Million |
| Asia Pacific Reusable Water Bottles Market, CAGR | 6.06% |
| Asia Pacific Reusable Water Bottles Market Size 2032 | USD 5,851.08 Million |
Market Overview
The Asia Pacific Reusable Water Bottles Market is projected to grow from USD 3,421.85 million in 2023 to an estimated USD 5,851.08 million by 2032, with a compound annual growth rate (CAGR) of 6.06% from 2024 to 2032. This growth trajectory underscores the increasing consumer awareness regarding environmental sustainability and the benefits of reducing single-use plastic waste. The market's robust expansion is driven by the rising adoption of eco-friendly practices across the region, coupled with the growing health consciousness among consumers preferring reusable water bottles over disposable ones.
Market drivers for reusable water bottles in the Asia Pacific region include heightened environmental concerns and stringent governmental regulations aimed at reducing plastic waste. Consumers are becoming increasingly aware of the detrimental impacts of single-use plastics, prompting a shift towards sustainable alternatives. Additionally, the market is influenced by innovative product developments such as smart water bottles and aesthetically appealing designs that cater to the evolving preferences of tech-savvy and style-conscious consumers. Trends such as the incorporation of advanced materials for better durability and the introduction of bottles with enhanced functionality, like built-in filters and temperature retention features, are further propelling market growth.
Geographically, the Asia Pacific reusable water bottles market is segmented into key regions including China, India, Japan, South Korea, and Australia. China and India are leading the market due to their large population base and growing environmental initiatives. Japan and South Korea are also witnessing significant growth owing to high consumer disposable income and increased health awareness. Australia presents a steady market expansion driven by its strong environmental policies and consumer inclination towards sustainable living. Key players in the market include S'well, Thermos LLC, Klean Kanteen, Inc., and Hydro Flask, among others, who are continually innovating to capture the burgeoning demand in this dynamic market.
Market Drivers
Environmental Awareness and Government Regulations
A significant driver propelling the Asia Pacific reusable water bottle market is the escalating environmental awareness among consumers and stringent government regulations aimed at reducing plastic waste. In recent years, there has been a heightened global consciousness regarding the detrimental impacts of single-use plastics on ecosystems and marine life. This awareness is particularly pronounced in Asia and the and the Pacific, where large-scale environmental movements and campaigns have highlighted the urgent need for sustainable practices. Governments across the region have responded by implementing policies that restrict the use of single-use plastics and promote eco-friendly alternatives. For instance, countries like India and China have introduced bans and heavy taxes on plastic products. These regulatory measures, combined with increased public awareness, are significantly driving the demand for reusable water bottles as consumers seek to align their purchasing habits with sustainable practices.
Health consciousness and lifestyle changes
The rise in health consciousness and lifestyle changes among consumers is another critical factor driving the Asia-Pacific reusable water bottle market. Modern consumers are increasingly aware of the health risks associated with plastic bottles, such as chemical leaching, which can lead to various health issues. As a result, there is a growing preference for reusable bottles made from safe, non-toxic materials like stainless steel, glass, and BPA-free plastics. Moreover, the shift towards active and outdoor lifestyles has further fueled the demand for durable and portable water bottles. The trend toward fitness and wellness, coupled with the need to stay hydrated while on the go, has made reusable water bottles an essential accessory for many individuals. This change in consumer behavior, focusing on health and well-being, significantly contributes to the market’s growth.
Innovative Product Designs and Technological Advancements
Innovative product designs and technological advancements are crucial drivers of the reusable water bottles market in the Asia Pacific region. Manufacturers are continuously exploring new materials and technologies to enhance the functionality and appeal of reusable water bottles. For instance, the integration of smart technology, such as hydration tracking sensors and self-cleaning features, has garnered considerable attention among tech-savvy consumers. Additionally, the introduction of aesthetically pleasing designs and customizable options caters to the style preferences of a diverse consumer base. These innovations not only make reusable water bottles more attractive and user-friendly but also differentiate brands in a competitive market. The emphasis on product innovation and technological advancement is instrumental in attracting and retaining consumers, thereby driving market growth.
Economic Growth and Increasing Disposable Income
The economic growth and increasing disposable income in Asia Pacific countries are pivotal in driving the market for reusable water bottles. As economies in the region continue to expand, there is a corresponding rise in the standard of living and consumer spending power. This economic progress enables more consumers to afford higher-quality, durable reusable water bottles as opposed to cheaper, single-use alternatives. Furthermore, the urbanization trend in many Asia Pacific countries has led to a higher demand for convenient and sustainable products among city dwellers. The burgeoning middle class, with its growing purchasing power and propensity to spend on premium and eco-friendly products, plays a significant role in boosting the market. This economic dynamic, combined with an increasing focus on sustainability and quality, drives the widespread adoption of reusable water bottles across the region.
Market Trends
Increased Adoption of Eco-Friendly Materials
One prominent trend in the Asia Pacific reusable water bottles market is the increased adoption of eco-friendly materials. Consumers are gravitating towards products made from stainless steel, glass, bamboo, and BPA-free plastics, which are perceived as safer and more sustainable alternatives to conventional plastic bottles. This shift is driven by growing environmental consciousness and a desire to reduce plastic waste. Manufacturers are responding to this demand by innovating and offering a wide range of environmentally friendly options.
Integration of Smart Technology
The integration of smart technology into reusable water bottles is gaining traction in the market. Features such as hydration tracking sensors, temperature control, and self-cleaning capabilities are becoming increasingly popular. These smart bottles not only enhance user convenience but also promote better hydration habits. The use of mobile apps to monitor water intake and receive reminders to drink water is particularly appealing to tech-savvy consumers who prioritize health and wellness.
Customization and Personalization
Customization and personalization are significant trends influencing the Asia Pacific reusable water bottles market. Consumers are seeking products that reflect their individual styles and preferences. Companies are offering customizable options, allowing customers to choose colors, designs, and even engrave their names or messages on the bottles. This trend is particularly strong among younger demographics who value uniqueness and self-expression in their purchases.
Focus on Aesthetic Appeal
Aesthetic appeal has become a key factor in the purchase decision of reusable water bottles. Consumers are looking for bottles that are not only functional but also visually appealing. Stylish designs, vibrant colors, and sleek finishes are highly sought after. This trend has led to collaborations between bottle manufacturers and designers or artists, resulting in limited edition and fashion-forward collections that attract attention and drive sales.
Promotion of Hydration and Wellness Campaigns
Hydration and wellness campaigns are playing a crucial role in promoting the use of reusable water bottles. Brands are actively engaging in campaigns that emphasize the importance of staying hydrated for overall health and wellness. These initiatives are often supported by partnerships with fitness influencers, health experts, and environmental activists who advocate for sustainable and healthy living. Such campaigns effectively raise awareness and encourage the adoption of reusable bottles.
Expansion of Retail and Online Channels
The expansion of retail and online channels is facilitating the growth of the reusable water bottles market in the Asia Pacific region. E-commerce platforms, in particular, have made it easier for consumers to access a wide variety of products. Additionally, retailers are increasing their focus on sustainable products and dedicating more shelf space to reusable water bottles. The convenience of online shopping, coupled with attractive deals and discounts, is driving higher sales volumes.
Educational Initiatives and Corporate Social Responsibility
Educational initiatives and corporate social responsibility (CSR) programs are becoming more prevalent in the market. Companies are investing in educational campaigns to inform consumers about the environmental impact of single-use plastics and the benefits of using reusable water bottles. Furthermore, businesses are aligning their CSR strategies with sustainability goals, often donating a portion of their profits to environmental causes or participating in cleanup drives. These efforts not only enhance brand image but also foster a loyal customer base committed to sustainability.
Market Restraints and Challenges
High Initial Cost
One of the primary restraints in the Asia Pacific reusable water bottles market is the high initial cost associated with these products. Unlike single-use plastic bottles, reusable water bottles are often made from premium materials like stainless steel, glass, or advanced BPA-free plastics, which significantly increase their price. While the long-term benefits and savings of reusable bottles are clear, the upfront cost can be a deterrent for many consumers, especially in price-sensitive markets within the Asia Pacific region. This financial barrier can limit the market penetration of reusable water bottles among lower-income groups.
Consumer Habits and Convenience
Changing consumer habits and preferences pose a significant challenge to the adoption of reusable water bottles. Single-use plastic bottles are deeply ingrained in daily routines due to their convenience and widespread availability. The habit of using disposable bottles, combined with the perceived inconvenience of carrying and maintaining a reusable bottle, can impede market growth. Additionally, the need for regular cleaning and the weight of some reusable bottles compared to their plastic counterparts can discourage consumers from making the switch.
Limited Awareness and Education
Despite increasing environmental awareness, there remains a segment of the population in the Asia Pacific region that is either unaware of or indifferent to the benefits of reusable water bottles. Limited education on the environmental impact of single-use plastics and the health advantages of reusable alternatives hinders market growth. Effective awareness campaigns and educational initiatives are essential to bridge this knowledge gap and motivate consumers to adopt sustainable practices. Without adequate outreach, the market's potential remains constrained by a lack of informed consumer base.
Market Competition and Counterfeit Products*
The Asia Pacific reusable water bottles market faces intense competition from a plethora of brands offering a wide range of products. This competitive landscape can lead to market saturation, making it challenging for new entrants and smaller players to establish a foothold. Furthermore, the prevalence of counterfeit products poses a significant challenge. These low-quality imitations, often sold at cheaper prices, can erode consumer trust and damage the reputation of genuine brands. Addressing the issue of counterfeiting and ensuring product authenticity is crucial for maintaining market integrity and consumer confidence.
Supply Chain and Distribution Challenges
Supply chain and distribution challenges also restrain the growth of the reusable water bottles market in the Asia Pacific region. Logistics complexities, such as inadequate infrastructure, high transportation costs, and regulatory hurdles, can impede the efficient distribution of products. These challenges are particularly pronounced in rural and remote areas, where access to sustainable products is limited. Improving supply chain efficiencies and expanding distribution networks are essential to ensure wider availability and accessibility of reusable water bottles.
Market Segmentation Analysis
By Material Type
Glass reusable water bottles are becoming increasingly popular due to their non-toxic and BPA-free properties, making them a preferred choice for health-conscious consumers. However, their fragility and higher weight compared to other materials present challenges, though innovations like silicone sleeves are mitigating these issues. Stainless steel bottles, known for their durability and double-wall insulation, are ideal for active lifestyles and offer a range of stylish designs. BPA-free plastic bottles are affordable and lightweight, popular among children and for everyday use, though growing environmental concerns about plastic may impact preferences. Silicone bottles are flexible, collapsible, durable, and non-toxic, perfect for travel and space-saving needs, gradually gaining traction in a niche market. Additionally, bottles made from innovative and sustainable materials such as bamboo and recycled plastics cater to eco-conscious consumers seeking the latest sustainable options.
By Distribution Channel
Specialty stores in the Asia Pacific reusable water bottles market provide a wide selection and expert advice, catering to niche markets with specific needs, which helps in building strong brand loyalty through personalized service and exclusive product lines. Convenience stores offer quick and easy access, catering to impulse purchases due to their strategic locations, although they may have a limited variety compared to larger retail formats. Supermarkets and hypermarkets attract a diverse customer base with their wide range of competitively priced products and the convenience of one-stop shopping. Additionally, online retailers and direct sales channels, including brand-owned stores and pop-up shops, are gaining popularity by offering a vast selection, home delivery convenience, and personalized shopping experiences, which enhance brand engagement.
Segments
Based on Material Type
- Glass
- Stainless Steel
- Plastic
- Silicone
- Others
Based on Distribution Channel
- Specialty Stores
- Convenience Stores
- Supermarkets and Hypermarkets
- Others
Regional Analysis
India (25%):
India is the second-largest market, with a market share of around 25%. The growing middle class and increasing disposable income levels contribute to the rising demand for reusable water bottles. Environmental awareness campaigns and government regulations aimed at reducing single-use plastics are significant drivers in the Indian market. Urban areas, in particular, see a high adoption rate of reusable water bottles due to lifestyle changes and health consciousness. The expansion of retail and online channels in India also plays a crucial role in making reusable water bottles more accessible to consumers across the country.
Japan (15%):
Japan holds a market share of approximately 15%. The country's advanced economy, high consumer purchasing power, and strong environmental consciousness drive the market for reusable water bottles. Japanese consumers prefer high-quality and innovative products, such as bottles with advanced features like insulation and smart technology. The market is also influenced by a cultural emphasis on health and wellness, which promotes the use of safe, reusable bottles. The presence of well-established brands and a wide distribution network further support market growth in Japan.
South Korea (10%):
South Korea accounts for about 10% of the market share. The country's increasing health awareness and focus on sustainable living contribute to the demand for reusable water bottles. South Korean consumers are keen on stylish and functional products, leading to a preference for bottles with innovative designs and features. Government initiatives to reduce plastic waste and promote eco-friendly products also play a crucial role in market expansion. Additionally, the influence of online shopping and social media in South Korea facilitates the widespread adoption of reusable water bottles.
Key players
- Smith Corporation
- Newell Brands, Inc.
- Vista Outdoor, Inc. (CamelBak Products LLC)
- Groupe SEB
- Tupperware Brands Company
- SIGG Switzerland Bottles AG (Zhejiang Haers Vacuum Containers Co., Ltd.)
- Klean Kanteen
- Hydaway LLC
- Bulletin Bottle
Competitive Analysis
The Asia Pacific reusable water bottles market is highly competitive, with key players focusing on innovation, quality, and sustainability to differentiate their products. A. O. Smith Corporation and Newell Brands, Inc. leverage their extensive distribution networks and strong brand reputation to maintain market leadership. Vista Outdoor, Inc. (CamelBak Products LLC) and Klean Kanteen emphasize advanced features such as insulation and smart technology to attract tech-savvy consumers. Groupe SEB and Tupperware Brands Company capitalize on their established market presence and diverse product portfolios to cater to varying consumer preferences. SIGG Switzerland Bottles AG benefits from its reputation for high-quality, durable products, while Hydaway LLC and Bulletin Bottle focus on unique, portable designs that appeal to eco-conscious travelers. Continuous innovation and strategic partnerships are essential for these companies to stay competitive and meet the evolving demands of the Asia Pacific market.
Recent Developments
In April 2023, Nalgene announced its transition to using Eastman’s Tritan Renew for its reusable bottle production. Tritan Renew is a certified 50% recycled material determined using the mass balance technique. The transition from copolyester to Tritan Renew began in 2020 and was finalized by January 2023. During this process, Nalgene successfully repurposed over 2.35 million pounds of plastic waste, underscoring its commitment to sustainability and environmental responsibility.
In February 2023, SIGG Switzerland AG participated in the ABN AMRO Open tennis tournament in Rotterdam, providing all players with reusable drinking bottles. These bottles were crafted from Tritan Renew, a highly impact- and scratch-resistant material. The Tritan used is certified by the International Sustainability and Carbon Certification (ISCC), ensuring both durability and sustainability. This initiative highlights SIGG's commitment to promoting eco-friendly practices in high-profile sporting events.
In December 2022, Klean Kanteen, along with outdoor drinkware companies MiiR, Stanley, and YETI, formed the Drinkware CoLab. This collaboration aims to reduce carbon emissions within their supply chains and supports the Outdoor Industry Association's goal of becoming the first climate-positive industry by 2030. As members of the OIA’s Climate Action Corps, these brands are committed to generating net-positive environmental benefits, going beyond achieving net zero emissions.
In August 2022, S’well introduced its Elements Collection, featuring three high-gloss bottles named ‘Blue Marble’, ‘Charcoal Granite’, and ‘Opal Marble’. These bottles are designed with earthy tones and shades. Made from double-walled stainless steel, they maintain cold contents for 24 hours and hot contents for 12 hours. The bottles also prevent condensation, offer drip-free sipping, and have a wide mouth for adding ice, combining functionality with aesthetic appeal.
In June 2022, Tupperware Brands Corporation partnered with Vera Bradley, a U.S.-based fashion company, to launch a limited-edition collection of reusable ECO+ water bottles, snack sets, and sandwich keepers. The collection features three distinct patterns: Daisy Smile, Falling Daisies, and Sunflower. This collaboration merges Tupperware’s commitment to sustainability with Vera Bradley’s unique designs, offering stylish and eco-friendly solutions for everyday use.
Market Concentration and Characteristics
The Asia Pacific reusable water bottles market is characterized by moderate to high market concentration, with a few key players dominating the landscape. Companies such as A. O. Smith Corporation, Newell Brands, Inc., and Vista Outdoor, Inc. (CamelBak Products LLC) hold significant market shares due to their strong brand presence, extensive distribution networks, and continuous innovation in product design and functionality. The market is driven by increasing environmental awareness, health consciousness, and regulatory measures promoting the reduction of single-use plastics. It is also marked by diverse product offerings, ranging from basic plastic bottles to advanced stainless steel and smart technology-enabled bottles, catering to varying consumer preferences and lifestyles across the region.
Report Coverage
The research report offers an in-depth analysis based on Material Type and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to maintain a steady growth trajectory due to increasing environmental awareness and consumer preference for sustainable products.
- Innovations in smart technology, such as hydration tracking and self-cleaning features, will drive consumer interest and product differentiation.
- The rise of e-commerce will continue to facilitate market growth, providing consumers with easy access to a wide variety of reusable water bottles.
- Stringent government regulations aimed at reducing plastic waste will further boost the adoption of reusable water bottles across the region.
- Manufacturers will invest more in developing and utilizing eco-friendly materials, enhancing the sustainability and appeal of their products.
- The emphasis on health and wellness will continue to drive demand, as consumers seek non-toxic and safe alternatives to single-use plastic bottles.
- The trend towards customization and personalization will grow, with consumers favoring products that reflect their individual styles and preferences.
- Emerging economies within the Asia Pacific region will see increased market penetration as disposable incomes rise and awareness of reusable products spreads.
- Strategic collaborations and partnerships between brands, designers, and technology firms will result in innovative product offerings and expanded market reach.
- Companies will increasingly align with environmental advocacy and corporate social responsibility initiatives, enhancing their brand image and consumer loyalty.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Asia Pacific reusable water bottles market?
What are the main drivers of the market growth?
Which regions are leading in the reusable water bottles market in Asia Pacific?
What materials are commonly used in reusable water bottles?
How are companies addressing environmental concerns in the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Asia Pacific Reusable Water Bottles Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Asia Pacific Reusable Water Bottles Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 3,421.85 million → 2032: USD 5,851.08 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Asia Pacific Reusable Water Bottles Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Asia Pacific Reusable Water Bottles Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Asia Pacific Reusable Water Bottles Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Asia Pacific Reusable Water Bottles Market Drivers
- 3.3 Asia Pacific Reusable Water Bottles Market Restraints & Challenges
- 3.4 Asia Pacific Reusable Water Bottles Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Asia Pacific Reusable Water Bottles Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Asia Pacific Reusable Water Bottles Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Asia Pacific Reusable Water Bottles category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Asia Pacific Reusable Water Bottles Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Asia Pacific Reusable Water Bottles Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Asia Pacific Reusable Water Bottles market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Asia Pacific Reusable Water Bottles Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Asia Pacific Reusable Water Bottles Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Asia Pacific Reusable Water Bottles Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Asia Pacific Reusable Water Bottles (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Asia Pacific Reusable Water Bottles Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Asia Pacific Reusable Water Bottles Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Asia Pacific Reusable Water Bottles Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Asia Pacific Reusable Water Bottles Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Asia Pacific Reusable Water Bottles Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Asia Pacific Reusable Water Bottles Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Asia Pacific Reusable Water Bottles Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Asia Pacific Reusable Water Bottles Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Asia Pacific Reusable Water Bottles Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
