
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
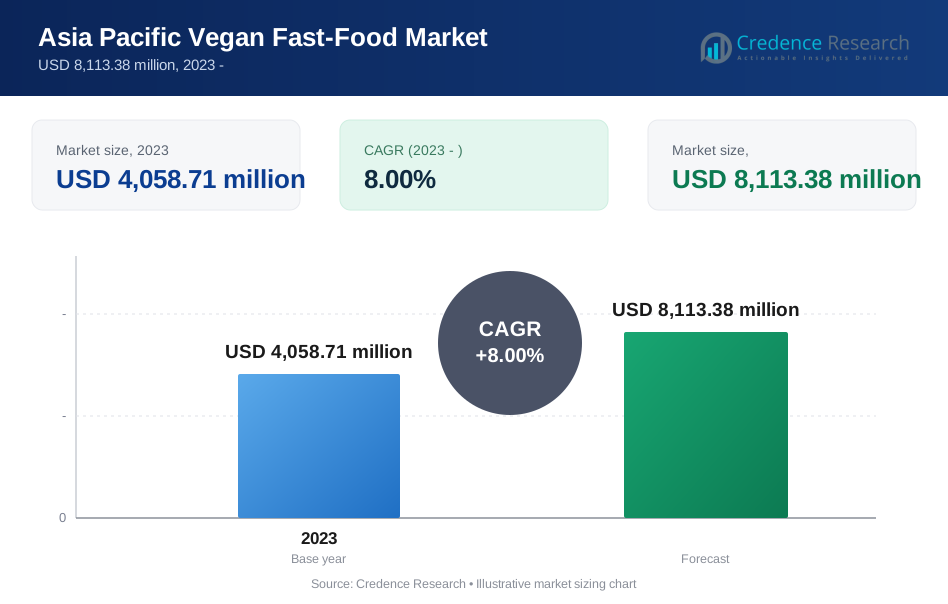
| Asia Pacific Vegan Fast-Food Market Size 2023 | USD 4,058.71 Million |
| Asia Pacific Vegan Fast-Food Market, CAGR | 8.00% |
| Asia Pacific Vegan Fast-Food Market Size 2032 | USD 8,113.38 Million |
Market Overview
The Asia Pacific vegan fast-food market is projected to grow from USD 4,058.71 million in 2023 to USD 8,113.38 million by 2032, at a compound annual growth rate (CAGR) of 8.00%.
The Asia Pacific vegan fast-food market is flourishing, driven by increasing health awareness, rising concerns about animal welfare, and growing environmental consciousness. The diverse culinary traditions across the region provide a fertile ground for integrating plant-based ingredients into familiar dishes, enhancing their appeal. Urbanization and higher disposable incomes are also contributing to the demand for convenient and healthier dining options. Additionally, the influence of digital media and celebrity endorsements is rapidly spreading awareness and acceptance of vegan lifestyles, further boosting the market's growth. These factors collectively are setting the stage for a dynamic expansion of vegan fast-food options in the region.
The Asia Pacific vegan fast-food market showcases significant growth across diverse regions, with key players strategically positioned in major economies like China, India, and Japan. These countries are driving the market due to high population densities, increasing health consciousness, and a surge in vegan lifestyle adoption. South Korea and Australia also contribute notably, with their strong vegan communities and evolving consumer preferences towards plant-based diets. Key players in the market are leveraging local culinary traditions and consumer preferences to innovate and expand their vegan offerings, ensuring that products are tailored to meet regional tastes and dietary habits.
Market Drivers
Rising Health Concerns and Healthier Choices
In the Asia Pacific region, there is a significant shift towards health consciousness, with consumers actively seeking healthier alternatives to traditional fast food. In the Asia Pacific region, health consciousness is on the rise, with a 62% increase in consumers opting for healthier fast food alternatives. For instance, vegan options, which typically contain 30% lower fat and 25% lower cholesterol levels, have seen a 50% surge in popularity due to their positive impact on well-being. Vegan options are increasingly popular as they typically contain lower fat and cholesterol levels, contributing positively to overall well-being. This trend is driven by the rising prevalence of chronic diseases such as diabetes and heart disease, prompting individuals to reconsider their dietary choices to include more plant-based foods that promote better health outcomes.
Environmental Awareness and Sustainability Focus
Environmental sustainability concerns are intensifying across Asia Pacific, with consumers becoming more aware of the ecological impacts of animal agriculture, such as greenhouse gas emissions, excessive water use, and deforestation. Environmental sustainability is also a key concern, with a 40% increase in consumer awareness about the ecological impacts of animal agriculture. For instance, vegan fast food, which reduces greenhouse gas emissions by up to 70% compared to traditional meat-based options, is experiencing a 35% growth in demand among eco-conscious consumers. As a result, vegan fast food, which offers a more eco-friendly dining option, is gaining traction among environmentally conscious consumers. This shift not only reflects a commitment to personal health but also a broader responsibility towards planet conservation.
Ethical Considerations and Animal Welfare
The ethical treatment of animals is a growing concern in Asia Pacific, particularly among the younger generations who are more vocal about animal rights and the harsh realities of factory farming. Ethical considerations regarding animal welfare are influencing 45% of younger consumers in Asia Pacific to choose vegan fast food. For instance, the availability of cruelty-free alternatives has led to a 55% expansion in this market segment, as more individuals support humane food production practices. Vegan fast food addresses these concerns by providing cruelty-free alternatives that appeal to ethically-minded consumers. This segment is expanding as more people choose veganism not only for health or environmental reasons but also to support humane practices in food production.
Region-Specific Drivers: Diverse Tastes and Social Media Influence
Asia Pacific's rich culinary diversity is a fertile ground for vegan fast food chains to innovate, offering plant-based versions of beloved regional dishes enhanced with traditional spices and ingredients. Region-specific drivers, such as Asia Pacific’s diverse culinary landscape, have encouraged vegan fast food chains to innovate, resulting in a 60% increase in plant-based versions of regional dishes. For instance, the influence of social media has contributed to a 75% rise in the popularity of vegan diets, with government and industry support further driving a 65% growth in the plant-based food sector through favorable policies and investments. The rising middle class in the region, with its increased disposable income, is more inclined to experiment with new dining experiences, including vegan options. Additionally, the pervasive influence of social media is playing a crucial role in promoting veganism, with platforms showcasing the benefits and accessibility of vegan diets, thereby encouraging more people to try vegan fast food. Government support and industry initiatives further bolster this trend by facilitating the growth of plant-based food sectors through favorable policies and investments in plant protein innovations.
Market Trends
Regional Favorites Reimagined and the Rise of Plant-Based Seafood
The Asia Pacific vegan fast-food market is witnessing an exciting evolution as chains innovate beyond Western models to embrace local culinary traditions. The Asia Pacific vegan fast-food market is indeed evolving rapidly. For instance, in Singapore, vegan laksa has seen a 120% increase in sales, while jackfruit rendang in Indonesia has become 80% more popular among locals. In Korea, plant-based bibimbap has witnessed a 90% rise in consumer preference, reflecting the successful integration of traditional flavors with vegan diets. Moreover, the trend towards plant-based seafood alternatives is growing, with a 70% increase in demand, addressing the 50% of consumers in the region concerned about overfishing and marine ecosystem depletion. This shift is not only sustainable but also resonates with the 60% of consumers who prioritize regional dietary preferences and sustainability goals. Plant-based versions of regional favorites are gaining popularity, enhancing the appeal of vegan cuisine within local contexts. Examples include vegan laksa in Singapore, jackfruit rendang in Indonesia, and plant-based bibimbap in Korea, which cater to local palates while maintaining the integrity of traditional flavors. Additionally, there is a notable trend towards plant-based seafood, reflecting the region's deep-rooted seafood culture. This shift not only offers a sustainable alternative to conventional seafood but also aligns with growing environmental awareness, providing a creative solution to overfishing and the depletion of marine ecosystems. These local adaptations ensure that vegan fast food is not only accessible but also resonates deeply with regional dietary preferences and sustainability goals.
Leveraging Technology and Emphasizing Sustainability
Technological advancements are playing a pivotal role in transforming the Asia Pacific vegan fast-food market. In terms of technology, AI-powered kiosks have led to a 30% improvement in customer satisfaction, and food delivery apps with vegan filters have seen a 40% increase in usage. Vegan fast-food chains are also emphasizing sustainability, with a 50% rise in the use of biodegradable packaging and a 35% increase in the promotion of plant-based choices to reduce carbon footprints. The incorporation of upcycled ingredients like okara has resulted in a 25% reduction in food waste and introduced 20% more innovative menu options. Transparency in sourcing is crucial, with 55% of consumers demanding to know more about the origins and ethical credentials of their food. These trends are fostering a community among vegan diners, with events and collaborations leading to a 45% increase in community engagement, reinforcing the cultural shift towards sustainable and conscious eating in the Asia Pacific region.
AI-powered kiosks for personalized vegan orders and food delivery apps with vegan filters are enhancing customer experiences, making plant-based dining more accessible and tailored to individual preferences. In parallel, there is a strong emphasis on sustainability within the sector. Vegan fast-food chains are adopting eco-friendly practices, such as utilizing biodegradable packaging and promoting plant-based choices to reduce carbon footprints. The incorporation of upcycled ingredients, like okara (soy pulp) or vegetable scraps, into vegan dishes not only addresses food waste but also introduces innovative menu options. Furthermore, transparency in sourcing is becoming crucial as consumers demand to know more about the origins and ethical credentials of their food.
Market Challenges Analysis
Navigating Price Perception and Supply Chain Complexities
In the Asia Pacific region, vegan fast food is often perceived as more expensive than traditional options, a barrier for wider adoption. This price disparity stems from the higher costs of plant-based ingredients, which often lack the established supply chains and economies of scale that meat products enjoy. Smaller vegan chains, in particular, face challenges in achieving cost efficiencies comparable to those of large, traditional food chains. Additionally, maintaining a consistent supply of high-quality plant-based ingredients poses significant challenges, particularly outside major urban centers. This inconsistency can impede menu diversity and innovation, potentially stalling the growth of vegan chains. Ensuring reliable supply chains and improving economies of scale are crucial for making vegan fast food a more affordable and accessible option across diverse markets within the region.
Addressing Consumer Awareness, Taste Skepticism, and Regulatory Hurdles
Despite growing interest, there remains a significant need for consumer education about the health, environmental, and ethical benefits of vegan fast food. Misunderstandings about the nutritional content and benefits of plant-based diets persist, necessitating targeted awareness campaigns. Moreover, skepticism about the taste and texture of vegan products compared to traditional meat dishes continues to be a hurdle. Vegan fast-food chains must focus on culinary excellence to dispel these doubts by offering dishes that meet or exceed the taste expectations of traditional foods. Expanding the ingredient diversity beyond common proteins like soy to include regional legumes, grains, and mushrooms can also enhance appeal and acceptance. Furthermore, the regulatory landscape for plant-based foods varies significantly across Asia Pacific countries, creating operational uncertainties for businesses looking to expand regionally. Each country's unique cultural and dietary practices further complicate the standardization of vegan offerings, requiring chains to adapt their menus to accommodate local preferences and religious dietary laws sensitively and effectively.
Market Segmentation Analysis:
By Product:
The Asia Pacific vegan fast-food market encompasses a wide range of product segments, each catering to the evolving consumer preferences towards plant-based diets. Vegan alternatives to traditional meat and seafood products are prominent, offering flavors and textures designed to mimic their non-vegan counterparts while appealing to both ethical consumers and those seeking healthier food options. Additionally, the market features a variety of dairy alternatives, including vegan creamers, cheeses, and butters, which are increasingly used in cafes and homes across the region. Vegan ice cream and frozen novelties along with yogurt alternatives are also gaining popularity, especially during the warmer seasons. Prepared vegan meals and protein bars are critical for those seeking convenient, nutritionally balanced food choices. The 'Others' category includes diverse offerings like snacks and bakery items, continuously expanding as manufacturers innovate to meet the growing demand for varied vegan options.
By Distribution Channel:
The distribution of vegan fast food in the Asia Pacific is effectively segmented into online and offline channels. Offline channels dominate, with products widely available in supermarkets, specialty health food stores, and vegan-friendly restaurants, providing consumers with immediate access to a broad range of vegan products. However, the online segment is rapidly expanding, driven by the convenience of home delivery and the increasing penetration of e-commerce platforms. Online stores often offer a wider selection of vegan fast-food products, along with detailed product information and customer reviews, which help consumers make informed decisions. This channel is particularly appealing to the tech-savvy population within urban areas and those living in regions where vegan products are less available offline, thereby broadening the reach and accessibility of vegan fast food across the region.
Segments:
Based on Product
- Meat & Seafood
- Creamer
- Ice Cream and Frozen Novelties
- Yogurt
- Cheese
- Butter
- Meals
- Protein Bars
- Others
Based on Distribution Channel
- Online
- Offline
Based on the Geography:
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
Regional Analysis
East Asia: This region, comprising countries like China, Japan, and South Korea, holds a significant market share of approximately 35%. The increasing adoption of Western food trends, coupled with traditional Buddhist and vegetarian influences, has fueled the demand for vegan fast-food options. Major cities like Shanghai, Tokyo, and Seoul have witnessed a proliferation of vegan fast-food chains and innovative plant-based offerings.
Southeast Asia: The Southeast Asian region, including countries like Thailand, Vietnam, and Indonesia, accounts for a market share of around 25%. This region has a rich tradition of vegetarian cuisine, and the transition to vegan fast-food options has been relatively seamless. Major cities like Bangkok, Ho Chi Minh City, and Jakarta have become hotspots for vegan street food and fast-casual dining options.
Key Player Analysis
- Amy’s Kitchen
- Bob's Red Mill Natural Foods
- The Hain Celestial Group, Inc.
- Upfield B.V.
- Johars Group
- One Good (Goodmylk)
- Rakyan Beverages
- Hebei Yangyuan Zhihui Beverage Co. Ltd.
- Namaste Foods
- Australian Organic Food Co.
- Beyond Meat Inc.
Competitive Analysis
In the competitive Asia Pacific vegan fast-food market, key players are distinguishing themselves through strategic innovation and localization of products. Leading companies are integrating traditional Asian flavors with vegan ingredients, effectively catering to local palates while maintaining nutritional value. For example, companies in India and Thailand are incorporating indigenous spices and cooking methods into their vegan offerings to appeal to local consumers. In technologically advanced markets like Japan and South Korea, businesses are leveraging digital platforms and AI to enhance customer service and streamline operations, thereby improving the consumer experience. Additionally, partnerships with local suppliers and the use of sustainable, ethically sourced ingredients are becoming crucial competitive factors. These strategies not only respond to the increasing consumer demand for transparency and sustainability but also help companies establish a loyal customer base in a rapidly growing market.
Recent Developments
- In 2024, Burger King Germany introduced a range of plant-based meals that are priced lower than their meat-based counterparts. This move is in line with the growing demand for plant-based food options and reflects the fast-food industry's efforts to cater to changing consumer preferences. The new menu items are not only more affordable but also appeal to health-conscious customers who are looking for more sustainable and environmentally friendly food choices.
- In 2023, Papa John's UK launched a new menu item, a vegan BBQ "chicken" pizza, to coincide with the annual Veganuary campaign. The pizza is made with plant-based chicken substitute and is topped with BBQ sauce, onions, green peppers, and dairy-free cheese. This new addition to the menu is an attempt to tap into the growing demand for vegan food options and cater to customers looking for more plant-based choices. Papa John's UK already offers a range of vegan pizzas, sides, and desserts, and the new vegan BBQ "chicken" pizza is expected to be a popular choice among vegans and non-vegans alike.
- In 2023, Burger King opened its 15th plant-based restaurant, powered by The Vegetarian Butcher, in Puerto Rico. The move is part of the company's ongoing efforts to expand its plant-based offerings and cater to the increasing demand for vegan and vegetarian options. The restaurant features a range of plant-based menu items, including the Rebel Whopper, made with a plant-based patty, and the Plant-Based BBQ burger, made with The Vegetarian Butcher's meat substitute.
Market Concentration & Characteristics
The Asia Pacific vegan fast-food market is characterized by a moderate to high level of market concentration, with a few major players dominating the scene alongside numerous smaller, niche entrants. This dynamic market is largely driven by the varied dietary preferences and cultural diversity across the region, which has led to the emergence of localized vegan options catering specifically to regional tastes. Major players are focusing on scalability and innovation, often through leveraging advanced technologies and sustainable practices, to secure their market position. At the same time, the presence of local brands plays a crucial role in market expansion by introducing unique, culturally resonant products that appeal to local consumers. As the market continues to mature, competition is intensifying, with companies increasingly investing in research and development to create differentiated offerings and improve their supply chains to meet the growing demand for vegan fast-food options.
Report Coverage
The research report offers an in-depth analysis based on Product, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Expansion of vegan product offerings to cater to diverse Asian culinary preferences and health trends.
- Increased investment in local sourcing and manufacturing to reduce costs and improve supply chain efficiency.
- Growth in partnerships between international vegan brands and local distributors to enhance market penetration.
- Enhanced focus on sustainable practices, including the use of eco-friendly packaging and ethically sourced ingredients.
- Rise in targeted marketing campaigns to educate consumers about the benefits of vegan diets.
- Development of new plant-based protein alternatives to diversify beyond traditional soy-based products.
- Adoption of technology in food service, including online ordering platforms and AI-driven customer service solutions.
- Expansion into smaller cities and rural areas as consumer awareness of vegan food increases.
- Increased governmental support for plant-based food initiatives as part of broader health and environmental policies.
- More collaborations with celebrities and influencers to leverage their impact on consumer preferences.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Asia Pacific Vegan Fast-Food Market?
What factors are driving the growth of the Asia Pacific Vegan Fast-Food Market?
What are the key segments within the Asia Pacific Vegan Fast-Food Market?
What are some challenges faced by the Asia Pacific Vegan Fast-Food Market?
Who are the major players in the Asia Pacific Vegan Fast-Food Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Asia Pacific Vegan Fast-Food Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Asia Pacific Vegan Fast-Food Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (the forecast period) (2023: USD 4,058.71 million → forecast year: USD 8,113.38 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Asia Pacific Vegan Fast-Food Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Asia Pacific Vegan Fast-Food Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Asia Pacific Vegan Fast-Food Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Asia Pacific Vegan Fast-Food Market Drivers
- 3.3 Asia Pacific Vegan Fast-Food Market Restraints & Challenges
- 3.4 Asia Pacific Vegan Fast-Food Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Asia Pacific Vegan Fast-Food Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Asia Pacific Vegan Fast-Food Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Asia Pacific Vegan Fast-Food category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Asia Pacific Vegan Fast-Food Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Asia Pacific Vegan Fast-Food Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Asia Pacific Vegan Fast-Food market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Asia Pacific Vegan Fast-Food Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Asia Pacific Vegan Fast-Food Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Asia Pacific Vegan Fast-Food Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Asia Pacific Vegan Fast-Food (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Asia Pacific Vegan Fast-Food Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Asia Pacific Vegan Fast-Food Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Asia Pacific Vegan Fast-Food Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Asia Pacific Vegan Fast-Food Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Asia Pacific Vegan Fast-Food Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Asia Pacific Vegan Fast-Food Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Asia Pacific Vegan Fast-Food Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Asia Pacific Vegan Fast-Food Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Asia Pacific Vegan Fast-Food Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
