
Market Overview:
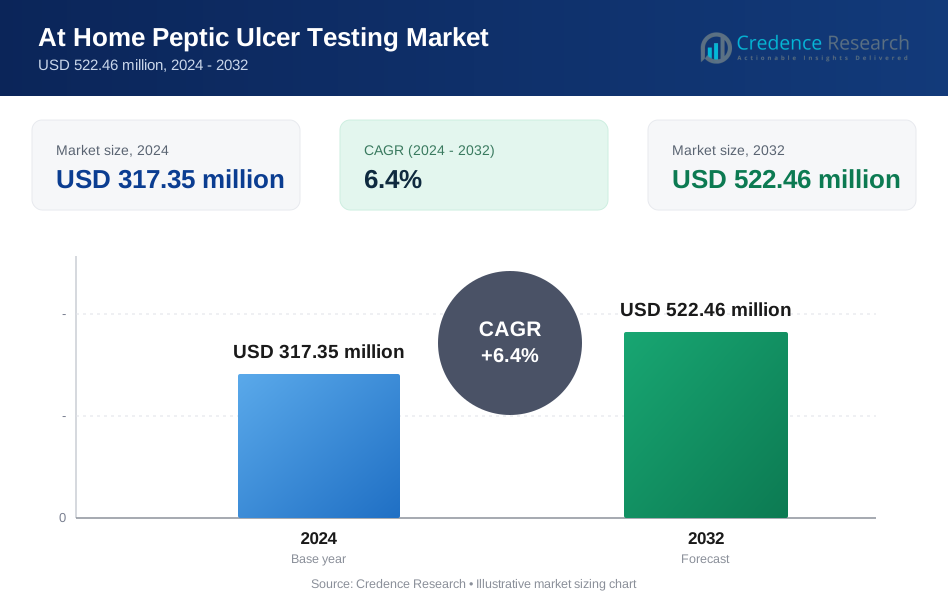
The At Home Peptic Ulcer Testing Market is projected to grow from USD 317.35 million in 2024 to an estimated USD 522.46 million by 2032, with a CAGR of 6.4% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| At Home Peptic Ulcer Testing Market Size 2024 | USD 317.35 Million |
| At Home Peptic Ulcer Testing Market, CAGR | 6.4% |
| At Home Peptic Ulcer Testing Market Size 2032 | USD 522.46 Million |
At Home Peptic Ulcer Testing Market Insights:
- Demand rises due to increasing awareness of H. pylori infection, strong preference for non-invasive testing, and wider availability of accurate home-based diagnostic kits.
- Restraints include limited user familiarity in certain regions, regulatory variations affecting product approvals, and concerns regarding proper sample handling.
- North America leads due to strong diagnostic adoption and telehealth integration, while Europe follows with structured screening support and high consumer acceptance.
- Asia Pacific, Latin America, and the Middle East & Africa show emerging growth driven by expanding digital pharmacies, rising health awareness, and improved access to home-testing tools.
At Home Peptic Ulcer Testing Market Drivers
Rising Preference for Non-Invasive Home Diagnostics
Growing demand for non-invasive self-testing methods drives strong interest in home-based ulcer detection. Users choose simple stool or breath tests that avoid clinical procedures. The At Home Peptic Ulcer Testing Market gains traction due to higher awareness of H. pylori risks. Many consumers trust at-home kits for privacy and convenience. Online platforms expand access to credible testing products. Healthcare providers guide patients toward early detection approaches. Manufacturers improve accuracy to match clinical expectations. It supports confidence among first-time users who seek faster answers.
Increasing Burden of H. pylori Infection Across Key Regions
High infection rates push health systems to promote early diagnosis to prevent complications. Patients face rising digestive discomfort that prompts at-home test adoption. The At Home Peptic Ulcer Testing Market benefits from wider concern about stomach health. Many households store self-testing kits to avoid delayed treatment. Awareness programs encourage detection before ulcers progress further. Pharmacies highlight reliable products that meet strict quality checks. Teleconsultation services help users interpret results safely. It strengthens trust in remote diagnostic pathways.
- For instance, Everlywell’s Celiac Disease Screening Test , which is frequently bundled with broader GI health panels, achieves a clinical sensitivity of 98% for detecting IgA antibodies, addressing the 40% of the global population that carries the genetic risk for digestive-related autoimmune conditions.
Growing Acceptance of Remote Healthcare and Digital Platforms
Digital channels influence testing patterns by guiding users through simple steps. Many people rely on mobile apps for instructions and support. The At Home Peptic Ulcer Testing Market expands quickly due to consumer comfort with telehealth. E-commerce distribution widens access for rural and urban buyers. Brands market easy-to-use kits that require minimal preparation. Patient groups share positive experiences that improve public confidence. Medical professionals endorse safe self-testing for preliminary screening. It encourages more users to shift away from clinic-only testing.
- For instance, OMED Health launched a clinician-led digital pathway in Great Britain that integrates a handheld breath analyzer with a smartphone app, utilizing hydrogen and methane sensors to achieve over 90% concordance with hospital-grade laboratory instruments for remote gastrointestinal monitoring.
Advancements in Test Accuracy and Biomarker Detection Technologies
Manufacturers develop improved reagents that deliver consistent result quality. Advances in H. pylori antigen and antibody detection enhance reliability. The At Home Peptic Ulcer Testing Market benefits from innovation in sample-processing methods. Several kits require small stool samples that simplify the process. Faster reaction times reduce waiting stress for users. Laboratories validate new product batches to ensure precision. Regulators approve modern devices that meet high safety standards. It drives stronger adoption among users seeking dependable outcomes.
At Home Peptic Ulcer Testing Market Trends
Expansion of Direct-to-Consumer Diagnostic Brands and Subscription Models
DTC brands invest in user-friendly packaging and digital support tools. Many firms introduce subscription plans for routine gut health screening. The At Home Peptic Ulcer Testing Market aligns with a broader push toward consumer-led care. Some platforms combine test delivery with diet and symptom tracking. Personalization grows through tailored advice after result review. Users expect faster delivery and wider product choices. Convenience shapes brand loyalty within competitive markets. It signals a shift toward long-term engagement rather than single-use purchases.
Integration of AI-Based Result Interpretation and Digital Guidance Tools
AI tools support users by explaining outcomes with clear steps. Smart apps track symptoms and guide users toward medical review when needed. The At Home Peptic Ulcer Testing Market moves toward deeper digital integration. Automated result interpretation reduces confusion and raises confidence. Predictive tools assess user risk levels based on stored patterns. Companies embed chat-based support for immediate help. Many buyers prefer guided workflows that mimic clinical advice. It enhances trust in remote testing solutions.
- For instance, SD Biosensor’s STANDARD™ F H. pylori Ag test utilizes a fluorescent immunoassay (FIA) analyzer that provides an automated numerical result in 15 minutes, achieving 96.3% sensitivity and 97.2% specificity by eliminating the subjective human error associated with visual line interpretation.
Growing Retail Pharmacies and E-Commerce Penetration for Self-Testing Kits
Large pharmacy chains highlight prominent ulcer testing options. Online marketplaces drive high visibility for trending self-testing tools. The At Home Peptic Ulcer Testing Market benefits from broader shelf placement and active promotions. Buyers compare features easily through digital catalogs. Companies optimize packaging for shipment safety and clarity. Demand rises due to availability across multiple sales channels. Retailers prioritize health diagnostics due to strong consumer interest. It strengthens product uptake, especially in emerging urban regions.
Development of Multi-Condition Gastrointestinal Test Panels
Manufacturers introduce kits that detect several digestive markers in one test. Users show interest in broader GI screening without clinic visits. The At Home Peptic Ulcer Testing Market supports this shift toward bundled diagnostics. Multi-condition panels appeal to people with recurring stomach issues. Branded kits target both ulcer detection and gut health monitoring. Healthcare providers endorse combined testing for comprehensive insight. Companies refine biomarker combinations for better accuracy. It widens the market reach and encourages repeat usage.
- For instance, Genova Diagnostics’ GI Effects® Comprehensive Profile utilizes a multi-parameter stool antigen panel that screens for H. pylori, alongside 24 commensal bacteria and inflammatory markers like calprotectin, providing a 20-page digital report with an "Individualized Microbiome Map" to guide targeted clinical interventions.
At Home Peptic Ulcer Testing Market Challenges Analysis
Limited User Familiarity and Accuracy Concerns in Self-Testing Processes
Some users doubt whether home kits match clinical standards. Confusion about sample collection reduces test reliability for certain buyers. The At Home Peptic Ulcer Testing Market faces trust gaps among first-time users. Many people seek professional confirmation despite using self-tests. Poor technique may affect result clarity for stool-based tests. Instruction gaps can lower confidence during the testing cycle. Manufacturers address these issues with clearer guides and support lines. It may take sustained education to improve user comfort.
Regulatory Variations and Supply Chain Constraints Across Multiple Regions
Approval pathways differ in major countries, limiting uniform product availability. Companies struggle with fragmented compliance requirements. The At Home Peptic Ulcer Testing Market must navigate complex distribution rules. Shipping delays reduce access in remote regions. Retail stock levels fluctuate during demand peaks. Supply challenges hinder rapid market expansion in new territories. Firms invest in local partnerships to stabilize channels. It requires ongoing coordination to maintain consistent product reach.
At Home Peptic Ulcer Testing Market Opportunities
Rising Demand for Early Ulcer Detection and Preventive Gastrointestinal Screening
Early diagnosis gains importance among consumers who monitor digestive health. Many people view self-testing as a practical step toward faster treatment. The At Home Peptic Ulcer Testing Market aligns with preventive care awareness. Educational programs promote symptom recognition and testing behavior. Growth in chronic digestive issues encourages broader screening adoption. Wellness platforms promote test kits as part of healthy routines. Providers collaborate with diagnostic brands to reinforce safe use. It supports stronger participation from proactive consumers.
Expanding Role of Telehealth Platforms and Integrated Home Diagnostic Ecosystems
Telehealth platforms link users to medical guidance after self-testing. Doctors interpret results and suggest treatment when necessary. The At Home Peptic Ulcer Testing Market gains value through connected systems. Integrated platforms combine symptom logs, diet plans, and monitoring tools. These ecosystems interest users who want structured remote care. Companies explore partnerships to embed testing into virtual clinics. Service bundles attract buyers seeking complete support. It strengthens market penetration through unified digital care pathways.
At Home Peptic Ulcer Testing Market Segmentation Analysis:
By Test Type
Stool antigen kits lead the segment due to strong accuracy and simple sample requirements. Many users rely on these kits for reliable H. pylori detection. The At Home Peptic Ulcer Testing Market benefits from clear instructions and stable reagent quality that supports user confidence. Finger-stick serology kits attract buyers who prefer quick results without stool handling. Urea breath test kits gain interest due to their clinical relevance, though device costs limit broad adoption. Other home tests include emerging biomarker tools that target wider digestive issues. It continues to evolve with improved sensitivity and user-friendly formats.
- For instance, SD Biosensor’s STANDARD™ F H. pylori Ag test reports 96.3% sensitivity and 97.2% specificity, strengthening user trust in home-based detection.
By Distribution Channel
Online direct-to-consumer platforms dominate due to strong convenience and wide product choice. Digital stores offer fast access for users seeking private testing. The At Home Peptic Ulcer Testing Market gains demand through e-commerce promotions and guided product selection tools. Retail pharmacies and clinics support buyers who want in-person assistance. Pharmacists help users choose tests that match symptoms. Telehealth-linked channels grow as virtual care integrates diagnostic kits into remote treatment plans. Many consumers value seamless pathways between testing and medical review. It strengthens the reach of structured remote health support.
By Application
Peptic or gastric ulcer detection holds the largest share due to rising awareness of H. pylori-related risks. Many users prefer home kits to avoid delays linked to clinical appointments. The At Home Peptic Ulcer Testing Market aligns with preventive screening among individuals with recurring digestive discomfort. Gastrointestinal monitoring grows through multi-condition test panels that track long-term gut health. These tools support people with chronic symptoms who need periodic checks. The “others” category includes wellness-focused tests that evaluate broader digestive biomarkers. It widens adoption among users seeking holistic insight into stomach health.
- For instance, Biomerica’s Fortel® Ulcer Test demonstrates over 90% concordance with laboratory ELISA benchmarks, boosting confidence in home-based evaluation.
Segmentation:
By Test Type
- Stool Antigen Kits
- Finger-stick Serology Kits
- Urea Breath Test Kits
- Other Home Tests
By Distribution Channel
- Online Direct-to-Consumer (DTC)
- Retail Pharmacies & Clinics
- Telehealth-Linked Channels
By Application
- Peptic/Gastric Ulcer Detection
- Gastrointestinal Monitoring
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America holds the largest share of the At Home Peptic Ulcer Testing Market, accounting for roughly 35–38% of global revenue. Strong healthcare infrastructure and high consumer awareness support widespread use of home testing kits. Large retail and e-commerce networks help sell products directly to consumers. Telehealth integration further encourages remote diagnostics in the United States and Canada. Regional programs promote early detection of H. pylori infections, boosting test adoption. It benefits from direct distribution through pharmacies and online stores.
Europe maintains the second-largest share at about 25–28% due to structured health systems and high acceptance of self-testing tools. Major Western European countries report strong uptake in home diagnostic kits. Regulatory clarity in the EU speeds product approval and distribution across member states. Digital health remains a key driver, with healthcare providers recommending at-home tests. Companies tailor offerings for local language support and guidance. It supports sustained demand from both clinical and consumer segments.
Asia Pacific is emerging with an approximate 20–22% market share driven by rapid urbanization and rising health awareness. Countries such as China, India, and Japan show increased interest, supported by expanding online sales channels. Growing middle-class income allows more households to invest in health monitoring products. Local manufacturers partner with global brands to widen distribution. Latin America and Middle East & Africa contribute the remaining share, with gradual adoption in major urban centers. It presents long-term potential due to growing digital health initiatives and expanding pharmacy access.
Key Player Analysis:
- Abbott Laboratories
- QuidelOrtho Corp
- SD Biosensor, Inc.
- Bio-Rad Laboratories
- Siemens Healthineers
- Roche Diagnostics
- Thermo Fisher Scientific
- LabCorp
- Biomerica, Inc.
- Meridian Bioscience
- OraSure Technologies, Inc.
- Randox Laboratories Ltd
Competitive Analysis:
The At Home Peptic Ulcer Testing Market features competition between global diagnostics leaders and specialized kit producers. Major players like Abbott Laboratories, Roche Diagnostics, and Siemens Healthineers leverage strong brand equity and wide product portfolios. Their focus on reliable test accuracy and strong distribution helps secure large market segments. Mid-sized firms such as Biomerica, Inc. and Meridian Bioscience compete by targeting niche home testing needs with tailored solutions. LabCorp supports market reach through diagnostic services linked to telehealth networks. Smaller players like SD Biosensor, Inc. and OraSure Technologies, Inc. focus on affordable and user-friendly kits to attract first-time buyers. Competitive strategies include partnerships with pharmacies and online platforms to expand sales. Manufacturers invest in product improvements to meet quality standards and gain regulatory approvals. It maintains pressure on pricing and product differentiation, with a clear push toward digital support and guided test interpretation.
Recent Developments:
- In August 2025, Biomerica, Inc. received approval from the United Arab Emirates Ministry of Health and Prevention for its Fortel Ulcer Test, a 10-minute at-home diagnostic identifying the bacterium causing peptic ulcers, dyspepsia, and gastric cancer risks.
- In April 2025, Biomerica's Fortel® Ulcer Test a rapid point-of-care test for detecting H. pylori antibodies linked to peptic ulcers, dyspepsia, and gastric cancer gained approval from the United Arab Emirates Ministry of Health and Prevention, enabling its launch in the UAE market where GI diseases are rising.
- In August 2024, Kihealth partnered with Genova Diagnostics to deliver advanced gut health testing, including H. pylori assays, directly to consumers via retail pharmacies for greater accessibility.
Report Coverage:
The research report offers an in-depth analysis based on Test Type, Distribution Channel, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for self-testing tools will rise due to higher awareness of H. pylori risks and early ulcer detection needs.
- Digital platforms will shape stronger adoption through guided test support and integrated symptom tracking.
- Product accuracy will improve as manufacturers refine biomarkers and optimize reagents for home use.
- Broader acceptance of remote care will boost test–telehealth integration across major markets.
- E-commerce expansion will strengthen global access, particularly in high-growth emerging regions.
- Multi-condition gastrointestinal panels will attract users seeking broader digestive insights.
- Subscription-based home diagnostic services will gain traction among proactive health consumers.
- Partnerships between diagnostic firms and virtual clinics will support more structured testing journeys.
- User-friendly formats will improve first-time adoption through simpler sample handling and better instructions.
- Competitive pressure will push companies toward innovation, affordability, and wider distribution coverage.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for At Home Peptic Ulcer Testing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the At Home Peptic Ulcer Testing Market projected to grow between 2024 and 2032?
Which At Home Peptic Ulcer Testing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the At Home Peptic Ulcer Testing Market?
Who are the leading companies in the At Home Peptic Ulcer Testing Market?
Which region commanded the largest share of the At Home Peptic Ulcer Testing Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 317.35 million → 2032: USD 522.46 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global At Home Peptic Ulcer Testing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global At Home Peptic Ulcer Testing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global At Home Peptic Ulcer Testing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global At Home Peptic Ulcer Testing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global At Home Peptic Ulcer Testing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global At Home Peptic Ulcer Testing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global At Home Peptic Ulcer Testing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global At Home Peptic Ulcer Testing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 317.35 million → 2032: USD 522.46 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global At Home Peptic Ulcer Testing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global At Home Peptic Ulcer Testing Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global At Home Peptic Ulcer Testing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global At Home Peptic Ulcer Testing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

