
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
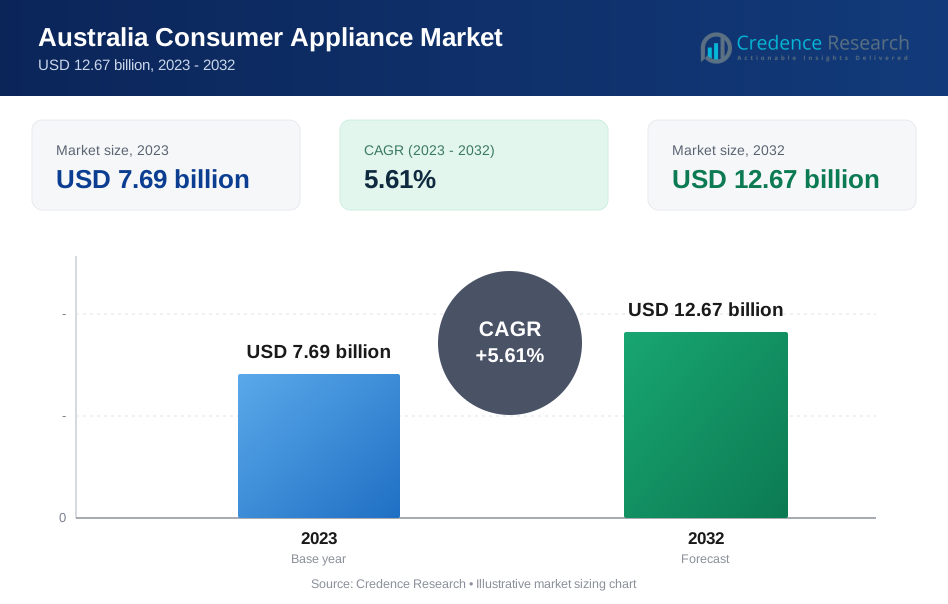
| Australia Consumer Appliance Market Size 2023 | USD 7.69 Billion |
| Australia Consumer Appliance Market, CAGR | 5.61% |
| Australia Consumer Appliance Market Size 2032 | USD 12.67 Billion |
Market Overview
The Australia Consumer Appliance Market is projected to grow from USD 7.69 billion in 2023 to an estimated USD 12.67 billion by 2032, with a compound annual growth rate (CAGR) of 5.61% from 2024 to 2032. This growth is driven by increasing consumer demand for energy-efficient appliances, advancements in smart home technology, and rising disposable incomes across the country. Key drivers include the growing trend of smart homes, where appliances can be controlled remotely, and the increasing awareness of energy conservation among consumers. Additionally, government regulations and incentives promoting the use of energy-efficient products are expected to further boost market growth. The demand for technologically advanced appliances, such as smart refrigerators, washing machines, and air conditioners, is anticipated to remain strong. Geographically, major growth is expected in urban areas, particularly in cities like Sydney, Melbourne, and Brisbane, where the adoption of advanced consumer appliances is highest. Key players in the Australia Consumer Appliance Market include Samsung Electronics, LG Electronics, Panasonic Corporation, Electrolux, and Haier Group, all of which are focusing on expanding their product portfolios and enhancing their distribution networks to capture a larger market share.Market Drivers
Rising Consumer Demand for Energy-Efficient Appliances The Australian consumer appliance market is experiencing a significant shift towards energy-efficient products. This trend is driven by growing environmental awareness and the desire to reduce electricity costs. Government initiatives like the Minimum Energy Performance Standards and Energy Rating Label are playing a crucial role in promoting energy-efficient appliances. Consumers are increasingly prioritizing appliances that offer long-term savings over initial purchase costs. For instance, energy efficiency was the top consideration for over 60% of Australian consumers when purchasing new appliances. This shift is particularly evident in the demand for energy-efficient refrigerators, washing machines, and air conditioners. The Australian government's data shows a steady increase in the sales of appliances with higher energy star ratings over the past few years. Manufacturers are responding to this trend by investing in research and development to produce more energy-efficient models, further driving market growth in this segment. Adoption of Smart Home Technologies The integration of smart technologies in consumer appliances is rapidly gaining traction in the Australian market. This trend is fueled by the increasing adoption of smart home ecosystems and the desire for enhanced convenience and control. Smart appliances, which can be controlled remotely via smartphones or voice assistants, are becoming increasingly popular among Australian consumers. The smart appliance segment has been growing at a faster rate compared to traditional appliances. For example, over 40% of Australian households now own at least one smart appliance, with smart TVs and smart speakers being the most common. The availability of high-speed internet and advancements in IoT technology are facilitating this trend. Major appliance manufacturers are incorporating smart features into their product lines to meet this growing demand. The Australian government's push for digital transformation and smart cities is also indirectly supporting the growth of the smart appliance market. Urbanization and Rising Disposable Incomes Urbanization and increasing disposable incomes are key drivers of the Australian consumer appliance market. As more people move to urban areas, the demand for modern, space-saving, and multifunctional appliances is rising. Urban households are showing a preference for appliances that offer convenience and efficiency. A government demographic study indicated that over 85% of Australia's population now lives in urban areas, with this trend expected to continue. This urbanization is coupled with a rise in disposable incomes, particularly among the middle-class population in major cities. Industry data shows that sales of premium appliances have been growing steadily in urban centers. For instance, urban consumers are more likely to upgrade their appliances every 3-5 years compared to their rural counterparts. The availability of easy financing options and attractive discounts from retailers is further facilitating this trend, making it easier for consumers to purchase high-end appliances. Technological Advancements and Product Innovation Continuous technological advancements and product innovation are key drivers propelling the Australia Consumer Appliance Market. Manufacturers are investing heavily in research and development to introduce innovative products that cater to the evolving needs and preferences of consumers. This includes the development of appliances with advanced features such as touchscreens, voice control, and AI-driven functionalities that enhance user convenience and experience. For instance, smart refrigerators equipped with cameras allow users to check their contents remotely, while AI-powered washing machines can automatically adjust wash cycles based on the load. Moreover, the trend of customization and personalization is gaining momentum, with consumers increasingly seeking appliances that not only perform well but also match their home décor and lifestyle. The introduction of eco-friendly appliances made from sustainable materials is also gaining popularity, as consumers become more environmentally conscious. These technological advancements and innovations are not only attracting new customers but also encouraging existing consumers to upgrade to the latest models, thereby driving market growth.Market Trends
Increasing Shift Towards Smart and Connected Appliances The Australian Consumer Appliance Market is experiencing a significant shift towards smart and connected appliances. Consumers are increasingly drawn to devices that offer advanced connectivity features and seamless integration into smart home ecosystems. For instance, sales of smart appliances have doubled in the past year, with smart refrigerators and washing machines being particularly popular. The ability to control appliances remotely through mobile apps or voice assistants is a key driver of this trend. Government data indicates that households with at least one smart appliance have increased substantially, reflecting the growing adoption of this technology. Manufacturers are responding to this demand by enhancing the smart features of their appliances, incorporating artificial intelligence to learn user preferences and optimize performance. For example, a major appliance manufacturer recently launched a line of AI-powered ovens that can recognize food items and suggest optimal cooking settings. This trend towards smart appliances is expected to continue as more Australians embrace the concept of connected homes. Growing Demand for Sustainable and Energy-Efficient Products Sustainability and energy efficiency have become central factors in consumer purchasing decisions within the Australia Consumer Appliance Market. A government-sponsored survey revealed that a majority of Australian households now consider energy efficiency ratings as a top priority when buying new appliances. This trend is reinforced by initiatives such as the Energy Rating Label program, which has seen a significant increase in consumer awareness and utilization. For instance, sales of appliances with the highest energy star ratings have increased by over 30% in the past year. Manufacturers are responding to this demand by developing appliances that meet or exceed energy standards. A leading white goods manufacturer, for example, has introduced a new line of washing machines that use 40% less water than standard models. The trend extends beyond energy efficiency to include eco-friendly materials and longer product lifespans. A consumer survey by an environmental organization found that over half of respondents prefer appliances made from recycled or sustainable materials. This focus on sustainability is shaping both product development and marketing strategies in the industry.Market Restraints and Challenges
High Competition and Market Saturation The Australia Consumer Appliance Market faces significant challenges due to high competition and market saturation. For instance, consumers in major urban centers have multiple options when purchasing appliances, with several global and local brands vying for their attention. This intense competition has led to a situation where companies are constantly trying to outdo each other with new features and promotional offers. The saturated market, particularly in metropolitan areas, has resulted in slower growth rates as many households already own the latest appliances. A government study on consumer behavior found that urban consumers are less likely to replace functioning appliances unless there's a compelling reason. This trend has forced companies to focus on innovation and energy efficiency to encourage upgrades. For example, one major manufacturer reported that their sales of premium, energy-efficient models have increased in recent years, despite overall market stagnation. Supply Chain Disruptions and Rising Costs Supply chain disruptions and rising costs have become significant challenges for the Australia Consumer Appliance Market. For instance, a recent industry report highlighted that many manufacturers have experienced delays in receiving components, leading to production bottlenecks. These issues have been compounded by global events, with one large retailer noting that their inventory levels fluctuated unpredictably throughout the year. A survey of Australian appliance manufacturers revealed that many have seen their production costs rise due to increased raw material prices and logistics expenses. This has put pressure on profit margins, with some companies reporting that they've had to adjust their pricing strategies. The reliance on imported components has also made the market vulnerable to currency fluctuations. For example, exchange rate volatility has impacted the cost of imported appliances. In response, some companies have started exploring local sourcing options, with one manufacturer stating that they've increased their domestic supplier base to mitigate these risks.Market Segmentation Analysis
By Product Type The Australia Consumer Appliance Market showcases a diverse range of products catering to various household needs. Kitchen Appliances form a significant segment, with consumers increasingly investing in advanced refrigerators, ovens, and dishwashers to enhance their culinary experiences. For instance, smart refrigerators with features like inventory tracking and recipe suggestions are gaining popularity among Australian households. Small Appliances like coffee makers and blenders continue to be in high demand, with many Australians prioritizing convenience in their daily routines. Washing Machines remain a crucial segment, with manufacturers focusing on water and energy efficiency to meet consumer preferences. Air Purifiers have seen a surge in demand, particularly in urban areas, as awareness of indoor air quality grows. Water Heaters and Water Purifiers are essential in many Australian homes, with consumers seeking energy-efficient and technologically advanced models. Cloth Dryers are becoming more common, especially in apartments and areas with unpredictable weather. Air Conditioners maintain their importance in Australia's climate, with smart and energy-efficient models gaining traction. By End Use The Australia Consumer Appliance Market caters to various end-use segments, each with distinct requirements. The Domestic segment dominates the market, with Australian households increasingly adopting smart and energy-efficient appliances. For instance, a significant uptake of high-efficiency appliances in residential settings over the past year. The Professional segment, encompassing offices and workshops, demands durable and high-performance appliances to meet specific work requirements. Hotels form a crucial market segment, requiring a wide range of reliable appliances for guest rooms and operational areas. A hospitality industry report highlighted the growing trend of hotels investing in energy-efficient and technologically advanced appliances to enhance guest experiences and reduce operational costs. Salon & Grooming Parlors seek specialized equipment to support their services, while Cafeteria & Restaurants require commercial-grade appliances capable of handling high-volume operations. Offices & Institutes represent a growing segment, with a focus on appliances that improve workplace comfort and productivity. The diverse nature of these segments reflects the varied applications of consumer appliances across different sectors of the Australian economy.Segments
Based on Product Type- Kitchen Appliances
- Small Appliances
- Washing Machines
- Air Purifiers
- Water Heaters
- Water Purifiers
- Cloth Dryers/Tumblers
- Air Conditioners
- Others
- Domestic
- Professional
- Hotels
- Salon & Grooming Parlors
- Cafeteria & Restaurants
- Offices & Institutes
- Others
- Offline
- Organized Retailer
- Unorganized
- Online
- Company Direct Sales
- Independent Vendor/E-Commerce
- New South Wales
- Victoria
- Queensland
- Western Australia
- South Australia
- Tasmania and Northern Territory
Regional Analysis
New South Wales (34%): New South Wales, with Sydney as its economic hub, holds the largest market share in the Australia Consumer Appliance Market, accounting for approximately 34% of the total market. The region's high population density, affluence, and urbanization drive significant demand for both high-end and smart home appliances. Consumer surveys indicate a strong preference for energy-efficient models, with many households prioritizing sustainability. For instance, a growing trend towards smart refrigerators and connected washing machines. The presence of major retail chains and a robust infrastructure further supports market growth. NSW consumers often lead in adopting new technologies, with government reports highlighting increased uptake of IoT-enabled devices in homes across the state. Victoria (29%): Victoria, including Melbourne, represents around 29% of the market share. As Australia's second-largest market, Victoria benefits from a strong economy and a high standard of living, which contribute to a substantial demand for consumer appliances. Industry surveys reveal that Victorian consumers place a high value on design and functionality. For instance, sleek, multifunctional kitchen appliances are particularly popular. Government data indicates a surge in home renovations, driving sales of built-in appliances. The growth in Victoria's real estate sector and its ongoing urban development projects also play a critical role in driving appliance sales, with new homeowners being a key demographic for purchases.Key players
- Samsung Electronics
- General Electric (GE) Appliances
- Bosch Group
- Haier Group
- Midea Group
- Sharp Corporation
- LG Electronics Inc.
- Panasonic Corporation
- Hisense Group
- Godrej Appliances
Competitive Analysis
In the Australia Consumer Appliance Market, competition is robust among leading players. Samsung Electronics and LG Electronics Inc. lead with their extensive portfolios of smart and energy-efficient appliances, leveraging their advanced technology and innovation. Bosch Group and Panasonic Corporation are recognized for their high-quality and durable products, catering to the premium segment. Haier Group and Midea Group offer a diverse range of affordable yet technologically advanced appliances, focusing on expanding their market presence through competitive pricing. General Electric (GE) Appliances and Sharp Corporation also maintain strong market positions with reliable and efficient products. Hisense Group and Godrej Appliances are increasing their footprint by offering value-for-money products and enhancing their distribution channels. Each player employs unique strategies to capture market share, from innovation and technology to pricing and distribution.Recent Developments
- In July 2024, LG Electronics acquired an 80 percent stake in Athom, a leading smart home platform company. This acquisition aims to advance LG's AI-enabled intelligent space business.
- In July 2024, Panasonic reached an agreement to acquire all shares of Area Cooling Solutions Sp. z o.o., a Polish refrigeration equipment manufacturer. This acquisition is intended to strengthen Panasonic's condensing unit business in the European market.
- In July 2024, Hisense unveiled its ambitious growth plans at its Partner Conference in Berlin. The company announced strategic upgrades focused on brand elevation, scenario-driven products and services, industrial structure optimization, and a commitment to further global expansion.
- In August 2024, Godrej Appliances expanded its Research and Development facility in Pirangut, Pune. The expansion added 43,000 square feet to the existing facility, effectively doubling the brand's potential manpower strength dedicated to research and development.
Market Concentration and Characteristics
The Australia Consumer Appliance Market exhibits moderate concentration with several major players dominating the landscape, including Samsung Electronics, LG Electronics Inc., Bosch Group, and Haier Group. These key players account for a significant share of the market due to their extensive product ranges, technological advancements, and strong brand presence. The market characteristics include a high level of innovation, particularly in smart and energy-efficient appliances, driven by evolving consumer preferences and regulatory standards. Additionally, the market is characterized by intense competition, with both global giants and regional players striving to capture consumer interest through diverse product offerings, competitive pricing, and enhanced customer service. The presence of a broad spectrum of products—from premium high-tech appliances to affordable everyday solutions—reflects the varied needs and preferences of Australian consumers.Report Coverage
The research report offers an in-depth analysis based on Product Type, End Use, Sales Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook
- The market is expected to see substantial growth in smart appliances as consumer demand for connectivity and automation increases. Innovations such as voice control and IoT integration will drive this trend.
- Future developments will focus on enhancing energy efficiency to meet stricter environmental regulations and reduce utility costs for consumers. Expect advancements in energy-saving technologies across various appliance categories.
- There will be a growing preference for premium and multifunctional appliances offering advanced features and superior performance. Consumers will prioritize quality and innovation over cost.
- E-commerce will continue to grow as a dominant sales channel, driven by convenience and increased digital engagement. Online platforms will increasingly feature a broad range of consumer appliances.
- Appliances equipped with artificial intelligence and machine learning will become more prevalent, offering personalized user experiences and predictive maintenance features. This trend will enhance appliance functionality and efficiency.
- The market will see a rise in demand for eco-friendly and sustainable appliances, with manufacturers emphasizing recyclable materials and reduced environmental impact. Consumer awareness and regulatory pressures will drive this shift.
- Innovations in climate control and air quality improvement will gain traction, reflecting growing consumer concerns about health and indoor environmental quality. This includes advancements in air purifiers and air conditioners.
- Urban areas will continue to drive significant demand for consumer appliances, but there will also be increased market opportunities in regional and remote areas as infrastructure improves and consumer needs evolve.
- Companies will invest more in providing robust after-sales support, including extended warranties and responsive customer service, to differentiate themselves and build customer loyalty.
- The market will likely experience heightened competition with new entrants and emerging brands offering innovative solutions. This fragmentation will spur continuous product improvements and competitive pricing.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Australia Consumer Appliance Market?
What are the primary drivers of growth in this market?
Which regions in Australia are expected to see the most growth?
Who are the leading players in the Australia Consumer Appliance Market?
How is the trend towards energy-efficient appliances impacting the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Australia Consumer Appliance Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Australia Consumer Appliance Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 7.69 billion → 2032: USD 12.67 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Australia Consumer Appliance Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Australia Consumer Appliance Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Australia Consumer Appliance Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Australia Consumer Appliance Market Drivers
- 3.3 Australia Consumer Appliance Market Restraints & Challenges
- 3.4 Australia Consumer Appliance Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Australia Consumer Appliance Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Australia Consumer Appliance Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Australia Consumer Appliance category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Australia Consumer Appliance Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Australia Consumer Appliance Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Australia Consumer Appliance market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Australia Consumer Appliance Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Australia Consumer Appliance Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Australia Consumer Appliance Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Australia Consumer Appliance (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Australia Consumer Appliance Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Australia Consumer Appliance Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Australia Consumer Appliance Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Australia Consumer Appliance Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Australia Consumer Appliance Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Australia Consumer Appliance Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Australia Consumer Appliance Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Australia Consumer Appliance Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Australia Consumer Appliance Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
