
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Australia In Vitro Diagnostics (IVD) market Size 2023 | USD 445.6 million |
| Australia In Vitro Diagnostics (IVD) market, CAGR | 4.60% |
| Australia In Vitro Diagnostics (IVD) market Size 2032 | USD 678.24 million |
Market Overview:
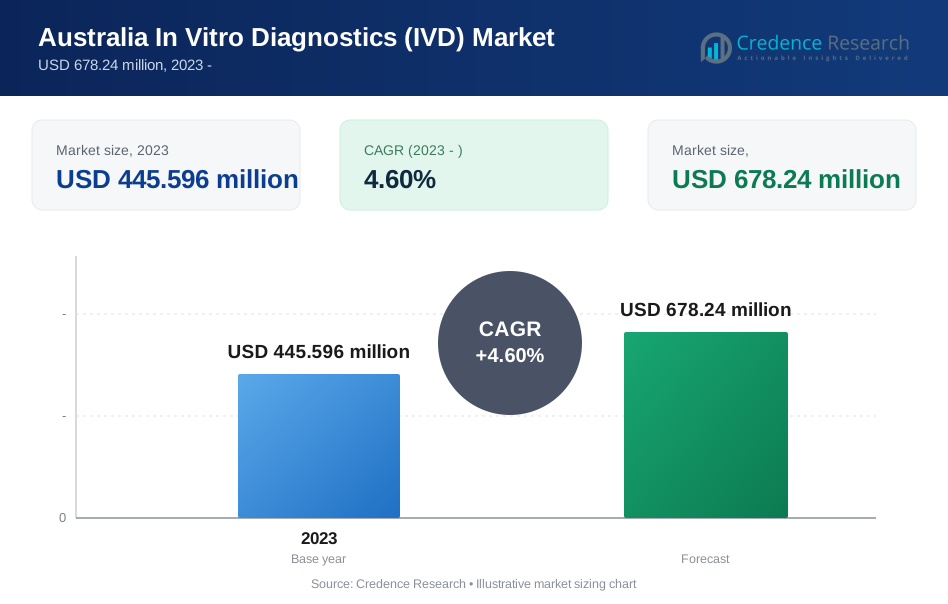
The Australia In Vitro Diagnostics (IVD) market is expected to develop at a CAGR of 4.60% between 2024 and 2032, from its estimated USD 445.6 million in 2023 to USD 678.24 million in 2032.
The Australia In Vitro Diagnostics (IVD) market is experiencing growth driven by several key factors, including the rising prevalence of chronic diseases such as diabetes and cancer. This trend underscores the increasing demand for diagnostic tools aimed at early detection and improved treatment outcomes. Moreover, the focus on personalized medicine and the aging population further contribute to the market expansion, as accurate and specific diagnostic information becomes crucial for tailoring treatments to individual needs. Technological advancements, supported by government initiatives promoting innovation and accessibility, are enhancing the development of more advanced and user-friendly IVD kits.
The market landscape is characterized by the presence of both established international players and domestic manufacturers, competing for market share. Companies like Abbott Laboratories, Roche Diagnostics, and Siemens Healthineers are prominent participants in this dynamic market. While the market is currently concentrated in major cities with dense healthcare infrastructure, efforts are underway to improve access to IVD technologies in remote and regional areas. However, challenges such as stringent regulatory requirements, reimbursement complexities, and data security concerns persist, necessitating ongoing efforts to address these obstacles and sustain the market's growth trajectory.
Market Drivers:
Rising Prevalence of Chronic Diseases:
Australia’s population is aging, and with it comes an increased prevalence of chronic diseases like diabetes, heart disease, and cancer. These conditions require regular monitoring and diagnosis, leading to a heightened demand for IVD kits for early detection, management, and treatment optimization. For instance, nearly 9 in 10 (89%) of deaths in 2020 were associated with the 10 chronic diseases. In 2020–21, 1 in 2 Australians (47%) had 1 or more of 10 selected chronic conditions. The prevalence of chronic conditions increased from 42% over the last decade. Females aged 15 years and over were more likely than males to have a chronic condition (57% compared to 51%).
Growing Focus on Personalized Medicine:
The healthcare landscape is shifting towards personalized medicine, tailoring treatment plans to individual patients’ genetic makeup and specific needs. IVD kits play a crucial role in this approach by providing valuable diagnostic information for personalized treatment decisions. For instance, in February 2022, Genomic Medicine Sweden (GMS) and the Centers for Personalized Medicine (ZPM) in Germany, collaborated for strategic, structural, and content-specific efforts to implement precision medicine in healthcare. Moreover, a research study published in Elsevier in 2020 indicated that COVID-19 infections are linked with gene variants on chromosomes and loss of variants present on the X-chromosome . This has propelled the demand for personalized medicine in gauging an individual’s immunity to combat COVID-19 infection. Another instance is a research study carried out at the University of California at Irvine in September 2022, which proposed a novel technique for management of inherited retinal diseases (IRDs) by using precision genome editing that is very specific to an individual's requirements.
Government Initiatives and Reimbursement Policies:
The Australian government is actively involved in supporting the development and adoption of new diagnostic technologies. Additionally, favorable reimbursement policies for certain IVD tests incentivize healthcare providers to utilize these tools, further stimulating market growth. For instance, the Australian government has set out clear and measurable steps for how stakeholders across the nation will implement Australia’s National Digital Health Strategy. Key recommendations from the report, Diagnostic Technology Sovereign Capability & Resilience: A National Action Plan, include establishing a National Diagnostics Development Centre and Diagnostics Manufacturing Fund to support the commercialisation and in-country manufacture of diagnostic products.
Technological Advancements and Innovation:
Continuous advancements in IVD technologies are leading to the development of more accurate, user-friendly, and rapid diagnostic kits. This includes innovations in areas like molecular diagnostics, point-of-care testing, and automation, which improve efficiency and accessibility of diagnostic testing.
Market Trends:
Focus on Early Disease Detection and Chronic Disease Management:
Australia’s increasing emphasis on preventative healthcare, driven by rising awareness among the population, is fostering a greater demand for IVD kits tailored for early disease detection and chronic disease management. For instance, in 2020, the Australian government invested around AUD 400 million in preventative health measures, including early disease detection. With chronic conditions like diabetes and cancer posing significant healthcare challenges, timely diagnosis facilitated by IVD kits are crucial for effective disease management. For instance, it is estimated that over 1.2 million Australians had diabetes in 2021, and this number is expected to grow. Government initiatives aimed at promoting preventative healthcare, such as subsidizing specific IVD tests and raising public awareness, further bolster this trend, encouraging Australians to proactively engage in healthcare monitoring and intervention. Consequently, the market for IVD kits is experiencing growth as individuals seek tools to manage their health proactively and mitigate the burden of chronic diseases.
Rise in Point-of-Care (POC) Testing Adoption:
In line with global trends, Australia is witnessing an increasing adoption of POC IVD kits, offering rapid diagnostic capabilities outside traditional laboratory settings. For instance, during the COVID-19 pandemic, the use of POC testing increased significantly, with over 5 million COVID-19 POC tests conducted in Australia. Particularly advantageous in remote areas or situations requiring swift diagnoses, POC testing enhances healthcare accessibility and efficiency. Advancements in POC technology, making these kits more user-friendly and reliable, are further propelling their adoption. For instance, the introduction of connected POC devices, which can transmit test results to healthcare providers in real-time, has improved the utility of these tests. With a broader range of conditions now addressable through POC tests, their utility and market demand continue to expand. This trend is expected to persist as healthcare providers and patients alike recognize the convenience and efficacy offered by POC testing in expediting treatment decisions and improving patient outcomes.
Market Challenges Analysis:
Addressing Regulatory and Reimbursement Challenges:
Navigating through stringent regulatory requirements imposed by the Therapeutic Goods Administration (TGA) and securing adequate reimbursement for IVD kits are critical hurdles faced by the Australian healthcare system. These obstacles can impede the timely access to innovative diagnostic tools and limit patient diagnoses, particularly for those without private health insurance. Streamlining the TGA approval process, especially for proven effective technologies from other developed nations, could accelerate access to new diagnostic solutions. Additionally, collaborative efforts among government bodies, healthcare providers, and the IVD industry are essential in developing fair and sustainable reimbursement models that balance affordability and innovation.
Investing in Workforce Development and Domestic Manufacturing:
Ensuring a skilled workforce proficient in operating and interpreting results from complex IVD technologies is paramount for effective healthcare delivery. Australia faces the challenge of a potential workforce gap, particularly in regional and remote areas. Investing in educational programs and training initiatives can help bridge this gap and ensure widespread proficiency in utilizing advanced IVD technologies. Moreover, fostering domestic manufacturing capabilities for IVD kits can reduce reliance on imports, mitigating risks associated with supply chain disruptions and price fluctuations. Encouraging local production not only enhances supply chain security but also promotes cost control and strengthens Australia's self-sufficiency in providing essential healthcare services.
Segmentation Analysis:
By Technology:
IVD kits encompass a wide array of diagnostic technologies tailored to different medical needs. Immunoassays, such as ELISA and rapid tests, are prominent for detecting antigens or antibodies indicative of infections or immune responses. Molecular diagnostics, employing techniques like PCR, offer highly precise identification of pathogens' genetic material, crucial for diagnosing infectious diseases accurately. Hematology tests, assessing blood components like red and white blood cell counts, aid in identifying potential blood disorders. Additionally, cytogenetics and histology techniques provide comprehensive disease diagnosis through chromosome analysis and microscopic examination of tissues, respectively. This diverse range of technologies ensures comprehensive diagnostic capabilities across various medical specialties, enabling precise and timely disease detection and management.
By Application:
IVD kits cater to a spectrum of healthcare needs, with infectious diseases at the forefront. These kits are instrumental in diagnosing infections, including critical ones like COVID-19 and sexually transmitted infections, facilitating prompt treatment and containment efforts. Furthermore, IVD tests play a pivotal role in managing chronic diseases like diabetes and cholesterol disorders, enabling early detection and personalized treatment approaches. In cancer diagnostics, IVD kits support screening and early intervention efforts, enhancing patient outcomes through timely diagnosis. Beyond these primary applications, IVD kits serve diverse healthcare needs, including pregnancy testing, fertility assessment, and other diagnostic requirements, ensuring comprehensive healthcare provision across various medical domains.
Segments:
Based On Product Type
- Instruments
- Reagents & Consumables
- Data Management Software
Based On Techniques
- Immunodiagnostics
- Clinical Chemistry
- Molecular Diagnostics
- Microbiology
- Hematology
- Coagulation and Hemostasis
- Urinalysis
- Others
Based On Settings
- Laboratories
- Point-of-Care
Based On Applications
- Infectious Diseases
- Diabetes
- Drug Testing/ Pharmacogenomics
- Autoimmune Diseases
- Cardiology
- Oncology
- HIV/AIDS
- Nephrology
- Gastroenterology
- Others
Based On End-user
- Clinical Laboratories
- Hospitals
- Point-of-care testing centers
- Others
Based On Region
- Western Australia
- Northern Territory
- Queensland
- South Australia
- New South Wales
- Victoria
- Tasmania
Regional Analysis:
Eastern States:
The Eastern States region, comprising New South Wales, Victoria, Queensland, and the Australian Capital Territory, holds the larger share of the Australian In Vitro Diagnostics market, estimated to be around 65%. This region's dominance can be attributed to several factors, including a high concentration of healthcare facilities, research centers, and the presence of major industry players.The Eastern States region is home to several prominent medical institutions, such as the Royal Prince Alfred Hospital in Sydney and the Peter MacCallum Cancer Centre in Melbourne, which drive the demand for advanced in vitro diagnostic technologies. Additionally, the region's strong focus on medical research and development has led to the introduction of innovative diagnostic solutions, further propelling market growth.
Western States:
The Western States region, including Western Australia, South Australia, and the Northern Territory, accounts for approximately 35% of the Australian In Vitro Diagnostics market share. While the demand for in vitro diagnostic technologies in this region has been relatively lower compared to the Eastern States, it is steadily increasing.The Western States region is characterized by a growing healthcare industry, particularly in Western Australia, which has become a hub for medical research and innovation. The region's focus on personalized medicine and the increasing adoption of advanced diagnostic technologies have contributed to the growth of the In Vitro Diagnostics market.
Key player:
- Abbott Laboratories
- Arkray Inc.
- Becton, Dickinson, and Company
- bioMérieux SA
- Bio-Rad Laboratories Inc.
- Danaher Corporation
- F Hoffmann-La Roche AG
- Transasia Bio-Medicals Ltd
- Sysmex Corporation
- Thermo Fisher Scientific
Competitive Analysis:
In the Australian in vitro diagnostics (IVD) market, a diverse range of players contributes to its dynamism and growth. Multinational corporations such as Roche Diagnostics, Abbott Laboratories, and Siemens Healthineers dominate with their extensive product ranges, global recognition, and well-established distribution channels. Meanwhile, domestic players like Sonic Healthcare and Mesocarp offer specialized products tailored to regional requirements, leveraging their agility to navigate local regulatory landscapes. Additionally, a burgeoning ecosystem of startups and mid-sized companies is injecting innovation, particularly in areas like molecular diagnostics and point-of-care testing, potentially disrupting the market with novel solutions and approaches.
Recent Developments:
In December 2023, the Bridgewest Group announced their expansion of biomedical operations in Bentley, Perth with the help of USD 2 million investment from the Western Australian Government. The expansion is aimed at boosting local manufacturing of several medical products along with the installation of new automated blow, fill, and seal line of products. Apart from boosting the infrastructure and facilities, the initiative is expected to offer 400 jobs to the local community, boosting the overall economy as well. The market has been experiencing similar investment initiatives and partnerships to enhance the quality of solutions and facilities being offered to the patients.
In July 2022, COVID-19 test kits were included in the Australian Register of Therapeutic Goods (ARTG) for legal supply in Australia by Abbott.
In June 2022, CerTest Biotec and BD announced a collaboration to develop a molecular diagnostic test for the monkeypox virus.
Market Concentration & Characteristics:
The Australian In Vitro Diagnostics (IVD) market showcases a moderately concentrated landscape. Multinational corporations currently hold a substantial share, but a growing number of domestic and regional players are actively contributing to market dynamism. This blend of established industry leaders and innovative local companies fosters a competitive environment that continuously drives advancements in diagnostic technologies. This fosters a competitive environment that continuously drives advancements in diagnostic technologies, benefiting patients with a wider range of testing options.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Technology, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is expected to see a rise in demand for personalized diagnostic tools that tailor treatment plans to individual patient needs and genetic profiles.
- Advancements in POC technology will likely lead to wider adoption of these rapid and user-friendly diagnostic tests outside traditional laboratory settings.
- Continued innovation in areas like molecular diagnostics, automation, and artificial intelligence (AI) will drive the development of more accurate, efficient, and user-friendly IVD kits.
- The increasing number of Australians diagnosed with chronic conditions like diabetes and cancer will fuel the demand for diagnostic tools to monitor and manage these diseases.
- Supportive government policies promoting early detection and diagnosis, along with favorable reimbursement structures for IVD kits, are anticipated to stimulate market growth.
- Heightened public awareness about preventive healthcare and early disease detection will likely increase demand for consumer-oriented IVD kits.
- The healthcare system's growing emphasis on value-based care will encourage the adoption of cost-effective and efficient IVD solutions that improve patient outcomes.
- The integration of IVD data with electronic health records (EHRs) and big data analytics will provide valuable insights to improve disease management and treatment strategies.
- The rise of telehealth services could create opportunities for remote diagnostics using innovative IVD technologies.
- Regulatory hurdles, data security concerns, and ensuring affordability of IVD kits will require ongoing attention from stakeholders within the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Australia In Vitro Diagnostics (IVD) Market?
What factors are driving the growth of the Australia IVD market?
What are the key segments within the Australia IVD market?
What are some challenges faced by the Australia IVD market?
Who are the major players in the Australia IVD Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 445.596 million → 2032: USD 678.24 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia In Vitro Diagnostics (IVD) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia In Vitro Diagnostics (IVD) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia In Vitro Diagnostics (IVD) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia In Vitro Diagnostics (IVD) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia In Vitro Diagnostics (IVD) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia In Vitro Diagnostics (IVD) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia In Vitro Diagnostics (IVD) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia In Vitro Diagnostics (IVD) Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 445.596 million → 2032: USD 678.24 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia In Vitro Diagnostics (IVD) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Australia In Vitro Diagnostics (IVD) Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Australia In Vitro Diagnostics (IVD) Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Australia In Vitro Diagnostics (IVD) Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
