
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
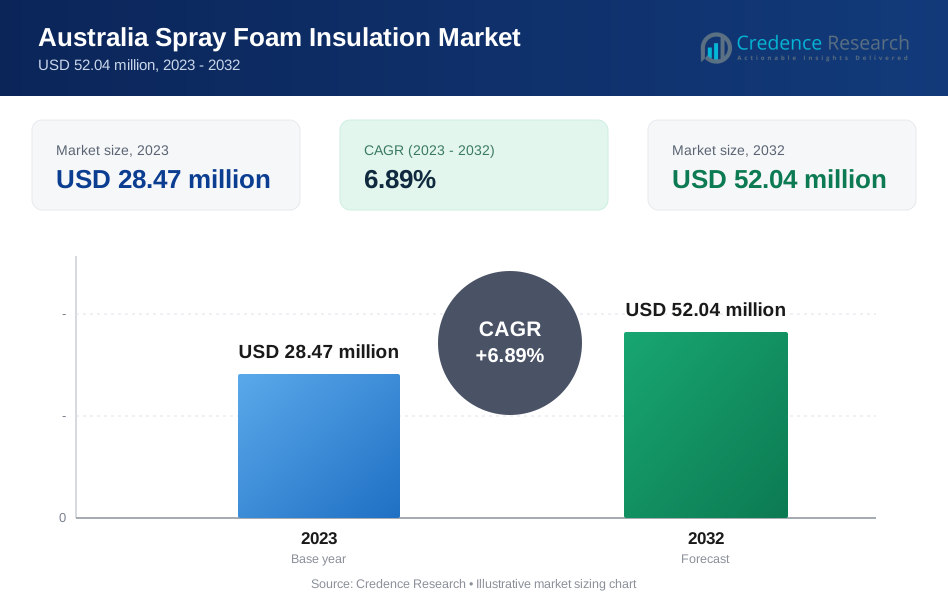
| Australia Spray Foam Insulation Market Size 2023 | USD 28.47 Million |
| Australia Spray Foam Insulation Market, CAGR | 6.89% |
| Australia Spray Foam Insulation Market Size 2032 | USD 52.04 Million |
Market Overview
The Australia Spray Foam Insulation Market is projected to grow from USD 28.47 million in 2023 to an estimated USD 52.04 million by 2032, with a compound annual growth rate (CAGR) of 6.89% from 2024 to 2032. This substantial growth is driven by increasing awareness of energy efficiency and the benefits of spray foam insulation in reducing energy consumption.
Key drivers in the Australia Spray Foam Insulation Market include rising construction activities, particularly in residential and commercial sectors, and growing demand for environmentally friendly insulation materials. Additionally, advancements in spray foam technology, offering superior thermal insulation and reduced installation time, are fueling market growth. Trends such as the increasing focus on green buildings and sustainable construction practices are also positively impacting the market.
Geographically, the market is witnessing significant growth across major regions in Australia, including New South Wales, Victoria, and Queensland, driven by rapid urbanization and infrastructural development. Leading players in the market, such as BASF SE, Huntsman Corporation, and Lapolla Industries, are focusing on expanding their product portfolios and enhancing distribution networks to cater to the rising demand. These companies are also investing in research and development to introduce innovative and high-performance insulation products, thereby maintaining a competitive edge in the market.
Market Drivers
Increasing Awareness of Energy Efficiency
One of the primary drivers propelling the growth of the Australia Spray Foam Insulation Market is the increasing awareness of energy efficiency among consumers and businesses. As energy costs continue to rise and environmental concerns become more pressing, the demand for effective insulation solutions has surged. Spray foam insulation is recognized for its superior thermal properties, which significantly reduce energy consumption by minimizing heat loss during winters and heat gain during summers. For instance, spray foam insulation is recognized for its superior thermal properties, which significantly reduce energy consumption by minimizing heat loss during winters and heat gain during summers. This heightened awareness is not only prevalent among homeowners but also among commercial building owners and industrial facilities seeking to lower their operational costs and carbon footprints. The government's initiatives and programs aimed at promoting energy efficiency, such as rebates and incentives for energy-efficient home improvements, further bolster this trend. As a result, more consumers are opting for spray foam insulation as a long-term investment in energy savings.
Growth in Construction Activities
The robust growth in construction activities across Australia is another significant driver for the spray foam insulation market. The residential, commercial, and industrial sectors are witnessing an upsurge in construction projects due to rapid urbanization, population growth, and economic development. In the residential sector, there is a rising demand for new housing units and renovations of existing homes, driven by favorable lending rates and government support for first-time homebuyers. For instance, there is a rising demand for new housing units and renovations of existing homes, driven by favorable lending rates and government support for first-time homebuyers. In the commercial sector, the expansion of office spaces, retail establishments, and hospitality projects is contributing to the increased demand for high-quality insulation materials. Additionally, the industrial sector's development, including warehouses, manufacturing plants, and cold storage facilities, requires efficient insulation solutions to maintain temperature control and energy efficiency. Spray foam insulation, with its ability to provide airtight seals and high R-value, is becoming the preferred choice in these diverse construction applications, driving market growth.
Advancements in Spray Foam Technology
Technological advancements in spray foam insulation products and application techniques are significantly driving the market in Australia. Modern spray foam formulations offer enhanced performance characteristics, such as higher R-values, improved moisture resistance, and better fire retardant properties. These advancements make spray foam insulation more effective and versatile for various applications, including roofs, walls, and floors. For instance, modern spray foam formulations offer enhanced performance characteristics, such as higher R-values, improved moisture resistance, and better fire retardant properties. The development of eco-friendly spray foam products with low Global Warming Potential (GWP) blowing agents is also gaining traction, aligning with the growing demand for sustainable building materials. Manufacturers are continuously investing in research and development to innovate and introduce new products that meet the evolving needs of the market. These technological advancements not only enhance the performance and durability of spray foam insulation but also increase its adoption in the construction industry.
Government Regulations and Incentives
Government regulations and incentives play a crucial role in driving the Australia Spray Foam Insulation Market. The Australian government has implemented stringent building codes and energy efficiency standards that mandate the use of effective insulation materials in new constructions and renovations. These regulations aim to reduce energy consumption and greenhouse gas emissions, promoting sustainable building practices. For instance, the National Construction Code (NCC) outlines specific thermal performance requirements for buildings, encouraging the use of high-performance insulation solutions like spray foam. Additionally, various state and federal government programs offer financial incentives, rebates, and grants for homeowners and businesses that invest in energy-efficient upgrades, including insulation improvements. These incentives make it more affordable for consumers to choose spray foam insulation, accelerating its adoption. The government's commitment to reducing carbon emissions and promoting green building practices creates a favorable regulatory environment for the growth of the spray foam insulation market.
Market Trends
Shift Towards Sustainable and Eco-Friendly Insulation Solutions
A significant trend in the Australian spray foam insulation market is the growing shift towards sustainable and eco-friendly insulation solutions. As environmental concerns become more prominent, there is an increasing demand for green building materials that contribute to reducing the carbon footprint of construction projects. Manufacturers are responding to this trend by developing spray foam products with environmentally friendly formulations. For instance, according to a report, global industrialization has been one of the most important and influential processes in the world in the past three centuries. These products often feature low Global Warming Potential (GWP) blowing agents, which have a minimal impact on the environment compared to traditional hydrofluorocarbon (HFC) blowing agents. Additionally, the use of renewable and recycled materials in spray foam production is gaining traction, aligning with the broader sustainability goals of the construction industry. This trend is supported by the growing adoption of green building certifications such as Green Star and LEED (Leadership in Energy and Environmental Design), which encourage the use of sustainable insulation solutions. The emphasis on eco-friendly products not only helps in complying with stringent environmental regulations but also appeals to environmentally conscious consumers and builders, driving market growth.
Integration of Smart Technology in Insulation Systems
Another notable trend in the Australian spray foam insulation market is the integration of smart technology into insulation systems. As the construction industry increasingly embraces digitalization and smart building concepts, there is a rising demand for advanced insulation solutions that can enhance the energy efficiency and performance of buildings. Smart spray foam insulation systems incorporate sensors and monitoring devices that provide real-time data on the thermal performance and integrity of the insulation. For instance, according to the “Insulation in Australia” report by the Affiliated Insulation Industry Coalition, insulation is a heavy hitter for improving energy efficiency. These systems enable proactive maintenance and optimization of energy usage, resulting in significant cost savings and improved comfort for building occupants. Additionally, the integration of smart technology facilitates compliance with energy efficiency standards and building codes by providing accurate performance metrics. This trend is particularly evident in large-scale commercial and industrial projects, where the benefits of smart insulation systems in terms of energy management and operational efficiency are substantial. The growing popularity of smart buildings and the Internet of Things (IoT) is expected to further drive the adoption of smart spray foam insulation solutions, contributing to the overall growth of the market.
Market Restraints and Challenges
High Initial Costs and Installation Complexity
One of the primary restraints in the Australia Spray Foam Insulation Market is the high initial cost and complexity associated with installation. Spray foam insulation, while highly effective, is more expensive compared to traditional insulation materials like fiberglass or cellulose. The cost includes not only the price of the material itself but also the specialized equipment and skilled labor required for installation. This can be a significant barrier for homeowners and small businesses with limited budgets, making them hesitant to invest in spray foam insulation despite its long-term energy savings. Additionally, the installation process requires professional expertise to ensure proper application and adherence to safety standards. Incorrect installation can lead to issues such as uneven coverage, off-gassing of chemicals, and inadequate thermal performance, further discouraging potential customers from choosing this insulation method. The need for specialized training and certification for installers also limits the availability of qualified professionals, contributing to higher labor costs and longer project timelines.
Health and Environmental Concerns
Health and environmental concerns pose another significant challenge to the growth of the Australia Spray Foam Insulation Market. The production and application of spray foam insulation involve the use of chemicals that can be hazardous if not handled properly. There are concerns about the release of volatile organic compounds (VOCs) and other harmful substances during and after installation, which can impact indoor air quality and pose health risks to occupants. While advancements have been made to develop low-VOC and eco-friendly spray foam products, these concerns still persist and can influence consumer perception and regulatory scrutiny. Environmental regulations are becoming increasingly stringent, requiring manufacturers to comply with standards that limit the use of certain chemicals and reduce environmental impact. This can increase production costs and create compliance challenges for manufacturers. Additionally, the disposal of spray foam insulation poses environmental challenges, as it is not easily recyclable and can contribute to landfill waste. Addressing these health and environmental concerns is crucial for gaining consumer trust and ensuring sustainable market growth.
Market Segmentation Analysis
By Foam Type
Closed-cell spray foam is characterized by its high density and rigidity, making it an excellent choice for applications requiring strong structural support and moisture resistance. It offers superior thermal insulation properties and is commonly used in commercial and industrial settings. This type of foam is preferred for areas prone to high humidity or where additional strength is needed, such as in roofing and exterior walls. Open-cell spray foam is lighter and more flexible compared to closed-cell foam. It provides excellent air sealing properties and sound insulation. While it has a lower R-value per inch than closed-cell foam, it is often used in interior applications such as wall cavities, attics, and other areas where space constraints are less of a concern. Its cost-effectiveness makes it a popular choice for residential projects.
By Density
High-density spray foam is primarily used for exterior and roofing applications due to its durability and weather resistance. It provides excellent structural integrity and is often used in commercial and industrial buildings. Medium-density foam strikes a balance between strength and flexibility. It is commonly used in both residential and commercial applications, providing good insulation and air sealing properties without the rigidity of high-density foam. Low-density foam, also known as open-cell foam, is used for interior applications where air sealing and sound insulation are priorities. Its lower cost and ease of application make it suitable for residential projects, including wall and attic insulation.
Segments
Based on Foam Type
- Closed-Cell Foam
- Open-Cell Foam
Based on Density
- High-Density Foam
- Medium-Density Foam
- Low-Density Foam
Based on Application
- Wall Insulation
- Attic Insulation
- Roof Insulation
- Concrete Rehabilitation
- Other Applications
Based on End User
- Packaging
- Building & Construction
- Automotive & Transportation
- Consumer Goods
- Medical
- Others
Based on Region
- New South Wales
- Victoria
- Queensland
- Western Australia
- South Australia and Others
Regional Analysis
New South Wales (35%):
New South Wales (NSW) is the leading region in the Australia Spray Foam Insulation Market, holding approximately 35% of the market share. The state's dominance is driven by significant urbanization and construction activities, particularly in Sydney and its surrounding areas. The demand for energy-efficient buildings and sustainable construction practices is high, prompting widespread adoption of spray foam insulation. NSW's proactive government policies promoting energy efficiency and building sustainability further bolster market growth. The region's construction sector is robust, with both residential and commercial projects increasingly incorporating spray foam insulation to enhance thermal performance and reduce energy costs.
Victoria (25%):
Victoria accounts for about 25% of the Australia Spray Foam Insulation Market. Melbourne, being a major urban center, is at the forefront of driving demand in the region. The state's emphasis on green building standards and energy-efficient solutions significantly contributes to the market's expansion. The Victorian government’s initiatives and incentives for sustainable construction have encouraged builders and developers to adopt advanced insulation materials like spray foam. Additionally, the growth in residential construction, along with renovation projects, supports the increasing utilization of spray foam insulation in Victoria.
Key players
- BASF SE
- Bayer AG
- CertainTeed Corporation
- Demilec
- Icynene Inc
- Lapolla Industries Inc
- NCFI Polyurethane
Competitive Analysis
The Australia Spray Foam Insulation Market is highly competitive, with several key players striving to enhance their market presence through innovation and strategic initiatives. BASF SE and Bayer AG are industry leaders, leveraging their extensive R&D capabilities to develop advanced spray foam products that meet stringent environmental standards. CertainTeed Corporation and Demilec focus on expanding their product portfolios and distribution networks, ensuring accessibility and reliability for their customers. Icynene Inc and Lapolla Industries Inc emphasize eco-friendly formulations, catering to the growing demand for sustainable insulation solutions. NCFI Polyurethane distinguishes itself by offering customized solutions for diverse applications, including residential, commercial, and industrial sectors. These companies are investing in technological advancements and strategic collaborations to maintain their competitive edge and address the evolving needs of the market. Their efforts collectively contribute to the growth and dynamism of the Australia Spray Foam Insulation Market.
Recent Developments
On November 14, 2023, DAP, a leader in home improvement and construction products, revolutionized spray foam application by introducing the first-of-its-kind 1-component broadcast spray foam. The Wall & Cavity Foam, featuring a wide spray applicator, enhances efficiency and ease of use, setting a new standard in the industry. This innovation addresses the need for faster, more precise insulation applications, catering to both professional contractors and DIY enthusiasts. DAP's advancement highlights their commitment to developing cutting-edge solutions that meet the evolving demands of the construction and home improvement sectors.
On April 17, 2023, Huntsman Building Solutions' high-performance spray foam insulation was integral to Manchester's OGS container scheme. The project utilized Huntsman's advanced insulation technology to enhance energy efficiency and structural integrity. By incorporating Huntsman's spray foam, the OGS container scheme achieved superior thermal performance and durability, underscoring the product's versatility and effectiveness. This collaboration demonstrates Huntsman's commitment to delivering innovative building solutions that address contemporary construction challenges and support sustainable development.
On May 27, 2022, BASF’s water-blown polyurethane insulation spray foam was utilized in the latest bus model by Kinglong United Automotive (Suzhou) Co., Ltd. (Suzhou Kinglong). BASF collaborated to develop a 100% water-blown spray open-cell foam system, meeting stringent VOC standards and significantly improving interior air quality in public transportation. This development showcases BASF's dedication to providing environmentally friendly solutions that enhance safety and comfort in public transit, highlighting the company's leadership in sustainable and innovative insulation technologies.
Market Concentration and Characteristics
The Australia Spray Foam Insulation Market is characterized by a moderate to high level of market concentration, with several key players dominating the industry. Leading companies such as BASF SE, Bayer AG, CertainTeed Corporation, Demilec, Icynene Inc, Lapolla Industries Inc, and NCFI Polyurethane hold significant market shares due to their extensive product portfolios, innovative technologies, and robust distribution networks. The market is driven by the increasing demand for energy-efficient and sustainable insulation solutions, advancements in spray foam technology, and stringent government regulations promoting eco-friendly building practices. Despite the presence of dominant players, the market remains dynamic, with opportunities for new entrants and smaller firms to innovate and cater to niche segments.
Report Coverage
The research report offers an in-depth analysis based on Foam Type, Density, Application, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Australia Spray Foam Insulation Market is projected to continue growing at a steady pace, driven by increasing awareness of energy efficiency and the benefits of spray foam insulation.
- Ongoing advancements in spray foam technology will enhance product performance, offering superior insulation properties and easier application processes.
- Stringent environmental regulations will drive demand for eco-friendly and low-VOC spray foam products, encouraging manufacturers to innovate sustainable solutions.
- Continued growth in residential, commercial, and industrial construction projects will fuel the demand for effective insulation materials like spray foam.
- Government incentives and rebates for energy-efficient building improvements will promote the adoption of spray foam insulation among homeowners and businesses.
- The market will see a rise in retrofitting projects as older buildings are upgraded to improve energy efficiency and comply with new regulations.
- The commercial sector, particularly office spaces, retail establishments, and hospitality projects, will increasingly adopt spray foam insulation for its thermal and acoustic benefits.
- Industrial applications, including warehouses and cold storage facilities, will demand high-performance spray foam solutions to maintain temperature control and energy efficiency.
- A growing emphasis on green building certifications and sustainable construction practices will boost the demand for environmentally friendly spray foam insulation products.
- Companies will diversify their product offerings to cater to specific market needs, including customized solutions for different climatic conditions and building types, enhancing market competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Australia Spray Foam Insulation Market?
What are the key drivers of the Australia Spray Foam Insulation Market?
Which regions in Australia are experiencing significant growth in the spray foam insulation market?
Who are the leading players in the Australia Spray Foam Insulation Market?
What are the current trends impacting the Australia Spray Foam Insulation Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Australia Spray Foam Insulation Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Australia Spray Foam Insulation Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 28.47 million → 2032: USD 52.04 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Australia Spray Foam Insulation Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Australia Spray Foam Insulation Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Australia Spray Foam Insulation Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Australia Spray Foam Insulation Market Drivers
- 3.3 Australia Spray Foam Insulation Market Restraints & Challenges
- 3.4 Australia Spray Foam Insulation Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Australia Spray Foam Insulation Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Australia Spray Foam Insulation Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Australia Spray Foam Insulation category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Australia Spray Foam Insulation Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Australia Spray Foam Insulation Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Australia Spray Foam Insulation market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Australia Spray Foam Insulation Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Australia Spray Foam Insulation Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Australia Spray Foam Insulation Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Australia Spray Foam Insulation (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Australia Spray Foam Insulation Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Australia Spray Foam Insulation Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Australia Spray Foam Insulation Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Australia Spray Foam Insulation Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Australia Spray Foam Insulation Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Australia Spray Foam Insulation Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Australia Spray Foam Insulation Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Australia Spray Foam Insulation Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Australia Spray Foam Insulation Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
