
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automatic Plastic Recycling Machine Market Size 2024 | USD 299.73 million |
| Automatic Plastic Recycling Machine Market , CAGR | 4.97% |
| Automatic Plastic Recycling Machine Market Size 2032 | USD 441.8 million |
Market Overview:
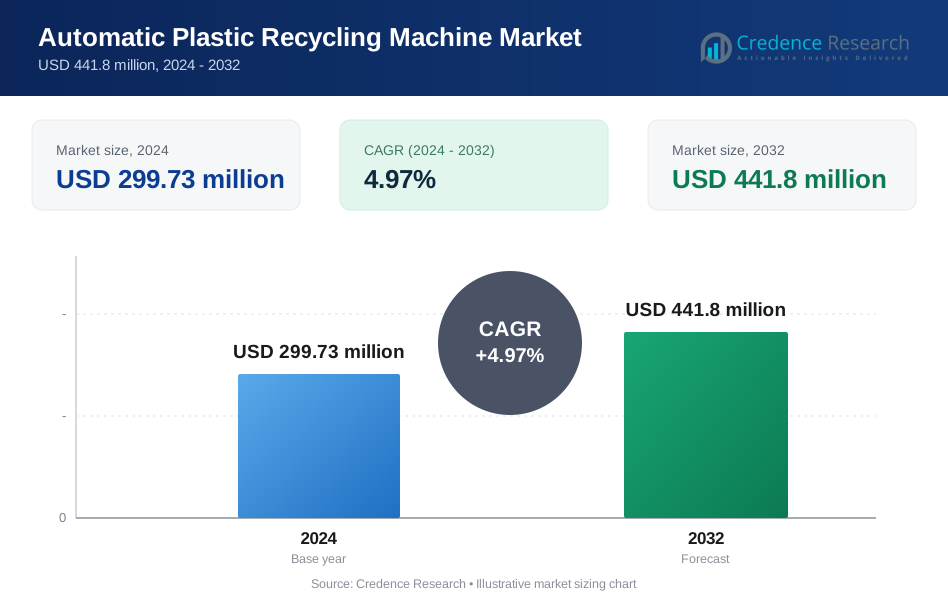
The Automatic Plastic Recycling Machine Market is projected to grow from USD 299.73 million in 2024 to an estimated USD 441.8 million by 2032, with a compound annual growth rate (CAGR) of 4.97% from 2024 to 2032.
The market's growth is fueled by several core drivers. First, the surge in global plastic consumption has necessitated more efficient and scalable recycling methods, particularly in densely populated and industrialized regions. Automated recycling machines help reduce labor dependency, enhance material purity, and increase throughput, making them an attractive investment for large recycling facilities. Regulatory mandates—such as the European Union’s circular economy initiatives and national-level Extended Producer Responsibility (EPR) schemes—are compelling manufacturers to adopt automated technologies to meet recycling targets. Consumer awareness and pressure on brands to adopt environmentally friendly practices are also pushing companies to invest in advanced recycling infrastructure. Moreover, technological advancements, including AI-driven sorting, sensor-based material identification, and energy-efficient extrusion systems, are further supporting market adoption by improving machine performance and reducing operational costs.
Regionally, North America dominates the current market landscape, supported by well-established recycling infrastructure, strong demand for sustainable packaging solutions, and proactive environmental regulations at both federal and state levels. The United States and Canada are witnessing increased deployment of automated plastic recycling systems, particularly in response to tightening landfill restrictions and corporate ESG targets. Asia-Pacific, however, is the fastest-growing regional market, propelled by rapid urbanization, rising plastic waste volumes, and evolving policy frameworks in countries such as China, India, and Indonesia. Government efforts to modernize waste management systems and encourage private sector participation are accelerating adoption across the region. Europe remains a mature market, with high recycling rates and regulatory consistency driving steady investment in automation and efficiency upgrades. Meanwhile, Latin America, the Middle East, and Africa are showing gradual market development, constrained by limited infrastructure and funding but supported by growing international cooperation and sustainability-driven initiatives. Overall, the global market is poised for robust long-term expansion, with automation playing a critical role in transforming the plastic recycling value chain.
Market Insights:
- The Automatic Plastic Recycling Machine Market is projected to grow from USD 299.73 million in 2024 to USD 441.8 million by 2032, registering a CAGR of 4.97%.
- Increasing plastic consumption and rising demand for recycled materials in packaging, automotive, and construction industries are driving market growth.
- Strict environmental regulations and Extended Producer Responsibility (EPR) mandates are compelling producers to invest in automated recycling technologies.
- Advancements in AI-based sorting, sensor technologies, and adaptive process controls are improving machine performance and output quality.
- High initial investment, energy costs, and technical complexity remain barriers for small and mid-sized recyclers.
- North America dominates the market due to established recycling infrastructure and regulatory compliance, while Asia-Pacific shows the fastest growth led by urbanization and policy reforms.
- Feedstock variability and lack of skilled operators challenge consistent system performance, pushing the need for adaptable, intelligent recycling solutions.
Market Drivers:
Surging Global Demand for Recycled Plastics Across End-Use Industries Is Strengthening Equipment Deployment:
The rising use of recycled plastic materials in industries such as packaging, automotive, construction, and consumer goods is directly influencing equipment demand. These industries seek consistent, high-quality recycled polymers to meet product standards and sustainability targets. The Automatic Plastic Recycling Machine Market is responding to this shift with systems designed to process diverse plastic types at industrial scale. Automated machines ensure material purity, maintain output uniformity, and deliver higher yield, making them essential for modern production needs. The shift from virgin to recycled plastics creates a strong business case for investing in advanced recycling technologies. Equipment that enables reliable conversion of waste into high-grade recyclate continues to attract attention from both private and public sectors.
- Erema group, for instance, launched the intarema® tveplus extrusion system in 2025, which delivers a 15% increase in throughput and 10% energy savings, processing up to 2,000 kg/h of recycled plastics.
Strict Environmental Regulations and Extended Producer Responsibility Are Driving Automation Adoption:
Global regulatory bodies are implementing firm mandates to curb plastic waste and promote recycling. Policies such as Extended Producer Responsibility (EPR), landfill restrictions, and minimum recycled content rules are placing accountability on producers and recyclers. The Automatic Plastic Recycling Machine Market is benefitting as companies upgrade to systems that comply with performance benchmarks and reporting requirements. Automated solutions support compliance by enhancing throughput, improving data collection, and reducing human error in waste handling. These machines also contribute to the traceability of recycled content, which is becoming a regulatory necessity. Governments are also offering subsidies and incentives that encourage the shift to automated recycling systems, particularly in high-waste regions.
- For instance, Vecoplan AG, introduced smart sensor integration for real-time monitoring and predictive maintenance, which reduced unplanned downtime by 22%.
Advancements in Automation, AI Integration, and Sensor-Based Sorting Are Improving System Performance:
Technological developments in robotics, machine vision, and data analytics are transforming plastic recycling operations. Automated machines now include features such as AI-driven recognition systems, near-infrared (NIR) sorting, and adaptive process controls. The Automatic Plastic Recycling Machine Market is advancing through innovations that allow machines to self-adjust based on waste input and contamination levels. These capabilities reduce reliance on manual labor while increasing efficiency and output quality. Smart systems also collect performance data in real time, enabling predictive maintenance and continuous improvement. As digital transformation accelerates in the waste management sector, intelligent automation becomes a standard rather than a differentiator.
Corporate Sustainability Goals and ESG Commitments Are Reinforcing Investment in Recycling Infrastructure:
Companies across the globe are committing to environmental, social, and governance (ESG) targets, including reductions in plastic use and carbon emissions. These commitments are pushing organizations to invest in technologies that support closed-loop production and responsible sourcing. The Automatic Plastic Recycling Machine Market aligns with these goals by offering machinery that enables efficient material recovery and traceable recycling outcomes. Brands that use recycled content can meet internal sustainability metrics while enhancing consumer trust. Pressure from investors, consumers, and regulatory agencies is amplifying the need for transparent, high-performance recycling operations. This creates sustained demand for systems that integrate automation, data tracking, and environmental accountability.
Market Trends:
Integration of Artificial Intelligence and Smart Sorting is Reshaping System Efficiency:
Manufacturers are increasingly incorporating artificial intelligence, machine vision, and sensor-based technologies to improve sorting accuracy and operational speed. These features allow machines to detect, classify, and separate plastic types with minimal manual intervention, reducing contamination and maximizing yield. The Automatic Plastic Recycling Machine Market is evolving through systems that use deep learning algorithms and real-time data to adapt to changing waste streams. This shift improves consistency and reduces downtime caused by material variability. Smart sorting not only enhances product quality but also supports traceability, a growing requirement under ESG and regulatory frameworks. These capabilities are becoming standard expectations among large-scale recyclers and municipalities.
- For instance, AMP Robotics deployed AI-powered robotic sorting systems in 2025, increasing plastic recovery rates by 20% and reducing downtime by 15% in municipal recycling centers.
Modular and Scalable System Design is Gaining Market Preference:
Demand is rising for modular recycling machines that can be customized or expanded based on capacity needs, site conditions, or budget constraints. Buyers in both developed and developing markets are favoring equipment that allows for incremental investment and phased deployment. The Automatic Plastic Recycling Machine Market is seeing a trend toward compact, plug-and-play units that require minimal installation time and space. These systems are particularly attractive for decentralized recycling operations, small municipalities, and mobile applications. Manufacturers are responding by offering flexible configurations with shared components across machine lines. This design trend helps lower ownership costs while meeting diverse processing needs.
- For instance, Herbold Meckesheim GmbH developed a modular recycling line with plug-and-play components, reducing installation time by 40% and allowing capacity scaling from 500 to 3,000 kg/h.
Focus on Energy Efficiency and Emission Reduction is Influencing Equipment Design:
Environmental performance is a growing factor in machine procurement decisions, with energy consumption and carbon footprint under increased scrutiny. Equipment designers are engineering systems that minimize electricity use, improve heat recovery, and reduce emissions during plastic melting and extrusion. The Automatic Plastic Recycling Machine Market is incorporating features such as variable speed drives, optimized thermal control, and advanced filtration systems to meet stricter environmental standards. These enhancements support global decarbonization efforts and appeal to ESG-conscious investors and operators. Energy-efficient machines also lower operating costs over the system's lifecycle, improving return on investment. Manufacturers that align design with sustainability targets gain a competitive edge.
Digital Connectivity and Predictive Maintenance Are Enhancing Lifecycle Value:
Smart connectivity and IoT integration are enabling operators to monitor system performance, energy usage, and wear conditions in real time. This connectivity allows for predictive maintenance scheduling, reducing unplanned downtime and extending machine life. The Automatic Plastic Recycling Machine Market is moving toward platforms that support cloud-based analytics, remote diagnostics, and performance benchmarking. These digital tools help operators make data-driven decisions and optimize process settings dynamically. Integration with enterprise resource planning (ERP) and sustainability reporting tools is also becoming common. These advancements position automated recycling systems as long-term assets with measurable, trackable value contributions.
Market Challenges Analysis:
High Capital Investment and Operational Costs Restrain Broader Adoption:
The significant upfront cost of automatic plastic recycling machines remains a key barrier for small and mid-sized recyclers. These systems often require complex configurations, advanced automation features, and integration with digital monitoring tools, which increase capital requirements. The Automatic Plastic Recycling Machine Market faces hesitation from potential buyers who operate in low-margin environments or in regions with limited financing options. Operational costs, including energy consumption, maintenance, and skilled labor, further impact adoption. Companies must balance sustainability goals with return on investment, especially in cost-sensitive markets. Without government subsidies or favorable financing models, many recyclers delay or limit automation upgrades.
Technical Limitations and Feedstock Variability Impact Performance Consistency:
Inconsistent feedstock quality poses challenges for automated recycling systems, which rely on standardized input for optimal efficiency. Contaminated, mixed, or multilayer plastic waste often reduces machine performance, increases wear, and complicates sorting processes. The Automatic Plastic Recycling Machine Market must address these limitations through continued innovation in sensor technologies, AI integration, and modular design. Machine adaptability remains a concern, particularly in regions lacking proper waste segregation systems. Training gaps and shortages of qualified technical staff also hinder machine utilization and throughput. Without comprehensive support systems and adaptable machine designs, recyclers may struggle to achieve desired performance levels in diverse operating conditions.
Market Opportunities:
Rising Demand for Circular Economy Solutions is Creating Scalable Growth Avenues:
Governments and industries worldwide are accelerating the shift toward circular economy models, presenting strong market opportunities for automation in recycling processes. The Automatic Plastic Recycling Machine Market can leverage this shift by offering scalable solutions that enhance material recovery and reduce environmental impact. Companies across packaging, automotive, and electronics sectors require reliable recycled plastic sources to meet regulatory and consumer expectations. Automated systems enable consistent quality, high throughput, and compliance with sustainability targets, making them critical to circular operations. Demand for equipment that integrates seamlessly into closed-loop production lines is growing. This trend supports long-term expansion opportunities for manufacturers and technology providers.
Emerging Economies and Infrastructure Gaps Offer Room for Market Penetration:
Many developing countries are investing in waste management infrastructure, opening new markets for compact, cost-effective, and automated recycling machines. The Automatic Plastic Recycling Machine Market stands to gain from targeted solutions that address limited landfills, rising plastic consumption, and urbanization. Local governments and private operators are exploring modular systems that require less space and training while maintaining high output. Foreign direct investments and international development programs are improving access to funding and technical support. These factors enable market entry and sustained growth across Latin America, Southeast Asia, and parts of Africa. Strategic localization and service support will be critical to capturing these opportunities.
Market Segmentation Analysis:
By Type
The Automatic Plastic Recycling Machine Market includes single-stage and multi-stage machines. Single-stage systems are cost-effective and suited for less contaminated plastic waste. Multi-stage machines offer higher efficiency and flexibility for complex and mixed plastic streams, making them preferable for industrial-scale operations.
By Machine Type
Shredder-based machines dominate due to their ability to handle bulky plastic waste. Extruder-based machines are essential for melting and shaping plastic into usable forms. Pelletizer-based systems are widely used for producing uniform plastic pellets. Other machines cater to niche recycling needs and specialty plastics.
By Application / Plastic Type
PET and PE lead the market, driven by demand from packaging. PP and PVC also hold strong positions due to their widespread industrial use. The market supports diverse plastic types, reflecting the complexity of global plastic waste.
By End-Use Industry
Packaging remains the largest end-use segment due to high consumption and recycling mandates. Automotive and construction industries are adopting recycled plastic to meet sustainability targets. Electronics and other industrial sectors are expanding demand for high-quality recycled materials.
Segmentation:
By Type
- Single Stage
- Multi Stage
By Machine Type
- Shredder
- Extruder
- Pelletizer
- Other
By Application / Plastic Type
- Polyethylene Terephthalate (PET)
- Polyvinyl Chloride (PVC)
- Polyethylene (PE)
- Polypropylene (PP)
- Other Plastics
By End-Use Industry
- Packaging
- Automotive
- Construction
- Electronics
- Other Industries
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America Leads in Technological Adoption and Infrastructure
North America holds the largest share of the [ Automatic Plastic Recycling Machine Market], accounting for approximately 34% of global revenue. The region’s advanced waste management systems, strong environmental regulations, and rising investment in sustainable packaging contribute to this lead. The United States and Canada are deploying high-capacity, automated recycling lines to meet federal and state-level recycled-content mandates. Corporate sustainability goals are also driving machine upgrades and system expansions. Equipment manufacturers benefit from a mature industrial base and strong after-sales service networks. These conditions support high adoption rates among both private recycling firms and municipal operations.
Asia-Pacific Emerges as the Fastest-Growing Regional Market
Asia-Pacific represents around 29% of the global market and is projected to experience the highest CAGR during the forecast period. The region is seeing strong momentum from expanding urban populations, industrialization, and increased plastic consumption. China, India, Japan, and Southeast Asian countries are investing in automated recycling technologies to address mounting waste volumes and environmental degradation. Government reforms to upgrade municipal solid waste systems and attract private investment are further supporting market growth. It is positioning itself as a hub for cost-effective, high-volume recycling machine production and deployment. Strong manufacturing capacity and local demand are reinforcing market development.
Europe Maintains Steady Growth Driven by Policy and Innovation
Europe accounts for approximately 21% of the [ Automatic Plastic Recycling Machine Market], backed by strong regulatory alignment under the EU Green Deal and Circular Economy Action Plan. Member states implement strict recycling targets and plastic packaging regulations that favor automation. The region supports innovation in material recovery through public-private partnerships and funding for pilot plants. Germany, France, Italy, and the Netherlands lead in deploying advanced recycling technologies at scale. European recyclers prioritize system efficiency and traceability, adopting smart equipment that enables real-time data tracking and waste auditing. The market remains competitive with a focus on sustainability-driven engineering and low-emission operations.
Key Player Analysis:
- GENIUS MACHINERY
- Polystar Machinery
- Vecoplan
- KOWIN
- Munchy
- Doll Plast
- B+B Anlagenbau
- EREMA
- Sorema
Competitive Analysis:
The Automatic Plastic Recycling Machine Market is highly competitive, with key players focusing on innovation, capacity expansion, and regional diversification to strengthen their market position. Leading companies such as Vecoplan, EREMA Group, Polystar, Amstar Machinery, and KraussMaffei are investing in R&D to enhance machine efficiency, automation, and energy savings. It is characterized by intense rivalry, driven by growing demand for advanced recycling technologies and increasing regulatory pressure on sustainability. Companies are introducing modular, AI-integrated systems that offer flexibility and high throughput to cater to industrial-scale operations. Strategic partnerships and mergers are also shaping the landscape, helping players access new markets and technologies. Local manufacturers in Asia-Pacific are competing on price and customization, targeting small and medium recyclers. The market continues to evolve with an emphasis on digital integration, material traceability, and performance optimization, enabling established and emerging companies to address growing global demand for sustainable plastic processing solutions.
Recent Developments:
- In August 2023, Genius Machinery launched its advanced Plastic Washing Recycling Line for the Latin American market, featuring the Screw Press Dewatering Machine (Squeeze Dryer). According to company documentation, this system ensures that only 3% moisture content remains after drying, significantly improving pelletizing efficiency and final pellet quality for plastic film recycling operations.
- In June 2024, Vecoplan entered a strategic partnership with Pla.to Technology to advance plastic recycling cleaning processes. The partnership combines Vecoplan’s expertise in recyclable material processing with Pla.to’s durable, wear-resistant cleaning systems, providing customers with integrated processing solutions. Company statements emphasize that this collaboration will deliver end-to-end solutions for complex plastic waste streams, enhancing recyclate quality and system reliability.
Market Concentration & Characteristics:
The Automatic Plastic Recycling Machine Market shows moderate to high market concentration, with a mix of global leaders and region-specific manufacturers shaping its structure. It is defined by strong technological differentiation, where innovation in automation, energy efficiency, and output quality determines competitive advantage. Leading companies command significant shares through proprietary technologies and integrated service models. The market favors players with strong R&D capabilities and robust distribution networks. Barriers to entry remain high due to capital intensity and the need for technical expertise. Demand is skewed toward large-scale, automated systems suitable for industrial use, but smaller, modular solutions are gaining attention in developing regions. It continues to evolve with a focus on sustainability, digitalization, and performance reliability.
Report Coverage:
The research report offers an in-depth analysis based on By Type, By Machine Type, By Application / Plastic Type, By End-Use Industry and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for recycled plastics will continue to drive investment in automated recycling technologies across key industrial sectors.
- Regulatory enforcement on waste reduction and recycled content standards will expand market opportunities globally.
- Integration of AI, IoT, and sensor-based technologies will enhance efficiency, sorting accuracy, and machine intelligence.
- Manufacturers will develop modular and scalable systems to serve both large-scale facilities and small regional operators.
- Asia-Pacific will emerge as the primary growth engine due to industrial expansion, population growth, and government reforms.
- Energy-efficient and low-emission machine designs will gain preference amid stricter environmental standards.
- Digital monitoring and predictive maintenance features will become standard to reduce downtime and increase productivity.
- Strategic partnerships and acquisitions will intensify as companies seek to expand technological capabilities and global presence.
- Financing models such as equipment leasing and shared infrastructure will lower entry barriers for small recyclers.
- Consumer and investor pressure on sustainability will reinforce long-term demand for automated recycling solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Automatic Plastic Recycling Machine Market?
What factors are driving the growth of the Automatic Plastic Recycling Machine Market?
What are some challenges faced by the Automatic Plastic Recycling Machine Market?
Who are the major players in the Automatic Plastic Recycling Machine Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automatic Plastic Recycling Machine Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automatic Plastic Recycling Machine Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 299.73 million → 2032: USD 441.8 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automatic Plastic Recycling Machine Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automatic Plastic Recycling Machine Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automatic Plastic Recycling Machine Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automatic Plastic Recycling Machine Market Drivers
- 3.3 Automatic Plastic Recycling Machine Market Restraints & Challenges
- 3.4 Automatic Plastic Recycling Machine Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automatic Plastic Recycling Machine Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automatic Plastic Recycling Machine Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automatic Plastic Recycling Machine category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automatic Plastic Recycling Machine Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Automatic Plastic Recycling Machine Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Automatic Plastic Recycling Machine market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automatic Plastic Recycling Machine Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automatic Plastic Recycling Machine Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Automatic Plastic Recycling Machine Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automatic Plastic Recycling Machine (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Automatic Plastic Recycling Machine Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automatic Plastic Recycling Machine Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Automatic Plastic Recycling Machine Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automatic Plastic Recycling Machine Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automatic Plastic Recycling Machine Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automatic Plastic Recycling Machine Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automatic Plastic Recycling Machine Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automatic Plastic Recycling Machine Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automatic Plastic Recycling Machine Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
