
Market Overview:
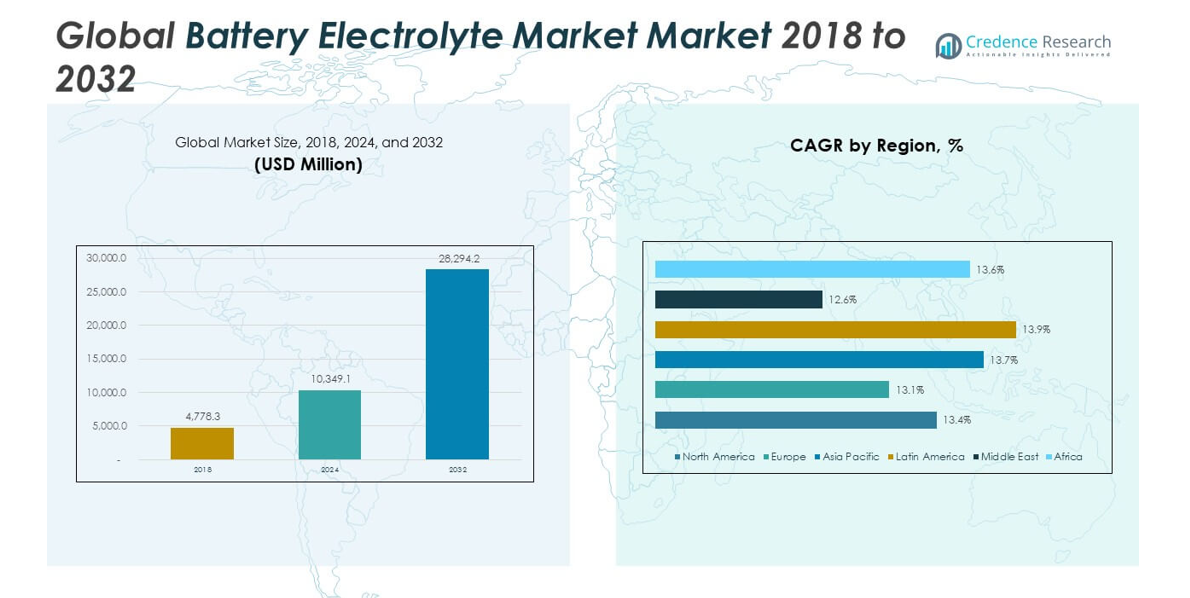
The Global Battery Electrolyte Market size was valued at USD 4,778.3 million in 2018, reached USD 10,349.1 million in 2024, and is anticipated to reach USD 28,294.2 million by 2032, at a CAGR of 13.47% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Battery Electrolyte Market Size 2024 | USD 10,349.1 million |
| Battery Electrolyte Market, CAGR | 13.47% |
| Battery Electrolyte Market Size 2032 | USD 28,294.2 million |
Growing demand for electric vehicles and renewable energy storage systems is driving strong adoption of advanced electrolytes. Lithium-ion technology dominates due to its high energy density and efficiency, while research into solid-state electrolytes is accelerating to overcome safety and performance limitations. Governments worldwide are actively supporting clean energy transitions, which increases investments in energy storage solutions and boosts electrolyte consumption. The rising penetration of portable electronics and industrial battery systems also strengthens long-term growth prospects for the market.
Regionally, Asia-Pacific leads the market with strong manufacturing bases in China, Japan, and South Korea. These countries benefit from established supply chains, high EV adoption, and government incentives for clean energy. North America and Europe are emerging growth hubs, driven by electric mobility adoption, grid modernization, and sustainable energy policies. Meanwhile, regions like Latin America and the Middle East & Africa show potential as infrastructure development and renewable energy projects expand, creating fresh opportunities for battery electrolyte adoption.
Market Insights:
- The Global Battery Electrolyte Market was valued at USD 4,778.3 million in 2018, reached USD 10,349.1 million in 2024, and is projected to hit USD 28,294.2 million by 2032, growing at a CAGR of 13.47%.
- Asia Pacific led the market with a 35.3% share in 2024, driven by China’s large-scale EV adoption and strong manufacturing capacity, followed by North America at 27% and Europe at 21.7% supported by regulations and automotive innovation.
- Latin America emerged as the fastest-growing region with a 9.1% share in 2024, supported by renewable energy integration, EV adoption in Brazil, and growing industrial demand.
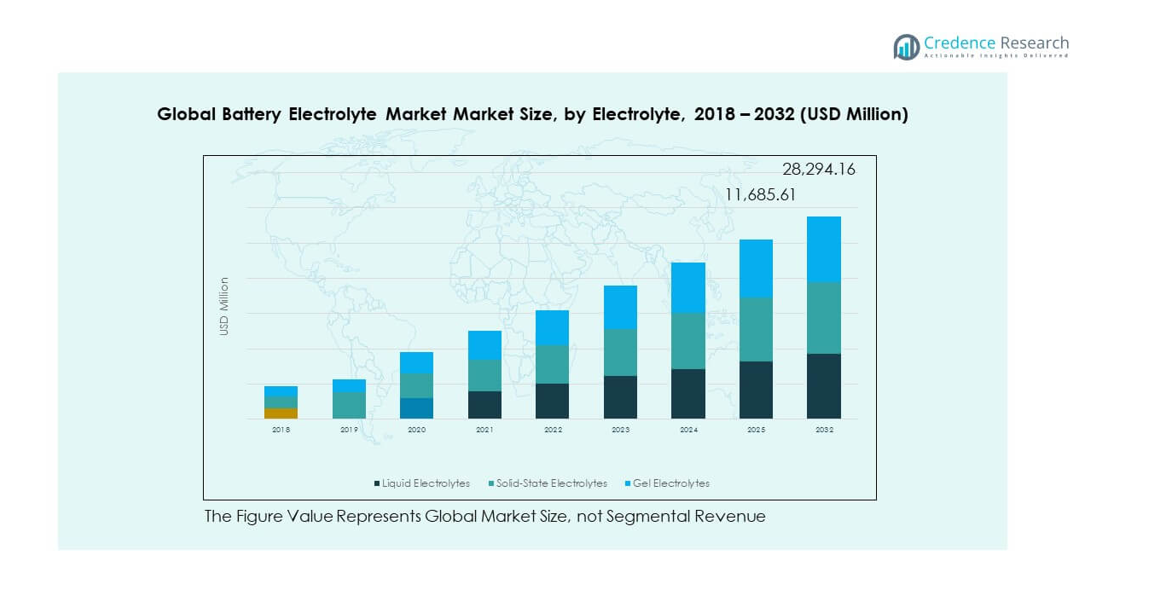
- Liquid electrolytes accounted for nearly 41% of the market in 2024, maintaining dominance due to their extensive use in lithium-ion and lead acid batteries.
- Solid-state electrolytes captured around 34% share in 2024, gaining traction from rising demand for safer, high-performance batteries, while gel electrolytes held the remaining share in niche applications.
Market Drivers:
Rising Adoption of Electric Vehicles Across Global Markets
The automotive industry is witnessing an unprecedented shift toward electrification, creating higher demand for advanced battery electrolytes. Government incentives and stricter emission regulations are accelerating electric vehicle adoption across key economies. The Global Battery Electrolyte Market benefits directly from this shift, as electrolytes play a critical role in battery performance. It gains strong traction from automakers investing in large-scale EV production. Consumers are increasingly choosing electric cars for cost efficiency and environmental benefits. Strong manufacturing ecosystems in Asia-Pacific further support mass production. Growing public charging infrastructure provides confidence for higher EV penetration. This alignment of technology, policy, and consumer preference drives electrolyte demand steadily upward.
- For instance, CATL (Contemporary Amperex Technology Co. Ltd.) announced in April 2025 that its second-generation Shenxing EV battery, an advanced lithium iron phosphate (LFP) battery, enables a driving range of 800 kilometers on a single charge. Mass production for this model was slated to begin later in 2025, with market availability expected in the first quarter of 2026.
Expanding Deployment of Renewable Energy Storage Systems
The integration of renewable energy into grids is transforming the demand landscape for electrolytes. Solar and wind projects require large-scale energy storage to ensure stability and reliability. The Global Battery Electrolyte Market grows as these projects expand, needing durable and efficient battery solutions. It supports the transition toward decentralized and sustainable power systems. Nations are investing heavily in energy storage capacity to meet rising clean energy targets. Industrial and residential storage systems also fuel significant growth momentum. Energy security concerns are pushing adoption of storage batteries in multiple regions. Continuous government funding and corporate investments make energy storage a leading driver of electrolyte consumption.
- For instance, LG Energy Solution has supplied grid-scale lithium-ion battery energy storage systems for several major projects in California. A prominent example is the Edwards & Sanborn project in Kern County, which was fully operational by early 2024 and utilizes batteries from LG Chem and other suppliers to provide over 3 GWh of storage. LG Energy Solution Vertech, a subsidiary, has also announced larger supply deals, including a contract to provide up to 8 GWh of systems to California-based Terra-Gen between 2026 and 2029.
Technological Innovations in Electrolyte Formulations and Designs
Research advancements are unlocking new opportunities in electrolyte materials with improved efficiency. Companies are investing in solid-state electrolytes to enhance safety and energy density. The Global Battery Electrolyte Market evolves as research shifts toward addressing flammability and long charging times. It benefits from breakthroughs that improve conductivity, stability, and overall battery performance. Emerging nanomaterials and advanced polymers create competitive product advantages. Manufacturers are developing solutions for both high-capacity EVs and compact consumer electronics. Technology collaborations among universities and corporations strengthen innovation pipelines. The focus on next-generation battery performance makes advanced formulations central to market expansion.
Growing Consumer Electronics Demand and Portable Device Penetration
The consumer electronics sector continues to drive strong demand for reliable batteries. Smartphones, laptops, and wearables all depend on advanced electrolytes for long battery life. The Global Battery Electrolyte Market benefits from growing digital lifestyles across developed and emerging markets. It secures growth through increasing penetration of IoT devices in daily activities. Portable electronics require lightweight, efficient, and safe electrolytes. Expansion of 5G networks and connected technologies supports larger device adoption. Manufacturers are developing compact electrolytes tailored for personal electronics. Rising consumer expectations for durability and performance sustain a steady demand for battery electrolytes globally.
Market Trends:
Shift Toward Sustainable and Eco-Friendly Electrolyte Solutions
The industry is witnessing rising interest in eco-friendly electrolyte formulations aligned with sustainability goals. Bio-based materials and recyclable components are gaining wider attention among manufacturers. The Global Battery Electrolyte Market adapts to environmental regulations by developing greener alternatives. It reflects a broader push toward low-impact and non-toxic chemical solutions. Governments and consumers are emphasizing eco-conscious production practices. Battery manufacturers are testing biodegradable solvents for reduced environmental risk. Corporate commitments to carbon neutrality also influence research directions. Sustainability-driven product differentiation is becoming a major market trend across regions.
- For instance, BASF and Group14 announced in May 2025 a market-ready silicon anode solution for batteries, and in April 2025, BASF announced the expansion of its Licity® anode binder production in the U.S. to support the sustainable battery materials market. In June 2025, BASF also started the commercial operation of a large-scale black mass plant in Schwarzheide for recycling end-of-life batteries.
Increasing Investments in Solid-State Battery Technologies
Solid-state battery research is advancing rapidly, reshaping expectations for future electrolytes. Leading companies are exploring solid electrolytes to replace liquid-based systems. The Global Battery Electrolyte Market tracks this transition with growing R&D intensity. It anticipates a shift that could improve safety, energy density, and lifecycle performance. Industry leaders are establishing partnerships to accelerate commercialization timelines. Pilot projects and prototype vehicles are showcasing early use cases. Solid-state development also gains momentum through rising venture capital support. This trend positions advanced electrolytes as a cornerstone of next-generation energy solutions.
Diversification of Applications Beyond Automotive and Electronics
The market is expanding into industrial and defense applications with specialized needs. Aerospace and marine industries are investing in advanced storage solutions for efficiency. The Global Battery Electrolyte Market is diversifying, supporting grid stabilization and remote energy access. It expands scope by meeting requirements of specialized sectors with customized electrolytes. Backup power systems and healthcare devices also present rising opportunities. Industrial machinery and robotics rely on reliable storage capabilities. Electrolyte solutions designed for extreme conditions are gaining traction. This diversification strengthens long-term growth potential and reduces overdependence on automotive demand.
Regional Manufacturing Consolidation and Supply Chain Shifts
Production bases are consolidating across regions to ensure resilience against disruptions. Asian economies remain dominant with strong production networks and expertise. The Global Battery Electrolyte Market aligns with regional expansions to meet surging local demand. It responds to geopolitical and economic factors influencing supply chain design. Companies are diversifying sources to mitigate risk from concentrated suppliers. North America and Europe are investing in localized manufacturing hubs. Strategic agreements between suppliers and automakers ensure consistent supply. These structural shifts are shaping a more balanced and resilient market ecosystem.
Market Challenges Analysis:
Concerns Over Raw Material Supply and Price Volatility
The market faces challenges from fluctuating prices of lithium, cobalt, and other raw materials. These elements remain essential for producing electrolytes at scale. The Global Battery Electrolyte Market experiences uncertainty due to supply chain disruptions and geopolitical tensions. It struggles with balancing affordability and sustainability in sourcing strategies. Environmental concerns over mining practices also affect availability and reputation. Price instability impacts the profitability of electrolyte manufacturers. Companies are under pressure to find reliable and ethical suppliers. Long-term planning remains difficult with unpredictable market conditions.
Safety Risks and Regulatory Compliance Pressures
Electrolytes face scrutiny for safety concerns including flammability and leakage risks. These risks affect consumer trust and regulatory requirements globally. The Global Battery Electrolyte Market must adapt to stricter safety standards and testing protocols. It requires continuous R&D to improve safety while maintaining performance. High costs of compliance create barriers for smaller firms. Public awareness of battery safety incidents increases market pressure. Manufacturers are developing safer alternatives like solid-state electrolytes. Achieving broad adoption requires balancing cost, safety, and scalability in production.
Market Opportunities:
Growing Potential in Emerging Markets for Clean Energy Adoption
Developing regions are experiencing a rise in clean energy projects and EV adoption. The Global Battery Electrolyte Market sees opportunities in expanding renewable capacity across Asia, Africa, and Latin America. It aligns with government-backed initiatives to modernize grids and reduce emissions. Rural electrification and urban development projects drive storage requirements. These areas provide scope for strong market penetration. Companies entering early can secure strategic positions in growing economies. Partnerships with local governments and utilities create pathways for long-term growth. Expanding infrastructure provides fertile ground for electrolyte demand.
Advancements in Next-Generation Battery Technologies and Partnerships
Innovations in nanotechnology, polymers, and solid-state systems are reshaping market potential. The Global Battery Electrolyte Market benefits from partnerships between universities, corporations, and start-ups. It supports collaborative ecosystems driving research into safer and more efficient materials. Strategic alliances reduce development costs and accelerate commercialization. Pilot programs in electric mobility and grid storage highlight future use cases. Companies that innovate early gain competitive advantages. The ability to tailor electrolytes for niche applications creates new revenue streams. Opportunities arise from combining advanced science with practical energy solutions.
Market Segmentation Analysis:
By Electrolyte Type
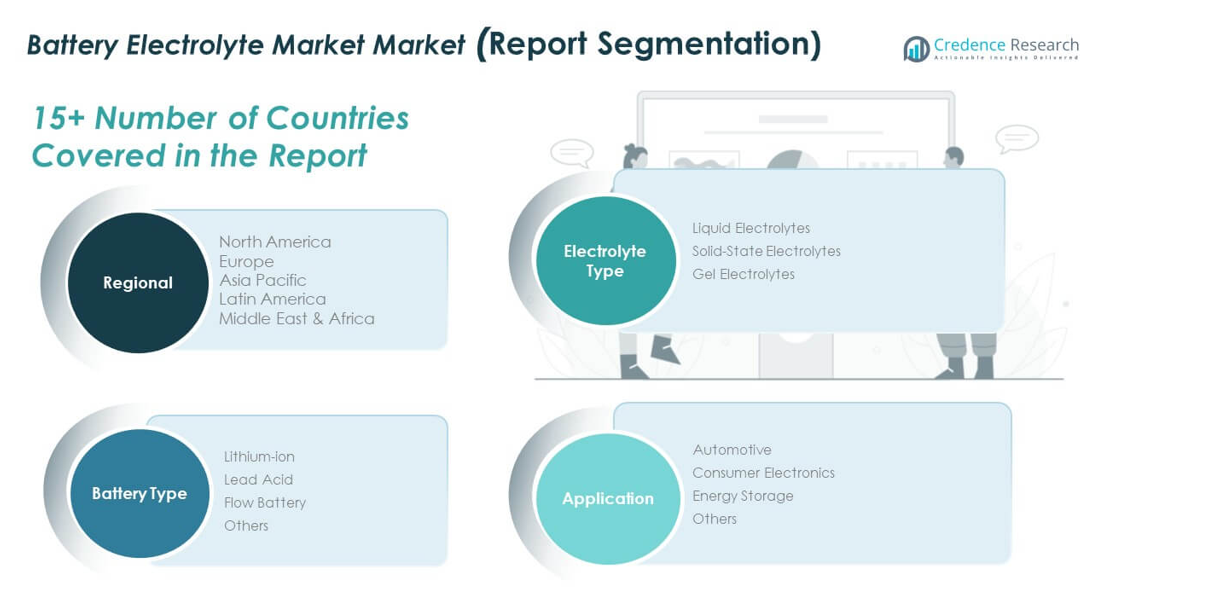
The Global Battery Electrolyte Market is segmented into liquid, solid-state, and gel electrolytes. Liquid electrolytes hold a major share due to their extensive use in lithium-ion and lead acid batteries. It benefits from mature production processes and widespread adoption in automotive and consumer electronics. Solid-state electrolytes are gaining momentum with rising demand for safer and high-energy-density solutions. Their growth is supported by R&D investments and pilot projects in electric vehicles. Gel electrolytes maintain relevance in specialized applications requiring leak-proof and stable performance.
- For instance, Samsung SDI is pursuing all-solid-state battery technology, aiming to begin mass production with a volumetric energy density of up to 900 Wh/L by 2027. In September 2025, the company showcased its new Battery Box products for energy storage systems at the RE+ 2025 trade show.
By Battery Type
The market is categorized into lithium-ion, lead acid, flow batteries, and others. Lithium-ion batteries dominate the segment, supported by strong use in EVs, energy storage, and electronics. The Global Battery Electrolyte Market grows as manufacturers enhance lithium-ion technology with advanced electrolyte formulations. Lead acid batteries retain significance in backup power and industrial uses due to low cost and reliability. Flow batteries show promise for large-scale grid storage, creating a niche growth pathway. Other battery chemistries add diversity, serving specialized and emerging applications.
By Application
The market spans automotive, consumer electronics, energy storage, and other uses. Automotive leads due to strong EV penetration across Asia, Europe, and North America. It accelerates demand for efficient electrolytes that ensure durability and safety. Consumer electronics drive steady growth as smartphones, laptops, and wearables expand globally. Energy storage applications are rising quickly, fueled by renewable integration and grid modernization. Other uses, including defense and healthcare, create tailored demand opportunities for advanced electrolyte solutions.
Segmentation:
By Electrolyte Type
- Liquid Electrolytes
- Solid-State Electrolytes
- Gel Electrolytes
By Battery Type
- Lithium-ion
- Lead Acid
- Flow Battery
- Others
By Application
- Automotive
- Consumer Electronics
- Energy Storage
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Battery Electrolyte Market size was valued at USD 1,310.20 million in 2018 to USD 2,827.98 million in 2024 and is anticipated to reach USD 7,696.01 million by 2032, at a CAGR of 13.4% during the forecast period. North America accounts for nearly 27% share of the Global Battery Electrolyte Market in 2024. The region benefits from strong electric vehicle adoption, driven by government incentives and tightening emission standards. It also gains support from renewable integration and modern grid infrastructure, which increases energy storage deployment. Major technology firms and battery producers in the U.S. fuel innovation and commercialization of advanced electrolytes. Consumer electronics demand further strengthens growth across Canada and Mexico. The region’s strong focus on sustainability attracts investments in solid-state and next-generation electrolyte technologies. Strategic partnerships between automakers and electrolyte suppliers provide long-term stability. Growth momentum continues with high EV penetration and renewable energy expansion.
Europe
The Europe Battery Electrolyte Market size was valued at USD 1,056.47 million in 2018 to USD 2,243.40 million in 2024 and is anticipated to reach USD 5,970.07 million by 2032, at a CAGR of 13.1% during the forecast period. Europe represents about 21.7% share of the Global Battery Electrolyte Market in 2024. The region is advancing with strong EV adoption supported by climate policies and subsidies. Germany, France, and the UK remain leading contributors through robust automotive manufacturing and R&D initiatives. It gains growth from energy transition projects and rising renewable storage capacities. Regulatory frameworks, such as the EU Green Deal, encourage sustainable battery development and electrolyte innovation. Growing demand in consumer electronics adds to the regional expansion. The presence of global automakers and material innovators ensures technological leadership. Europe remains a critical hub for advanced electrolyte adoption in clean energy mobility.
Asia Pacific
The Asia Pacific Battery Electrolyte Market size was valued at USD 1,661.88 million in 2018 to USD 3,648.66 million in 2024 and is anticipated to reach USD 10,154.77 million by 2032, at a CAGR of 13.7% during the forecast period. Asia Pacific commands nearly 35.3% share of the Global Battery Electrolyte Market in 2024, making it the largest regional contributor. China leads with massive EV production and energy storage investments, supported by government subsidies and industrial policy. Japan and South Korea play a major role with innovations in lithium-ion and solid-state electrolyte research. India shows rapid growth potential due to rising EV sales and renewable expansion. The region benefits from strong supply chain integration and large-scale battery manufacturing capacity. It also maintains cost competitiveness in raw materials and production. Consumer electronics growth across Asia enhances steady electrolyte consumption. The region secures long-term leadership through technology, scale, and demand growth.
Latin America
The Latin America Battery Electrolyte Market size was valued at USD 425.74 million in 2018 to USD 946.06 million in 2024 and is anticipated to reach USD 2,673.80 million by 2032, at a CAGR of 13.9% during the forecast period. Latin America accounts for nearly 9.1% share of the Global Battery Electrolyte Market in 2024. Brazil drives most of the demand with strong renewable energy projects and rising EV adoption. Mexico and Argentina add growth through automotive assembly and consumer electronics penetration. The region’s abundant natural resources support long-term opportunities in battery manufacturing. It benefits from growing government focus on sustainable mobility and clean energy. Energy storage systems for grid stability create rising demand for advanced electrolytes. It faces challenges in supply chain and infrastructure development, but opportunities remain strong. Latin America continues to emerge as a promising market for global players investing in early expansion.
Middle East
The Middle East Battery Electrolyte Market size was valued at USD 228.40 million in 2018 to USD 474.29 million in 2024 and is anticipated to reach USD 1,222.31 million by 2032, at a CAGR of 12.6% during the forecast period. The region holds nearly 4.5% share of the Global Battery Electrolyte Market in 2024. The Middle East is adopting advanced energy storage to complement solar and renewable initiatives. GCC nations lead in deploying storage systems to stabilize large renewable power plants. It benefits from government-led investments in sustainable infrastructure and smart city projects. Israel contributes with innovations in battery research and material technologies. Demand in the automotive sector remains smaller but is gradually increasing. The oil-rich economies are diversifying into renewable energy and clean mobility. It creates scope for electrolyte adoption in grid storage and industrial applications. The region remains in a development phase but is steadily gaining traction.
Africa
The Africa Battery Electrolyte Market size was valued at USD 95.57 million in 2018 to USD 208.76 million in 2024 and is anticipated to reach USD 577.20 million by 2032, at a CAGR of 13.6% during the forecast period. Africa contributes nearly 2% share of the Global Battery Electrolyte Market in 2024. Growth is supported by renewable energy projects aimed at addressing power shortages. South Africa leads with strong solar and wind adoption coupled with grid storage systems. Egypt and Nigeria are emerging with rising interest in energy diversification. It benefits from increasing investments by global firms targeting rural electrification and off-grid solutions. Demand in automotive and consumer electronics remains limited but is gradually expanding. Rising urbanization creates opportunities for storage in infrastructure and housing sectors. Strategic partnerships with international technology firms help accelerate development. Africa is building a steady growth pathway supported by renewable integration and development needs.
Key Player Analysis:
- UBE Industries Ltd.
- Guangzhou Tinci Materials Technology Co. Ltd.
- Mitsubishi Chemical Holdings Corporation
- Targray Industries Inc.
- Shenzhen Capchem Technology Co. Ltd.
- NEI Corporation
- Advanced Electrolyte Technologies, LLC
- Solvay SA
- Enchem Co. Ltd.
- Capchem
- Other Key Players
Competitive Analysis:
The Global Battery Electrolyte Market is highly competitive, with established chemical companies, specialized electrolyte producers, and emerging technology firms competing for market share. It is characterized by continuous investment in R&D to improve electrolyte safety, conductivity, and energy density. Key players focus on expanding product portfolios and forming partnerships with battery manufacturers to secure long-term contracts. Regional leaders maintain cost advantages through integrated supply chains, while global firms emphasize innovation and sustainability. The market is also witnessing new entrants targeting solid-state and advanced polymer electrolytes. Intense price competition and technological advancements define the current competitive dynamics.
Recent Developments:
- In May 2025, Shenzhen Capchem Technology Co. Ltd. debuted a new electrolyte additive for lithium-ion batteries, which demonstrated a 15% enhancement in cycle stability during independent laboratory testing.
- In February 2025, UBE Industries Ltd. broke ground on a new $500 million manufacturing facility in Louisiana designed to produce key components of lithium-ion battery electrolytes, specifically dimethyl carbonate (DMC) and ethyl methyl carbonate (EMC), aimed to boost the domestic EV battery supply chain in the United States.
- In June 2024, Guangzhou Tinci Materials Technology Co. Ltd. received a large order from CATL to supply lithium battery electrolytes through the end of 2025, supporting CATL’s aggressive expansion in electric vehicle battery manufacturing.
Report Coverage:
The research report offers an in-depth analysis based on electrolyte type, battery type, and application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising EV adoption will accelerate demand for advanced electrolytes.
- Solid-state electrolytes will move closer to commercialization.
- Energy storage deployment will fuel growth in renewable projects.
- Consumer electronics will sustain steady electrolyte consumption.
- Asia Pacific will strengthen its leadership through scale and innovation.
- Europe will advance sustainable battery initiatives under strict regulations.
- North America will expand production with localized supply chains.
- Strategic alliances will drive product innovation and commercialization.
- Supply chain diversification will reduce dependency on key regions.
- Sustainability-driven solutions will create new growth opportunities.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is driving the growth of the Battery Electrolyte Market?
What is the projected market value of the Battery Electrolyte Market by 2032?
At what Compound Annual Growth Rate is the Global Battery Electrolyte Market projected to grow between 2025 and 2032?
Which regions are expected to dominate the Battery Electrolyte Market?
What innovations are occurring in battery electrolyte formulations?
How does the transition to sustainable energy sources impact the Battery Electrolyte Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 4,778.3 million → 2032: USD 28,294.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Battery Electrolyte Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Battery Electrolyte Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Battery Electrolyte Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Battery Electrolyte Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Battery Electrolyte Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Battery Electrolyte Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Battery Electrolyte Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Battery Electrolyte Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 4,778.3 million → 2032: USD 28,294.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Battery Electrolyte Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Battery Electrolyte Geographic Market Outlook, 2018-2032
- 13.1 Regional Market Size and Share, 2018
- 13.2 Regional Market Forecast, 2018-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Battery Electrolyte Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2018-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Battery Electrolyte Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2018
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2018-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
