
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Biomaterials Market Size 2024 | USD 2,03,827.80 million |
| Biomaterials Market CAGR | 14.91% |
| Biomaterials Market Size 2032 | USD 6,19,828.57 million |
Market Overview
Global Biomaterials market size was valued at USD 2,03,827.80 million in 2024 and is anticipated to reach USD 6,19,828.57 million by 2032, at a CAGR of 14.91% during the forecast period (2024-2032).
The global biomaterials market is driven by increasing advancements in medical technologies, growing demand for innovative healthcare solutions, and the rising prevalence of chronic diseases. As healthcare systems prioritize better treatments, biomaterials play a critical role in tissue engineering, drug delivery, and implants, propelling market growth. The aging population and the need for prosthetics and orthopedic implants further fuel the market demand. Moreover, the rapid development of bioresorbable materials, which eliminate the need for surgical removal, and the growing focus on sustainability in medical products are key trends. Additionally, the rise in personalized medicine and the growing adoption of 3D printing technology for custom biomaterial applications are shaping the future of the market. With continuous innovations in material science and an expanding healthcare sector, the biomaterials market is poised for substantial growth in the coming years.
The geographical analysis of the global biomaterials market reveals strong growth across North America, Europe, Asia-Pacific, and Latin America, driven by regional advancements in healthcare infrastructure, rising patient awareness, and technological innovation. North America and Europe remain key innovation hubs with extensive R&D activities and established regulatory systems, while Asia-Pacific is rapidly emerging due to increasing healthcare investments, a growing aging population, and expanding medical tourism. Latin America and the Middle East & Africa are steadily advancing with improvements in healthcare access and supportive government initiatives. Leading industry players shaping the global biomaterials landscape include BASF SE, Victrex Plc, Covestro AG, Celanese Corporation, and Evonik Industries AG. These companies are focused on product innovation, strategic partnerships, and geographic expansion to enhance their market presence and meet rising demand across applications such as orthopedics, cardiovascular care, dentistry, and regenerative medicine. Their efforts contribute significantly to the market’s continuous evolution and competitive dynamics.
Market Insights
- The global biomaterials market was valued at USD 2,03,827.80 million in 2024 and is projected to reach USD 6,19,828.57 million by 2032, growing at a CAGR of 14.91% during the forecast period.
- Rising demand for advanced implantable devices and tissue engineering applications is driving market growth across healthcare sectors.
- Increasing adoption of natural and polymer-based biomaterials is shaping key market trends, especially in regenerative medicine and drug delivery systems.
- Leading players such as BASF SE, Victrex Plc, and Evonik Industries AG are focusing on innovation, partnerships, and regional expansion to stay competitive.
- High production costs and strict regulatory approval processes remain major market restraints, affecting smaller manufacturers and new entrants.
- North America and Europe continue to dominate due to their advanced healthcare systems and strong R&D infrastructure.
- Asia-Pacific is emerging as a key growth region, supported by expanding healthcare infrastructure and rising medical tourism.
Report Scope
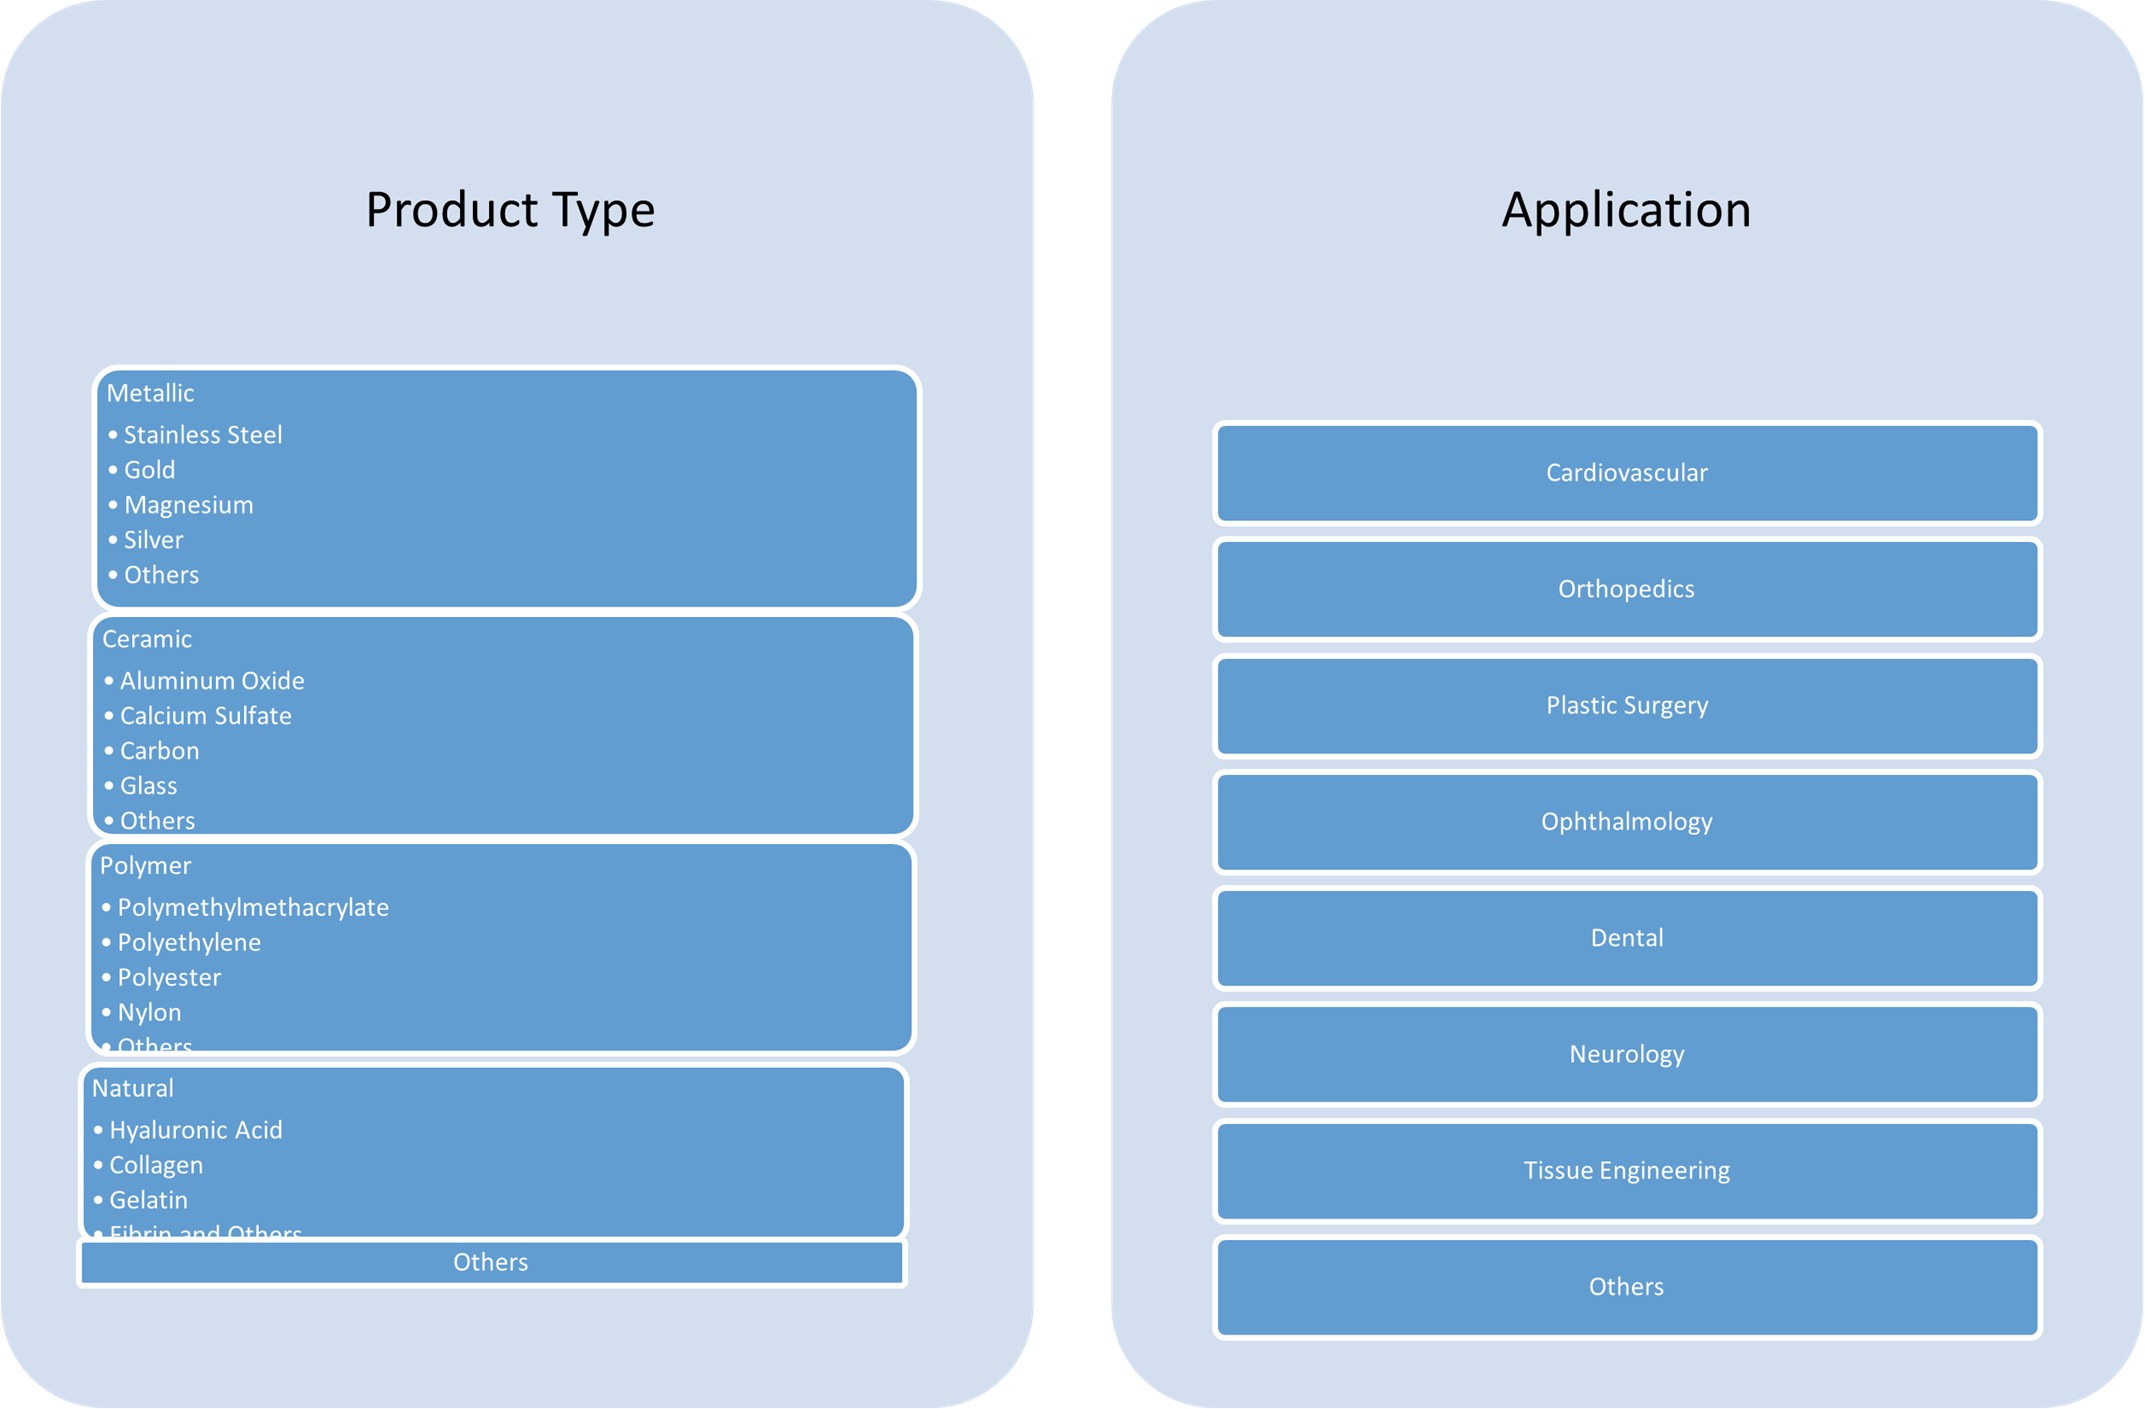
This report segments the Global Biomaterials Market as follows:
Market Drivers
Advancements in Medical Technology
The rapid advancements in medical technology have significantly contributed to the growth of the global biomaterials market. For instance, the biomaterials market is evolving with innovations such as 3D printing, regenerative medicine, and minimally invasive surgeries. These technologies require materials that can support complex biological functions, promote healing, and improve the longevity of implants. The development of smart biomaterials that respond to external stimuli, such as temperature and pH, is another example of how advancements in technology are shaping the biomaterials sector. These innovations are enabling the creation of highly tailored medical devices and implants, which is boosting the market as the healthcare industry seeks more efficient, precise, and customizable solutions.
Rising Prevalence of Chronic Diseases
The increasing incidence of chronic diseases, such as cardiovascular diseases, diabetes, and musculoskeletal disorders, is another key driver for the biomaterials market. As the global population ages, the demand for medical interventions like implants, prosthetics, and tissue-engineered products continues to rise. Biomaterials are essential in creating devices that replace or support damaged tissues and organs, improving patients' quality of life. For instance, orthopedic implants, including joint replacements and spinal devices, rely heavily on biomaterials like titanium and polymers. This growing need for long-term medical solutions to manage chronic conditions is fueling the demand for biomaterials, thus expanding the market.
Increased Focus on Regenerative Medicine
Regenerative medicine is one of the most promising fields in healthcare, and it is significantly driving the demand for biomaterials. For instance, regenerative medicine is expanding rapidly, with biomaterials playing a crucial role in tissue engineering and stem cell applications. Biomaterials are essential in this field, providing scaffolds that support tissue regeneration and growth. With the increasing success of regenerative treatments for conditions such as burns, chronic wounds, and organ failure, the market for biomaterials used in these applications is rapidly expanding. Moreover, advancements in gene therapy and cell-based treatments further increase the reliance on specialized biomaterials to support the complex interactions between cells, tissues, and implanted devices.
Growing Demand for Sustainable Solutions
Sustainability is becoming an increasingly important focus in healthcare, and the biomaterials market is no exception. With growing concerns about environmental impact, the healthcare industry is seeking more eco-friendly materials that can reduce waste and improve recyclability. Biomaterials, especially those derived from natural sources, such as collagen, chitosan, and silk proteins, are gaining popularity for their biodegradability and biocompatibility. The shift towards sustainable biomaterials is not only driven by environmental concerns but also by the need for safer, less toxic materials for patients. The development of bioresorbable materials that naturally degrade in the body without the need for surgical removal is a key trend that aligns with these sustainability efforts. As consumers and healthcare providers increasingly prioritize environmental responsibility, the demand for sustainable biomaterials continues to rise, positioning the market for long-term growth.
Market Trends
Rise of Bioabsorbable and Biodegradable Materials
One of the most significant trends in the global biomaterials market is the growing adoption of bioabsorbable and biodegradable materials. These materials, which naturally break down in the body over time, eliminate the need for secondary surgeries to remove implants. For instance, bioabsorbable polymers like polylactic acid (PLA) and polyglycolic acid (PGA) are increasingly used in sutures, stents, and drug delivery systems. This trend is driven by the advantages of reducing patient recovery time and minimizing risks associated with long-term foreign body presence. As researchers continue to innovate in this area, the development of new biodegradable materials for more complex medical applications is expected to expand rapidly.
Integration of 3D Printing in Biomaterial Manufacturing
The integration of 3D printing technology into the biomaterials sector is revolutionizing the way medical devices and implants are designed and produced. 3D printing allows for the creation of highly customized products tailored to the specific needs of individual patients, particularly in orthopedics and prosthetics. For instance, 3D printing is revolutionizing biomaterials manufacturing by enabling highly customized implants and scaffolds for tissue engineering. As 3D printing technology advances, it is becoming more efficient, cost-effective, and capable of producing intricate, patient-specific devices with improved functionality. This trend is expected to drive the market as demand for personalized and precise medical solutions increases.
Growth of Tissue Engineering Applications
Tissue engineering is rapidly gaining traction as an innovative and transformative approach to treating various medical conditions. By combining biomaterials with living cells, this field aims to regenerate or replace damaged tissues and organs. Biomaterials used in tissue engineering act as scaffolds, providing structural support for cell growth and guiding tissue formation. The trend toward more effective tissue engineering solutions is driven by the increasing need for organ transplants, the limitations of donor organ availability, and advancements in stem cell research. As techniques improve, the market for biomaterials used in tissue engineering, particularly in areas such as skin, bone, and cartilage regeneration, is expected to expand significantly.
Increasing Focus on Natural and Sustainable Materials
Another prominent trend in the biomaterials market is the increasing focus on natural and sustainable materials. As the healthcare industry faces growing pressure to reduce its environmental impact, there is a notable shift toward biomaterials derived from natural sources, such as plant-based polymers, proteins, and ceramics. These materials not only offer biodegradability and reduced toxicity but also align with the broader trend of sustainability in the medical sector. Natural biomaterials, such as collagen, chitosan, and silk proteins, are being used for various applications, from wound healing to drug delivery. This trend toward sustainability is further supported by consumer demand for eco-friendly products, regulatory incentives, and research into new, environmentally responsible materials. As demand for these materials rises, they are expected to play an increasingly important role in shaping the future of the biomaterials market.
Market Challenges Analysis
High Cost of Development and Manufacturing
One of the primary challenges facing the global biomaterials market is the high cost associated with the development and manufacturing of advanced biomaterials. For instance, the production of high-performance biomaterials requires specialized equipment and extensive testing, contributing to elevated costs. These factors contribute to elevated production costs, which can limit the accessibility of these materials, especially in emerging markets. Furthermore, the long and costly regulatory approval processes for medical devices that incorporate biomaterials add another layer of financial burden. As a result, companies in the biomaterials sector must balance innovation with cost-effectiveness to remain competitive while meeting stringent regulatory standards.
Biocompatibility and Safety Concerns
Biocompatibility and safety concerns remain a significant challenge in the biomaterials market. While advancements have been made in improving the performance of biomaterials, ensuring their compatibility with human tissues and minimizing adverse reactions continues to be a critical issue. The risk of inflammatory responses, allergic reactions, and long-term health complications can limit the adoption of certain biomaterials in medical applications. Moreover, the long-term behavior of biomaterials, especially those that remain implanted in the body for extended periods, remains a key area of research. Developing materials that offer consistent performance, minimal risk, and enhanced safety over time is crucial for market growth, yet remains an ongoing challenge for manufacturers and researchers.
Market Opportunities
The global biomaterials market offers significant opportunities driven by the increasing demand for advanced medical solutions and the ongoing advancements in material science. One of the most promising opportunities lies in the growing demand for regenerative medicine and tissue engineering. As the prevalence of chronic diseases and age-related conditions rises, there is an increasing need for biocompatible materials that can aid in the regeneration of tissues and organs. The ability of biomaterials to provide scaffolding for tissue growth opens doors for innovations in personalized medicine, allowing for customized solutions tailored to individual patient needs. Additionally, the continuous evolution of 3D printing technologies further enhances the potential for biomaterials in creating bespoke implants and devices, reducing the need for off-the-shelf solutions and improving patient outcomes.
Another significant opportunity in the biomaterials market is the rising focus on sustainable and eco-friendly materials. As the healthcare sector increasingly prioritizes environmental responsibility, there is a growing demand for biomaterials that are biodegradable and made from renewable resources. This trend is driving the development of natural and bio-based materials, such as those derived from plants and animals, that offer reduced toxicity and environmental impact. These materials not only meet sustainability requirements but also address the consumer and regulatory push for greener medical products. As research into bioresorbable materials progresses, the biomaterials market is poised to benefit from a shift toward sustainable practices, providing new opportunities for innovation and growth.
Market Segmentation Analysis:
By Product Type:
The global biomaterials market, segmented by product type, demonstrates significant diversity, catering to a wide range of biomedical applications. Metallic biomaterials hold a prominent share due to their strength and durability, with stainless steel, gold, magnesium, and silver being widely used in orthopedic and cardiovascular devices. These metals exhibit excellent mechanical properties and biocompatibility, making them ideal for load-bearing implants. Ceramic biomaterials, including aluminum oxide, calcium sulfate, carbon, and glass, are highly favored for their inert nature and wear resistance, especially in dental and orthopedic applications. Polymers such as polymethylmethacrylate (PMMA), polyethylene, polyester, and nylon are extensively utilized for their flexibility, moldability, and compatibility with human tissues. Natural biomaterials, including hyaluronic acid, collagen, gelatin, and fibrin, are gaining traction due to their superior biocompatibility and biodegradability, which are critical in tissue engineering and wound healing. The growing emphasis on regenerative medicine and bioresorbable implants continues to propel the demand across all biomaterial types, with ongoing innovation further expanding application potential.
By Application:
In terms of application, the biomaterials market is primarily driven by the rising adoption in cardiovascular and orthopedic treatments. Cardiovascular applications dominate the market, supported by the increasing prevalence of heart diseases and the demand for advanced stents, grafts, and pacemaker components made from biocompatible materials. Orthopedic applications closely follow, owing to the aging population and the subsequent surge in joint replacement surgeries that utilize metallic and polymer-based biomaterials. Plastic surgery and ophthalmology represent rapidly expanding segments, driven by technological advancements and a growing preference for minimally invasive procedures. Dental applications continue to see steady growth, with ceramic and polymer materials frequently used in prosthetics and restorations. Neurology and tissue engineering are emerging as high-growth areas, spurred by breakthroughs in nerve regeneration and stem cell integration. The “others” category, encompassing drug delivery systems and wound care, is also gaining momentum as the therapeutic versatility of biomaterials becomes increasingly recognized across a broader range of medical disciplines.
Segments:
Based on Product Type:
- Metallic
- Stainless Steel
- Gold
- Magnesium
- Silver
- Others
- Ceramic
- Aluminum Oxide
- Calcium Sulfate
- Carbon
- Glass
- Others
- Polymer
- Polymethylmethacrylate
- Polyethylene
- Polyester
- Nylon
- Others
- Natural
- Hyaluronic Acid
- Collagen
- Gelatin
- Fibrin and others
- Others
Based on Application:
- Cardiovascular
- Orthopedics
- Plastic Surgery
- Ophthalmology
- Dental
- Neurology
- Tissue Engineering
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America held the largest share of the global biomaterials market in 2024, accounting for approximately 38% of the total revenue. This dominance can be attributed to the region’s advanced healthcare infrastructure, high healthcare spending, and strong presence of leading market players. The United States, in particular, leads the regional growth due to its robust investment in biomedical research, high incidence of chronic diseases, and increasing adoption of implantable devices. Government initiatives, such as funding through the National Institutes of Health (NIH), continue to promote innovation in biomaterials for medical applications. Furthermore, the presence of well-established regulatory frameworks ensures the safe and accelerated introduction of new biomaterial-based products, enhancing the region's market attractiveness.
Europe
Europe represented the second-largest share of the biomaterials market, contributing around 29% of the global revenue in 2024. The region benefits from strong academic and industrial collaboration, a well-developed regulatory system, and growing demand for orthopedic, dental, and cardiovascular biomaterial applications. Countries such as Germany, the UK, and France are at the forefront of biomaterials adoption, driven by increasing geriatric populations and rising cases of degenerative bone diseases. Moreover, substantial investments in regenerative medicine and biotechnology projects, along with supportive healthcare reimbursement policies, are strengthening the market landscape across Europe. Innovation hubs and research centers across the continent continue to foster product development and commercialization in emerging biomaterials.
Asia-Pacific
Asia-Pacific captured a market share of approximately 21%, positioning it as one of the fastest-growing regions in the global biomaterials space. The region's rapid expansion is fueled by rising healthcare expenditures, growing awareness of advanced treatment options, and a significantly increasing elderly population. China, Japan, South Korea, and India are leading contributors due to government investments in healthcare infrastructure and the expansion of medical tourism. In addition, local manufacturing capabilities and lower operational costs have attracted multinational companies to set up production bases in the region. With rising chronic disease prevalence and favorable regulatory support, Asia-Pacific is expected to witness strong growth over the forecast period.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa collectively accounted for around 12% of the market in 2024. While smaller in comparison, these regions are showing steady growth due to improving healthcare access, urbanization, and economic development. In Latin America, Brazil and Mexico are emerging as key markets, supported by increasing demand for orthopedic and dental implants. In the Middle East & Africa, government-led healthcare initiatives, particularly in the Gulf Cooperation Council (GCC) countries and South Africa, are enhancing the market outlook. Though market penetration remains limited due to economic and infrastructure challenges, rising investments in healthcare and partnerships with global suppliers are paving the way for gradual expansion in these regions.
Key Player Analysis
- BASF SE
- Victrex Plc
- Covestro AG
- Celanese Corporation
- Evonik Industries AG
Competitive Analysis
The global biomaterials market is characterized by intense competition, with leading players focusing on innovation, strategic collaborations, and regional expansion to strengthen their market positions. Key players in this space include BASF SE, Victrex Plc, Covestro AG, Celanese Corporation, and Evonik Industries AG. These companies possess strong R&D capabilities and diverse product portfolios that allow them to meet the evolving needs of medical and healthcare sectors, particularly in orthopedics, cardiovascular applications, and tissue engineering. To maintain a competitive edge, these firms are heavily investing in the development of high-performance, biocompatible materials such as biodegradable polymers, advanced ceramics, and metal-based biomaterials. Collaborations with research institutions and healthcare providers enable them to bring innovative solutions to market more rapidly. Additionally, strategic mergers, acquisitions, and partnerships help expand their geographic footprint and technological expertise. These companies also emphasize sustainability and regulatory compliance, positioning themselves as reliable suppliers in an increasingly quality-driven market environment.
Recent Developments
- In April 2025,BASF expanded its EcoBalanced portfolio for Care Chemicals in North America, introducing the first EcoBalanced personal care products in the region. These include Dehyton® PK 45 and Dehyton® KE UP, both certified as EcoBalanced grades using a biomass balance (BMB) approach to reduce carbon footprint. Additionally, six U.S. Care Chemicals production sites are now powered entirely by renewable electricity, saving approximately 33,000 tons of CO₂ annually.
- In November 2024, Covestro began production of Desmophen® CQ NH, a partially bio-based polyaspartic resin (at least 25% bio-based content), at its Foshan, China site. The facility is powered entirely by renewable energy, and the product is used in wind turbine and flooring coatings, supporting both local supply and sustainability goals.
- In January 2025, BASF’sPerformance Materials division transitioned all European sites to 100% renewable electricity, covering engineering plastics, polyurethanes, thermoplastic polyurethanes, and specialty polymers.
- In June 2023,Invibio announced a collaboration with Paragon Medical to scale up manufacturing of PEEK-OPTIMA Ultra-Reinforced composite trauma devices in China, responding to growing global demand for high-performance biomaterials in trauma fixation.
- In February 2023, Celaneseintroduced ECO-B, more sustainable versions of Acetyl Chain materials, incorporating mass balance bio-content to provide chemically identical, bio-based alternatives for engineered materials.
Market Concentration & Characteristics
The global biomaterials market exhibits a moderately concentrated structure, with a few dominant players accounting for a significant portion of market revenue. These companies maintain a strong presence through extensive product portfolios, robust research and development initiatives, and global distribution networks. The market is characterized by high entry barriers due to stringent regulatory requirements, substantial capital investments, and the need for advanced technological capabilities. Innovation plays a critical role, as continuous advancements in material science drive product differentiation and competitive advantage. Furthermore, the market demonstrates high demand elasticity, as biomaterials are integral to a wide range of medical applications including orthopedics, cardiovascular treatments, and regenerative medicine. Strategic collaborations between manufacturers, healthcare providers, and research institutions are common, fostering the rapid development and adoption of next-generation biomaterials. Overall, the market reflects a dynamic and innovation-intensive environment where key players compete on the basis of quality, performance, biocompatibility, and regulatory compliance.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for biomaterials will continue to grow as healthcare needs evolve globally, especially in regenerative medicine.
- Advancements in nanotechnology will lead to the development of more precise and efficient biomaterials for medical devices and implants.
- Biodegradable and biocompatible materials will see increased use in surgical applications, reducing long-term health risks.
- The rise of personalized medicine will drive the demand for tailored biomaterials that suit individual patient profiles.
- 3D printing technologies will revolutionize the fabrication of custom biomaterials for prosthetics and implants.
- There will be an increasing focus on sustainable biomaterials sourced from natural or renewable resources.
- Smart biomaterials, capable of responding to external stimuli, will gain traction in drug delivery and wound healing applications.
- Regulatory frameworks will continue to evolve to accommodate new biomaterials, ensuring safety and efficacy.
- Collaborative research between materials scientists, medical professionals, and engineers will accelerate innovation in biomaterial development.
- Emerging markets, particularly in Asia and Africa, will contribute significantly to the global biomaterials market growth due to increasing healthcare investments.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advancements in Medical Technology
Rapid innovation in medical technologies, such as 3D printing, regenerative medicine, and minimally invasive surgeries, is increasing the demand for advanced biomaterials that can support complex biological functions and improve patient outcomes.
Rising Prevalence of Chronic Diseases
The global increase in chronic conditions like cardiovascular diseases, diabetes, and musculoskeletal disorders is driving the need for implants, prosthetics, and tissue-engineered products, all of which rely heavily on biomaterials.
Increased Focus on Regenerative Medicine
Growth in regenerative medicine and tissue engineering is fueling demand for biomaterials that serve as scaffolds for tissue growth and repair, especially as stem cell and gene therapies become more prevalent.
Growing Demand for Sustainable Solutions
Healthcare providers and regulators are prioritizing eco-friendly, biodegradable, and bioresorbable biomaterials to reduce environmental impact and improve patient safety, driving innovation and adoption in the market.
Integration of 3D Printing Technology
The adoption of 3D printing in biomaterial manufacturing enables the production of highly customized implants and devices, meeting the rising demand for personalized medical solutions and accelerating market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Biomaterials?
What factors are driving the growth of the Global Biomaterials?
What are the key segments within the Global Biomaterials?
What are some challenges faced by the Global Biomaterials?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Cardiovascular
- 1.2.2 Orthopedics
- 1.2.3 Plastic Surgery
- 1.2.4 Ophthalmology
- 1.2.5 Dental
- 1.2.6 Neurology
- 1.2.7 Tissue Engineering
- 1.2.8 Others
- 1.3 By Product Type
- 1.3.1 Metallic (Stainless Steel, Gold, Magnesium, Silver, Others)
- 1.3.2 Ceramic (Aluminum Oxide, Calcium Sulfate, Carbon, Glass, Others)
- 1.3.3 Polymer (Polymethylmethacrylate, Polyethylene, Polyester, Nylon, Others)
- 1.3.4 Natural (Hyaluronic Acid, Collagen, Gelatin, Fibrin and others)
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 203,827.80 million → 2032: USD 6,19,828.57 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Biomaterials Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Biomaterials Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Biomaterials Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Biomaterials Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Biomaterials Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Biomaterials Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Biomaterials Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Biomaterials Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 203,827.80 million → 2032: USD 6,19,828.57 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Biomaterials Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cardiovascular
- 12.3.7.2 Orthopedics
- 12.3.7.3 Plastic Surgery
- 12.3.7.4 Ophthalmology
- 12.3.7.5 Dental
- 12.3.7.6 Neurology
- 12.3.7.7 Tissue Engineering
- 12.3.7.8 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Metallic (Stainless Steel, Gold, Magnesium, Silver, Others)
- 12.4.7.2 Ceramic (Aluminum Oxide, Calcium Sulfate, Carbon, Glass, Others)
- 12.4.7.3 Polymer (Polymethylmethacrylate, Polyethylene, Polyester, Nylon, Others)
- 12.4.7.4 Natural (Hyaluronic Acid, Collagen, Gelatin, Fibrin and others)
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Biomaterials End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Biomaterials Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Biomaterials Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Biomaterials Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Victrex Plc
- 18.4 Covestro AG
- 18.5 Celanese Corporation
- 18.6 Evonik Industries AG
- 18.7 Invibio Ltd.
- 18.8 DSM Biomedical
- 18.9 Corbion N.V.
- 18.10 Zimmer Biomet
- 18.11 Stryker Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

