
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Biomaterials Market Size 2023 | USD 1,902.70 million |
| Australia Biomaterials Market, CGR | 15.66% |
| Australia Biomaterials Market Size 2032 | USD 6,091.98 million |
Market Overview
Australia Biomaterials market size was valued at USD 1,902.70 million in 2024 and is anticipated to reach USD 6,091.98 million by 2032, at a CAGR of 15.66% during the forecast period (2024-2032).
The Australian biomaterials market is driven by the growing demand for biocompatible materials in healthcare applications, including implants, prosthetics, and medical devices. Increasing investments in research and development, coupled with advancements in biotechnology and materials science, are fostering innovation in biomaterial products. Additionally, the rising prevalence of chronic diseases and an aging population are contributing to the need for advanced medical solutions, boosting demand for biomaterials. Sustainability concerns are also pushing for eco-friendly alternatives in manufacturing, further fueling market growth. The trend toward personalized medicine and the development of biodegradable biomaterials are creating new opportunities for market expansion. Furthermore, the rising adoption of 3D printing technologies for customized medical devices is enhancing the versatility and efficiency of biomaterials, opening up new avenues for growth in the Australian market. This combination of technological, demographic, and environmental factors is expected to sustain the market’s robust growth trajectory.
The geographical landscape of the Australian biomaterials market is shaped by key regions such as New South Wales, Victoria, Queensland, and Western Australia, each contributing to the growth of the sector through strong healthcare infrastructure, research institutions, and biotechnology companies. Major cities like Sydney, Melbourne, and Brisbane are central to the adoption of biomaterials in medical applications, driven by advancements in research, personalized medicine, and healthcare technologies. Key players in the market, such as OrthoShoe, Biotronik Australia, ResMed Australia, Cook Medical Australia, and Toshiba Medical Systems, play a pivotal role in the development and distribution of biomaterials. These companies are at the forefront of innovation, offering a diverse range of products for applications in orthopedics, dental care, tissue engineering, and cardiovascular treatments. Their continued investments in R&D, strategic partnerships, and technological advancements are driving the market's evolution and expanding its potential in Australia’s healthcare sector.
Market Insights
- The Australia biomaterials market was valued at USD 1,902.70 million in 2024 and is expected to reach USD 6,091.98 million by 2032, growing at a CAGR of 15.66% from 2024 to 2032.
- The global biomaterials market was valued at USD 2,03,827.80 million in 2024 and is projected to reach USD 6,19,828.57 million by 2032, growing at a CAGR of 14.91% during the forecast period.
- The increasing demand for biocompatible materials in medical applications such as implants and prosthetics is a key market driver.
- Advancements in 3D printing and nanotechnology are significantly enhancing the functionality and customization of biomaterials.
- The market is witnessing a growing shift toward sustainable and biodegradable biomaterials to address environmental concerns.
- Competitive landscape includes prominent players like OrthoShoe, Biotronik Australia, ResMed Australia, and Cook Medical Australia, fostering innovation and strategic partnerships.
- Regulatory challenges and high costs associated with R&D are key restraints limiting the market’s growth potential.
- New South Wales, Victoria, and Queensland are leading the market, driven by their strong healthcare and research infrastructure.
Report Scope
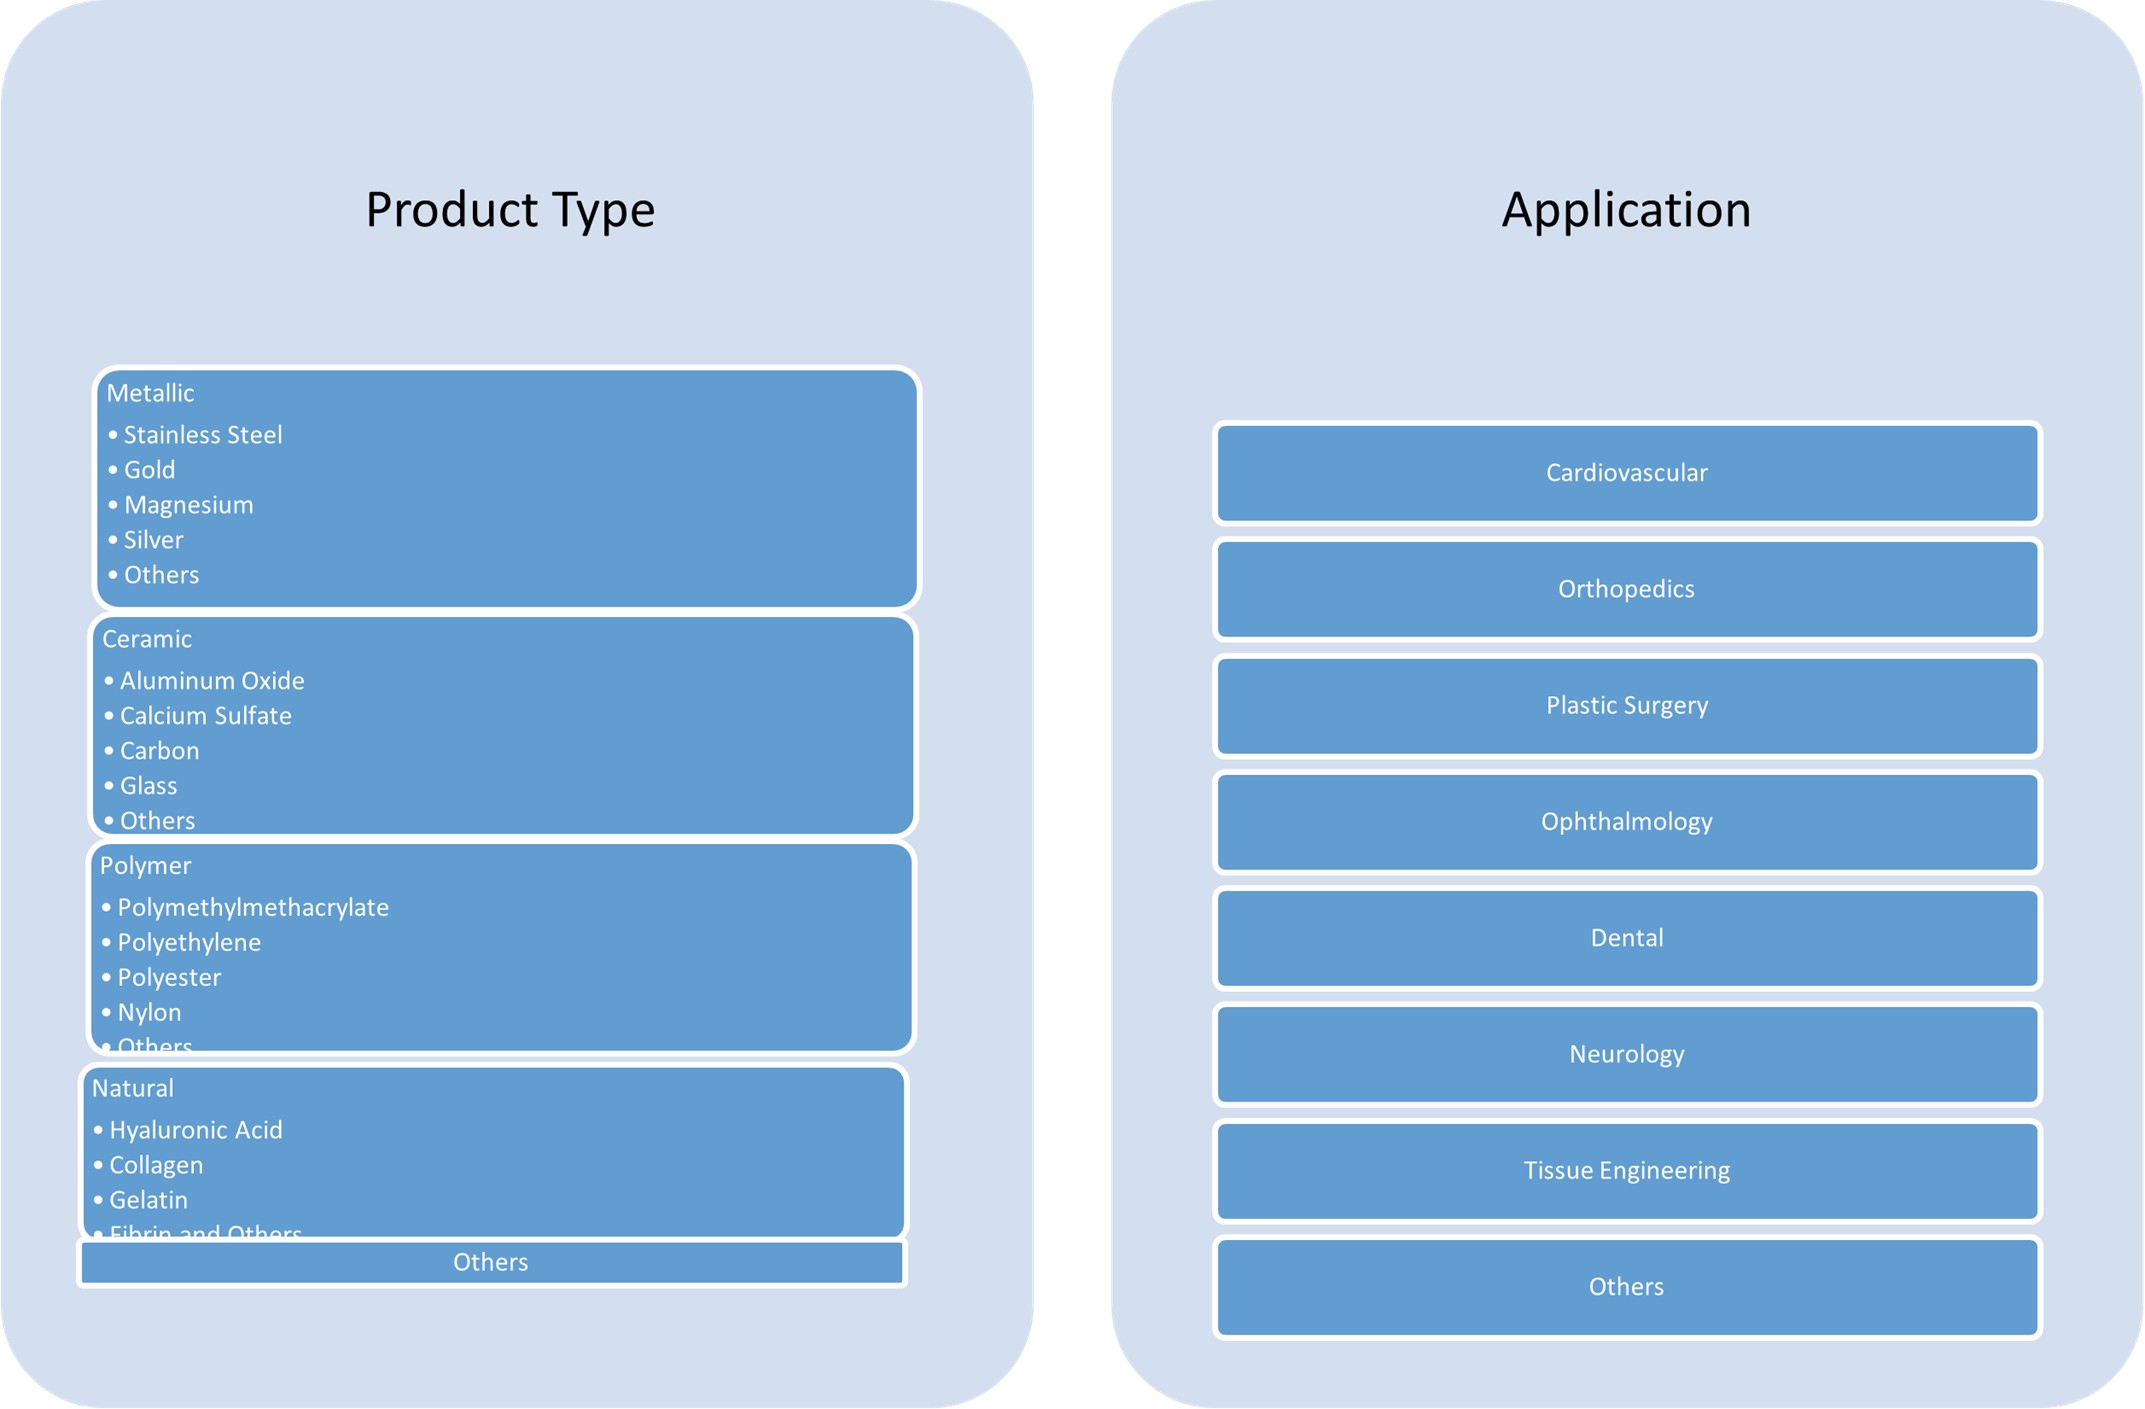
This report segments the Australia Biomaterials Market as follows:
Market Drivers
Increasing Healthcare Needs and Aging Population
One of the primary drivers of the Australian biomaterials market is the growing healthcare demand, particularly in the medical device and implant sectors. With an aging population, the need for advanced healthcare solutions such as prosthetics, orthopedic implants, and dental materials is on the rise. For instance, reports from the Australian Institute of Health and Welfare indicate that the proportion of Australians aged 65 and over is projected to increase significantly over the next decade, with estimates suggesting that by 2053, 21% of the population will be aged 65 and over. This demographic shift is expected to create a larger patient pool requiring medical treatments and implants. Biomaterials are crucial for these applications as they offer biocompatibility and durability, essential for long-term use in the human body. This demographic shift will continue to stimulate demand for advanced biomaterials to address chronic health conditions, arthritis, bone-related diseases, and other age-related ailments.
Technological Advancements in Biomaterial Development
Advancements in materials science and biotechnology are playing a key role in the growth of the Australian biomaterials market. Innovations in nanotechnology, tissue engineering, and 3D printing are enabling the development of more effective and customizable biomaterials. For instance, research institutions in Australia have been actively exploring the use of polymer-based biomaterials for regenerative medicine applications, supported by government funding. These innovations are not only improving the quality and performance of biomaterials but also reducing the costs associated with production. The integration of 3D printing technology allows for the creation of personalized medical devices and implants that perfectly match the patient’s anatomical structure, enhancing the effectiveness of treatments. This ability to create tailored biomaterials for specific medical needs is expanding the scope of applications for biomaterials in various fields, including orthopedics, dental care, and cardiovascular treatments. As research continues to progress, new types of biomaterials with enhanced properties will likely emerge, further driving market growth.
Rising Focus on Sustainability and Eco-Friendly Alternatives
Another important driver is the increasing focus on sustainability within the biomaterials industry. As environmental concerns rise globally, the demand for eco-friendly and biodegradable biomaterials has grown. Traditional materials, such as metals and synthetic polymers, pose environmental challenges, prompting industries to shift towards more sustainable alternatives. Biomaterials derived from renewable sources, such as plant-based polymers and natural fibers, are gaining traction for their ability to reduce environmental impact. In particular, biodegradable biomaterials are expected to play a significant role in applications where long-term environmental exposure is a concern. For example, in surgical implants and drug delivery systems, biodegradable options are being preferred for their ability to degrade naturally over time without leaving harmful residues. The demand for greener solutions is expected to drive innovation in the market and lead to the increased adoption of environmentally friendly biomaterials.
Growing Investments in Healthcare and Biotechnology Sectors
Significant investments in Australia’s healthcare and biotechnology sectors are further driving the biomaterials market’s growth. The Australian government, along with private sector players, is focusing on expanding the nation’s biotechnology and medical technology industries, positioning Australia as a hub for innovation in healthcare. These investments are fostering the development of new biomaterials, advanced manufacturing processes, and cutting-edge healthcare solutions. For example, government-funded research programs and collaborations between universities, research institutions, and healthcare companies are accelerating the commercialization of new biomaterials. Additionally, the rise of health-tech startups and the expansion of medical research facilities are contributing to a strong ecosystem that supports biomaterial innovations. These growing investments not only enhance the local production capacity but also improve the country’s ability to meet increasing domestic and international demand for high-quality biomaterials, driving overall market growth.
Market Trends
Advancements in 3D Printing and Customization
Technological innovations, particularly in 3D printing, are transforming the biomaterials landscape in Australia. For instance, healthcare facilities and research institutions are leveraging 3D printing to develop customized implants and prosthetics tailored to individual patient needs. This advancement allows for the creation of complex structures that mimic natural tissues, enhancing the functionality and integration of biomaterials in the human body. Government regulatory frameworks are also evolving to support the safe and effective use of 3D-printed medical devices
Integration of Nanotechnology in Biomaterials
Nanotechnology is playing a pivotal role in enhancing the properties of biomaterials. For instance, Australian research initiatives are focusing on incorporating nanoparticles into biomaterials to improve their mechanical strength, biocompatibility, and functionality. This integration allows for the development of smart biomaterials that can respond to environmental stimuli, such as changes in pH or temperature, making them ideal for applications in drug delivery systems and tissue engineering.
Surge in Natural and Biodegradable Biomaterials
The Australian biomaterials market is witnessing a significant shift towards natural and biodegradable materials, driven by environmental concerns and the need for sustainable medical solutions. Natural biomaterials, such as chitosan, alginate, and hyaluronic acid, are gaining popularity due to their excellent biocompatibility and biodegradability properties. These materials are increasingly being used in various medical applications, including wound healing and tissue engineering, as they reduce the environmental impact of medical devices and minimize the risk of adverse reactions.
Strategic Collaborations and Research Initiatives
The Australian biomaterials sector is experiencing increased collaboration between academic institutions, research organizations, and industry players. These partnerships are fostering innovation and accelerating the development of new biomaterials. For instance, researchers like Hala Zreiqat are pioneering the creation of 3D-printed bone scaffolds that stimulate bone regrowth, offering alternatives to traditional metal implants. Such collaborative efforts are enhancing the country's capabilities in biomaterial research and development.
Market Challenges Analysis
Regulatory Hurdles and Compliance Issues
One of the key challenges facing the Australian biomaterials market is navigating the complex regulatory landscape. Biomaterials, especially those used in medical devices and implants, must undergo rigorous testing and certification processes to meet the standards set by regulatory bodies such as the Therapeutic Goods Administration (TGA) and the Australian Competition and Consumer Commission (ACCC). For instance, reports indicate that the Australian Government has implemented strict compliance measures requiring extensive testing and validation before market approval. These regulations ensure that biomaterials are safe and effective for human use but can also lead to lengthy approval processes. The stringent compliance requirements, along with the associated costs, may delay market entry for new biomaterial innovations and limit the ability of small and medium-sized enterprises to introduce cutting-edge products. As a result, companies in the biomaterials sector often face high barriers to entry and increased time-to-market for their products.
High Costs of Research and Development
Another challenge in the Australian biomaterials market is the high cost associated with research and development (R&D). Developing new biomaterials often requires significant investments in both time and resources. Research into biocompatibility, durability, and sustainability involves complex processes, including extensive laboratory testing, pre-clinical trials, and clinical trials to ensure product safety and effectiveness. These efforts can be particularly costly when developing materials for specialized medical applications, such as implants or drug delivery systems. Additionally, the high cost of production for advanced biomaterials can limit their commercial viability, especially in price-sensitive markets. While technological advancements, such as 3D printing, have the potential to reduce costs, the overall financial burden of R&D remains a significant challenge for companies striving to innovate and remain competitive in the market.
Market Opportunities
The Australian biomaterials market presents significant opportunities driven by the increasing demand for advanced healthcare solutions and the growing adoption of sustainable materials. With an aging population and the rising prevalence of chronic diseases, the need for biocompatible materials in medical devices, implants, and prosthetics is expected to surge. Biomaterials are integral to addressing these demands, particularly in the fields of orthopedics, dental care, and cardiovascular treatments. Additionally, the ongoing advancements in 3D printing technology create new opportunities for the production of customized biomaterials tailored to individual patients, further enhancing their effectiveness. This growing trend in personalized medicine provides a promising avenue for companies to develop and commercialize new biomaterial products that can offer better outcomes for patients, thus capturing a larger share of the market.
Furthermore, the increasing emphasis on sustainability within the healthcare and biotechnology sectors presents a unique opportunity for the biomaterials market. As industries and consumers alike shift toward eco-friendly solutions, there is growing demand for biodegradable and natural biomaterials. Innovations in sustainable materials, such as plant-based polymers and biocompatible composites, are positioned to meet these expectations while reducing environmental impact. Australia’s focus on green initiatives and sustainable practices aligns with the global push for environmental responsibility, creating a favorable environment for the growth of biomaterials that are both high-performing and environmentally friendly. This demand for sustainable, biodegradable alternatives in medical applications and other sectors is expected to fuel market growth, presenting ample opportunities for companies to develop and capitalize on environmentally conscious biomaterial innovations.
Market Segmentation Analysis:
By Product Type:
The Australian biomaterials market is segmented based on product types, including metallic, ceramic, polymer, natural, and others. Metallic biomaterials are widely used in orthopedic implants and cardiovascular applications due to their strength and durability. Subcategories such as stainless steel, gold, magnesium, and silver are favored for their biocompatibility and ability to withstand mechanical stress. Ceramic biomaterials are typically employed in dental, orthopedic, and bone regeneration applications. Materials like aluminum oxide, calcium sulfate, carbon, and glass offer excellent wear resistance and osseointegration properties, making them suitable for load-bearing implants and bone scaffolds. Polymer biomaterials, such as polymethylmethacrylate, polyethylene, polyester, and nylon, are valued for their flexibility, moldability, and ease of processing. They are commonly used in soft tissue applications and drug delivery systems. Natural biomaterials, including hyaluronic acid, collagen, gelatin, and fibrin, are derived from biological sources and are gaining traction in regenerative medicine and tissue engineering for their ability to promote healing and cell growth. Other biomaterials continue to emerge as innovative solutions for specific medical needs.
By Application:
The Australian biomaterials market also spans various applications, including cardiovascular, orthopedics, plastic surgery, ophthalmology, dental, neurology, tissue engineering, and others. In cardiovascular applications, biomaterials are used for stents, valves, and vascular grafts, where durability and biocompatibility are crucial for long-term function. The orthopedic segment remains one of the largest consumers of biomaterials, utilizing metallic and ceramic materials for implants, prosthetics, and joint replacements. Plastic surgery benefits from polymer-based biomaterials that offer flexibility and ease of integration with human tissues. Ophthalmology applications utilize biomaterials for corneal implants, eye surgeries, and contact lenses, where biocompatibility is vital for tissue integration and comfort. In dental applications, biomaterials like ceramics and polymers are used in crowns, bridges, and implants. Neurology benefits from biomaterials used in spinal implants, neural scaffolds, and brain tissue engineering. The growing field of tissue engineering leverages natural and synthetic biomaterials to regenerate damaged tissues and organs, creating significant growth opportunities in regenerative medicine.
Segments:
Based on Product Type:
- Metallic
- Stainless Steel
- Gold
- Magnesium
- Silver
- Others
- Ceramic
- Aluminum Oxide
- Calcium Sulfate
- Carbon
- Glass
- Others
- Polymer
- Polymethylmethacrylate
- Polyethylene
- Polyester
- Nylon
- Others
- Natural
- Hyaluronic Acid
- Collagen
- Gelatin
- Fibrin and others
- Others
Based on Application:
- Cardiovascular
- Orthopedics
- Plastic Surgery
- Ophthalmology
- Dental
- Neurology
- Tissue Engineering
- Others
Based on the Geography:
- New South Wales
- Victoria
- Queensland
- Western Australia (WA)
- South Australia
Regional Analysis
New South Wales (NSW)
New South Wales (NSW) holds the largest market share in the Australian biomaterials sector, accounting for approximately 35% of the total market. This dominance is primarily driven by the state's robust healthcare infrastructure, significant research and development activities, and concentration of medical technology companies. Sydney, as the largest city and a major hub for biotechnology and medical research, plays a pivotal role in the market's growth. The strong presence of hospitals, universities, and innovation centers in NSW contributes to the increasing adoption of advanced biomaterials in various medical applications such as orthopedic implants, dental care, and tissue engineering. Additionally, the region's focus on sustainability and eco-friendly medical solutions further boosts demand for natural and biodegradable biomaterials, positioning NSW as a leader in the country's biomaterial industry.
Victoria
Victoria holds the second-largest market share in the Australian biomaterials market, estimated at around 28%. The state is home to several renowned research institutions, including the University of Melbourne and Monash University, which are heavily involved in biomaterial innovation. Victoria’s strong focus on healthcare and biotechnology, coupled with substantial government support for the sector, has led to rapid advancements in medical devices and biomaterial technologies. Melbourne, as the state capital, attracts numerous biotechnology firms that specialize in developing novel biomaterials, particularly in regenerative medicine and tissue engineering. The rising demand for personalized medicine and advancements in 3D printing technologies are contributing to the market’s expansion in Victoria, with the region seeing increased adoption of customized biomaterials for medical implants and devices.
Queensland
Queensland’s biomaterials market accounts for approximately 20% of the total Australian market. The region’s growth in the biomaterials sector is largely driven by its expanding medical research capabilities and a thriving healthcare ecosystem. Brisbane, the state's capital, is becoming a key center for medical technology companies and research institutions specializing in biomaterials. The state's strong emphasis on biotechnology and life sciences innovation has led to increased production and application of advanced biomaterials in orthopedics, dental care, and drug delivery systems. Additionally, Queensland's growing healthcare infrastructure, along with the increasing number of clinical trials and collaborations with universities, ensures that the demand for high-performance biomaterials continues to rise, further contributing to the region’s market share.
Western Australia and South Australia
Western Australia (WA) and South Australia (SA) together account for approximately 17% of the Australian biomaterials market. WA, with a market share of around 10%, benefits from the region's strong focus on medical research and innovation in biotechnology. The state's emphasis on sustainable biomaterials and increasing investment in health technologies are key drivers of its market growth. Similarly, South Australia, contributing roughly 7% to the market, has established itself as a growing hub for biomaterials innovation. Adelaide, the state capital, is home to several universities and research institutions focusing on advanced biomaterials, particularly in regenerative medicine and tissue engineering. Both regions are expected to witness steady growth due to their ongoing investments in health tech, medical research, and biotechnology. The combined market share of WA and SA reflects the increasing regional demand for innovative biomaterial solutions in healthcare applications.
Key Player Analysis
- OrthoShoe
- Biotronik Australia
- ResMed Australia
- Cook Medical Australia
- Toshiba Medical Systems
Competitive Analysis
The competitive landscape of the Australian biomaterials market is marked by the presence of several key players that drive innovation, research, and development in the sector. Leading companies such as OrthoShoe, Biotronik Australia, ResMed Australia, Cook Medical Australia, and Toshiba Medical Systems play a vital role in shaping market dynamics. These companies focus on providing advanced biomaterial solutions for various medical applications, including orthopedic implants, cardiovascular treatments, and dental care. These players are competing through the introduction of innovative products, strong research and development (R&D) capabilities, and strategic partnerships. Many companies are investing in cutting-edge technologies like 3D printing, nanotechnology, and sustainable biomaterials to differentiate themselves in the market. The focus is also shifting towards biocompatible and biodegradable materials that address both clinical needs and environmental concerns. This trend is fostering a competitive edge for companies that can provide environmentally-friendly and customizable solutions. Additionally, the competition is intensifying due to the increasing demand for personalized medicine, which requires biomaterials that can be tailored to individual patients' needs. Regulatory requirements and high R&D costs remain significant challenges, but companies are adapting by forming collaborations with research institutions and healthcare providers to innovate and expand their market presence. As a result, competition remains fierce, with companies striving to capture a larger share of this rapidly growing market.
Recent Developments
- In April 2025, BASF expanded its EcoBalanced portfolio for Care Chemicals in North America, introducing the first EcoBalanced personal care products in the region. These include Dehyton® PK 45 and Dehyton® KE UP, both certified as EcoBalanced grades using a biomass balance (BMB) approach to reduce carbon footprint. Additionally, six U.S. Care Chemicals production sites are now powered entirely by renewable electricity, saving approximately 33,000 tons of CO₂ annually.
- In November 2024, Covestro began production of Desmophen® CQ NH, a partially bio-based polyaspartic resin (at least 25% bio-based content), at its Foshan, China site. The facility is powered entirely by renewable energy, and the product is used in wind turbine and flooring coatings, supporting both local supply and sustainability goals.
- In January 2025, BASF’s Performance Materials division transitioned all European sites to 100% renewable electricity, covering engineering plastics, polyurethanes, thermoplastic polyurethanes, and specialty polymers.
- In June 2023, Invibio announced a collaboration with Paragon Medical to scale up manufacturing of PEEK-OPTIMA Ultra-Reinforced composite trauma devices in China, responding to growing global demand for high-performance biomaterials in trauma fixation.
- In February 2023, Celanese introduced ECO-B, more sustainable versions of Acetyl Chain materials, incorporating mass balance bio-content to provide chemically identical, bio-based alternatives for engineered materials.
Market Concentration & Characteristics
The Australian biomaterials market exhibits moderate concentration, with a few key players holding a significant share of the market. However, it remains open to innovation, with a mix of established multinational companies and emerging local firms contributing to its growth. The market is characterized by high competition driven by continuous advancements in materials science, medical technology, and research. Companies are increasingly focused on product differentiation through the development of specialized, biocompatible, and sustainable biomaterials tailored for specific medical applications, such as orthopedic implants, tissue engineering, and drug delivery systems. The demand for personalized and biodegradable biomaterials is further intensifying this competitive landscape. Additionally, the market is marked by a strong emphasis on regulatory compliance and quality standards to ensure the safety and efficacy of biomaterials used in healthcare. Despite challenges such as high R&D costs and stringent regulations, the market remains dynamic, with opportunities for growth through innovation and collaboration.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Australia's biomaterials sector is expected to see continued growth due to increasing demand for sustainable and eco-friendly materials across various industries.
- Innovations in bio-based materials will drive advancements in manufacturing, offering new solutions for industries like construction, packaging, and healthcare.
- The Australian government is likely to increase funding and support for research and development in biomaterials, aiming to boost national competitiveness.
- There will be a growing focus on circular economy principles, encouraging the use of biodegradable and recyclable biomaterials to reduce environmental impact.
- Strong collaboration between academic institutions, industry players, and government bodies will enhance Australia's capabilities in developing next-generation biomaterials.
- The medical sector will remain a key growth area, with biomaterials playing a critical role in creating advanced implants, prosthetics, and tissue engineering solutions.
- Australia’s renewable resource base, including plant and marine materials, will provide a competitive advantage in producing innovative biomaterials.
- As global demand for sustainable alternatives rises, Australia is poised to strengthen its position as a key supplier of high-quality, bio-based materials.
- Advances in biotechnology and nanotechnology will lead to new biomaterials with enhanced performance, driving their use in various applications such as energy storage and electronics.
- Australia's commitment to sustainability will drive the adoption of biomaterials in various sectors, helping to meet both domestic and international environmental goals.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Healthcare Needs and Aging Population
Australia's aging population is leading to a higher incidence of chronic diseases and age-related conditions, driving demand for advanced biomaterials in implants, prosthetics, and medical devices. This demographic shift is expanding the patient pool requiring biocompatible and durable materials for long-term healthcare solutions.
Technological Advancements in Biomaterial Development
Innovations in biotechnology, nanotechnology, and 3D printing are enabling the creation of more effective, customizable, and cost-efficient biomaterials. These advancements allow for tailored medical devices and implants, improving patient outcomes and expanding the range of biomaterial applications.
Rising Focus on Sustainability and Eco-Friendly Alternatives
Growing environmental concerns and regulatory pressures are pushing the market toward biodegradable and renewable biomaterials. The adoption of plant-based polymers and natural fibers is increasing, as both manufacturers and healthcare providers seek to reduce the environmental impact of medical products.
Growing Investments in Healthcare and Biotechnology Sectors
Significant public and private investments in Australia's healthcare and biotechnology industries are fostering innovation and commercialization of new biomaterials. Government support, research collaborations, and the expansion of medical research facilities are strengthening the ecosystem for biomaterial development and adoption.
Adoption of 3D Printing and Personalized Medicine
The integration of 3D printing technologies is enabling the production of patient-specific implants and devices, enhancing the effectiveness and acceptance of biomaterials in clinical practice. This trend toward personalized medicine is creating new opportunities for market growth and product differentiation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Australia Biomaterials?
What factors are driving the growth of the Australia Biomaterials?
What are some challenges faced by the Australia Biomaterials?
Who are the major players in the Australia Biomaterials?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Cardiovascular
- 1.2.2 Orthopedics
- 1.2.3 Plastic Surgery
- 1.2.4 Ophthalmology
- 1.2.5 Dental
- 1.2.6 Neurology
- 1.2.7 Tissue Engineering
- 1.2.8 Others
- 1.3 By Product Type
- 1.3.1 Metallic (Stainless Steel, Gold, Magnesium, Silver, Others)
- 1.3.2 Ceramic (Aluminum Oxide, Calcium Sulfate, Carbon, Glass, Others)
- 1.3.3 Polymer (Polymethylmethacrylate, Polyethylene, Polyester, Nylon, Others)
- 1.3.4 Natural (Hyaluronic Acid, Collagen, Gelatin, Fibrin, Others)
- 1.3.5 Others
- 1.4 By Geography (Australia)
- 1.4.1 New South Wales
- 1.4.2 Victoria
- 1.4.3 Queensland
- 1.4.4 Western Australia
- 1.4.5 South Australia
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,902.70 million → 2032: USD 6,091.98 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Biomaterials Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Biomaterials Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Biomaterials Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Biomaterials Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Biomaterials Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Biomaterials Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Biomaterials Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Biomaterials Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,902.70 million → 2032: USD 6,091.98 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Biomaterials Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cardiovascular
- 12.3.7.2 Orthopedics
- 12.3.7.3 Plastic Surgery
- 12.3.7.4 Ophthalmology
- 12.3.7.5 Dental
- 12.3.7.6 Neurology
- 12.3.7.7 Tissue Engineering
- 12.3.7.8 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Metallic (Stainless Steel, Gold, Magnesium, Silver, Others)
- 12.4.7.2 Ceramic (Aluminum Oxide, Calcium Sulfate, Carbon, Glass, Others)
- 12.4.7.3 Polymer (Polymethylmethacrylate, Polyethylene, Polyester, Nylon, Others)
- 12.4.7.4 Natural (Hyaluronic Acid, Collagen, Gelatin, Fibrin, Others)
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Geography (Australia) - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 New South Wales
- 12.5.7.2 Victoria
- 12.5.7.3 Queensland
- 12.5.7.4 Western Australia
- 12.5.7.5 South Australia
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Biomaterials End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Biomaterials Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Biomaterials Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Biomaterials Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 OrthoShoe
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Biotronik Australia
- 18.4 ResMed Australia
- 18.5 Cook Medical Australia
- 18.6 Toshiba Medical Systems
- 18.7 Stryker
- 18.8 Zimmer Biomet
- 18.9 Baxter International
- 18.10 Invibio
- 18.11 BASF
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

