
Market Overview:
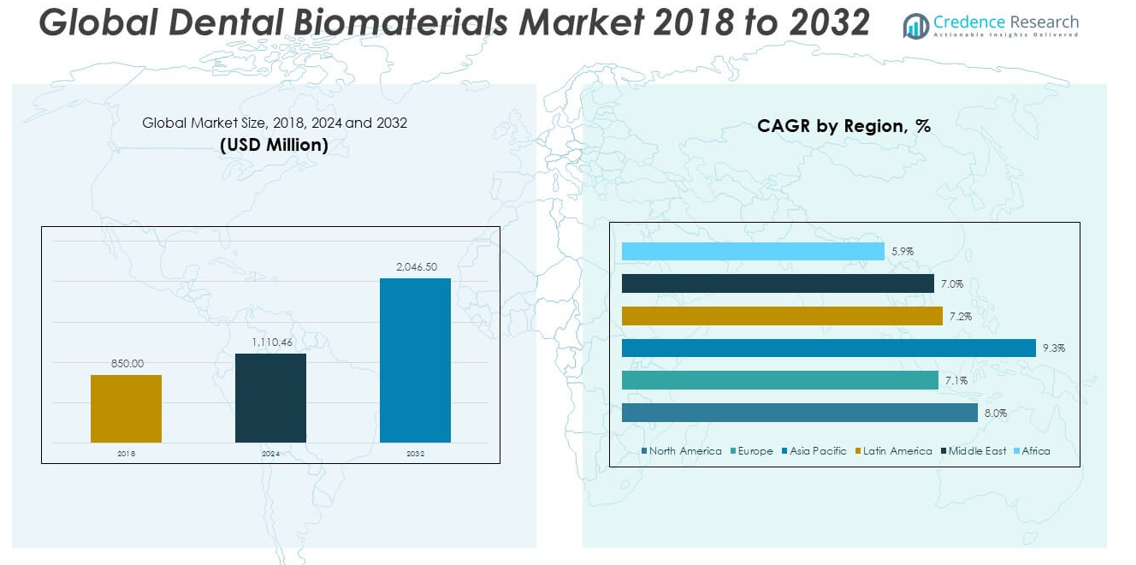
The Dental Biomaterials Market size was valued at USD 850 million in 2018, reached USD 1,110.46 million in 2024, and is anticipated to reach USD 2,046.50 million by 2032, at a CAGR of 7.99% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dental Biomaterials Market Size 2024 | USD 1,110.46 million |
| Dental Biomaterials Market, CAGR | 7.99% |
| Dental Biomaterials Market Size 2032 | USD 2,046.50 million |
Rising dental disorders, increased demand for cosmetic procedures, and advancements in biocompatible materials are major factors propelling the dental biomaterials market. Heightened awareness of oral hygiene and the expansion of dental care services in urban and semi-urban areas further support this growth. The aging population significantly drives the need for prosthetics and implants, while rising disposable incomes in emerging economies fuel elective dental treatments. Innovations in regenerative dentistry, including nanomaterials and bioactive ceramics, are enhancing outcomes. R&D investments and strategic collaborations enable better material performance and faster product development.
The Dental Biomaterials Market is experiencing significant traction across developed and emerging regions due to expanding dental infrastructure and healthcare investments. North America leads, driven by advanced dental technologies, well-established clinical networks, and insurance coverage. Europe follows, with widespread use of dental implants and prosthetics among aging populations supported by national dental programs. Asia Pacific is the fastest-growing region, driven by large patient pools, increasing awareness, and supportive government programs in China, India, and Japan.
Market Insights:
- The Dental Biomaterials Market grew from USD 850 million in 2018 to USD 1,110.46 million in 2024 and is projected to reach USD 2,046.50 million by 2032, at a CAGR of 7.99%.
- Rising dental disorders, growing cosmetic dentistry, and adoption of biocompatible materials are fueling market expansion globally.
- Increased demand for prosthetics and implants among aging populations and urban consumers is strengthening the market’s implantology and aesthetic restoration segments.
- Ongoing R&D in nanomaterials, bioactive ceramics, and regenerative biomaterials is enhancing functionality, durability, and patient outcomes.
- North America leads the market due to advanced dental infrastructure, high insurance coverage, and early adoption of innovative materials.
- Asia Pacific is the fastest-growing region, driven by rising healthcare investments, expanding middle-class populations, and public dental programs in China, India, and Japan.
- High material costs and regulatory complexities continue to challenge adoption in emerging markets, where affordability and infrastructure gaps persist.
Market Drivers:
Growing Prevalence of Dental Disorders and Increasing Surgical Interventions
The rise in dental diseases such as caries, periodontal issues, and edentulism is one of the primary drivers of the Dental Biomaterials Market. It responds to an expanding global patient base requiring advanced restorative and reconstructive solutions. Dental implants, bridges, and dentures utilize biomaterials extensively to ensure long-term compatibility and success. The demand for surgical interventions has grown with the increasing geriatric population and lifestyle changes that negatively affect oral health. Governments and private players are also investing in dental camps and awareness programs, pushing patients toward treatment rather than prevention. It also benefits from technological innovations that improve the precision of procedures and the success rates of surgical implants.
- For example, Dentsply Sirona’s DS OmniTaper Implant System, which features the OsseoSpeed surface for enhanced bone healing and a pre-mounted TempBase abutment allowing immediate restorations directly aiming to reduce patient recovery times and improve clinical integration.
Cosmetic Dentistry Uptake Fueling Material Innovation
A growing demand for cosmetic dentistry is reshaping consumer expectations and encouraging the adoption of high-performance dental biomaterials. It fuels the development of ceramic, polymeric, and hybrid biomaterials that offer natural aesthetics, longevity, and ease of application. Rising media influence and self-image consciousness push individuals toward cosmetic corrections such as veneers, crowns, and aesthetic restorations. Dental biomaterials enable minimally invasive, highly aesthetic outcomes with increased comfort. It gains traction in affluent urban markets and is gradually penetrating middle-income segments. The growth of digital dentistry and 3D printing supports this trend by enabling faster, custom-fitted prosthetics.
R&D Advancements in Regenerative and Bioactive Materials
Continued research and innovation in regenerative dental materials drive deeper market penetration. It includes developments in stem cell-compatible scaffolds, growth factor delivery systems, and nanostructured biomaterials. Such innovations improve healing time, tissue regeneration, and implant integration. These materials are increasingly adopted in advanced procedures like periodontal regeneration and bone grafting. The Dental Biomaterials Market benefits from the clinical shift toward biomimetic and patient-specific solutions that reduce post-operative complications. It enables dentists to achieve better predictability in outcomes while enhancing patient satisfaction and clinical workflow efficiency.
- For example, Nanostructured ceramics like zirconia now achieve flexural strengths of 900–1200 MPaand fracture toughness of 4–6 MPa√m, exceeding traditional alumina ceramics in both mechanical performance and longevity.
Favorable Healthcare Spending and Institutional Support
Increased healthcare investments across both public and private sectors are accelerating the adoption of quality dental biomaterials. It is supported by favorable reimbursement policies in developed markets and oral healthcare initiatives in developing regions. Institutional collaborations between universities, dental hospitals, and manufacturers promote access to training, innovation, and new product adoption. Economic growth in emerging markets leads to a rise in discretionary spending, enabling access to premium dental care. The presence of global manufacturers and their push into new geographies via mergers, partnerships, and local production facilities is expanding the market's global footprint.
Market Trends:
Integration of Digital Dentistry with Biomaterials
The incorporation of digital workflows in dental practices is transforming how biomaterials are utilized. The Dental Biomaterials Market benefits from CAD/CAM technology, intraoral scanning, and 3D printing, which enable custom prosthetic and restorative solutions. It allows for greater precision, reduced chair time, and improved patient satisfaction. Dentists are now able to design and fabricate restorations in-house, which accelerates adoption of compatible biomaterials. The shift toward digital platforms also improve inventory management and speeds up treatment planning. These technologies require biomaterials with specific properties such as machinability, strength, and biocompatibility, driving the demand for tailored products.
- For example, Stratasys and 3D Systems-two leading dental 3D printer manufacturers-highlight their machines' capabilities for layer resolutions under 30 μm, supporting complex custom prosthetics with tolerances under ±40 μm. These advances require biomaterials like zirconia and lithium disilicate, whose machinability and biocompatibility are certified under ISO 6872 and ISO 10993 protocols.
Shift Toward Biologically Derived and Sustainable Materials
A growing trend toward biologically sourced and environmentally sustainable dental materials is shaping procurement choices. The Dental Biomaterials Market is experiencing an increase in demand for biodegradable and non-toxic alternatives that align with green dentistry principles. Patients and practitioners are becoming more conscious of the origin and impact of the materials used. It encourages innovation in natural polymers, collagen-based scaffolds, and hydroxyapatite derived from sustainable sources. Regulatory support for sustainable healthcare practices further bolsters this trend. This evolution not only reduces the ecological footprint but also improves patient acceptance, especially in preventive and pediatric dentistry.
- For example, major dental biomaterial manufacturers, including Geistlich Pharma and Straumann, are pioneering collagen-based scaffolds and hydroxyapatite derived from sustainable sources offering verified biocompatibility and biodegradation profiles. Geistlich’s Bio-Gide® membrane, for example, is 90% resorbed within six months, reducing the need for secondary intervention.
Rising Role of AI in Biomaterial Selection and Procedure Planning
Artificial intelligence tools are playing an expanding role in dental diagnostics, planning, and material selection. The Dental Biomaterials Market is being influenced by decision-support systems that help choose optimal biomaterials based on clinical conditions. AI applications assess patient history, imaging data, and material characteristics to suggest compatible options for implants or restorations. It enhances outcomes by minimizing errors and increasing personalization in treatments. Machine learning also helps manufacturers improve product performance through real-time feedback and usage analytics. These integrations make dental care more precise, predictable, and cost-effective for both providers and patients.
Globalization of Supply Chains and Distribution Networks
Global supply chains are evolving to make high-quality dental biomaterials accessible across more geographies. The Dental Biomaterials Market is expanding through localized manufacturing hubs, streamlined logistics, and international regulatory harmonization. It enables faster distribution of products while reducing dependency on imports in growing economies. Manufacturers are also setting up regional warehouses and partnering with local distributors to increase reach. These dynamics help reduce cost variations and improve market responsiveness. The trend contributes to a more balanced competitive landscape by allowing smaller players to access markets once dominated by large multinationals.
Market Challenges Analysis:
Complex Regulatory Landscape and Compliance Constraints
Navigating the regulatory requirements remains a significant challenge for stakeholders in the Dental Biomaterials Market. Each region has its own set of medical device regulations, which complicates international product launches and limits global scalability. It requires time-consuming clinical validation, extensive documentation, and repeated compliance audits, especially for innovative or bioactive materials. Smaller manufacturers often struggle to keep up with changing standards, delaying their entry or restricting their expansion. Inconsistent classification of biomaterials across jurisdictions further adds to the uncertainty. These factors lead to higher compliance costs, prolong product approval cycles, and hinder the availability of new material technologies in cost-sensitive markets.
High Material Cost and Limited Access in Emerging Markets
The high cost of premium dental biomaterials continues to limit adoption in developing regions. The Dental Biomaterials Market faces barriers in affordability, particularly for advanced ceramics, composite scaffolds, and implant-grade materials. It restricts access for middle-income populations who often depend on out-of-pocket dental expenditures. Public dental healthcare services in many countries do not subsidize biomaterials, which deters patients from opting for high-quality treatments. Infrastructural gaps such as lack of skilled technicians and specialized equipment also reduce the effectiveness of biomaterials in certain regions. Market expansion in these areas depends on cost reduction strategies, training programs, and increased public-private investments in dental care infrastructure.
Market Opportunities:
Emerging Demand in Pediatric and Geriatric Dentistry
Expanding oral healthcare services tailored to pediatric and geriatric populations is creating targeted opportunities in the Dental Biomaterials Market. It benefits from demand for minimally invasive, biocompatible, and age-specific materials. The rise in early childhood dental interventions and aging-related prosthetic needs opens avenues for specialized biomaterials that support rapid healing and long-term integration. Manufacturers are developing fluoride-releasing, antibacterial, and soft-tissue friendly materials to serve these segments. Growing government support for age-inclusive dental programs further strengthens this opportunity across developed and developing regions.
Untapped Potential in Tier-2 Cities and Rural Healthcare Networks
Tier-2 cities and rural regions represent untapped markets where dental infrastructure is gradually improving. The Dental Biomaterials Market can expand by leveraging mobile clinics, tele-dentistry, and public-private partnerships to supply essential materials. It gains from rising disposable incomes and awareness initiatives that drive people toward preventive and restorative care. Local manufacturing and distribution alliances reduce logistic hurdles and bring down costs, enabling wider penetration. These regions require durable, easy-to-use, and cost-effective materials tailored for general dentistry, creating new avenues for growth outside metropolitan clusters.
Market Segmentation Analysis:
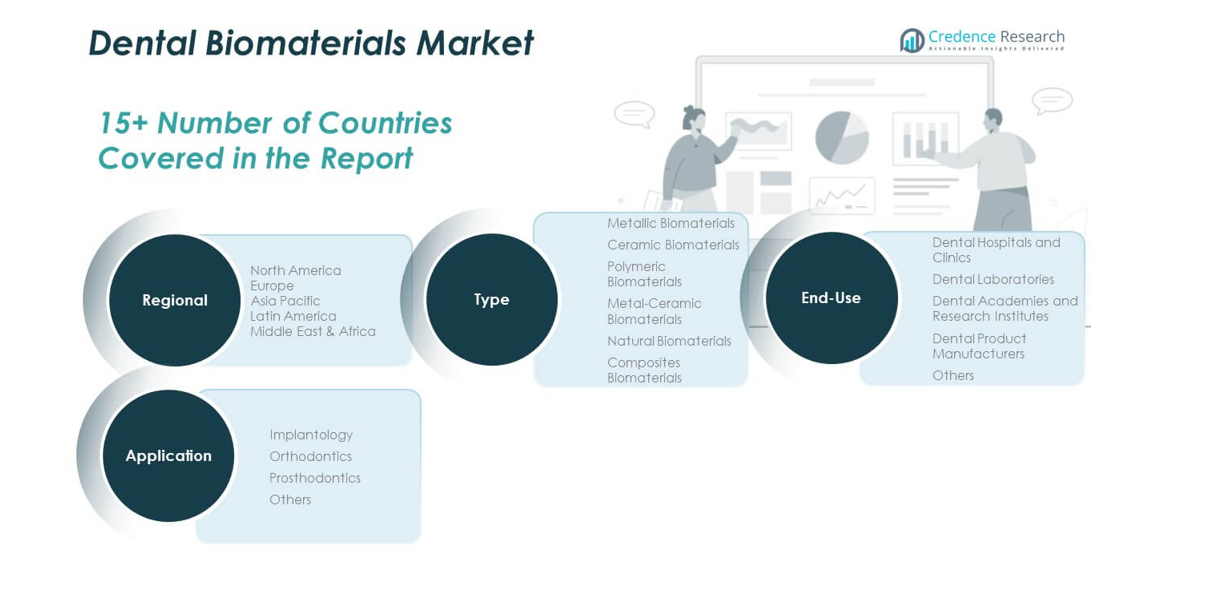
The Dental Biomaterials Market demonstrates diverse segmentation across type, application, and end-use categories.
By type, metallic biomaterials lead due to their superior strength and durability, especially in dental implants. Ceramic biomaterials follow closely, offering high biocompatibility and aesthetic appeal in restorative dentistry. Polymeric biomaterials gain momentum for their flexibility and use in orthodontic applications, while metal-ceramic combinations address both mechanical and aesthetic needs. Natural biomaterials, though limited by mechanical strength, serve niche applications requiring enhanced biocompatibility. Composites biomaterials integrate multiple properties to meet performance demands across advanced dental procedures.
- For example, Straummann Group, a leader in dental implants, utilizes medical-grade titanium (Ti-6Al-4V), which holds ISO 5832-3 certification and provides tensile strength up to 960 MPa, crucial for long-term implant stability.
By application, implantology dominates the Dental Biomaterials Market, driven by rising demand for dental implants among aging populations and individuals with tooth loss. Orthodontics sees stable growth due to increasing awareness of dental aesthetics, especially among younger demographics. Prosthodontics holds a significant share, benefiting from growing cases of edentulism and the adoption of crowns and bridges. The others segment includes preventive and regenerative treatments, supporting market expansion across varied clinical needs.
- For example, Nobel Biocare’s TiUnite® implant surface technology, used in over 20 million procedures worldwide, demonstrates significant cumulative survival rate at 10 years in peer-reviewed clinical studies.
By end-use, dental hospitals and clinics form the largest segment, owing to high patient footfall and availability of comprehensive dental services. Dental laboratories contribute significantly by customizing prosthetics and restorations. Dental academies and research institutes play a crucial role in material development and clinical testing. Dental product manufacturers continue to invest in innovation and material enhancement to meet evolving practitioner requirements. It also sees contributions from other end-users involved in dental product distribution and support services.
Segmentation:
By Type
- Metallic Biomaterials
- Ceramic Biomaterials
- Polymeric Biomaterials
- Metal-Ceramic Biomaterials
- Natural Biomaterials
- Composites Biomaterials
By Application
- Implantology
- Orthodontics
- Prosthodontics
- Others
By End-use
- Dental Hospitals and Clinics
- Dental Laboratories
- Dental Academies and Research Institutes
- Dental Product Manufacturers
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The North America Dental Biomaterials Market size was valued at USD 312.80 million in 2018 to USD 403.75 million in 2024 and is anticipated to reach USD 743.09 million by 2032, at a CAGR of 8.0% during the forecast period. North America holds the largest share in the Dental Biomaterials Market due to its advanced dental infrastructure, strong reimbursement systems, and high demand for cosmetic and implant procedures. It benefits from an active research ecosystem and early adoption of bioactive and regenerative materials. The U.S. dominates the regional market through extensive R&D investments and the presence of leading companies. Canada also contributes with a growing emphasis on dental education and public oral health initiatives. High per capita income and a rising elderly population support continued demand for premium dental materials. It leads in terms of product innovation, regulatory clarity, and patient awareness.
The Europe Dental Biomaterials Market size was valued at USD 194.57 million in 2018 to USD 242.83 million in 2024 and is anticipated to reach USD 418.82 million by 2032, at a CAGR of 7.1% during the forecast period. Europe ranks second in market share, supported by high dental care standards and a mature patient base. The Dental Biomaterials Market in this region benefits from insurance-backed procedures and a surge in geriatric restorations. Countries like Germany, France, and the UK dominate the regional landscape, with growing adoption of aesthetic biomaterials. It sees steady innovation from regional manufacturers, universities, and clinical research centers. Regulatory frameworks are stringent but offer clear guidance for biomaterial certifications. Public health campaigns and subsidized oral care programs sustain demand for both functional and cosmetic materials.
The Asia Pacific Dental Biomaterials Market size was valued at USD 209.95 million in 2018 to USD 286.33 million in 2024 and is anticipated to reach USD 581.82 million by 2032, at a CAGR of 9.3% during the forecast period. Asia Pacific emerges as the fastest-growing region due to rapid urbanization, rising income levels, and increased investment in dental infrastructure. The Dental Biomaterials Market is fueled by expanding middle-class populations in China, India, and Southeast Asia seeking quality dental care. Japan and South Korea contribute significantly with technological advancements and a focus on dental innovation. It benefits from strong government initiatives promoting dental education and public health awareness. Growth in private dental chains and medical tourism also drives adoption of advanced biomaterials.
The Latin America Dental Biomaterials Market size was valued at USD 67.07 million in 2018 to USD 86.94 million in 2024 and is anticipated to reach USD 150.97 million by 2032, at a CAGR of 7.2% during the forecast period. Latin America exhibits moderate growth in the Dental Biomaterials Market, driven by increasing cosmetic dentistry and improved access to oral healthcare services. Brazil leads the region due to its large population and a growing base of dental professionals. Mexico and Argentina are emerging markets supported by public-private partnerships and educational outreach. It sees greater use of polymeric and cost-efficient materials suited for general dentistry. Despite economic disparities, urban centers continue to demand advanced biomaterials, creating segmented growth opportunities across the region.
The Middle East Dental Biomaterials Market size was valued at USD 43.52 million in 2018 to USD 54.18 million in 2024 and is anticipated to reach USD 92.72 million by 2032, at a CAGR of 7.0% during the forecast period. The Middle East market is gaining traction through investments in private dental clinics and rising dental tourism. It benefits from increasing awareness among affluent populations and expanding healthcare infrastructure. The Gulf Cooperation Council countries lead the regional growth due to high-income levels and demand for aesthetic solutions. It sees gradual adoption of regenerative materials in specialist clinics. Market players are entering through local partnerships and exhibitions, expanding product availability and clinician exposure. Continued emphasis on quality standards and accreditation strengthens its regional outlook.
The Africa Dental Biomaterials Market size was valued at USD 22.10 million in 2018 to USD 36.43 million in 2024 and is anticipated to reach USD 59.08 million by 2032, at a CAGR of 5.9% during the forecast period. Africa remains an emerging region for the Dental Biomaterials Market, marked by limited but growing infrastructure. South Africa leads the regional uptake, followed by Egypt and Nigeria, where urban demand for dental restoration is rising. It faces challenges including inadequate training, limited access to high-end materials, and low insurance coverage. Nevertheless, mobile clinics and NGO-backed programs are improving rural access. The market gains traction through donations, international partnerships, and the slow expansion of dental academic centers. Long-term growth depends on strengthening supply chains and scaling basic oral healthcare services.
Key Player Analysis:
- Straumann Holding AG
- Geistlich Pharma AG
- Zimmer Biomet Holdings, Inc.
- Danaher Corporation
- Dentsply Sirona, Inc.
- 3M Company
- Royal DSM
- Carpenter Technology Corporation
- Kuraray Co., Ltd.
- Medtronic PLC
- Henry Schein, Inc.
- Mitsui Chemicals, Inc.
- Victrex PLC
- Ivoclar Vivadent AG
- GC Corporation
Competitive Analysis:
The Dental Biomaterials Market remains moderately fragmented with a mix of multinational corporations and highly specialized niche manufacturers. It features strong competition around implant-grade alloys, high-strength ceramics, and bioactive composites. Companies differentiate through proprietary formulations, CAD/CAM compatibility, and clinical education programs that build practitioner loyalty. Strategic moves include targeted acquisitions to access regenerative technologies and regional manufacturing hubs, which shorten supply chains and cut lead times. Pricing remains competitive, yet quality and regulatory credentials act as primary purchase filters, especially in North America and Europe. Rapid growth in Asia Pacific intensifies rivalry, prompting global leaders to forge distribution alliances with local labs. Product bundling with digital workflow solutions gives vendors a service edge and deepens client integration. Continuous R&D investment, supported by collaborations with universities, drives material innovation and secures intellectual property. Effective brand positioning now relies on documented clinical outcomes, sustainability certifications, and robust after-sales technical support globally today.
Recent Developments:
- In March 2025, Straumann launched the Straumann AXS cloud-based platform and introduced new digital dentistry solutions including Smile-in-a-Box, UN!Q prosthetics, the iEXCEL implant system, and a co-branded 3D printer with SprintRay. These initiatives advance digital workflow and the use of sophisticated biomaterials for dental prosthetics and implants, marking a significant impact in dental biomaterials.
- In April 2024, Geistlich Pharma acquired Bionnovation Biomedical, a Brazilian medtech company specializing in dental regenerative products. This acquisition enhances Geistlich’s portfolio in regenerative dental biomaterials and expands its global reach, especially in emerging markets.
Market Concentration & Characteristics:
The Dental Biomaterials Market exhibits moderate concentration, with the top five companies commanding a significant portion of global revenue while an extended tail of regional specialists fills niche demands. It balances high entry barriers stemming from stringent regulatory protocols and capital-intensive R&D with vibrant innovation cycles that invite academic spin-offs and start-ups. Product lifecycles remain relatively long because clinical validation and brand trust carry significant weight in material selection. Price elasticity stays low; dentists prioritize reliability and support over cost, particularly for implant and prosthetic applications. Distribution networks rely on hybrid models that combine direct sales to large hospital chains with dealer channels serving independent clinics. Sustainability credentials and digital compatibility increasingly influence purchasing decisions, signaling a shift toward greener, tech-ready portfolio.
Report Coverage:
The research report offers an in-depth analysis based on type, application, and end-use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Nanostructured surfaces will gain traction, enhancing osseointegration and shortening recovery periods across implant procedures.
- Dental labs will adopt AI-driven design software, boosting demand for biomaterials compatible with high-speed additive manufacturing.
- Bioactive glass composites will enter mainstream restorative dentistry, delivering sustained antimicrobial protection and stimulating tissue regeneration.
- Public dental programs in emerging economies will increase reimbursement, expanding access to premium prosthetic materials.
- Green dentistry initiatives will push manufacturers toward recyclable packaging and carbon-neutral production processes.
- Customized pediatric crowns using flexible polymers will address growing demand for child-friendly restorative solutions.
- Regional manufacturing hubs in Asia Pacific will cut lead times and reduce pricing disparities across global markets.
- Cross-industry collaborations with orthopedic material specialists will accelerate innovation in high-strength, lightweight dental alloys.
- Cloud-based training platforms will upskill dentists in rural areas, spurring wider adoption of advanced biomaterials.
- Regulatory harmonization across major markets will streamline approvals, enabling faster global rollouts of next-generation products.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Prevalence of Dental Disorders and Surgical Interventions
The increasing incidence of dental diseases such as caries, periodontal disease, and tooth loss is expanding the patient base requiring restorative and reconstructive dental procedures. This drives demand for advanced biomaterials used in implants, bridges, and dentures, especially as the global population ages and surgical interventions become more common.
Rising Demand for Cosmetic Dentistry and Aesthetic Restorations
Heightened awareness of dental aesthetics, influenced by media and self-image trends, is fueling the uptake of cosmetic procedures like veneers, crowns, and aesthetic restorations. This trend encourages the adoption of high-performance biomaterials that offer natural appearance, durability, and patient comfort.
Advancements in Biocompatible and Regenerative Materials
Ongoing R&D in nanomaterials, bioactive ceramics, and regenerative biomaterials is enhancing the functionality, integration, and longevity of dental treatments. These innovations improve clinical outcomes, reduce recovery times, and support the shift toward minimally invasive, patient-specific solutions.
Expansion of Dental Infrastructure and Healthcare Investments
Increased investments in dental care infrastructure, especially in emerging markets, are improving access to quality dental services. Government initiatives, public-private partnerships, and the growth of dental insurance coverage are making advanced biomaterials more accessible to a broader population.
Integration of Digital Dentistry and 3D Printing
The adoption of digital workflows, CAD/CAM technology, and 3D printing in dental practices is accelerating the use of biomaterials compatible with these systems. This enables custom, precise, and rapid fabrication of prosthetics and restorations, further driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Dental Biomaterials Market?
What are the key segments within the Dental Biomaterials Market?
How do dental biomaterials contribute to patient care and treatment outcomes?
What factors influence the growth and trends within the dental biomaterial market?
How do dental professionals ensure the quality and safety of biomaterials used in patient care?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Metallic Biomaterials
- 1.2.2 Ceramic Biomaterials
- 1.2.3 Polymeric Biomaterials
- 1.2.4 Metal-Ceramic Biomaterials
- 1.2.5 Natural Biomaterials
- 1.2.6 Composites Biomaterials
- 1.3 By End-use
- 1.3.1 Dental Hospitals and Clinics
- 1.3.2 Dental Laboratories
- 1.3.3 Dental Academies and Research Institutes
- 1.3.4 Dental Product Manufacturers
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Implantology
- 1.4.2 Orthodontics
- 1.4.3 Prosthodontics
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,110.46 million → 2032: USD 2,046.50 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dental Biomaterials Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dental Biomaterials Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dental Biomaterials Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dental Biomaterials Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dental Biomaterials Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dental Biomaterials Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dental Biomaterials Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dental Biomaterials Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,110.46 million → 2032: USD 2,046.50 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dental Biomaterials Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Metallic Biomaterials
- 12.3.7.2 Ceramic Biomaterials
- 12.3.7.3 Polymeric Biomaterials
- 12.3.7.4 Metal-Ceramic Biomaterials
- 12.3.7.5 Natural Biomaterials
- 12.3.7.6 Composites Biomaterials
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Dental Hospitals and Clinics
- 12.4.7.2 Dental Laboratories
- 12.4.7.3 Dental Academies and Research Institutes
- 12.4.7.4 Dental Product Manufacturers
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Implantology
- 12.5.7.2 Orthodontics
- 12.5.7.3 Prosthodontics
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dental Biomaterials End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Dental Biomaterials Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Dental Biomaterials Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Dental Biomaterials Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Straumann Holding AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Geistlich Pharma AG
- 18.4 Zimmer Biomet Holdings, Inc.
- 18.5 Dentsply Sirona, Inc.
- 18.6 Danaher Corporation
- 18.7 3M Company
- 18.8 Ivoclar Vivadent AG
- 18.9 GC Corporation
- 18.10 Kuraray Co., Ltd.
- 18.11 Henry Schein, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

