
Market Overview:
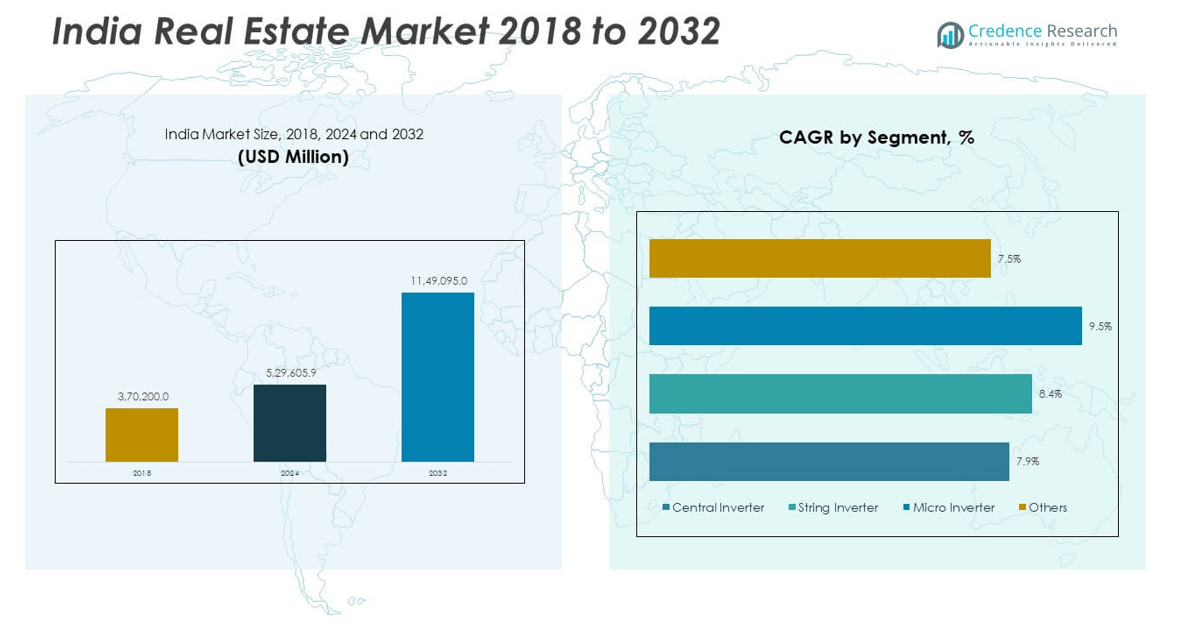
The India Real Estate Market size was valued at USD 3,70,200.0 million in 2018 to USD 5,29,605.9 million in 2024 and is anticipated to reach USD 11,49,095.0 million by 2032, at a CAGR of 10.30% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Real Estate Market Size 2024 | USD 5,29,605.9 million |
| India Real Estate Market, CAGR | 10.30% |
| India Real Estate Market Size 2032 | USD 11,49,095.0 million |
The market growth is fueled by rapid urbanization, rising disposable incomes, and government initiatives such as affordable housing schemes and smart city projects. The expanding middle-class population is driving demand for residential spaces, while growth in retail, IT, and manufacturing sectors boosts commercial real estate. Foreign direct investments and reforms such as Real Estate Regulatory Authority (RERA) have strengthened transparency, enhancing investor confidence. Increased adoption of digital platforms for property transactions and the demand for sustainable and energy-efficient buildings are also contributing to market expansion.
Regionally, metropolitan hubs such as Delhi-NCR, Mumbai, and Bengaluru dominate the market due to strong infrastructure, higher employment opportunities, and growing investor activity. Tier-II and Tier-III cities are emerging as high-potential markets, driven by rising affordability, improved connectivity, and expansion of industrial corridors. Southern cities such as Hyderabad and Chennai are gaining traction in the IT and residential segments, while western regions including Pune and Ahmedabad are attracting investments in logistics and industrial real estate. This regional diversification is shaping India into a balanced and opportunity-rich real estate market.
Market Insights:
- The India Real Estate Market size was valued at USD 3,70,200.0 million in 2018, reached USD 5,29,605.9 million in 2024, and is projected to touch USD 11,49,095.0 million by 2032, growing at a CAGR of 10.30% during the forecast period.
- Rapid urbanization, smart city projects, and large-scale infrastructure investments continue to boost demand across residential, commercial, and industrial real estate segments.
- Expanding middle-class population and rising disposable incomes increase housing demand in both premium and affordable segments.
- Regulatory frameworks like RERA and GST enhance transparency and streamline the sector, improving buyer and investor confidence.
- High construction costs, project delays, and financing hurdles remain significant restraints that impact timely project delivery and affordability.
- Metropolitan hubs including Delhi-NCR, Mumbai, and Bengaluru dominate growth due to strong connectivity, employment generation, and investment appeal.
- Tier-II and Tier-III cities emerge as high-potential markets with rising affordability, industrial expansion, and improved infrastructure networks.
Market Drivers:
Rapid Urbanization and Expanding Infrastructure Investments:
The India Real Estate Market benefits from strong urbanization trends supported by major infrastructure projects. Metropolitan areas continue to attract both domestic and global investors due to better connectivity and expanding business opportunities. The government’s push for urban renewal programs, metro expansions, and expressway networks improves accessibility and raises property values. Rising migration to tier-I and tier-II cities drives higher demand for both residential and commercial spaces. Affordable housing schemes and urban planning reforms further create long-term growth opportunities. Investment in industrial corridors and smart cities strengthens the ecosystem for sustained development. Growing household incomes and lifestyle aspirations accelerate housing demand in both premium and mid-segment categories. It positions urban centers as critical anchors for future real estate growth.
Growing Middle-Class Demand and Shifts in Lifestyle Preferences:
The expanding middle-class population acts as a core driver of growth in the India Real Estate Market. Consumers are now prioritizing ownership of modern homes with advanced amenities and security features. Shifts in lifestyle patterns create demand for integrated townships and gated communities. Young professionals and nuclear families prefer compact yet high-quality housing located near employment hubs. Rising disposable incomes enable aspirational buyers to consider luxury apartments and branded residences. Retail real estate also benefits from lifestyle-driven demand for malls, multiplexes, and shopping districts. Commercial projects in IT and business parks attract both domestic companies and multinational corporations. It ensures steady momentum for both residential and commercial segments across regions.
- For instance, Godrej Properties launched the "Godrej Athena" project in Bengaluru with over a dozen smart amenities and achieved 95% pre-booking of its units within the first three months of launch in 2025. Oberoi Realty delivered over 2,500 luxury apartments integrated with IoT-enabled smart home features, while Brigade Group reported in FY2025 that more than 75% of its city-center township sales were to first-time urban nuclear families seeking compact, tech-enabled homes.
Regulatory Reforms and Enhanced Transparency Measures:
The India Real Estate Market experiences accelerated growth due to strong policy reforms and regulatory frameworks. The implementation of RERA enforces accountability and instills confidence in buyers and investors. GST rationalizes taxation across the sector, streamlining processes for both developers and purchasers. Foreign direct investment policies open new opportunities for global capital inflows. Policy incentives for affordable housing reduce entry barriers for developers and buyers. These reforms create a transparent, efficient, and sustainable growth environment. Developers are adopting ethical practices to align with the strengthened compliance requirements. Buyers increasingly trust the regulated ecosystem, fueling greater market participation. It ensures long-term credibility and stability for the sector.
Expanding Commercial Sector and Rise of Organized Retail:
The India Real Estate Market gains traction from the expanding commercial sector and large-scale retail investments. IT hubs, co-working spaces, and corporate campuses fuel rising demand for grade-A office spaces. Retail real estate benefits from the entry of international brands and expansion of shopping centers. E-commerce companies invest heavily in logistics and warehousing facilities, boosting industrial real estate. Strong demand for organized retail hubs drives mixed-use developments that combine shopping, leisure, and housing. Developers are focusing on integrated projects that cater to both professional and consumer needs. The rise of corporate campuses in metro and tier-II cities generates consistent demand for commercial assets. It strengthens investor interest and enhances the sector’s overall dynamism.
Market Trends:
Adoption of Digital Platforms and Virtual Property Transactions:
The India Real Estate Market is undergoing a digital transformation with wider adoption of online property platforms. Buyers and investors rely on virtual tours, 3D walkthroughs, and AI-enabled tools to evaluate projects remotely. Real estate portals enhance decision-making with transparent data on pricing, legal clearances, and neighborhood analysis. Developers are integrating digital marketing strategies to target specific customer segments. The pandemic accelerated the use of digital tools, making online engagement a permanent feature of property buying. Digital mortgage processing and automated verification further streamline property ownership. Virtual transactions attract younger buyers who prefer seamless digital experiences. It creates a competitive advantage for developers with robust online platforms.
- For instance, Lodha Group saw 48% of new flat bookings for its Mumbai launches in 2025 completed through digital platforms offering full virtual tours and online contracts. NoBroker processed more than 220,000 verified online property transactions between April 2024 and March 2025, leveraging AI for pricing, legal validation, and remote documentation.
Sustainability and Eco-Friendly Housing Developments:
The India Real Estate Market embraces sustainability by integrating green designs and energy-efficient technologies. Developers focus on LEED-certified projects and eco-friendly construction practices. Rising consumer awareness about environmental impact drives demand for solar power, rainwater harvesting, and energy-efficient appliances. Institutional investors favor sustainable projects, recognizing their long-term value and lower operational costs. Builders are introducing recyclable materials and innovative building methods that reduce environmental footprint. Government policies encourage green buildings with tax incentives and regulatory support. Eco-friendly housing resonates strongly with young professionals and environmentally conscious buyers. It positions sustainability as a defining trend shaping the future of real estate projects.
- For instance, Tata Housing has integrated solar power and rainwater harvesting across several projects. Its project Tata Housing Myst (Kasauli) became one of India’s first residential projects with IGBC pre-certified Platinum rating.
Rise of Co-Living and Flexible Housing Models:
The India Real Estate Market sees increasing adoption of co-living spaces driven by millennial and Gen Z preferences. Young professionals migrating to cities prefer cost-efficient, flexible, and community-driven living arrangements. Developers are collaborating with operators to offer shared housing solutions near employment zones. The model caters to affordability concerns while providing modern amenities and digital connectivity. Flexible leasing options appeal to transient workforces and students. Investors find co-living attractive for steady rental yields and lower vacancy rates. Co-living also aligns with cultural shifts toward shared consumption and collaborative lifestyles. It establishes a new growth avenue beyond conventional housing models.
Growth in Mixed-Use and Smart City Developments:
The India Real Estate Market expands through integrated projects combining residential, commercial, and retail functions. Developers are focusing on mixed-use complexes that create self-sustained ecosystems. Smart city initiatives incorporate digital connectivity, intelligent traffic management, and energy efficiency. Residents prefer these projects for convenience, reduced travel times, and enhanced quality of life. Corporates and retailers benefit from proximity to large residential catchments. Investors see mixed-use assets as resilient against market volatility due to diversified revenue streams. Rapid urban expansion makes such developments critical for future-ready cities. It reinforces the role of integrated planning in shaping real estate growth.
Market Challenges Analysis:
High Construction Costs and Delayed Project Deliveries:
The India Real Estate Market faces persistent challenges due to high construction costs and frequent project delays. Rising prices of steel, cement, and labor inflate overall costs for developers. Many projects struggle to maintain profitability while balancing affordability. Delayed government approvals and land acquisition hurdles further prolong timelines. Buyers lose confidence when possession dates extend, creating reputational risks for developers. Stalled projects tie up capital and reduce liquidity across the sector. Developers often face funding shortages as lenders grow cautious about delayed ventures. It creates operational inefficiencies that slow sectoral growth despite rising demand.
Limited Financing Access and Regulatory Complexities:
The India Real Estate Market is also constrained by restricted access to affordable financing and complex regulations. Small and mid-sized developers struggle to secure funding due to stringent lending criteria. Private equity funds often prefer large players, leaving smaller firms undercapitalized. Regulatory compliance with multiple state and central bodies creates administrative burdens. Lengthy approval cycles increase costs and reduce efficiency. Buyers also face financing difficulties due to strict loan-to-value requirements and high interest rates. These limitations restrict participation across consumer and developer segments. It underscores the need for balanced financial support and simplified governance structures.
Market Opportunities:
Rising Demand in Tier-II and Tier-III Cities:
The India Real Estate Market offers opportunities in emerging tier-II and tier-III cities due to improving infrastructure. These cities attract IT parks, logistics hubs, and manufacturing facilities that stimulate real estate growth. Affordable housing demand rises in smaller towns with increasing middle-class populations. Improved highways and regional airports enhance connectivity, boosting investor interest. Developers expand into these cities to capture untapped demand across segments. Rising aspirations among young professionals create momentum for modern housing solutions. Retail and commercial projects also see growing traction in expanding urban clusters. It strengthens the long-term potential of non-metro markets.
Expansion of Industrial and Warehousing Real Estate:
The India Real Estate Market also sees opportunities in the industrial and warehousing segment. E-commerce growth creates large-scale demand for storage and distribution centers. Logistics players invest in modern warehouses with advanced technology and automation. Government initiatives like dedicated freight corridors support this transformation. Manufacturing expansion under “Make in India” drives industrial land requirements. Global firms seek reliable logistics and supply chain infrastructure, encouraging investment. Developers diversify portfolios by including industrial assets for stable returns. It positions warehousing and industrial real estate as growth engines of the sector.
Market Segmentation Analysis:
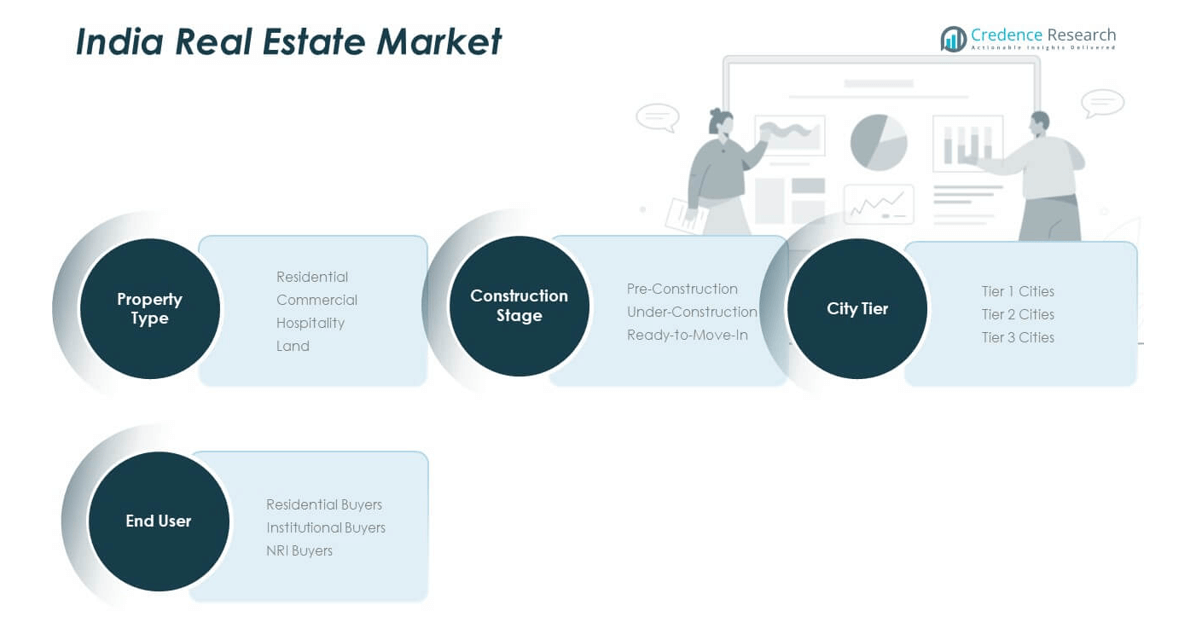
By Property Type
Residential holds the largest share, driven by rising urban housing demand and favorable mortgage access. Commercial assets benefit from corporate expansions and IT parks, while hospitality projects gain traction in tourism-driven regions. Land remains attractive for investors seeking long-term appreciation.
- For instance, Mindspace Business Parks REIT leased over 1.7 million sq ft in Q1 FY25 to global and Indian firms for GCCs and data centres across Mumbai.
By Construction Stage
Pre-construction and under-construction projects draw investors with lower entry points and potential value gains. Ready-to-move-in properties attract end-users prioritizing immediate occupancy, lower risk, and established infrastructure.
By City Tier
Tier 1 cities dominate due to premium projects, advanced infrastructure, and employment opportunities. Tier 2 cities are emerging as high-growth hubs, supported by government policies, rising affordability, and expanding connectivity. Tier 3 cities show gradual growth, primarily through affordable housing and regional development initiatives.
By End-User
Residential buyers form the largest segment, supported by middle-class aspirations and financing availability. Institutional buyers strengthen demand in commercial and retail segments, ensuring stability. NRI buyers focus on luxury housing and metropolitan markets, leveraging currency benefits and long-term returns.
Segmentation:
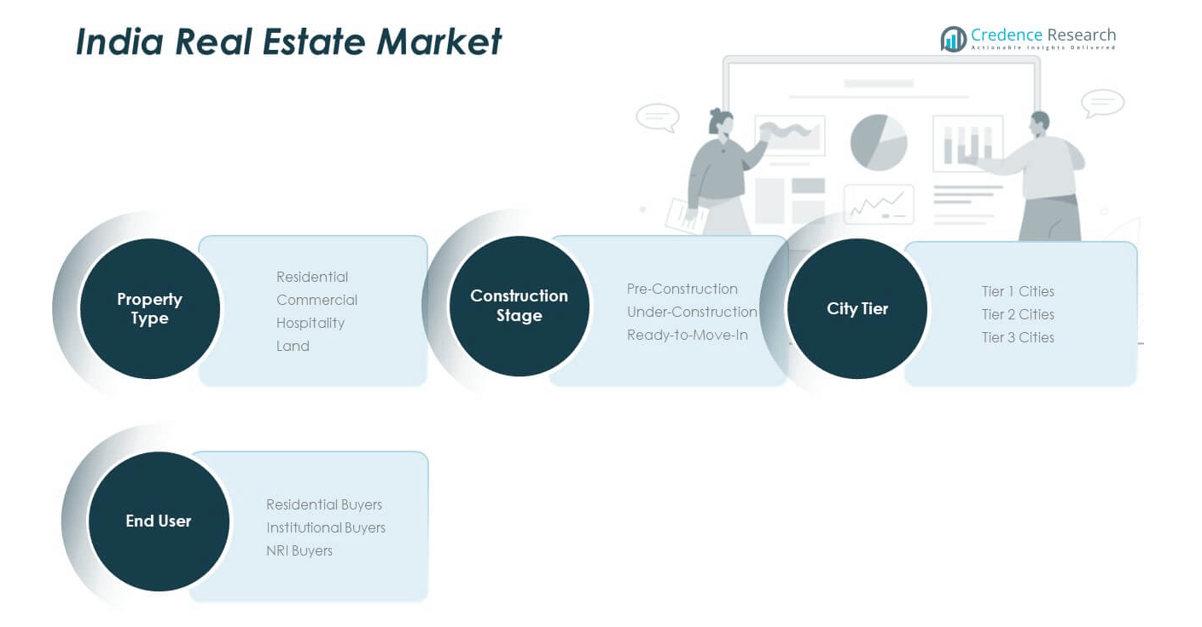
By Property Type
- Residential
- Commercial
- Hospitality
- Land
By Construction Stage
- Pre-Construction
- Under-Construction
- Ready-to-Move-In
By City Tier
- Tier 1 Cities
- Tier 2 Cities
- Tier 3 Cities
By End-User
- Residential Buyers
- Institutional Buyers
- NRI Buyers
Regional Analysis:
North India
North India dominates the India Real Estate Market with an estimated 35% share, led by the National Capital Region (NCR), which includes Delhi, Gurugram, and Noida. Strong demand for both residential and commercial projects in Gurugram and Noida has been driven by infrastructure development, corporate hubs, and proximity to the capital. Delhi NCR continues to attract large-scale investments in premium housing, IT parks, and retail spaces. Rising metro connectivity and upcoming expressways have strengthened investor confidence in this region. It also benefits from strong government focus on affordable housing and smart city projects. The combination of urban expansion and regulatory support positions North India as the most influential regional contributor.
West India
West India holds nearly 30% share of the India Real Estate Market, with Mumbai Metropolitan Region (MMR) and Pune as major growth centers. MMR, being the financial hub of India, attracts significant investments in luxury housing, commercial office spaces, and retail developments. Pune is witnessing rapid growth in IT parks, industrial corridors, and co-living spaces, driven by its expanding technology sector and student population. Gujarat, with cities like Ahmedabad, is also emerging due to smart city projects and industrial clusters. The presence of strong employment opportunities fuels continuous housing demand in this region. It remains a preferred destination for both end-users and institutional investors.
South and East India
South India accounts for around 25% share, driven by Bengaluru, Hyderabad, and Chennai. Bengaluru leads in IT-driven residential and commercial real estate demand, while Hyderabad benefits from strong government incentives and rapid infrastructure upgrades. Chennai maintains growth through manufacturing hubs and port-based industries. East India holds a smaller 10% share, led by Kolkata, Bhubaneswar, and Patna, where demand is rising due to urbanization and affordable housing initiatives. Although East India lags in large-scale developments, it shows potential with government-backed infrastructure and industrial projects. Together, South and East India strengthen the geographical diversity of the market by catering to varied consumer and investor segments.
Key Player Analysis:
- DLF Limited
- Godrej Pro
- Oberoi Realty
- perties
- Oberoi Realty
- Prestige Estates Projects Ltd.
- Sobha Limited
- Brigade Group
- Tata Housing
- Lodha Group
- Indiabulls Real Estate
- Puravankara
- Mahindra Lifespace Developers
- Shapoorji Pallonji Real Estate
- L&T Realty
- Raheja Developers
- Hiranandani Group
Competitive Analysis:
The India Real Estate Market is highly competitive, with leading developers such as DLF, Godrej Properties, Oberoi Realty, Prestige Estates, and Lodha Group shaping the landscape. It reflects a mix of established firms with nationwide presence and regional players targeting niche markets. Companies compete on pricing, location, design, and timely delivery, while differentiation strategies focus on sustainability, smart housing, and premium amenities. Institutional investors and foreign capital flows strengthen competition, driving consolidation and strategic partnerships. It remains dynamic, where brand reputation, project execution, and financial strength play a decisive role in capturing market share.
Recent Developments:
- In August 2025, DLF Limited announced the launch of residential and commercial projects worth ₹63 billion across multiple segments in the Indian real estate market. These launches include prime developments in Mumbai with the luxury 'Westpark' residential project marking DLF's re-entry into the city outside its traditional Delhi-NCR base. The company set a target to sell properties worth ₹20,000–22,000 crore during 2025–26, expanding pan-India aspirations.
- In August 2025, Godrej Properties unveiled plans to launch new residential projects worth ₹40,000 crore for the 2025–26 financial year, aiming to boost its market share across major Tier-I cities. In July 2025, Godrej Properties acquired 50 acres of land in Raipur, Chhattisgarh, for a premium plotted residential project near Old Dhamtari Road, marking its entry into the fast-developing corridor and strengthening its footprint in new geographies.
- In April 2025, Oberoi Realty Limited launched Elysian Tower D in Oberoi Garden City, Goregaon, Mumbai. This luxury tower recorded gross bookings of around ₹970 crore for nearly 2.1 lakh sq. ft. of carpet area. The Elysian project is part of Oberoi’s integrated township development, designed for premium urban residences with curated amenities.
Market Concentration & Characteristics:
The India Real Estate Market is moderately concentrated, with a few dominant players controlling significant market share across urban hubs, while regional developers cater to local demand. It is characterized by high capital intensity, cyclical demand patterns, and strong regulatory influence. Competitive differentiation emerges from sustainability practices, digital integration, and large-scale township projects. It remains sensitive to macroeconomic conditions, policy reforms, and consumer sentiment.
Report Coverage:
The research report offers an in-depth analysis based on Property Type and Construction Stage. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for residential housing will accelerate with urbanization and rising income levels.
- Commercial real estate will expand with IT hubs and co-working spaces gaining traction.
- Tier 2 cities will attract investments due to infrastructure growth and affordability.
- NRI participation will strengthen in luxury and metro-based projects.
- Affordable housing will remain a key driver, supported by government initiatives.
- Adoption of green buildings and smart technologies will enhance project value.
- Institutional investment will increase in warehousing, retail, and office segments.
- Consolidation among developers will intensify competition and improve efficiency.
- Policy reforms and RERA enforcement will ensure transparency and accountability.
- Market resilience will depend on economic growth, interest rates, and consumer confidence.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Urbanization and Infrastructure Investments
India's ongoing urbanization, supported by large-scale infrastructure projects such as metro expansions, expressways, and smart city initiatives, is driving demand for both residential and commercial real estate. Improved connectivity and urban renewal programs are raising property values and attracting both domestic and foreign investors.
Expanding Middle-Class and Lifestyle Shifts
The growing middle-class population, coupled with rising disposable incomes, is fueling demand for modern, amenity-rich housing and integrated townships. Young professionals and nuclear families are seeking compact, tech-enabled homes near employment hubs, boosting both premium and affordable housing segments.
Regulatory Reforms and Enhanced Transparency
Implementation of RERA and GST has increased transparency, accountability, and efficiency in the real estate sector, improving buyer and investor confidence. These reforms, along with relaxed FDI norms, have attracted institutional capital and encouraged ethical practices among developers.
Growth in Commercial, Retail, and Industrial Segments
Expansion of IT parks, co-working spaces, organized retail, and logistics hubs is driving demand for commercial and industrial real estate. E-commerce growth and the 'Make in India' initiative are further boosting the need for warehousing and industrial assets, diversifying the market beyond residential projects.
Digital Transformation and Sustainable Development
Widespread adoption of digital platforms for property transactions and the integration of green building practices are reshaping the market. Virtual tours, online contracts, and eco-friendly construction are attracting tech-savvy and environmentally conscious buyers, enhancing market competitiveness and long-term value.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for India Real Estate Market, and what is its projected size in 2032?
Which India Real Estate Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the India Real Estate Market?
Who are the leading companies in the India Real Estate Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Residential Buyers
- 1.2.2 Institutional Buyers
- 1.2.3 NRI Buyers
- 1.3 By City Tier
- 1.3.1 Tier 1 Cities
- 1.3.2 Tier 2 Cities
- 1.3.3 Tier 3 Cities
- 1.4 By Property Type
- 1.4.1 Residential
- 1.4.2 Commercial
- 1.4.3 Hospitality
- 1.4.4 Land
- 1.5 By Construction Stage
- 1.5.1 Pre-Construction
- 1.5.2 Under-Construction
- 1.5.3 Ready-to-Move-In
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,29,605.9 million → 2032: USD 1,149,095.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Real Estate Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Real Estate Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Real Estate Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Real Estate Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Real Estate Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Real Estate Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Real Estate Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Real Estate Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,29,605.9 million → 2032: USD 1,149,095.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Real Estate Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential Buyers
- 12.3.7.2 Institutional Buyers
- 12.3.7.3 NRI Buyers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By City Tier - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Tier 1 Cities
- 12.4.7.2 Tier 2 Cities
- 12.4.7.3 Tier 3 Cities
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Property Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Residential
- 12.5.7.2 Commercial
- 12.5.7.3 Hospitality
- 12.5.7.4 Land
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Construction Stage - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Pre-Construction
- 12.6.7.2 Under-Construction
- 12.6.7.3 Ready-to-Move-In
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 India Real Estate End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 India Real Estate Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 India Real Estate Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 India Real Estate Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DLF Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Godrej Properties
- 18.4 Oberoi Realty
- 18.5 Prestige Estates Projects Ltd.
- 18.6 Sobha Limited
- 18.7 Brigade Group
- 18.8 Tata Housing
- 18.9 Lodha Group
- 18.10 Indiabulls Real Estate
- 18.11 Puravankara
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

