
Rural gaps and mobile carriers shape home 5G demand
The Canada 5G fixed wireless access (FWA) market was valued at USD 486.3 million in 2025 and is projected to increase from USD 548.6 million in 2026 to USD 1.62 billion by 2035, registering a CAGR of 12.80% during 2026–2035. Demand comes from rural and small-town households that lack wired broadband, from mobile customers who take home internet as a bundle, and from small businesses, seasonal sites and public offices that need a fast connection without a cable or fiber line. Ontario held the largest regional share, 33.0% in 2025, while the Prairie Provinces are the fastest-growing region at 13.7% a year as rural Alberta and Saskatchewan receive publicly funded tower upgrades. The most important commercial change is the move from LTE to 5G gateways that use mid-band spectrum, including the 3800 MHz licenses sold in 2023. Competition from low earth orbit satellite service and new rural fiber remains the main restraint.
Home and business lines over mobile spectrum make up the market
The market counts what buyers in Canada pay for 5G fixed wireless service plans, for the indoor and outdoor gateways that convert the cellular signal into home or office Wi-Fi, and for femto, pico and access units that operators install to add fixed wireless capacity. Households and businesses buy service monthly from national carriers, regional operators and rural specialists, usually with the gateway included or rented.
Mobile phone plans, mobile hotspots used on the move, legacy LTE-only fixed wireless products, unlicensed point-to-multipoint networks and satellite internet are excluded. The value chain runs from radio and gateway vendors through carriers that own spectrum to the end customer, and the widest margins sit with operators that sell spare mid-band capacity that is already built.
Canada 5G Fixed Wireless Access (FWA) Market Insights
- The Canada 5G fixed wireless access (FWA) market was valued at USD 486.3 million in 2025 and is projected to reach USD 1.62 billion by 2035 at a 12.80% CAGR.
- Ontario held 33.0% of 2025 value because it has the most households and the widest choice of carrier home 5G plans.
- Services held 66.0% of 2025 value, because operators recover gateway costs through monthly plans rather than device sales.
- Freedom Mobile launched invite-only 5G home internet in four provinces in December 2025, joining Rogers, Bell and TELUS in selling home service over a mobile network.
- Spectrum rules issued in May 2026 open 4.8 GHz of mmWave spectrum to an auction that starts in October 2027.
Services and rural lines lead while gateways grow fastest
Monthly service leads while indoor gateways grow fastest
Based on offering, the market is categorized into services, indoor CPE, outdoor CPE and femto and pico cells. Services led with 66.0% of 2025 value because carriers bundle the gateway into the plan, and Rogers charged CAD 60 to CAD 100 a month for its three 5G Home Internet tiers from July 2025. Indoor CPE grows fastest at 14.2% as self-installed gateways replace older units, with Freedom supplying a Nokia Wi-Fi 7 gateway at no upfront cost under a 24-month TradeUp offer from December 2025. Outdoor units stay concentrated among rural customers who live several kilometers from the nearest tower.
Rural lines lead while urban plans grow fastest
Based on demography, the market is categorized into rural, semi-urban and urban. Rural areas led with 47.0% of 2025 value because fixed wireless often fills the gap left by cable and fiber, and Xplore says its 5G fixed wireless network is planned to reach more than 1.5 million homes across Canada. Urban areas grow fastest at 13.8% as carriers sell home 5G to renters, students and newcomers, the groups Rogers named when it relaunched the service at CAD 50 a month in March 2024. Urban growth depends on how much spare capacity each city cell site still has.
Sub-6 GHz radios carry nearly all lines today
Based on operating frequency, the market is categorized into sub-6 GHz and 24 GHz and above (mmWave). Sub-6 GHz led with 97.0% of 2025 value because carriers run home 5G on the mid-band holdings bought at auction, and the November 2023 auction alone sold 4,099 licenses to 20 winning bidders. 24 GHz and Above (Millimeter Wave) grows fastest at 21.7% from a very small base, because ISED will auction new 26 GHz and 38 GHz spectrum from October 2027. Until those licenses issue, mmWave lines remain mostly point-to-point links for enterprise sites.
Households lead while business sites grow fastest
Based on application, the market is categorized into residential, commercial, industrial and government. Residential buyers led with 76.0% of 2025 value because home plans are sold through mobile accounts, and Freedom priced its 200 GB home plan at CAD 24 a month for mobile customers against CAD 60 standalone. Commercial users grow fastest at 13.8% as Rogers sells 5G Business Internet at CAD 60 to CAD 80 a month for offices, seasonal businesses and construction trailers. Industrial demand stays small and is bought project by project for mines, farms and remote work camps.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Offering | Services | 66.0% | Indoor CPE | 14.2% |
| By Demography | Rural | 47.0% | Urban | 13.8% |
| By Operating Frequency | Sub-6 GHz | 97.0% | 24 GHz and Above (Millimeter Wave) | 21.7% |
| By Application | Residential | 76.0% | Commercial | 13.8% |
Home 5G plans sell at CAD 60 to 100 a month
Fixed wireless is priced per month by data allowance and speed tier, and the gateway is usually included or rented, so operators recover hardware through the plan rather than at the till. Data caps are the main price lever, because each gigabyte uses shared cell capacity, which is why Rogers slows lines to 10 Mbps after the allowance instead of charging overage fees. Bundling moves prices most, since Freedom cuts its home plan by more than half for mobile customers. Legacy fixed wireless costs more per megabit, so 5G gateways let operators raise speeds without raising prices, which protects margins while winning customers from older rural products.
| Plan or item | Typical price or fee | Basis |
|---|---|---|
| Rogers 5G Home Internet Essentials, 200 GB, up to 100 Mbps | CAD 60 a month | Rogers plan as reported by iPhone in Canada, July 2025 |
| Rogers 5G Home Internet Ultimate, 1,000 GB, up to 500 Mbps | CAD 100 a month | Rogers plan as reported by iPhone in Canada, July 2025 |
| Freedom 5G Home Internet, 200 GB, up to 100 Mbps | CAD 24 with a mobile plan, CAD 60 standalone | Freedom Mobile launch pricing, December 2025 |
| Rogers 5G Business Internet Office Pro, 600 GB, up to 250 Mbps | CAD 80 a month | Rogers business price list, November 2026 |
| SaskTel fusion 10 legacy fixed wireless, 100 GB, up to 10 Mbps | CAD 99.95 a month plus CAD 249 equipment | SaskTel price list, November 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Funding, mid-band spectrum and cheap gateways lift demand
Public funding pays for rural fixed wireless towers
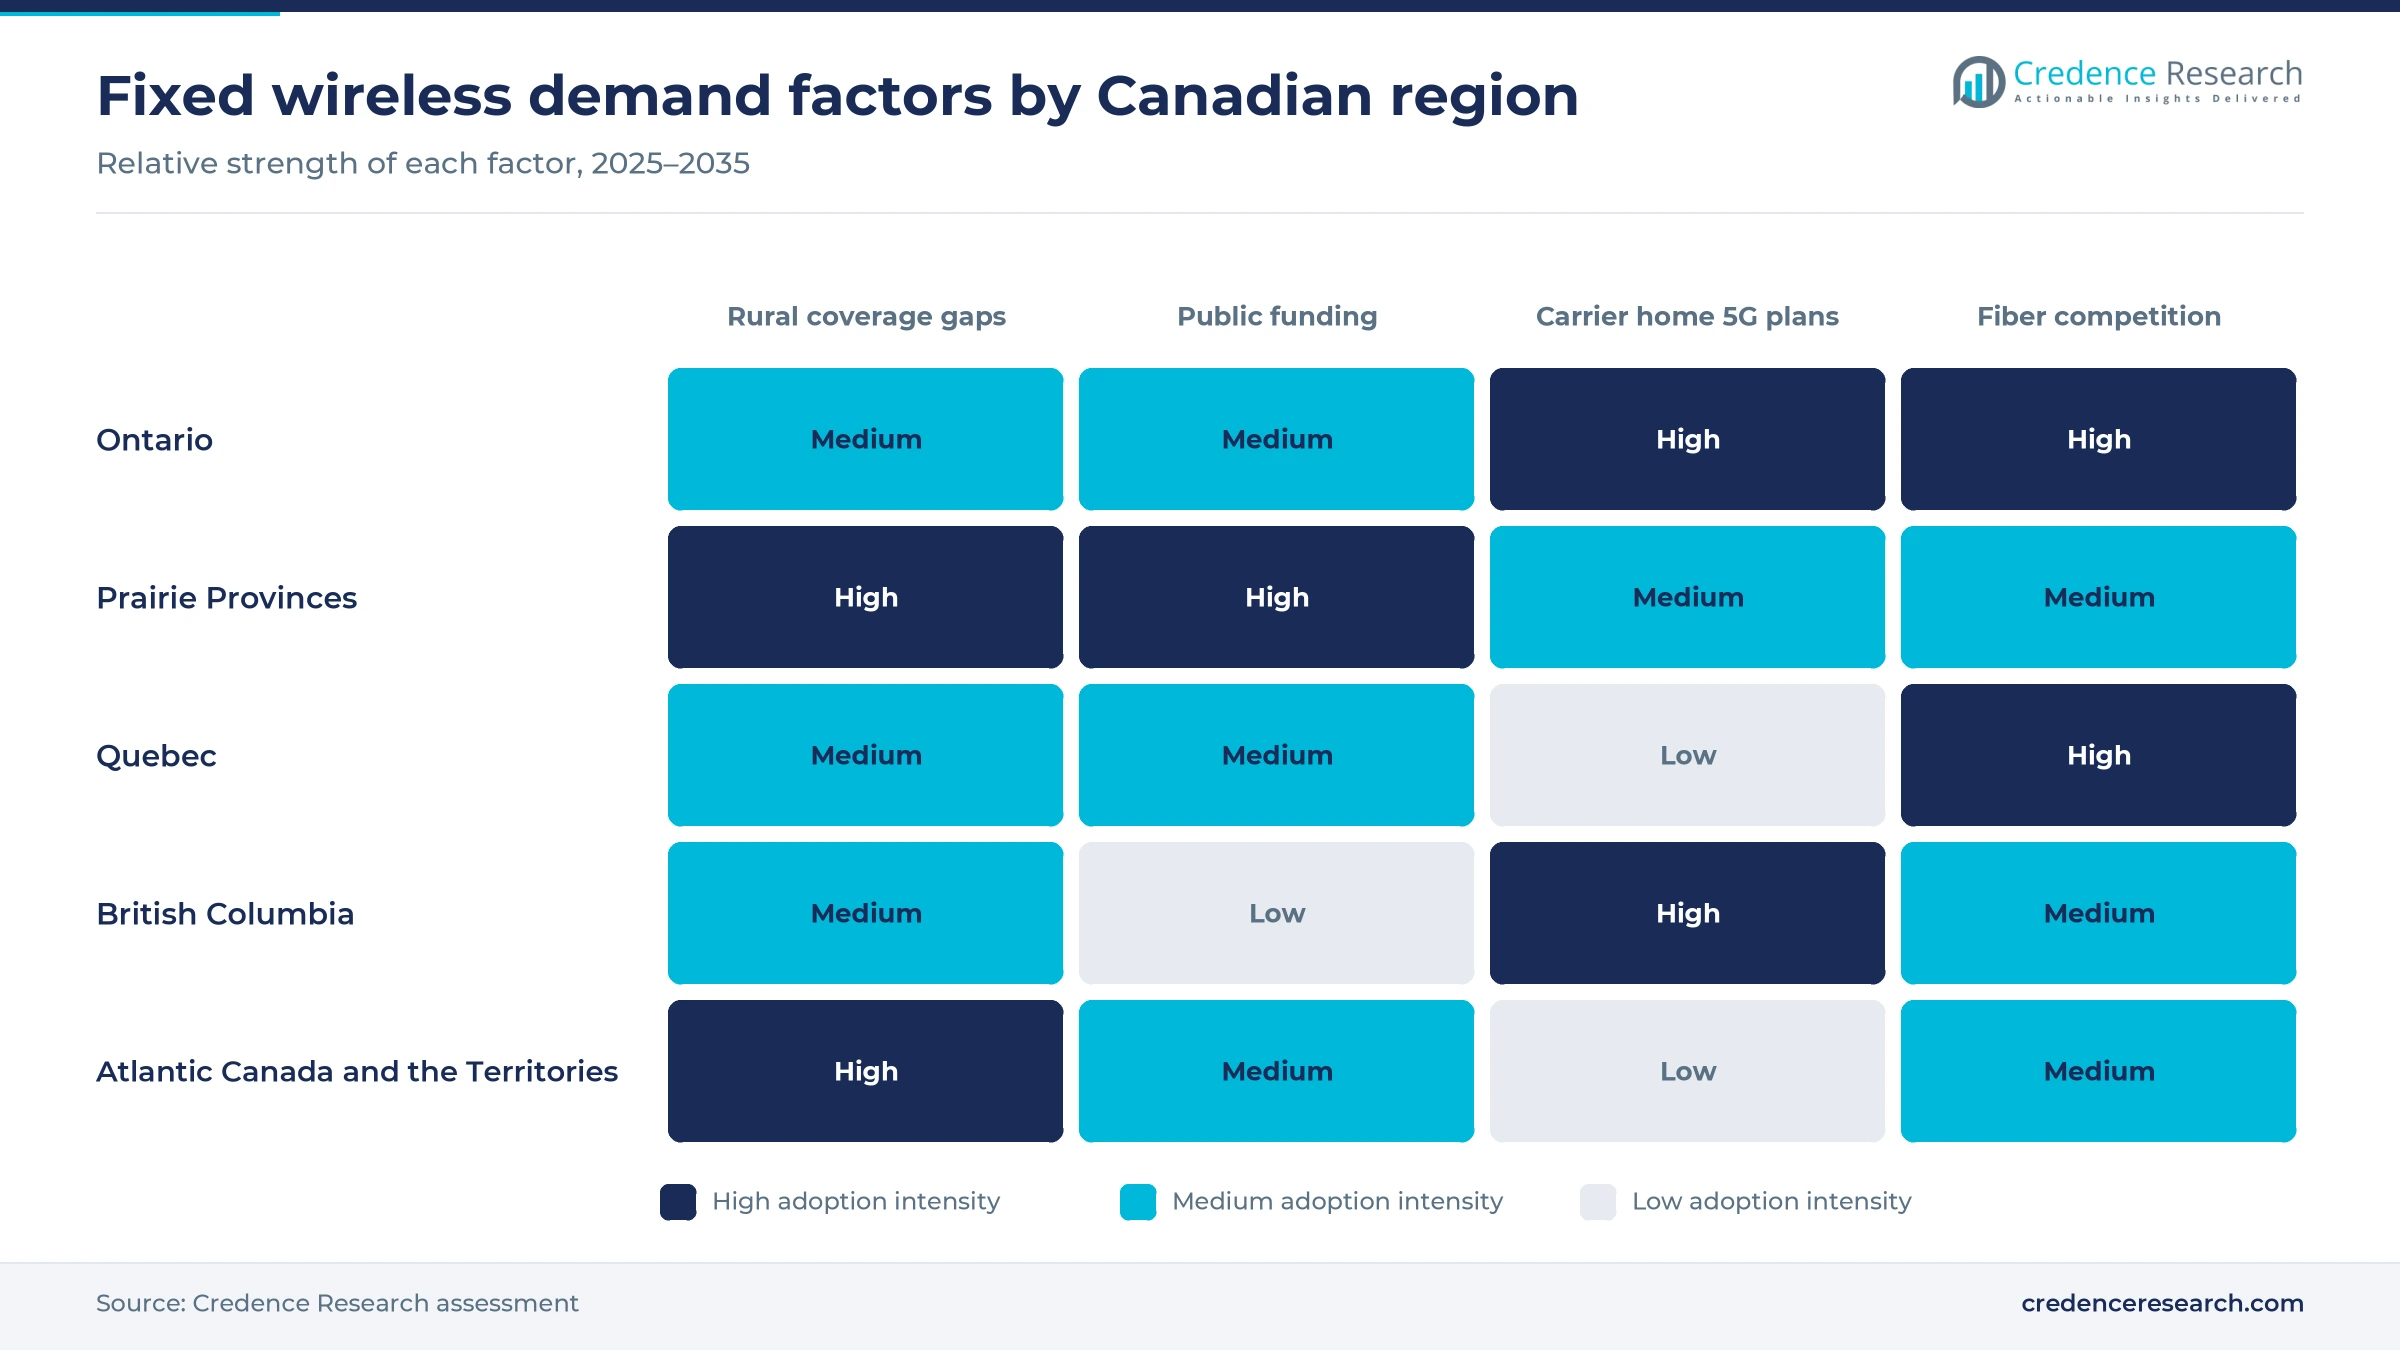
Federal and provincial broadband programs lower the cost of building fixed wireless in places where wired lines do not pay back, which turns rural households into paying customers. Xplore will receive CAD 60 million in combined federal and provincial funding and invest more than CAD 120 million to bring 5G Ultra service to more than 70,000 underserved Alberta households over more than 400 towers, according to Xplore. In July 2026, ISED funded four fixed wireless projects in Saskatchewan, including two Xplore projects for up to 18,103 households due by March 2027. The national target of 98% coverage at 50/10 Mbps by the end of 2026 keeps this money flowing. Operators that already own towers in the funded areas gain the most from each award.
Mid-band spectrum gives carriers capacity to sell
Mid-band spectrum gives carriers the spare capacity they need to sell home lines without slowing mobile users, which is the core economic condition for fixed wireless. TELUS paid CAD 619.64 million, Bell CAD 518.07 million and Rogers CAD 474.77 million in the 3800 MHz auction that closed in November 2023, adding to earlier 3500 MHz holdings. A combined cap across both bands let Videotron and other regional bidders secure capacity too. The CRTC reports that 5G reaches 93% of Canadians, so most households already sit inside a 5G footprint. Carriers with the deepest mid-band holdings per site can offer the largest data allowances.
Self-installed gateways cut the cost of each new line
Self-installed gateways remove the truck roll that made older fixed wireless expensive, which lowers the cost of adding each customer. Rogers ships a Nokia FastMile gateway that customers set up themselves with a placement app, with no technician appointment, and it moved its higher tiers to gateways with Wi-Fi 7 in July 2025. SaskTel still lists basic installation for its legacy fusion fixed wireless at CAD 99.99 on promotion against a regular CAD 489.99, which shows the cost that self-install avoids. TELUS also includes its Smart Hub hardware at no extra charge to customers. Gateway vendors such as Nokia benefit as each carrier standardizes on one or two indoor models.
Bundles with mobile plans make home 5G cheap to switch to
Bundling home internet with mobile plans lowers the effective price of fixed wireless, which persuades price-sensitive households to switch from cable or DSL. Freedom launched 5G home internet in December 2025 in Ontario, Manitoba, Alberta and British Columbia at CAD 24 a month for mobile customers, and the service ends three months after a mobile plan is cancelled. The CRTC says 50 GB mobile plans averaged CAD 40 in September 2024, about half the price a year earlier, so carriers now look to home lines for added revenue per account. Ericsson reports that 89% of North American providers it studied offered fixed wireless over 5G in April 2026. Carriers with large postpaid customer bases gain the most from these bundles.
Carriers bundle home 5G and rural builders upgrade towers
Rural builders are shifting from LTE to 5G fixed wireless
Rural operators are shifting their installed fixed wireless bases from LTE and legacy radios to 5G, creating openings for gateway and radio vendors across existing tower networks. Xplore launched 5G Ultra in March 2025 with speeds of up to 500 Mbps, ten times its most popular 50 Mbps plan, across select areas of Alberta, Saskatchewan, Manitoba, Ontario and all four Atlantic provinces. Its October 2024 recapitalization brought more than CAD 1.6 billion of new funding for fiber and 5G fixed wireless on a 1.6 billion MHz-POP spectrum portfolio. SaskTel still sells fusion plans at 5 Mbps and 10 Mbps, which shows how much legacy capacity remains to replace. Upgrades raise revenue per line, because customers move to higher tiers.
Carriers are moving radio networks to cloud and Open RAN
National carriers are shifting their radio networks toward virtualized and cloud designs to lower the cost per gigabyte, which matters most for data-heavy home lines. TELUS announced in February 2024 that it would build Canada's first commercial virtualized Open RAN network with Samsung, with large-scale rollout planned from mid-2024. Bell expanded its Nokia partnership in February 2025 to deploy Cloud RAN software and Open Fronthaul radios, and Ericsson remains the sole radio and core supplier for Rogers under its June 2020 award. Lower capacity costs let carriers widen data allowances on home plans. Vendors that win these software layers gain recurring license income.
The mmwave auction is an opening for dense urban lines
The coming mmWave auction is an opening for operators that want gigabit fixed wireless in dense neighborhoods and business districts where mid-band cells are full. ISED set rules in May 2026 for an auction of 4.8 GHz in the 26 GHz and 38 GHz bands, with a 1,200 MHz cap per bidder for five years and bidding from Oct. 19, 2027, according to MobileSyrup. TeraGo, which says it holds about 91% of current mmWave spectrum, can move existing licenses to flexible use and is running 5G fixed wireless trials. Vendors of millimeter wave technology gain the most once licenses issue, likely in 2028.
Business and temporary sites are a near-term opening
Small businesses and temporary sites are a near-term opening, because they need connectivity within days and cannot wait for a wired installation. Rogers sells 5G Business Internet Office plans at CAD 60 and CAD 80 a month on a Nokia 5G Gateway 12, aimed at seasonal businesses, construction trailers and pop-up retail, with no cancellation fees. TeraGo sells managed fixed wireless with service-level agreements in Toronto, Montreal, Calgary, Edmonton, Vancouver, Ottawa and Winnipeg, according to its May 2026 release. Bell said in September 2025 that it would add or upgrade 5G in 224 communities by early 2026. Carriers that pair home 5G with business backup lines raise revenue per site.
Capacity, satellite rivals and fiber builds cap growth
Shared cell capacity limits speed at peak hours
Fixed wireless shares cell capacity with mobile users, so speeds fall when neighbors stream at night. In the CRTC's January to February 2024 test of fixed wireless lines, average downloads were 51 Mbps over 24 hours and 48 Mbps at peak, and 54% of tests over 24 hours fell below the advertised 50 Mbps, according to the CRTC. Latency rose from 37 milliseconds on an idle line to 163 milliseconds during downloads and 398 milliseconds during uploads. Gamers and remote workers are most exposed, which is why operators cap data allowances.
Low earth orbit satellite service competes for rural homes
Low earth orbit satellite service competes directly for the rural homes that fixed wireless targets. Satellite plans need no tower within line of sight, which suits farms and cottages beyond fixed wireless range. The federal government has committed up to CAD 600 million to secure low earth orbit satellite capacity over Canada and a CAD 2.14 billion loan to Telesat Lightspeed, according to an ISED question period note. Operators with older towers and long distances to customers are most exposed, so 5G upgrades decide who keeps these homes.
Subsidized fiber builds remove future fixed wireless demand
Publicly funded fiber removes fixed wireless demand wherever it arrives, because rural households switch when a gigabit line becomes available. Xplore itself is investing CAD 200 million, including CAD 92 million of public money, to bring fiber-to-the-home service to about 24,000 rural Newfoundland households by early 2027. Bell added 58,643 residential fiber lines in Canada in the third quarter of 2026 alone. Fixed wireless operators in areas with approved fiber projects are most exposed, so they focus towers on places that fiber will not reach.
Legacy Prairie towers need costly 5G upgrades
SaskTel set CAD 111.5 million for 5G in its 2025/26 budget, including upgrades at more than 170 existing sites, because much of the Prairie fixed wireless base still runs on older radios. Its legacy fusion plans still top out at 5 Mbps or 10 Mbps, far below the 50/10 Mbps national target, so each customer kept needs a new radio and gateway. Prairie operators with long distances between towers and farms are most exposed, because each upgraded site serves few homes.
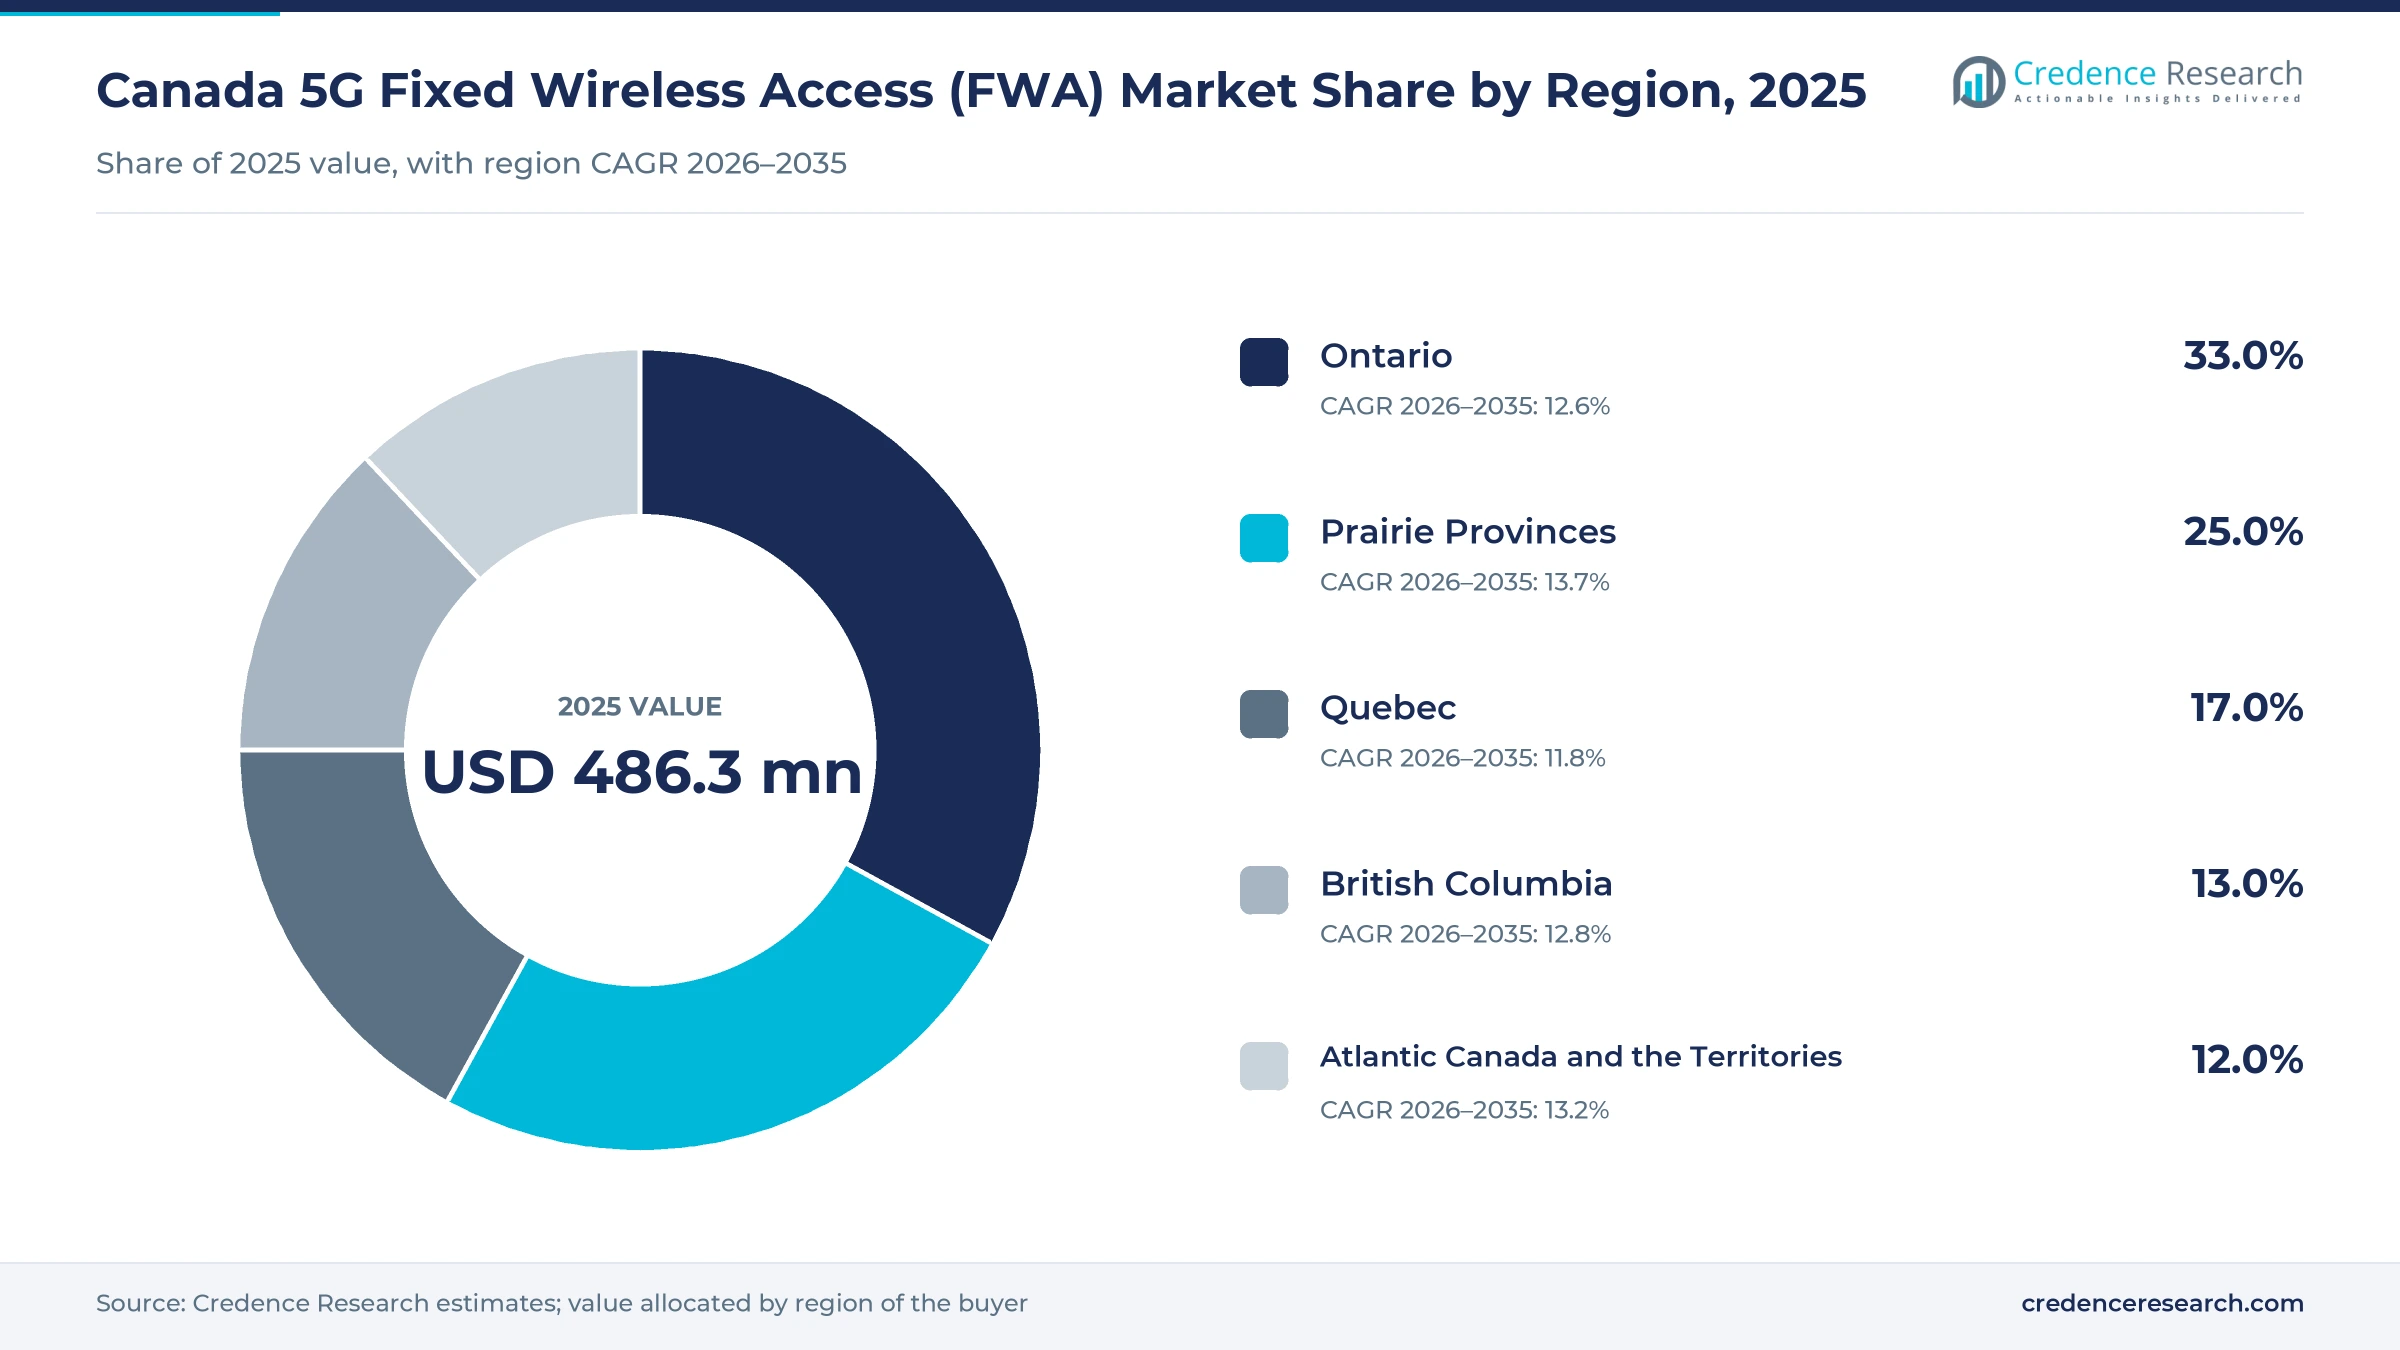
Ontario leads while the Prairie Provinces grow fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Ontario | 160.5 | 33.0% | 12.6% |
| Prairie Provinces | 121.6 | 25.0% | 13.7% |
| Quebec | 82.7 | 17.0% | 11.8% |
| British Columbia | 63.2 | 13.0% | 12.8% |
| Atlantic Canada and the Territories | 58.4 | 12.0% | 13.2% |
Ontario leads on household numbers and carrier choice
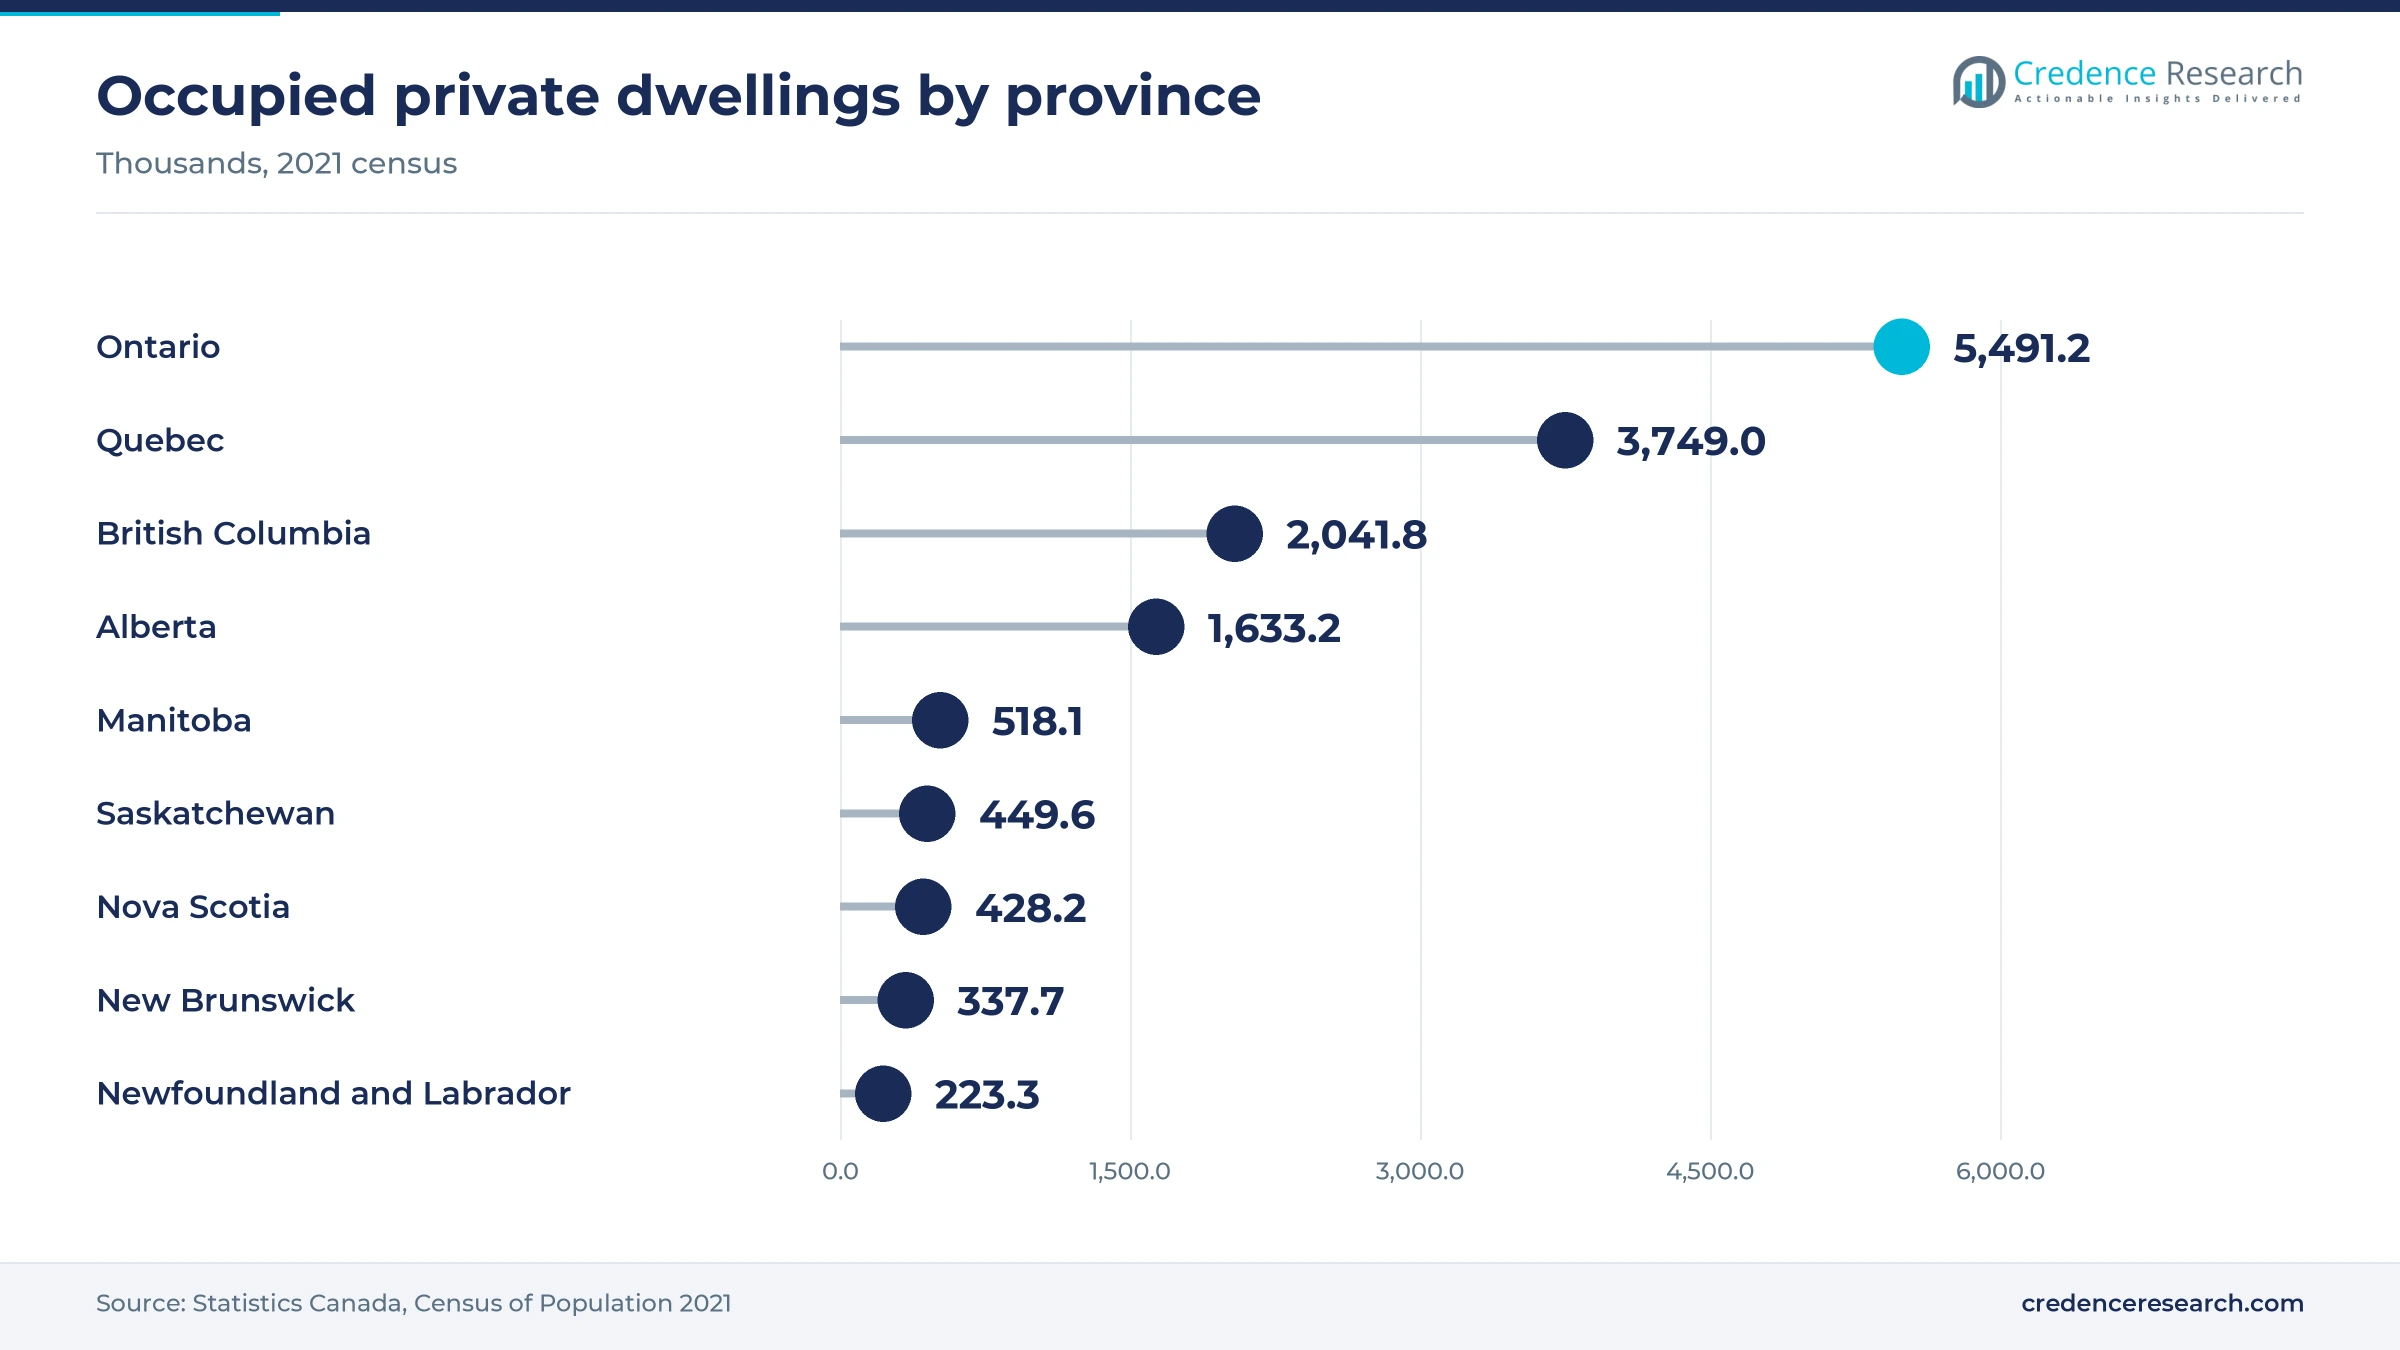
Ontario held a 33.0% share of 2025 value and grows at 12.6% a year. The province had 5.49 million occupied private dwellings in the 2021 census, according to Statistics Canada, more than any other, and Rogers, Bell, Freedom and Xplore all sell fixed wireless there. Rural Ontario reached 84% coverage at 50/10 Mbps in December 2024, according to the Rural Ontario Institute, so the remaining gap is smaller than on the Prairies. Growth trails the national pace because fiber and cable already reach most Ontario homes.
The Prairie Provinces grow fastest on funded rural towers
The Prairie Provinces held a 25.0% share of 2025 value and grow fastest at 13.7% a year. Saskatchewan households had 89.2% coverage at 50/10 Mbps in July 2026, up from 45.4% in 2017, according to ISED, so more rural homes remain to be served here than elsewhere. Xplore's Alberta plan, which could eventually reach about 245,000 households, and its two funded Saskatchewan projects anchor this growth. Long distances between farms keep outdoor gateways more common here than in other regions.
Quebec grows slowest as cable and fiber dominate
Quebec held a 17.0% share of 2025 value and grows at 11.8% a year, the slowest of the five regions. The province had 3.75 million occupied private dwellings in 2021, but Videotron and Bell concentrate on cable and fiber, and Freedom did not include Quebec in its December 2025 home 5G launch. Rogers brought gateways with Wi-Fi 7 for its 5G Home Internet to Quebec customers in August 2025, which gives it a share of renters and seasonal users. Cottage country and other seasonal areas provide much of the remaining demand.
British Columbia pairs carrier home 5G with mountain gaps
British Columbia held a 13.0% share of 2025 value and grows at 12.8% a year. TELUS, the province's incumbent, sells Smart Hub service there, which supports urban and suburban take-up. Freedom also included British Columbia in its December 2025 home 5G launch, adding a second bundled offer for mobile customers. Mountain terrain limits tower reach in interior valleys, so coverage remains patchier outside the Lower Mainland.
Atlantic Canada and the Territories add rural 5G upgrades
Atlantic Canada and the Territories held a 12.0% share of 2025 value and grow at 13.2% a year. Xplore launched 5G Ultra in all four Atlantic provinces in March 2025, and Eastlink switched on its first 5G sites in Halifax in March 2022. The Atlantic provinces had about 1.05 million occupied private dwellings in 2021, so absolute demand is small. Fiber builds in Newfoundland and satellite service in the North limit the long-term opportunity for fixed wireless.
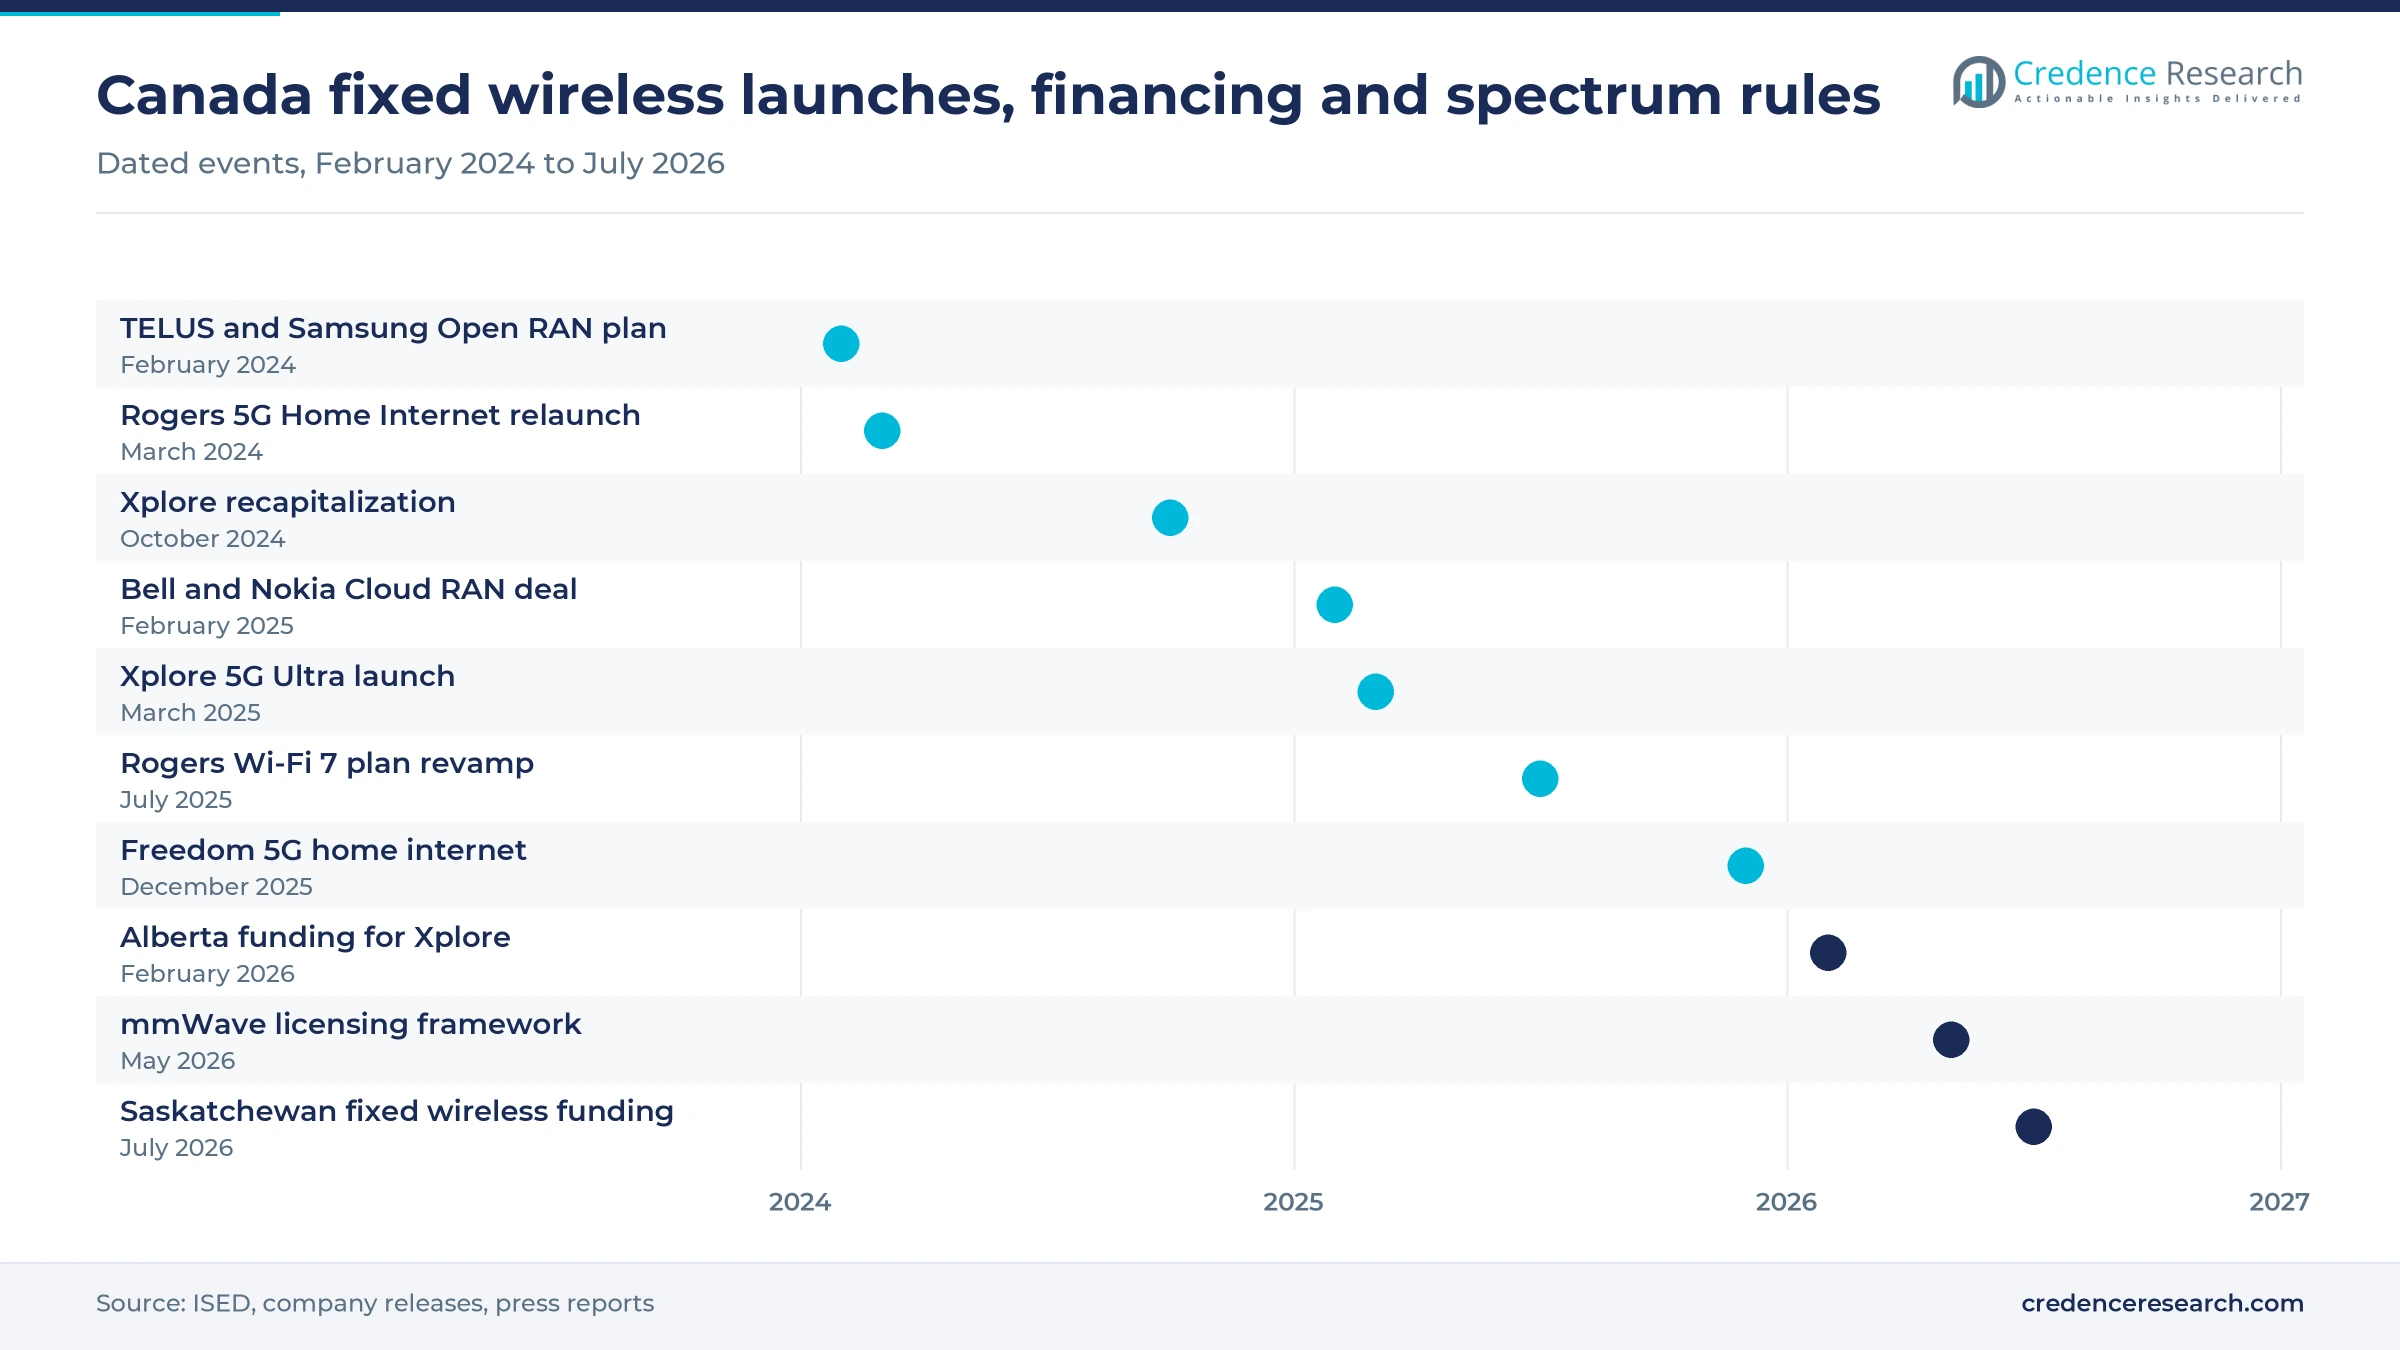
Launches, financing and spectrum rules, 2024–2026
| Development | Status and market relevance |
|---|---|
| In October 2024, Xplore completed a recapitalization with more than CAD 1.6 billion of new funding for rural fiber and 5G fixed wireless. | Completed financing; it funds 5G fixed wireless to more than 1.5 million homes, a company target. |
| In March 2025, Xplore launched its 5G Ultra fixed wireless service with speeds of up to 500 Mbps in six provinces. | Operational launch in select areas; Xplore did not disclose subscriber numbers or prices at launch. |
| In December 2025, Freedom Mobile launched 5G home internet in Ontario, Manitoba, Alberta and British Columbia. | Limited launch by invitation to eligible postpaid customers; wider availability has not been announced. |
| In February 2026, Xplore was awarded CAD 60 million of federal and provincial funding to expand 5G Ultra across rural Alberta. | Funding awarded and build planned for more than 70,000 households; no completion date was published. |
| In May 2026, ISED published the licensing framework for 26 GHz and 38 GHz mmWave spectrum. | Approved policy; the auction is scheduled to begin in October 2027 and licenses follow after bidding. |
Gateways, mid-band radios and mmwave set the speed ceiling
- Indoor 5G gateways such as the Nokia FastMile units used by Rogers combine a 5G modem with Wi-Fi routers in one box, which allows self-installation.
- Outdoor CPE mounts an antenna on the roof or wall, which adds signal strength for rural homes several kilometers from a tower.
- Mid-band massive MIMO radios serve many homes from one site, which sets how many lines each tower can sell.
- Millimeter wave links deliver gigabit speeds over short distances, which suits dense urban blocks and business parks after the 2027 auction.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Mobile carriers compete with one rural specialist
Competition splits between national mobile carriers that sell fixed wireless from spare capacity and one rural specialist. Rogers Communications sells 5G Home Internet and 5G Business Internet nationally. BCE competes through Bell Wireless Home Internet in rural areas, while TELUS sells Smart Hub service on its LTE and 5G networks. Xplore builds fixed wireless towers in rural regions with public co-funding, and Quebecor competes through Freedom Mobile's invite-only home 5G. TeraGo serves enterprise sites with managed fixed wireless and mmWave spectrum. Nokia supplies gateways and radio software, Ericsson supplies Rogers radio and core equipment, and Samsung supplies TELUS virtualized radio networks. Spectrum depth per site, tower density in rural areas and the ability to bundle mobile and home service decide who wins customers.
Three carriers hold the spectrum while one specialist owns rural towers
Supply is concentrated among the operators that own licensed spectrum. Rogers, Bell and TELUS sell most fixed wireless lines over networks they already built for mobile service, and they were the three largest buyers in the 2023 mid-band spectrum auction. Xplore is the main rural specialist, with its own spectrum and tower network, while Freedom Mobile gives Quebecor a regional challenger. Entry barriers are high, because spectrum, towers and backhaul take years and billions to assemble. Margins sit with carriers selling spare capacity, while gateway and radio vendors compete hard for a few large orders.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Rogers Communications Inc. | National carrier | 5G Home Internet and 5G Business Internet plans on its national 5G network |
| BCE Inc. (Bell Canada) | National carrier | Wireless Home Internet for rural households over its mobile network |
| TELUS Corporation | National carrier | Smart Hub wireless home internet on its LTE and 5G network |
| Xplore Inc. | Rural specialist | 5G Ultra fixed wireless on its own towers across rural Canada |
| Quebecor Inc. (Freedom Mobile) | Regional challenger | Invite-only 5G home internet for Freedom Mobile postpaid customers in four provinces |
| TeraGo Inc. | Enterprise specialist | Managed fixed wireless internet and mmWave spectrum for business sites |
| Nokia Corporation | Equipment vendor | FastMile 5G gateways with Wi-Fi 7, plus Cloud RAN for Bell |
| Telefonaktiebolaget LM Ericsson | Equipment vendor | Radio access network and 5G core supplier to Rogers |
| Samsung Electronics Co., Ltd. | Equipment vendor | Virtualized and Open RAN radio network supplier to TELUS |
Value follows spare mid-band capacity, not coverage maps
Credence Research's view is that fixed wireless value in Canada will follow spare mid-band capacity rather than coverage maps. National carriers can add home lines at low cost wherever their mid-band cells have room, so bundled urban and suburban plans will add the most new revenue. Rural demand remains the larger base, but satellite service and funded fiber compete for it, which favors operators that upgrade towers to 5G quickly. The supplier best placed through 2035 combines deep spectrum, rural towers co-funded by government and a large mobile base to bundle with.
Old estimate rebuilt from lines, prices and gear
The report uses 2025 as the base year and forecasts to 2035. Market values in this report come from the Credence Research model. This edition replaces the previous 2024 estimate with a rebuilt 2025 value, checked against operator footprints, published plan prices, equipment prices and the size of fixed internet revenue reported by the CRTC. Segment and regional shares are Credence Research estimates based on census household counts, ISED coverage data and company announcements. No official count of 5G fixed wireless lines is published, which is the main evidence gap. No interviews or surveys were carried out for this edition.
Migration from LTE and mmwave licenses set the pace
In the base case the Canada 5G fixed wireless access market grows at 12.80% a year through 2035, as operators move legacy fixed wireless customers to 5G gateways and carriers sell more home lines with mobile plans. Services keep the largest share, while indoor gateways grow fastest as each new line needs one. Ontario keeps the largest regional share, and the Prairie Provinces gain as funded towers go live by 2027. The main risks are satellite price cuts and subsidized fiber, so the pace will depend on how quickly towers are upgraded and mmWave licenses are used after 2028.
LTE migration, satellite pricing and fiber reach decide the range of outcomes
The outcome depends on how fast operators move legacy fixed wireless customers onto 5G gateways, how aggressively satellite services price rural plans, and how far subsidized fiber extends before 2030. Slow tower upgrades, cheaper satellite plans and wider fiber would hold growth near the downside case. Fast 5G upgrades, wider carrier bundles and early mmWave deployment after the 2027 auction would push the market toward the upside case.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 9.8% | USD 1.27 billion | Satellite service undercuts rural plans and fiber reaches most underserved homes before 2030 |
| Base | 12.80% | USD 1.62 billion | Operators upgrade towers and sell bundles at the pace seen in 2025 and 2026 |
| Upside | 15.3% | USD 1.98 billion | Fast 5G upgrades, wide carrier bundles and early mmWave lines after the 2027 auction |
Frequently Asked Questions
How big is the Canada 5G fixed wireless access (FWA) market?
Which mobile carriers offer 5G home internet in Canada?
How much does 5G home internet cost in Canada?
What customer premises equipment does 5G fixed wireless use in Canada?
When will mmWave 5G be available in Canada?
Which region leads the market in Canada?
What are the main challenges for fixed wireless operators in Canada?
Which companies lead the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Offering
- 1.2.1 Services
- 1.2.2 Indoor CPE
- 1.2.3 Outdoor CPE
- 1.2.4 Femto and Pico Cells
- 1.3 By Demography
- 1.3.1 Rural
- 1.3.2 Semi-urban
- 1.3.3 Urban
- 1.4 By Operating Frequency
- 1.4.1 Sub-6 GHz
- 1.4.2 24 GHz and Above (Millimeter Wave)
- 1.5 By Application
- 1.5.1 Residential
- 1.5.2 Commercial
- 1.5.3 Industrial
- 1.5.4 Government
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 486.3 million → 2035: USD 1.62 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Canada 5G Fixed Wireless Access (FWA) Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Canada 5G Fixed Wireless Access (FWA) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Canada 5G Fixed Wireless Access (FWA) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Canada 5G Fixed Wireless Access (FWA) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Canada 5G Fixed Wireless Access (FWA) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Canada 5G Fixed Wireless Access (FWA) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Canada 5G Fixed Wireless Access (FWA) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Canada 5G Fixed Wireless Access (FWA) Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 486.3 million → 2035: USD 1.62 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Canada 5G Fixed Wireless Access (FWA) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Offering - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Services
- 12.3.7.2 Indoor CPE
- 12.3.7.3 Outdoor CPE
- 12.3.7.4 Femto and Pico Cells
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Demography - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Rural
- 12.4.7.2 Semi-urban
- 12.4.7.3 Urban
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Operating Frequency - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Sub-6 GHz
- 12.5.7.2 24 GHz and Above (Millimeter Wave)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Residential
- 12.6.7.2 Commercial
- 12.6.7.3 Industrial
- 12.6.7.4 Government
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Canada 5G Fixed Wireless Access (FWA) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Canada 5G Fixed Wireless Access (FWA) Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Canada 5G Fixed Wireless Access (FWA) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Canada 5G Fixed Wireless Access (FWA) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Rogers Communications Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BCE Inc. (Bell Canada)
- 18.4 TELUS Corporation
- 18.5 Xplore Inc.
- 18.6 Quebecor Inc. (Freedom Mobile)
- 18.7 TeraGo Inc.
- 18.8 Nokia Corporation
- 18.9 Telefonaktiebolaget LM Ericsson
- 18.10 Samsung Electronics Co., Ltd.
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

