
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| China Wifi Chipset Market Size 2023 | USD 5,389.12 million |
| China Wifi Chipset Market, CAGR | 8.16% |
| China Wifi Chipset Market Size 2032 | USD 10,917.37 million |
Market Overview
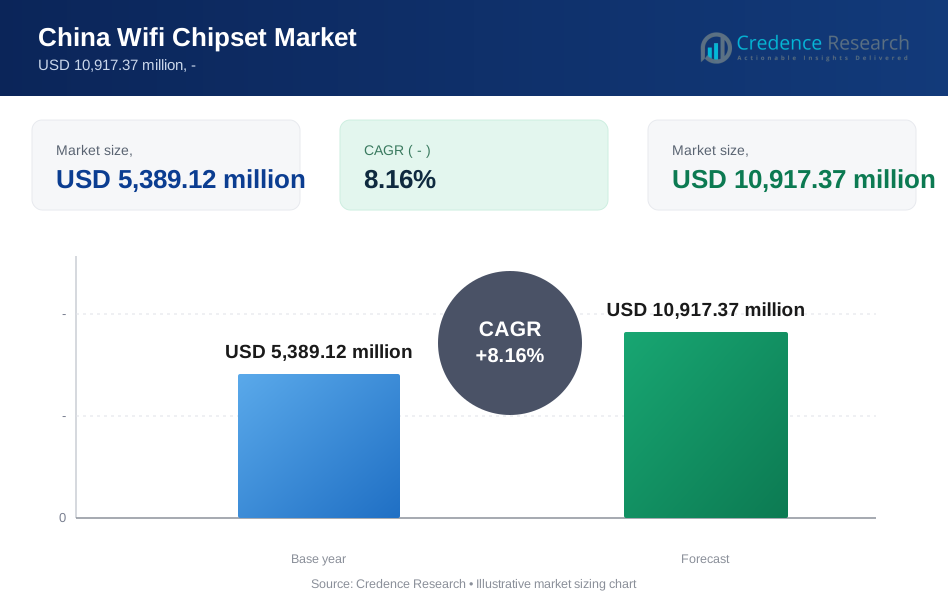
The China WiFi chipset market is projected to witness substantial growth, with its value expected to surge from USD 5,389.12 million in 2023 to USD 10,917.37 million by 2032, representing a robust CAGR of 8.16%. The China WiFi chipset market serves as a pivotal entity within the expansive realm of semiconductor technologies, driven by the ever-expanding domain of wireless connectivity and the seamless integration of WiFi-enabled devices across diverse sectors. China, renowned as a global technological powerhouse, holds substantial influence over semiconductor markets worldwide, placing its WiFi chipset sector squarely in the spotlight for investors, manufacturers, and stakeholders alike.
Propelled by a relentless surge in demand for high-speed, dependable wireless connectivity, the China WiFi chipset market has witnessed remarkable growth in recent years. The proliferation of smartphones, tablets, laptops, smart home devices, and IoT applications has spurred an insatiable appetite for WiFi-enabled components, propelling the market forward at an exponential pace. Moreover, advancements in WiFi standards such as Wi-Fi 6 and Wi-Fi 6E have acted as catalysts for the adoption of more efficient and potent chipsets, further fueling the market's expansion.
Despite promising growth prospects, the China WiFi chipset market faces several challenges. Intense competition among market players, both domestic and international, has resulted in price pressures and margin constraints, presenting challenges for profitability. Moreover, concerns regarding intellectual property rights, cybersecurity, and data privacy have emerged as potential hurdles, necessitating robust regulatory frameworks and industry standards to address these issues effectively. Furthermore, the rapid pace of technological evolution in the semiconductor industry poses both opportunities and challenges for market participants. Staying abreast of emerging WiFi standards, such as Wi-Fi 7, and integrating cutting-edge features like artificial intelligence (AI) and machine learning (ML) capabilities into WiFi chipsets are imperative to maintain competitiveness in the market.
Segmentation Analysis
By MIMO Configuration:
In the realm of WiFi chipset configurations, SU-MIMO (Single-User MIMO) and MU-MIMO (Multi-User MIMO) represent two distinct paradigms that address varying needs and challenges in wireless communication. SU-MIMO, characterized by its support for communication between a single transmitter and a single receiver, is tailored to scenarios where multiple users operate individual devices independently. This configuration facilitates seamless connectivity for individual users, ensuring reliable data transmission without interference from other devices. In contrast, MU-MIMO technology revolutionizes the landscape by enabling simultaneous data transmission to multiple users.
By Band:
The frequency spectrum utilized by WiFi chipsets, with Single & Dual Band chipsets operating across the 2.4 GHz and 5 GHz bands, offering versatile connectivity for myriad applications, while Tri Band chipsets provide enhanced performance and reduced interference in high-traffic environments. The delineation by IEEE Standard further refines market understanding, encompassing variations such as 802.11be (Wi-Fi 7), 802.11ax (Wi-Fi 6 and 6E), 802.11ac (Wi-Fi 5), among others, each tailored to specific use cases and technological requirements.
By Vertical:
Vertical segmentation aligns with industry sectors, spanning Electronics, Enterprise, Industrial, Retail, BFSI (Banking, Financial Services, and Insurance), Healthcare, Automotive, and others, each necessitating tailored WiFi chipset solutions to optimize performance and address sector-specific challenges.
By End-Use Application:
End-Use Application segmentation delves into specific devices and use cases leveraging WiFi connectivity, from Cameras and Smart home devices to Gaming devices and AR/VR devices, offering insights into diverse consumer demands and application requirements.
Segments:
By MIMO Configuration:
- SU-MIMO
- MU-MIMO
By Band:
- Single & dual band
- Tri band
By IEEE standard:
- 11be (Wi-Fi 7)
- 11ax (Wi-Fi 6 and 6E)
- 11 ac (Wi-Fi 5)
- 11ad
- 11b/g/n
By Vertical:
- By IEEE standard Electronics
- Enterprise
- Industrial
- Retail
- BFSI
- Healthcare
- Automotive
- Others (government & public sector)
By End-Use Application:
- By IEEE standard devices
- Cameras
- Smart home devices
- Gaming devices
- AR/VR devices
- Mobile robots
- Drones
- Networking devices
- mPOS
- In-vehicle infotainment
By Product Category
- Smartphones
- Tablets
- PCs
By Region:
- Eastern
- Northern
- Central
- Western
- Northeastern
Market Drivers
Surging Internet and Smartphone Penetration
China’s remarkable surge in internet and smartphone penetration has propelled its position as the world’s largest internet user base and a mammoth smartphone market. For instance, as of 2022, the penetration rate of smartphones in China reached almost 72 percent. As for internet usage, about 77.5 percent of the Chinese population had used the internet as of December 2023. This pervasive adoption of internet-connected devices has consequently fueled an unprecedented demand for Wi-Fi chipsets across the nation. With millions of users relying on Wi-Fi connectivity for a myriad of applications, from social media browsing to online gaming and video streaming, the need for reliable and high-performance chipsets has become paramount to meet the burgeoning demands of Chinese consumers.
Next-Generation Wi-Fi Adoption
The advent of next-generation Wi-Fi standards, spearheaded by the rollout of Wi-Fi 6 and future iterations like Wi-Fi 6E, stands as a significant driver shaping the landscape of the Chinese Wi-Fi chipset market. These standards promise substantial improvements in speed, capacity, and latency, revolutionizing the Wi-Fi experience for users. Wi-Fi 6 is forecast to make up 79% of all Wi-Fi product shipments within the next two years. However, it’s worth noting that under the current policy, China does not plan to allocate the 6GHz spectrum for Wi-Fi, which may impact the adoption of Wi-Fi 6E and future Wi-Fi 7. As Chinese consumers increasingly demand faster and more reliable connectivity to support bandwidth-intensive activities such as 4K video streaming and cloud gaming, the adoption of compatible chipsets becomes imperative, driving manufacturers to innovate and adapt to meet evolving consumer expectations.
Rise of Smart Technologies
The burgeoning smart home trend and the rapid development of smart cities across China underscore the critical role of seamless Wi-Fi connectivity in driving technological advancements. From smart thermostats and security cameras to connected appliances and intelligent infrastructure, the proliferation of smart technologies hinges on robust Wi-Fi networks supported by advanced chipsets. As Chinese consumers embrace the convenience and efficiency offered by smart devices, the demand for high-performance Wi-Fi chipsets capable of supporting these innovations continues to soar, driving growth in the market.
Government Initiatives
The Chinese government's unwavering commitment to developing a robust domestic semiconductor industry, including Wi-Fi chipsets, has been a pivotal driver of growth. Through substantial investments in research and development, the creation of supportive policies, and incentives to encourage domestic production, the government has catalyzed innovation and bolstered the capabilities of domestic chipset manufacturers. This proactive stance not only fosters technological self-reliance but also strengthens China's position as a global leader in semiconductor manufacturing.
Focus on Self-Sufficiency
In line with broader economic goals, China has intensified its efforts to reduce reliance on foreign chipmakers, particularly in critical sectors like telecommunications and technology. Government support, coupled with the growing capabilities of domestic companies, has propelled the domestic Wi-Fi chipset market forward. By prioritizing self-sufficiency and fostering a conducive ecosystem for indigenous innovation, China aims to strengthen its technological independence and enhance its competitiveness in the global semiconductor landscape.
Market Trends
Domestic Chip Development and Innovation
Chinese companies have entered a phase of robust development and innovation in the realm of Wi-Fi chipsets, exhibiting a determined stride towards technological self-sufficiency. For instance, Chinese companies like Hisilicon and Montage Technology are leading the way in Wi-Fi chipset design. Hisilicon, a world-leading Fabless semiconductor and device design company, has been actively involved in the research and development of Wi-Fi chipsets. Notably, there’s a concerted effort towards exploring the frontiers of next-generation Wi-Fi standards, exemplified by the exploration of standards like Wi-Fi 6E and beyond. Under the current policy, China does not plan to allocate the 6GHz spectrum for Wi-Fi, which may impact the adoption of Wi-Fi 6E and future Wi-Fi 7. However, Wi-Fi 6 is forecast to make up 79% of all Wi-Fi product shipments within the next two years. This ambitious pursuit underscores China’s aspirations to carve out a prominent position in the ever-evolving landscape of wireless connectivity.
Integration of Advanced Features
In line with global trends, Chinese chipsets are integrating a plethora of advanced features to enhance performance and functionality. Among these features, artificial intelligence (AI) and machine learning algorithms are increasingly being leveraged to optimize network performance. For example, Comcast and Broadcom are developing the world’s first AI-powered access network with a new chipset that embeds AI and machine learning within the nodes, amps, and modems. Moreover, technologies such as beamforming are being implemented to precisely direct signals towards intended recipients, ensuring robust and reliable connectivity. This technology allows for a more precise connection, boosting data speeds and reducing errors without having to increase the power of the broadcast. Wi-Fi-based IoT devices are typically battery-operated, and their wireless communication modules consume a relatively high amount of energy, especially when data needs to be sent over long distances.
Focus on Affordability
A distinctive trend shaping the Chinese Wi-Fi chipset market is the delicate balance between advanced features and affordability. Chinese manufacturers are adept at strategically incorporating cutting-edge functionalities into their chipsets while ensuring cost-effectiveness. This strategic approach not only caters to the price-sensitive domestic market but also positions Chinese chipsets competitively on the global stage. By offering high-quality chipsets at competitive prices, Chinese manufacturers can effectively capture a broad spectrum of consumers, fueling further growth and expansion in the market.
Miniaturization for Compact Devices
The relentless pursuit of innovation in smartphone design by Chinese manufacturers has led to an increased demand for miniaturized Wi-Fi chipsets. These chipsets play a pivotal role in enabling sleek and compact device designs without compromising on Wi-Fi functionality. By maximizing space utilization within devices, Chinese chipsets empower manufacturers to deliver devices that are not only aesthetically pleasing but also highly functional. This trend underscores the symbiotic relationship between technological innovation and consumer demand, as consumers increasingly seek devices that offer a seamless blend of form and function.
Integration with Other Technologies
In alignment with global market trends, Chinese chipsets are embracing integration with other wireless technologies to enhance connectivity and functionality. Wi-Fi and Bluetooth integration, for instance, simplifies device design and production processes while offering users the convenience of seamless connectivity across multiple protocols. By embracing this trend, Chinese chipset manufacturers are poised to capitalize on the growing demand for versatile and interoperable devices, further solidifying their position in the global marketplace.
Focus on Smart Home and IoT Applications
The rapid proliferation of smart home and IoT technologies in China has catalyzed the development of specialized Wi-Fi chipsets tailored to meet the unique demands of these ecosystems. These chipsets prioritize features such as low power consumption, mesh networking capabilities for broader coverage, and enhanced security features to safeguard smart home devices and data. This strategic focus on smart home and IoT applications underscores China's commitment to driving innovation in interconnected technologies and capitalizing on emerging market opportunities in the burgeoning smart home segment.
Market Restraints and Challenges
Reliance on Foreign Technology and Expertise
Despite China's advancements in domestic chip development, there remains a significant reliance on foreign technology and expertise for certain aspects of chip manufacturing processes and intellectual property (IP) for specific designs. This dependence poses a challenge as it limits China's ability to compete directly with established global players across all segments of the Wi-Fi chipset market. While strides have been made in indigenous innovation, the reliance on foreign resources presents a barrier to achieving complete technological self-sufficiency.
Catching Up in Advanced Chip Development
While China demonstrates prowess in producing more basic Wi-Fi chipsets, there exists a discernible gap in competing with the most advanced chipsets from leading manufacturers. This discrepancy poses a challenge as it hinders China's ability to capture the entire spectrum of the market. Despite significant progress, particularly in recent years, there remains a need to bridge this gap in advanced chip development to attain a more competitive position on the global stage.
Competition from Established Players
Chinese manufacturers face formidable competition from established players such as Broadcom, Qualcomm, and Intel. These industry giants possess a significant head start in terms of brand recognition, established global presence, and a broader range of advanced chip offerings. This competitive landscape presents a challenge for Chinese manufacturers seeking to carve out a larger share of the market, necessitating strategic differentiation and innovation to compete effectively.
Potential for Trade Wars
Geopolitical tensions and trade wars pose a potential threat to the Wi-Fi chipset market, disrupting global supply chains and impacting the import of critical materials or equipment necessary for production. Such disruptions can hinder the operational efficiency of Chinese manufacturers and introduce uncertainties that may affect market dynamics and profitability. Trade wars and geopolitical tensions have the potential to disrupt global supply chains, causing ripple effects throughout the Wi-Fi chipset market. Restrictions on the import of key materials such as silicon wafers, semiconductors, and rare earth minerals could lead to shortages and price fluctuations, impacting the production capabilities of Chinese manufacturers.
Fluctuations in Material Costs
The market's reliance on raw materials like silicon wafers exposes Chinese manufacturers to the risk of fluctuations in material costs. These fluctuations can significantly impact production costs and profitability, posing a challenge for manufacturers striving to maintain competitive pricing while ensuring product quality and performance standards are met consistently. Managing these cost fluctuations requires proactive risk management strategies and effective supply chain management practices.
Quality Control Issues
Quality control issues have emerged as a significant concern for Chinese chipmakers operating in the competitive Wi-Fi chipset market. While ensuring consistent quality and reliability is imperative for long-term success, some Chinese manufacturers have encountered criticism regarding their quality control practices in the past. Addressing these challenges and building a reputation for excellence will be paramount for Chinese manufacturers to gain the trust of consumers and compete effectively with established players in the global market.
Key Players
- Qualcomm Technologies, Inc.
- Broadcom Inc.
- MediaTek Inc.
- Intel Corporation
- Texas Instruments Incorporated
- Hewlett Packard Enterprise Co.
- STMicroelectronics N.V.
- Samsung Electronics Co., Ltd.
- Skyworks Solutions, Inc.
- Cisco Systems Inc.
- Dell Technologies
- Cypress Semiconductor Corporation
- Extreme Networks
- Netgear
- ASUS
- D-Link
- Fibocom
- Quectel
- Peraso Technologies, Inc.
- Simcom Wireless Solutions Limited.
Recent Developments
- In April 2022, Broadcom Inc. unveiled the availability of samples from its comprehensive Wi-Fi 7 chipset lineup, aimed at enhancing Wi-Fi routers, residential gateways, enterprise access points, and client devices. These Wi-Fi 7 chips offer over double the speed of the existing Wi-Fi 6 and 6E technologies, along with improved low-latency connections and extended coverage. Among the products in Broadcom's Wi-Fi 7 ecosystem are the BCM67263, BCM6726, BCM43740, BCM43720, and BCM4398.
- February 2022 saw Qualcomm introducing support for Wi-Fi 7 in its latest chipset, boasting advancements like High Band Simultaneous (HBS) Multi-Link for utilizing dual radios to create four streams of connection at high frequencies. Wi-Fi 7 also promises to double the maximum channel width to 320MHz in the 6Ghz band, a capability introduced with Wi-Fi 6E.
- In 2021, Cisco and Apple collaborated to improve Wi-Fi uplink performance for applications requiring real-time interaction, such as FaceTime and Webex. This partnership led to the development of "Fastlane+", a modification of Wi-Fi standards for more efficient uplink scheduling.
- In January 2021, Broadcom Inc. and Apple Inc. forged a strategic collaboration, whereby Broadcom would supply Apple with Wi-Fi 6 chipsets for its smartphones, laptops, and iPads as part of a $15 billion supply agreement. Broadcom also supplied Wi-Fi 6 chipsets for Samsung devices, including the Galaxy S10 and Galaxy Note 10, delivering over 150 million chipsets to Samsung by February 2021.
- NXP Semiconductors acquired Marvell's wireless connectivity business in May 2021 for $1.76 billion. The acquisition included Marvell's Bluetooth and Wi-Fi (including Wi-Fi 6) technology portfolio and assets, allowing NXP to expand its range of Wi-Fi 6 chipsets for industrial, IoT, and automotive applications.
In March 2022, MediaTek unveiled two new chipsets, the Filogic 880 and Filogic 380, designed specifically for Wi-Fi 7 technology. These chipsets cater to a wide range of devices including access points, routers, gateways, smartphones, and laptops.
In March 2022, Qualcomm announced the launch of the third generation of its Qualcomm Networking Pro series, featuring Wi-Fi 7 chipsets tailored for access points. These developments by key market players are anticipated to bolster the Wi-Fi chipset market throughout the forecast period.
Regional Analysis
Eastern
The Eastern region of China, comprising provinces such as Guangdong, Jiangsu, and Zhejiang, holds the largest market share of approximately 38% in the country's WiFi chipset market. This region's status as a global manufacturing hub and the presence of major technology companies have significantly contributed to its dominance in this sector.
Shenzhen, often referred to as the "Silicon Valley of China," is home to industry giants such as Huawei, ZTE, and Tencent. These companies are at the forefront of WiFi chipset design and manufacturing, driving innovation and meeting the ever-growing demand for high-performance wireless connectivity solutions. Additionally, the region's well-established ecosystem of semiconductor suppliers, research institutions, and skilled workforce has created a fertile environment for the development and production of cutting-edge WiFi chipsets.
Northern
The Northern region of China, encompassing municipalities like Beijing and Tianjin, accounts for approximately 22% of the country's WiFi chipset market share. This region's strong technology and telecommunications industries have played a crucial role in supporting the WiFi chipset market. Beijing, the capital city and a major technology hub, is home to numerous technology companies, research institutes, and universities that are actively involved in the development of WiFi chipsets and wireless technologies. These entities collaborate closely with local chipset manufacturers to drive innovation and create advanced wireless connectivity solutions. Furthermore, the region's thriving telecommunications sector, including companies like China Mobile and China Unicom, has fueled the demand for WiFi chipsets to support wireless networking and mobile applications.
Central
The Central region of China, comprising provinces like Hubei and Hunan, holds a market share of approximately 15% in the WiFi chipset market. This region's growing emphasis on smart city initiatives and the development of technology parks have contributed to the demand for WiFi chipsets. Cities like Wuhan and Changsha have recognized the importance of reliable wireless connectivity in fostering urban development and improving the quality of life for residents. Local authorities and private enterprises have invested in the deployment of WiFi infrastructure, driving the adoption of WiFi chipsets in access points, routers, and other networking equipment. Additionally, the region's technology parks, such as the Wuhan Optics Valley and the Changsha High-Tech Industrial Development Zone, have attracted technology companies and research institutions focused on wireless communication technologies, further boosting the demand for WiFi chipsets.
Western
The Western region of China, comprising provinces like Sichuan and Shaanxi, accounts for a market share of approximately 12% in the WiFi chipset market. While not a major technology hub, this region's efforts to bridge the digital divide and improve connectivity in remote areas have contributed to the demand for WiFi chipsets. The Western region of China is home to numerous rural and mountainous areas where traditional wired infrastructure is challenging to deploy. Local authorities and service providers have recognized the importance of offering reliable wireless connectivity to support economic development and improve access to digital services. WiFi chipsets have played a crucial role in enabling wireless broadband access and providing internet connectivity in these remote areas, supporting local businesses, education, and communication efforts.
Northeastern
The Northeastern region of China, consisting of provinces like Liaoning and Jilin, holds a relatively smaller market share of approximately 13% in the WiFi chipset market. However, this region's industrial base and the presence of technology parks have contributed to the demand for WiFi chipsets. Cities like Shenyang and Dalian are home to various manufacturing industries, including automotive, machinery, and electronics, which require WiFi chipsets for their operations and wireless connectivity needs. The region's technology parks, such as the Shenyang High-Tech Industrial Development Zone and the Dalian Software Park, provide a conducive environment for research, development, and manufacturing activities related to WiFi chipsets.
Future Outlook
- The China Wi-Fi chipset market is poised for substantial growth driven by increasing demand for high-speed wireless connectivity across various sectors.
- Rapid technological advancements, including the adoption of next-generation Wi-Fi standards like Wi-Fi 6 and 6E, will fuel market expansion.
- Domestic chipmakers are expected to play a prominent role in the market, supported by government initiatives aimed at fostering indigenous innovation and self-sufficiency.
- Integration of advanced features such as AI, machine learning, and beamforming will enhance the performance and functionality of Wi-Fi chipsets.
- The proliferation of smart home and IoT applications will create new opportunities for Wi-Fi chipset manufacturers catering to these burgeoning segments.
- Continued investments in research and development will drive innovation and product differentiation in the market.
- Strategic partnerships and collaborations between industry players will facilitate technology transfer and knowledge sharing, accelerating market growth.
- Market players will focus on addressing quality control issues to build trust and credibility among consumers, essential for long-term success.
- Global supply chain disruptions and geopolitical tensions remain key challenges, necessitating proactive risk management strategies and diversified sourcing.
- Despite challenges, the China Wi-Fi chipset market is poised to maintain steady growth, supported by favorable market dynamics and evolving consumer preferences
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is driving the growth of the China WiFi chipset market?
What role do next-generation Wi-Fi standards play in shaping the market?
How are government initiatives impacting the WiFi chipset market in China?
What challenges does the China WiFi chipset market face?
What is the future outlook for the China WiFi chipset market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 China Wifi Chipset Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global China Wifi Chipset Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 5,389.12 million → forecast year: USD 10,917.37 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 China Wifi Chipset Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. China Wifi Chipset Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 China Wifi Chipset Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 China Wifi Chipset Market Drivers
- 3.3 China Wifi Chipset Market Restraints & Challenges
- 3.4 China Wifi Chipset Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 China Wifi Chipset Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 China Wifi Chipset Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, China Wifi Chipset category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 China Wifi Chipset Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. China Wifi Chipset Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the China Wifi Chipset market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 China Wifi Chipset Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 China Wifi Chipset Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 China Wifi Chipset Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in China Wifi Chipset (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New China Wifi Chipset Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global China Wifi Chipset Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America China Wifi Chipset Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe China Wifi Chipset Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific China Wifi Chipset Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America China Wifi Chipset Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East China Wifi Chipset Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa China Wifi Chipset Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. China Wifi Chipset Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
