
Market Overview
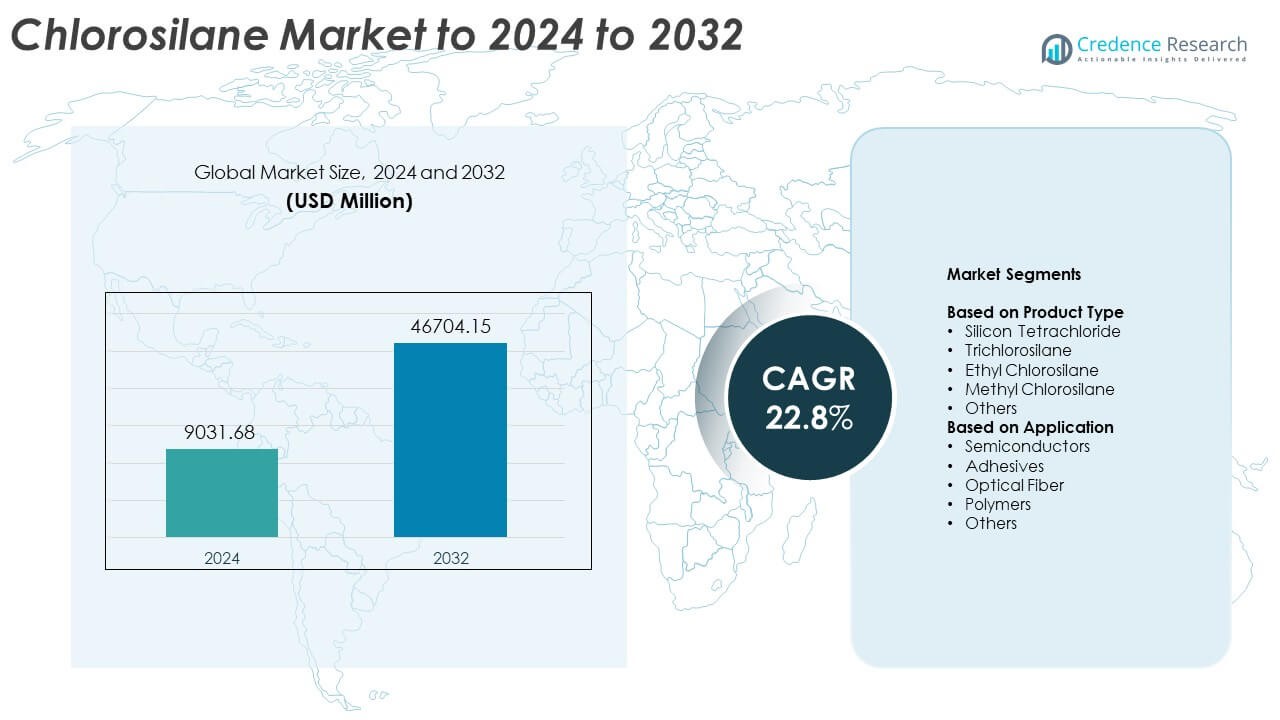
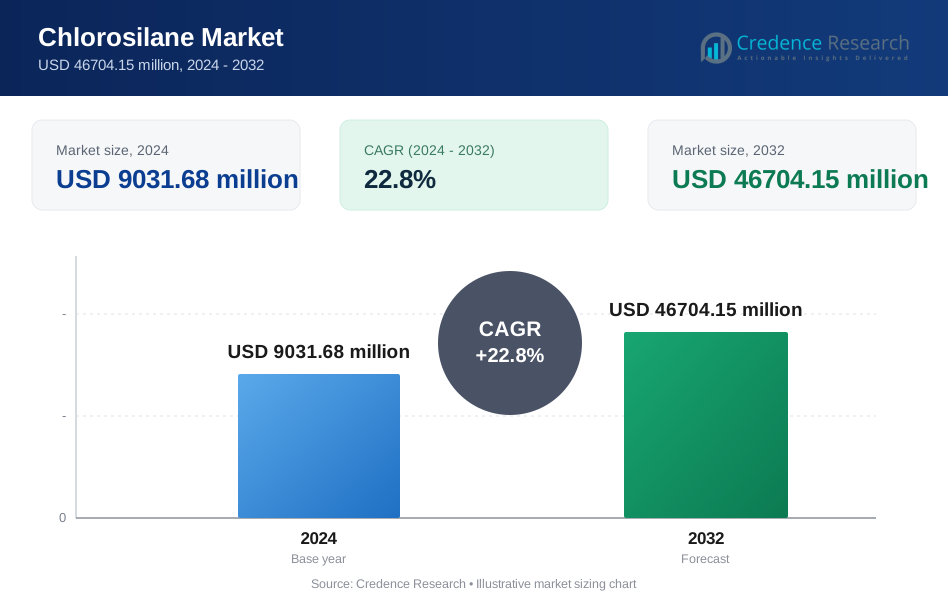
The Chlorosilane Market size was valued at USD 9031.68 million in 2024 and is anticipated to reach USD 46704.15 million by 2032, at a CAGR of 22.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Chlorosilane Market Size 2024 | USD 9031.68 Million |
| Chlorosilane Market, CAGR | 22.8% |
| Chlorosilane Market Size 2032 | USD 46704.15 Million |
The chlorosilane market features prominent players including Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd, Dow Inc., Tokuyama Corporation, Merck KGaA, Evonik, OCI Company Ltd, Gelest Inc., Wynca Group, BRB Silicones, and Linde AG. These companies dominate global production through large-scale manufacturing facilities and advanced purification technologies supporting semiconductor and solar applications. Asia Pacific led the market in 2024 with a 40% share, driven by strong demand from electronics and photovoltaic industries in China, Japan, and South Korea. North America accounted for 30%, supported by rising semiconductor investments, while Europe held 20%, reflecting its focus on renewable energy and high-purity chemical production.
Market Insights
- The chlorosilane market was valued at USD 9031.68 million in 2024 and is projected to reach USD 46704.15 million by 2032, expanding at a CAGR of 22.8% during the forecast period.
- Growing semiconductor and solar photovoltaic production drives strong demand for high-purity chlorosilanes, particularly silicon tetrachloride and trichlorosilane used in wafer and polysilicon manufacturing.
- Advancements in purification technologies and rising adoption of eco-friendly synthesis methods mark key trends, with manufacturers focusing on sustainable, low-emission production.
- The market is moderately consolidated, with global players emphasizing regional capacity expansion and product innovation to enhance competitiveness amid tightening environmental regulations.
- Asia Pacific dominated the market with a 40% share in 2024, followed by North America at 30% and Europe at 20%; by product, silicon tetrachloride led with 36.7% share, reflecting its critical role in optical fiber and semiconductor applications.
Market Segmentation Analysis:
By Product Type
Silicon tetrachloride dominated the chlorosilane market in 2024, accounting for 36.7% of the total share. Its strong demand is driven by extensive use in optical fibers, semiconductors, and polysilicon production. Increasing solar photovoltaic deployment and growth in the electronics sector further accelerate consumption. Trichlorosilane also gained traction due to its critical role in producing high-purity silicon for solar panels and integrated circuits. The segment benefits from advancements in purification technologies and expanding renewable energy capacity, particularly in Asia-Pacific manufacturing hubs.
- For instance, the OCI Tokuyama Semiconductor Materials Sdn. Bhd. (OTSM) plant being built in Samalaju is a joint venture that targets an annual production capacity of 8,000 metric tons of high-purity polysilicon, with commercial operations scheduled for 2029.
By Application
Semiconductors held the largest share of 41.2% in the chlorosilane market in 2024, driven by surging demand for high-performance chips and integrated circuits. Chlorosilanes serve as essential precursors in the chemical vapor deposition process, ensuring high-purity silicon layers. The rapid expansion of the electronics and solar industries strengthens market growth. Optical fiber applications also show robust growth, supported by global broadband infrastructure expansion and 5G deployment. Rising investments in telecommunications and smart device manufacturing sustain strong consumption across emerging economies.
- For instance, ASML recognized revenue on 2 High NA EUV systems in the fourth quarter of 2024, and had shipped a third High NA EUV system to a customer by the end of the year.
Key Growth Drivers
Expanding Semiconductor and Electronics Industry
The rising demand for semiconductors is a major growth driver for the chlorosilane market. Chlorosilanes play a crucial role in producing high-purity silicon, used in integrated circuits and microchips. The global shift toward advanced technologies such as AI, IoT, and electric vehicles boosts semiconductor consumption. Rapid industrialization and government support for chip manufacturing in Asia-Pacific and North America further strengthen the supply chain. Increased investment in silicon wafer production continues to propel chlorosilane demand across key manufacturing regions.
- For instance, Wacker’s new "Etching Line Next" in Burghausen expands semiconductor-grade polysilicon cleaning capacity by over 50%.
Rising Adoption of Solar Photovoltaics
The accelerating adoption of solar energy significantly drives chlorosilane consumption. Trichlorosilane and silicon tetrachloride are essential materials for producing polysilicon used in solar panels. Growing emphasis on renewable energy targets and declining installation costs enhance global solar capacity. Governments worldwide are incentivizing green energy projects, promoting large-scale solar infrastructure development. Expanding polysilicon production capacities in China, India, and the U.S. reinforce chlorosilane market growth through sustainable energy transitions.
- For instance, Daqo guided an initial polysilicon output range of 110,000 to 140,000 metric tons for the full year 2025 in April 2025.
Growth in Optical Fiber and Communication Networks
The increasing deployment of optical fiber networks is fueling chlorosilane demand. Silicon tetrachloride is a primary precursor in manufacturing optical fiber preforms, ensuring high transmission efficiency. The surge in 5G rollout, cloud computing, and data center expansion supports market growth. Telecommunication companies are investing heavily in broadband infrastructure to meet high-speed connectivity needs. This trend positions chlorosilane as a key material in the digital infrastructure ecosystem.
Key Trends & Opportunities
Shift Toward High-Purity and Eco-Friendly Production
Manufacturers are focusing on developing high-purity chlorosilane products to meet semiconductor-grade specifications. Advancements in refining and distillation technologies enhance product quality and yield. Companies are also adopting cleaner production processes to minimize by-products and emissions. Environmental regulations promoting low-waste and energy-efficient chemical synthesis methods create new opportunities. These innovations align with sustainability goals while maintaining consistent purity standards required by advanced industries.
- For instance, Hemlock (referring to Hemlock Semiconductor, HSC) reports it has recycled an average of 8.4 million pounds (3,810 metric tons) of materials per year since 2008.
Increasing Investment in Regional Manufacturing Expansion
Major producers are expanding chlorosilane production facilities in Asia-Pacific, driven by strong electronics and solar manufacturing bases. Strategic joint ventures and localization of supply chains reduce import dependence and improve cost efficiency. Rising foreign direct investment in India, China, and Southeast Asia supports regional industrialization. These developments create opportunities for new entrants to integrate into growing value chains. Enhanced capacity expansion strategies strengthen global market competitiveness.
- For instance, OCI is boosting Malaysian polysilicon capacity from 35,000 to 56,600 metric tons. The project strengthens Asia-Pacific upstream supply.
Key Challenges
Stringent Environmental and Safety Regulations
The production and handling of chlorosilanes pose environmental and occupational safety risks. Strict government regulations on emissions and waste disposal increase compliance costs. Producers must adopt advanced containment and treatment systems to manage hazardous by-products. The need for specialized storage and transportation also adds to operational expenses. Meeting these regulatory requirements while maintaining profitability remains a significant industry challenge.
Volatility in Raw Material Prices and Supply Disruptions
Fluctuations in raw material costs, particularly silicon and chlorine, directly affect production margins. Global supply chain disruptions, energy shortages, and transportation constraints exacerbate pricing instability. Dependence on a few major suppliers for high-purity inputs increases market vulnerability. Manufacturers face challenges in maintaining stable supply amid geopolitical uncertainties and trade restrictions. Managing cost efficiency under volatile conditions continues to be a major restraint for producers.
Regional Analysis
North America
In 2024, North America accounted for approximately 30% of the global chlorosilane market. The region’s strong presence in semiconductor manufacturing and solar-grade silicon production drives demand. Government incentives for renewables and domestic chip supply-chain investments further reinforce market growth. Increased construction of data centres and expansion of optical-fiber infrastructure also support chlorosilane consumption in the region.
Europe
Europe held around 20% of the global chlorosilane market in 2024. Growth arises from the region's focus on renewable energy installation and strict chemical manufacturing standards. The plastics, adhesives and polymers industries in Europe also absorb chlorosilane-based intermediates. However, slower industrial expansion compared with Asia limits more rapid share gains.
Asia Pacific
Asia Pacific dominated with roughly 40% market share in 2024. Rapid growth in electronics, solar-PV manufacturing and smart devices underpins high chlorosilane usage across China, India and Japan. Large-scale polysilicon plants and optical-fiber glass production further support consumption. Rising regional self-reliance in semiconductor materials strengthens Asia Pacific’s market position.
Latin America
Latin America captured about 6% of the global chlorosilane market in 2024. Expansion of solar power installations in Brazil and Chile creates new demand streams for high-purity silicon precursors. Constraint on local manufacturing capacities and reliance on imports limit faster growth, but favourable renewable-energy targets provide upward momentum.
Middle East & Africa
The Middle East & Africa region represented about 4% of the market in 2024. Growth stems from oil-&-gas downstream diversification and increasing solar-PV deployments in Gulf countries. Regulatory changes and rising demand for silicones and specialty adhesives in infrastructure rebuilds support market advancement. Limited domestic chemical manufacturing, however, constrains share expansion.
Market Segmentations:
By Product Type
- Silicon Tetrachloride
- Trichlorosilane
- Ethyl Chlorosilane
- Methyl Chlorosilane
- Others
By Application
- Semiconductors
- Adhesives
- Optical Fiber
- Polymers
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The chlorosilane market is characterized by the presence of major players such as Wacker Chemie AG, BRB Silicones, Shin-Etsu Chemical Co., Ltd, Gelest Inc., Dow Inc., Wynca Group, Tokuyama Corporation, Merck KGaA, OCI Company Ltd, Evonik, and Linde AG. The competitive landscape remains moderately consolidated, with leading companies focusing on expanding production capacities and enhancing product purity to meet semiconductor-grade requirements. Firms are investing in advanced distillation and purification technologies to strengthen their foothold in solar and electronic applications. Strategic collaborations with downstream manufacturers ensure supply stability and technical integration across value chains. Players are also pursuing vertical integration to control raw material sourcing and reduce dependency on imports. In addition, sustainability initiatives and process optimization strategies are gaining traction to comply with environmental standards and reduce emissions. Continuous research in high-purity chlorosilane formulations and regional capacity expansion underline the competition’s focus on innovation and long-term market leadership.
Key Player Analysis
- Wacker Chemie AG
- BRB Silicones
- Shin-Etsu Chemical Co., Ltd
- Gelest Inc.
- Dow Inc.
- Wynca Group
- Tokuyama Corporation
- Merck KGaA
- OCI Company Ltd
- Evonik
- Linde AG
Recent Developments
- In 2023, Evonik Industries completed an expansion of its rubber silanes production capacity at its joint venture plant, Evonik Lanxing (Rizhao) Chemical Industrial Co., Ltd., in China
- In 2023, BRB Silicones: Showcased novel silane, additive, resin, and water repellent products at the European Coatings Show.
- In 2023, Shin-Etsu Chemical Co., Ltd.: Established a Sustainable Silicone Business Development Department to focus on environmentally friendly silicone products.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Rising semiconductor production will sustain high demand for chlorosilane across Asia and North America.
- Expanding solar energy projects will continue driving trichlorosilane use in polysilicon manufacturing.
- Increasing investments in 5G networks will boost demand for silicon tetrachloride in optical fiber applications.
- Advancements in purification and distillation will enhance production efficiency and product quality.
- Growing preference for eco-friendly processes will encourage adoption of low-emission manufacturing technologies.
- Strategic partnerships between chemical producers and electronics firms will strengthen supply stability.
- Emerging economies will attract new chlorosilane capacity to meet rising industrial needs.
- Technological innovation in semiconductor materials will open opportunities for high-purity chlorosilane products.
- Government incentives for renewable energy and domestic chipmaking will support long-term growth.
- Market consolidation among leading producers will improve global competitiveness and production efficiency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Chlorosilane Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Chlorosilane Market projected to grow between 2025 and 2032?
Which Chlorosilane Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Chlorosilane Market?
Who are the leading companies in the Chlorosilane Market?
Which region commanded the largest share of the Chlorosilane Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Chlorosilane Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Chlorosilane Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9031.68 million → 2032: USD 46704.15 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Chlorosilane Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Chlorosilane Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Chlorosilane Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Chlorosilane Market Drivers
- 3.3 Chlorosilane Market Restraints & Challenges
- 3.4 Chlorosilane Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Chlorosilane Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Chlorosilane Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Chlorosilane category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Chlorosilane Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Chlorosilane Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Chlorosilane market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Chlorosilane Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Chlorosilane Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Chlorosilane Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Chlorosilane (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Chlorosilane Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Chlorosilane Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Chlorosilane Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Chlorosilane Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Chlorosilane Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Chlorosilane Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Chlorosilane Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Chlorosilane Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Chlorosilane Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
