
Market Overview
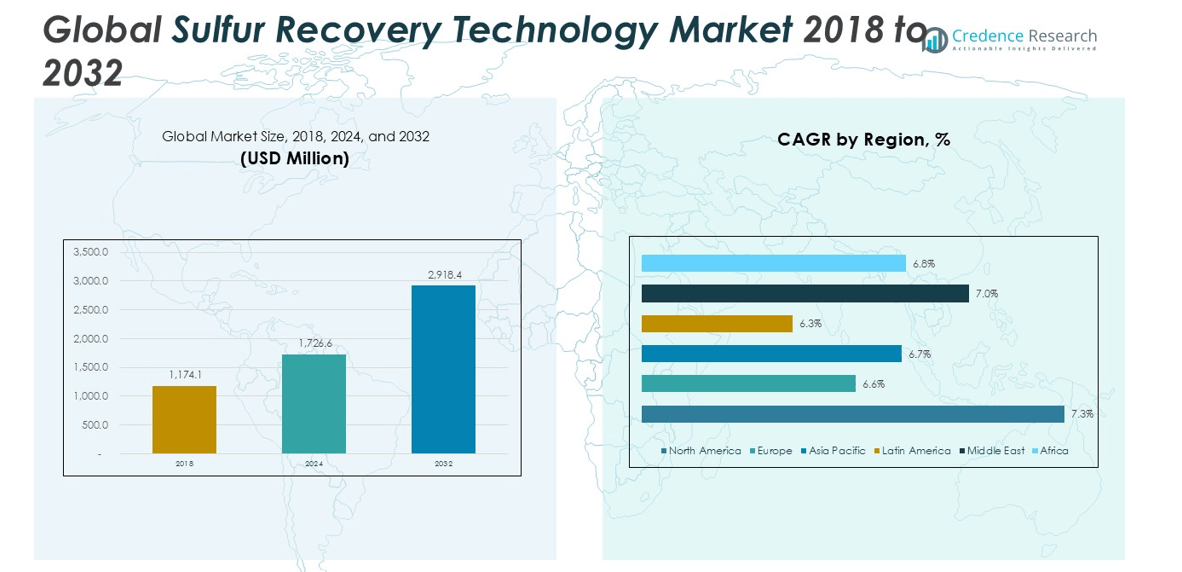
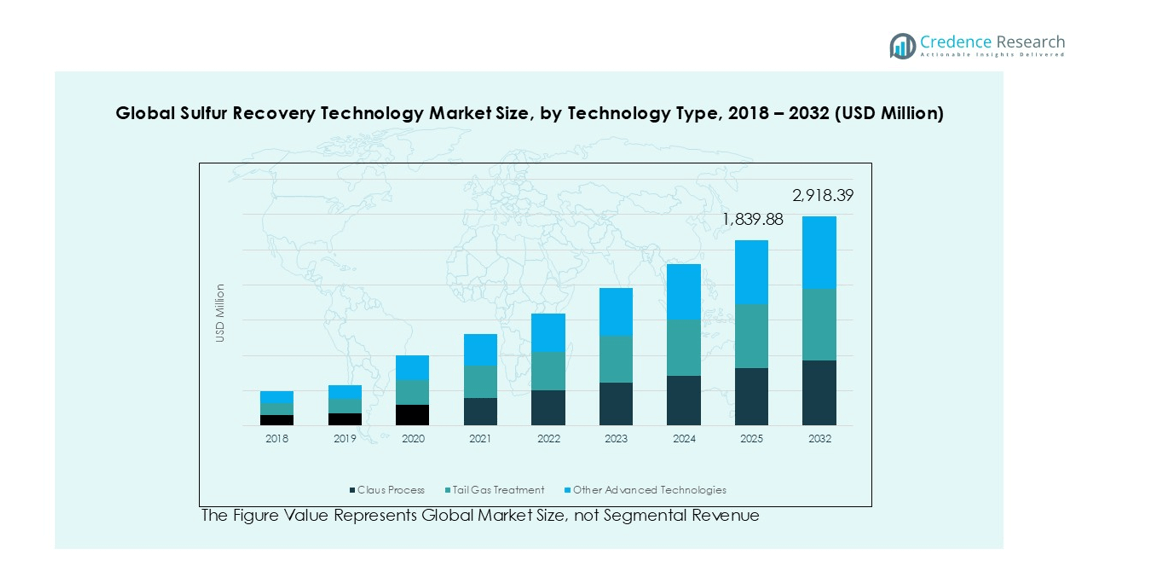
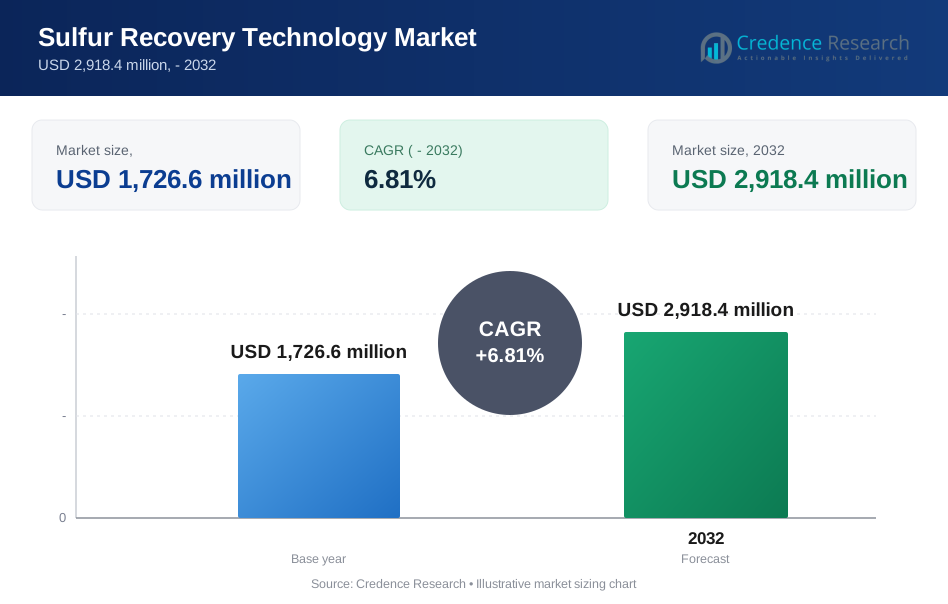
The Sulfur Recovery Technology Market size was valued at USD 1,174.1 million in 2018 and increased to USD 1,726.6 million in 2024. It is anticipated to reach USD 2,918.4 million by 2032, growing at a CAGR of 6.81% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Sulfur Recovery Technology Market Size 2024 | USD 1,726.6 million |
| Sulfur Recovery Technology Market, CAGR | 6.81% |
| Sulfur Recovery Technology Market Size 2032 | USD 2,918.4 million |
The Sulfur Recovery Technology Market is highly competitive, led by prominent players including Jacobs Engineering Group, Chiyoda Corporation, John Wood Group (Amec Foster Wheeler), Technip FMC, Worley Parsons, Linde AG, Fluor Corporation, KT-Kinetics Technology SpA, GTC Technology US, and Heurtey Petrochem. These companies drive innovation through advanced Claus, tail gas treatment, and hybrid recovery technologies, strengthening operational efficiency and ensuring compliance with stringent environmental regulations. Regionally, Asia Pacific dominates with a 23% market share, fueled by rapid industrialization, refinery expansions, and rising natural gas and oil production in China, India, and Australia. Europe follows with 19%, supported by strict sulfur emission standards and demand for ultra-low sulfur fuels, while North America accounts for 14%, driven by shale gas and LNG infrastructure development. Collectively, these regions represent the primary growth hubs for technology adoption and market expansion in sulfur recovery.
Market Insights
- The Sulfur Recovery Technology Market was valued at USD 1,726.6 million in 2024 and is projected to reach USD 2,918.4 million by 2032, growing at a CAGR of 6.81%.
- Rising demand for cleaner fuels and stricter environmental regulations globally are driving the adoption of advanced sulfur recovery technologies, particularly in oil and gas refineries and petrochemical plants.
- Industry trends show a shift toward sustainable operations, retrofitting older plants, and processing high-sulfur feedstocks using advanced Claus, superclaus, and hybrid processes to improve efficiency and reduce emissions.
- The market is highly competitive, led by key players such as Jacobs Engineering Group, Chiyoda Corporation, Technip FMC, Worley Parsons, Linde AG, and Fluor Corporation, focusing on R&D, partnerships, and technology optimization to capture high-value contracts.
- Regionally, Asia Pacific leads with a 23% market share, Europe holds 19%, North America 14%, Latin America 5%, Middle East 4%, and Africa 2%, while the natural gas feedstock segment dominates with 35% share and the Claus process leads technology adoption with 60%.
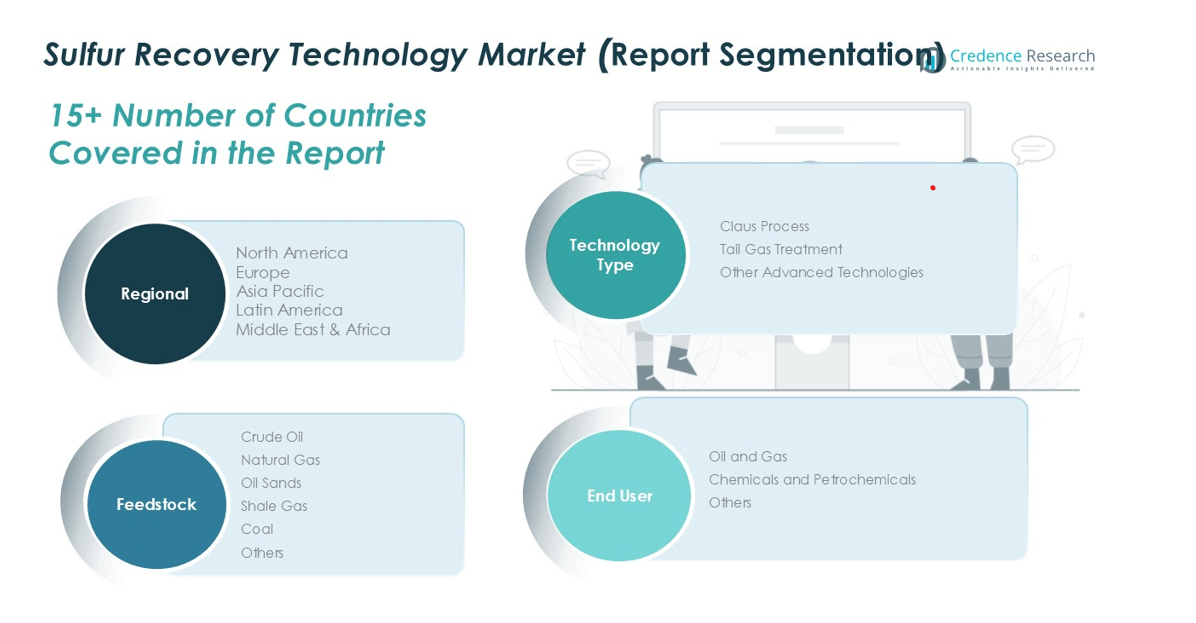
Market Segmentation Analysis:
By Feedstock
The Natural Gas sub-segment dominates the Sulfur Recovery Technology Market within the feedstock category, accounting for 35% of the market share. This leadership is driven by the rapid expansion of natural gas production and stringent environmental regulations requiring sulfur recovery to reduce emissions. Crude oil and coal also hold significant shares, supported by refinery expansions and coal-to-chemical processes. Oil sands and shale gas are witnessing gradual adoption due to technological advancements in sulfur removal. Overall, the feedstock segment growth is fueled by rising energy demand, cleaner fuel mandates, and increasing focus on sustainable operations.
- For instance, China's national mandates on sulfur dioxide emissions have prompted Sinopec to retrofit older Claus units with modern tail gas conversion reactors and hydrogenation systems, enhancing sulfur recovery efficiency
By Technology
Within the technology segment, the Claus Process holds a dominant position with 60% market share, owing to its widespread implementation, proven reliability, and cost-effectiveness in sulfur recovery. Tail Gas Treatment follows closely, enhancing overall sulfur recovery efficiency and meeting stringent environmental standards. Other advanced technologies, including superclaus and hybrid processes, are gradually gaining traction due to higher recovery rates and compatibility with complex feedstocks. The segment growth is primarily driven by refinery modernization, rising petrochemical output, and regulatory mandates on sulfur emissions in key global markets.
- For instance, ExxonMobil’s Fawley Refinery in the UK employs the three-stage Claus Process to recover more than 95% of elemental sulfur from acid gas streams, ensuring compliance with low-emission standards.
By End User
The Oil and Gas sub-segment leads the market with a share of 50%, reflecting extensive adoption of sulfur recovery technologies in refineries, gas processing plants, and petrochemical complexes. The chemicals and petrochemicals segment is expanding steadily due to increased production of fertilizers and industrial chemicals that require sulfur management. The “Others” category, encompassing power plants and coal gasification, contributes modestly but is poised for growth with emerging energy projects. Overall, end-user segment expansion is driven by stringent environmental regulations, rising global energy demand, and investment in clean fuel technologies.
Key Growth Drivers
Rising Demand for Cleaner Fuels
The increasing global focus on reducing sulfur emissions in fuels has significantly driven the adoption of sulfur recovery technologies. Stricter environmental regulations and government policies, especially in North America, Europe, and Asia Pacific, compel refineries and gas processing plants to implement efficient sulfur recovery solutions. The demand for ultra-low sulfur fuels in transportation and industrial sectors directly supports the growth of Claus process and tail gas treatment technologies. This regulatory push ensures steady investments and modernization of sulfur recovery infrastructure globally.
- For instance, Shell implemented advanced sulfur recovery units at its Pernis refinery in the Netherlands to meet the European Union’s ultra-low sulfur fuel standards.
Expansion of Oil and Gas Industry
Rapid growth in crude oil and natural gas production, particularly in emerging economies, fuels the demand for sulfur recovery solutions. The need to process high-sulfur feedstocks efficiently in refineries and gas plants drives the adoption of advanced sulfur recovery technologies. Investments in exploration, production, and refining facilities increase the market size while encouraging integration of tail gas treatment and hybrid recovery processes. Expansion of LNG production and shale gas development further boosts the adoption of sulfur recovery units to meet operational and environmental standards.
- For instance, Honeywell UOP has installed over 100 sulfur recovery units worldwide with recovery efficiencies up to 99.95%, incorporating technologies like the Shell Claus Off-gas Treating (SCOT) and Callidus Tailgas Scrubbing to achieve ultra-low sulfur emissions in refinery and gas processing plants.
Technological Advancements in Recovery Processes
Innovation in sulfur recovery technologies, including advanced Claus, superclaus, and hybrid processes, enhances efficiency and reduces operational costs. These technologies improve recovery rates from complex feedstocks such as shale gas and oil sands. Automation, process optimization, and integration with tail gas treatment solutions allow plants to meet stricter emission norms while maintaining profitability. Continuous R&D efforts and collaboration between engineering service providers and refineries accelerate adoption, offering a competitive advantage and driving market growth across regions.
Key Trends & Opportunities
Shift Toward Sustainable and Low-Emission Operations
Industry players are increasingly focusing on sustainable operations and reducing sulfur emissions across refineries and petrochemical plants. Adoption of energy-efficient recovery systems and integration with renewable energy sources presents growth opportunities. Additionally, retrofitting older plants with modern sulfur recovery technologies creates significant demand. Companies leveraging eco-friendly processes gain regulatory compliance and operational efficiency, positioning themselves strategically to benefit from the rising global emphasis on cleaner fuel production and low-carbon industrial practices.
- For instance, Dow Chemical is working toward carbon neutrality by 2050 by expanding its use of renewable energy and improving operational efficiencies in its petrochemical plants.
Emergence of High-Sulfur Feedstock Projects
The rising development of oil sands, shale gas, and heavy crude projects creates opportunities for advanced sulfur recovery solutions. Processing high-sulfur feedstocks requires robust technologies like superclaus and hybrid processes, offering high recovery efficiency. Companies investing in specialized equipment and tailored solutions can capture niche markets in regions with abundant high-sulfur resources. This trend is reinforced by the growing global energy demand and the need for sustainable refinery operations while maintaining compliance with environmental standards.
- For instance, Haldor Topsoe and Comprimo developed the TopClaus® technology, combining Claus and Wet Gas Sulfuric Acid (WSA) processes, to achieve sulfur recovery in excess of 99.9% while reducing energy intensity and equipment count.
Key Challenges
High Capital and Operational Costs
The installation and maintenance of sulfur recovery units, particularly advanced Claus and tail gas treatment systems, require substantial capital expenditure. Operational costs, including energy consumption, catalyst replacement, and skilled labor, further increase the total investment. Smaller refineries and developing markets often struggle with cost-effectiveness, slowing adoption. Balancing operational efficiency with regulatory compliance remains a challenge, and companies need to strategically plan investments and optimize recovery processes to ensure profitability while meeting stringent sulfur emission standards.
Stringent Regulatory Compliance and Environmental Norms
Meeting global environmental standards, such as ultra-low sulfur fuel mandates, poses significant challenges for refineries and gas processing facilities. Non-compliance can lead to heavy fines and operational restrictions, necessitating continuous monitoring and technology upgrades. Additionally, variations in regional regulations increase complexity for multinational operators. The need for consistent performance under stringent emission limits pressures companies to adopt advanced recovery technologies and tailor solutions for different feedstocks, creating both operational and strategic challenges in managing sulfur recovery operations efficiently.
Regional Analysis
North America
North America was valued at USD 254.42 million in 2018 and is expected to grow to USD 385.47 million in 2024 and USD 677.07 million by 2032, representing a CAGR of 7.3%. The region holds a market share of 14%, driven by stringent environmental regulations, refinery modernization, and expansion of natural gas and shale gas projects. The U.S. and Canada lead adoption of Claus and tail gas treatment technologies, while investments in LNG infrastructure and cleaner fuel production continue to propel market growth across the region.
Europe
Europe’s sulfur recovery technology market was valued at USD 335.31 million in 2018, projected to reach USD 486.60 million in 2024 and USD 807.81 million by 2032, growing at a CAGR of 6.6%. With a market share of 19%, Europe benefits from strict sulfur emission regulations and rising demand for ultra-low sulfur fuels. Germany, France, and the UK lead the market with refinery upgrades and chemical processing expansions. Advanced Claus and tail gas treatment technologies, combined with environmental compliance mandates, drive sustained adoption throughout the region.
Asia Pacific
Asia Pacific accounted for USD 400.47 million in 2018, expected to reach USD 586.49 million in 2024 and USD 985.83 million by 2032, with a CAGR of 6.7% and a market share of 23%. Growth is fueled by rapid industrialization, refinery expansions, and increasing natural gas and oil production in China, India, and Australia. Rising demand for cleaner fuels and adoption of advanced recovery technologies, including Claus and tail gas treatment, enhance operational efficiency. Strong energy demand and regulatory mandates make Asia Pacific the fastest-growing regional market.
Latin America
Latin America was valued at USD 85.94 million in 2018, projected to reach USD 123.20 million in 2024 and USD 201.08 million by 2032, at a CAGR of 6.3%, holding 5% of global market share. Brazil and Argentina lead the market with refinery modernization and high-sulfur crude processing projects. Environmental regulations and demand for cleaner fuels drive the adoption of advanced sulfur recovery technologies, while ongoing exploration and production expansions provide additional growth opportunities across the region.
Middle East
The Middle East market stood at USD 67.86 million in 2018, expected to grow to USD 100.76 million in 2024 and USD 172.48 million by 2032, at a CAGR of 7.0%. With a market share of 4%, growth is supported by rising oil and gas production, large-scale refinery projects, and stringent emission standards. GCC countries lead the adoption of advanced Claus and tail gas treatment technologies to ensure regulatory compliance and high recovery efficiency, while expansion of petrochemical facilities further strengthens market demand.
Africa
Africa’s sulfur recovery technology market was valued at USD 30.06 million in 2018, projected to reach USD 44.05 million in 2024 and USD 74.13 million by 2032, with a CAGR of 6.8% and a market share of 2%. South Africa and Egypt dominate regional growth, supported by refinery expansions and increased natural gas processing. Rising adoption of Claus and tail gas treatment technologies, coupled with stricter environmental regulations and industrial development projects, drives market expansion and creates long-term growth potential across Africa.
Market Segmentations:
By Feedstock
- Crude Oil
- Natural Gas
- Oil Sands
- Shale Gas
- Coal
- Others
By Technology
- Claus Process
- Tail Gas Treatment
- Other Advanced Technologies
By End User
- Oil and Gas
- Chemicals and Petrochemicals
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Sulfur Recovery Technology Market is led by key players including Jacobs Engineering Group, Chiyoda Corporation, John Wood Group (Amec Foster Wheeler), Technip FMC, Worley Parsons, Linde AG, Fluor Corporation, KT-Kinetics Technology SpA, GTC Technology US, and Heurtey Petrochem. Market competition is driven by the increasing adoption of advanced Claus, tail gas treatment, and hybrid sulfur recovery technologies to meet stringent environmental regulations and growing demand for cleaner fuels. Companies focus on strategic partnerships, mergers, and acquisitions to expand regional presence and enhance technological capabilities. Continuous innovation, including process optimization and automation, is key to improving recovery efficiency and reducing operational costs. Strong R&D investments, coupled with customer-centric solutions, allow players to differentiate offerings and capture high-value contracts across oil and gas, chemical, and petrochemical end-user segments globally. These dynamics intensify competition while promoting overall market growth.
Key Player Analysis
- Jacobs Engineering Group
- Chiyoda Corporation
- John Wood Group (Amec Foster Wheeler)
- Technip FMC
- Worley Parsons
- Linde AG
- Fluor Corporation
- KT-Kinetics Technology SpA
- GTC Technology US
- Heurtey Petrochem
Recent Developments
- In May 2025, AMETEK Process Instruments and Worley Comprimo announced a partnership to deliver the 2ACT™ Solution, a fully automated technology for sulfur recovery units.
- In July 2024, American Industrial Partners acquired Veolia North America's sulfuric acid regeneration business, rebranding it as Nexpera.
- In April 2024, Merichem Technologies, a portfolio company of Black Bay Energy Capital, acquired Chemical Products Industries (CPI), a provider of novel chemistries for sulfur removal and industrial cleaning applications.
- In August 2025, Marimaca Copper Corp. announced an option to acquire a 150,000 tonnes per annum (ktpa) sulfuric acid plant from CEMIN Holding Minero in Chile. This acquisition aims to secure a significant portion of the sulfuric acid supply for the Marimaca Oxide Deposit, reducing exposure to volatile acid markets
Report Coverage
The research report offers an in-depth analysis based on Feedstock, Technology, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to grow steadily due to increasing demand for ultra-low sulfur fuels.
- Expansion of oil, gas, and petrochemical industries will drive adoption of sulfur recovery technologies.
- Technological advancements, including hybrid and superclaus processes, will enhance recovery efficiency.
- Stricter environmental regulations globally will continue to push refineries to upgrade sulfur recovery units.
- Emerging markets in Asia Pacific and the Middle East will offer significant growth opportunities.
- Retrofitting older refineries with advanced recovery technologies will support sustained market expansion.
- Increasing investment in cleaner fuel production and sustainable operations will boost market demand.
- Collaboration between engineering service providers and refineries will accelerate technology adoption.
- Rising production of high-sulfur feedstocks will require more robust and efficient recovery solutions.
Continuous R&D and process optimization will create opportunities for cost reduction and higher operational efficiency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Sulfur Recovery Technology Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Sulfur Recovery Technology Marketprojected to grow between 2025 and 2032?
Which Sulfur Recovery Technology Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Sulfur Recovery Technology Market?
Who are the major players in this market?
Which region commanded the largest share of the Sulfur Recovery Technology Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Sulfur Recovery Technology Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Sulfur Recovery Technology Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 1,726.6 million → 2032: USD 2,918.4 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Sulfur Recovery Technology Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Sulfur Recovery Technology Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Sulfur Recovery Technology Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Sulfur Recovery Technology Market Drivers
- 3.3 Sulfur Recovery Technology Market Restraints & Challenges
- 3.4 Sulfur Recovery Technology Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Sulfur Recovery Technology Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Sulfur Recovery Technology Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Sulfur Recovery Technology category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Sulfur Recovery Technology Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Sulfur Recovery Technology Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Sulfur Recovery Technology market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Sulfur Recovery Technology Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Sulfur Recovery Technology Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Sulfur Recovery Technology Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Sulfur Recovery Technology (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Sulfur Recovery Technology Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Sulfur Recovery Technology Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Sulfur Recovery Technology Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Sulfur Recovery Technology Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Sulfur Recovery Technology Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Sulfur Recovery Technology Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Sulfur Recovery Technology Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Sulfur Recovery Technology Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Sulfur Recovery Technology Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
