
Clear polyimide film spreads beyond foldable phone windows
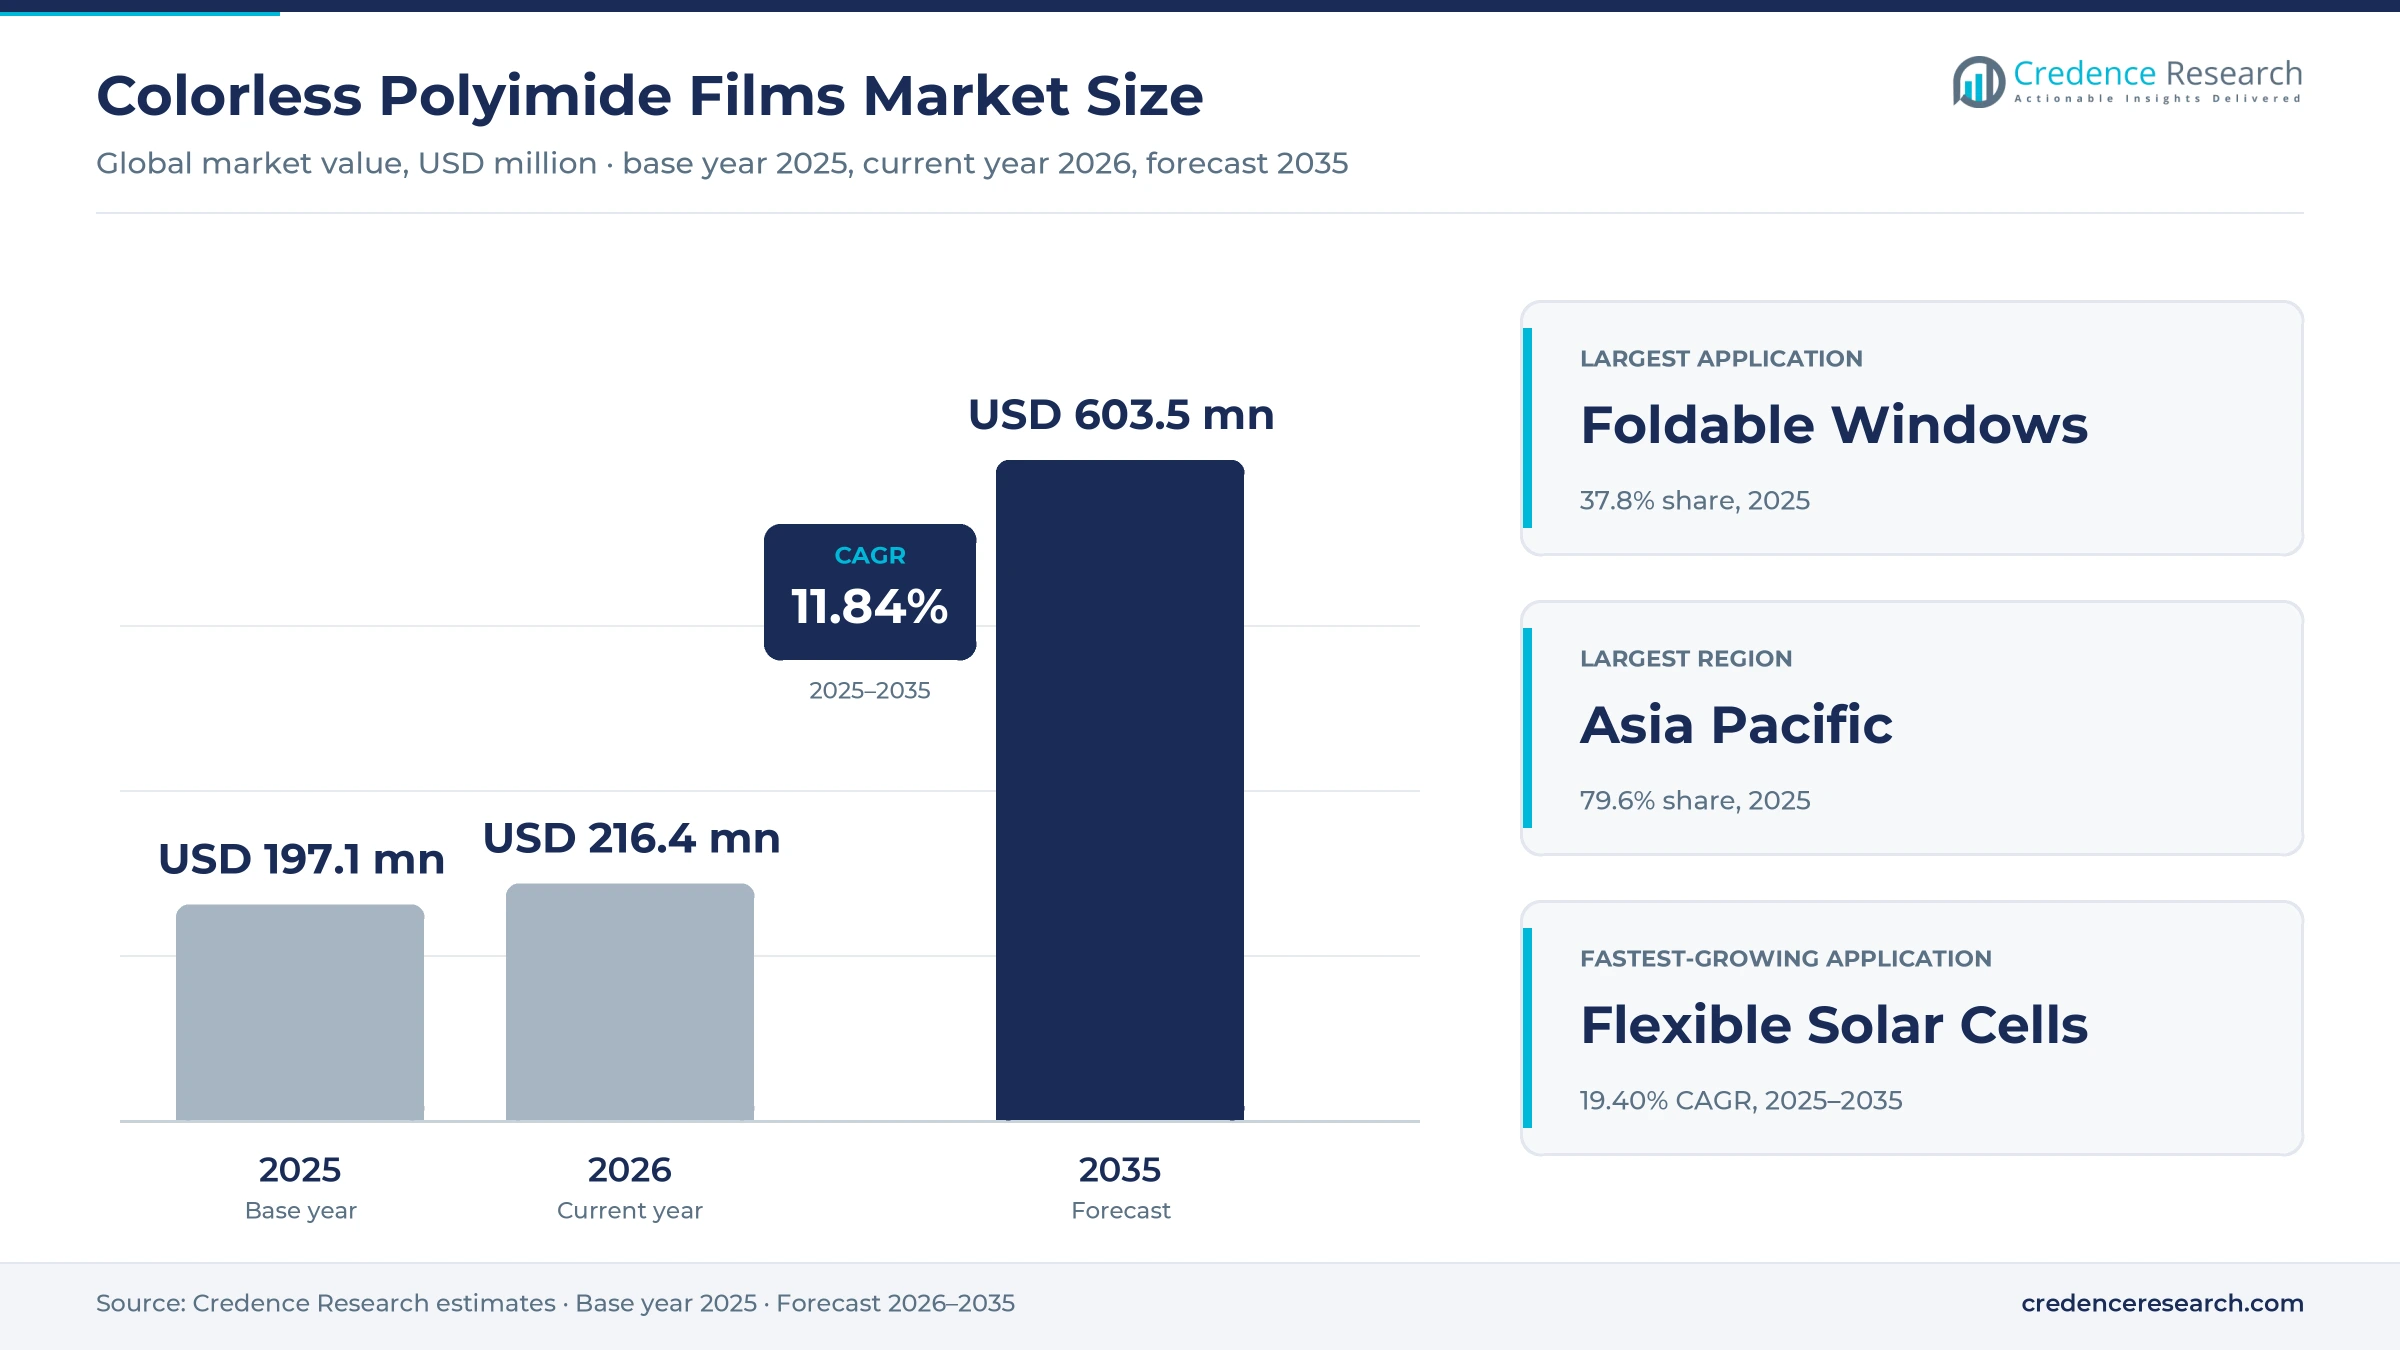
The colorless polyimide films market was valued at USD 197.1 million in 2025 and is projected to increase from USD 216.4 million in 2026 to USD 603.5 million by 2035, registering a CAGR of 11.84% during 2025–2035. Demand rests on protective films laminated over foldable ultra-thin glass, clear substrates for transparent, rollable and car displays, see-through circuits and space-grade solar covers that must tolerate heat and radiation. Asia Pacific held the largest regional share, 79.6% in 2025, because Korea and Japan host the film makers and Korea, China and Vietnam laminate most film into devices. The main commercial change is the move of premium foldable main screens to ultra-thin glass, which turned colorless polyimide (CPI) from the complete cover window into a hard-coated top layer and pushed suppliers toward substrates, circuits and solar film, where growth is now fastest.
What counts as colorless polyimide film?
The scope covers polyimide films engineered for high light transmission and a low yellowness index, sold in roll or sheet form, with or without a hard coat. Most grades use fluorinated monomers or alicyclic structures to break up the charge-transfer complexes that give ordinary polyimide its amber color. The market spans 6 application groups and 3 chemistry types.
Standard amber polyimide film is excluded, as is polyimide varnish cast on glass to form flexible OLED backplanes, which never ships as a film. Ultra-thin glass and PET or TAC protective films with no polyimide content are also excluded, which is why earlier estimates assuming every foldable used a CPI window were far larger.
Colorless Polyimide Films Market Insights
- The colorless polyimide films market is projected to grow from USD 216.4 million in 2026 to USD 603.5 million by 2035, an 11.84% CAGR, as uses widen beyond foldable phone windows.
- Asia Pacific held 79.6% of 2025 value, the largest regional share, because Korean and Japanese film makers supply panel and phone plants in Korea, China and Vietnam.
- Foldable cover windows and protective layers accounted for 37.8% of 2025 value, the largest application, though ultra-thin glass now takes most premium main screens.
- Flexible solar cells are the fastest-growing application at 19.40% a year, through 2035, as satellite constellations and solar sails need light, radiation-tolerant clear film.
- Ownership is consolidating. Arkema completed a 54% stake purchase in PI Advanced Materials in December 2023, and DuPont's electronics arm now trades as Qnity Electronics.
Foldable windows lead as solar film and alicyclic CPI surge
Foldable windows lead applications while flexible solar cells grow fastest
Based on application, the market is categorized into foldable cover windows and protective layers, display substrates and optical layers, flexible printed circuits, touch panels and sensors, flexible solar cells and AR optics, lighting and others. Foldable cover windows and protective layers led with 37.8% of 2025 value, combining full polymer windows on lower-priced foldables with top films over glass. Flexible solar cells grow fastest at 19.40% a year on satellite arrays and solar sails.
Fluorinated CPI leads by type while alicyclic grades grow fastest
Based on type, the market is categorized into fluorinated CPI, alicyclic CPI and noncoplanar and other CPI. Fluorinated CPI, built on monomers such as 6FDA and TFMB, led with 71.8% of 2025 value, because it gives the best mix of clarity, low yellowness and heat resistance and was the first chemistry qualified for foldable windows. Alicyclic CPI grows fastest at 13.60% a year, as it uses less fluorine and eases cost and chemicals-rule pressure.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2025–2035 |
|---|---|---|---|---|
| By Application | Foldable Cover Windows & Protective Layers | 37.8% | Flexible Solar Cells | 19.40% |
| By Type | Fluorinated CPI | 71.8% | Alicyclic CPI | 13.60% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Top films, clear substrates and space solar lift CPI demand
Glass moved CPI to the top of the foldable stack, not out of it
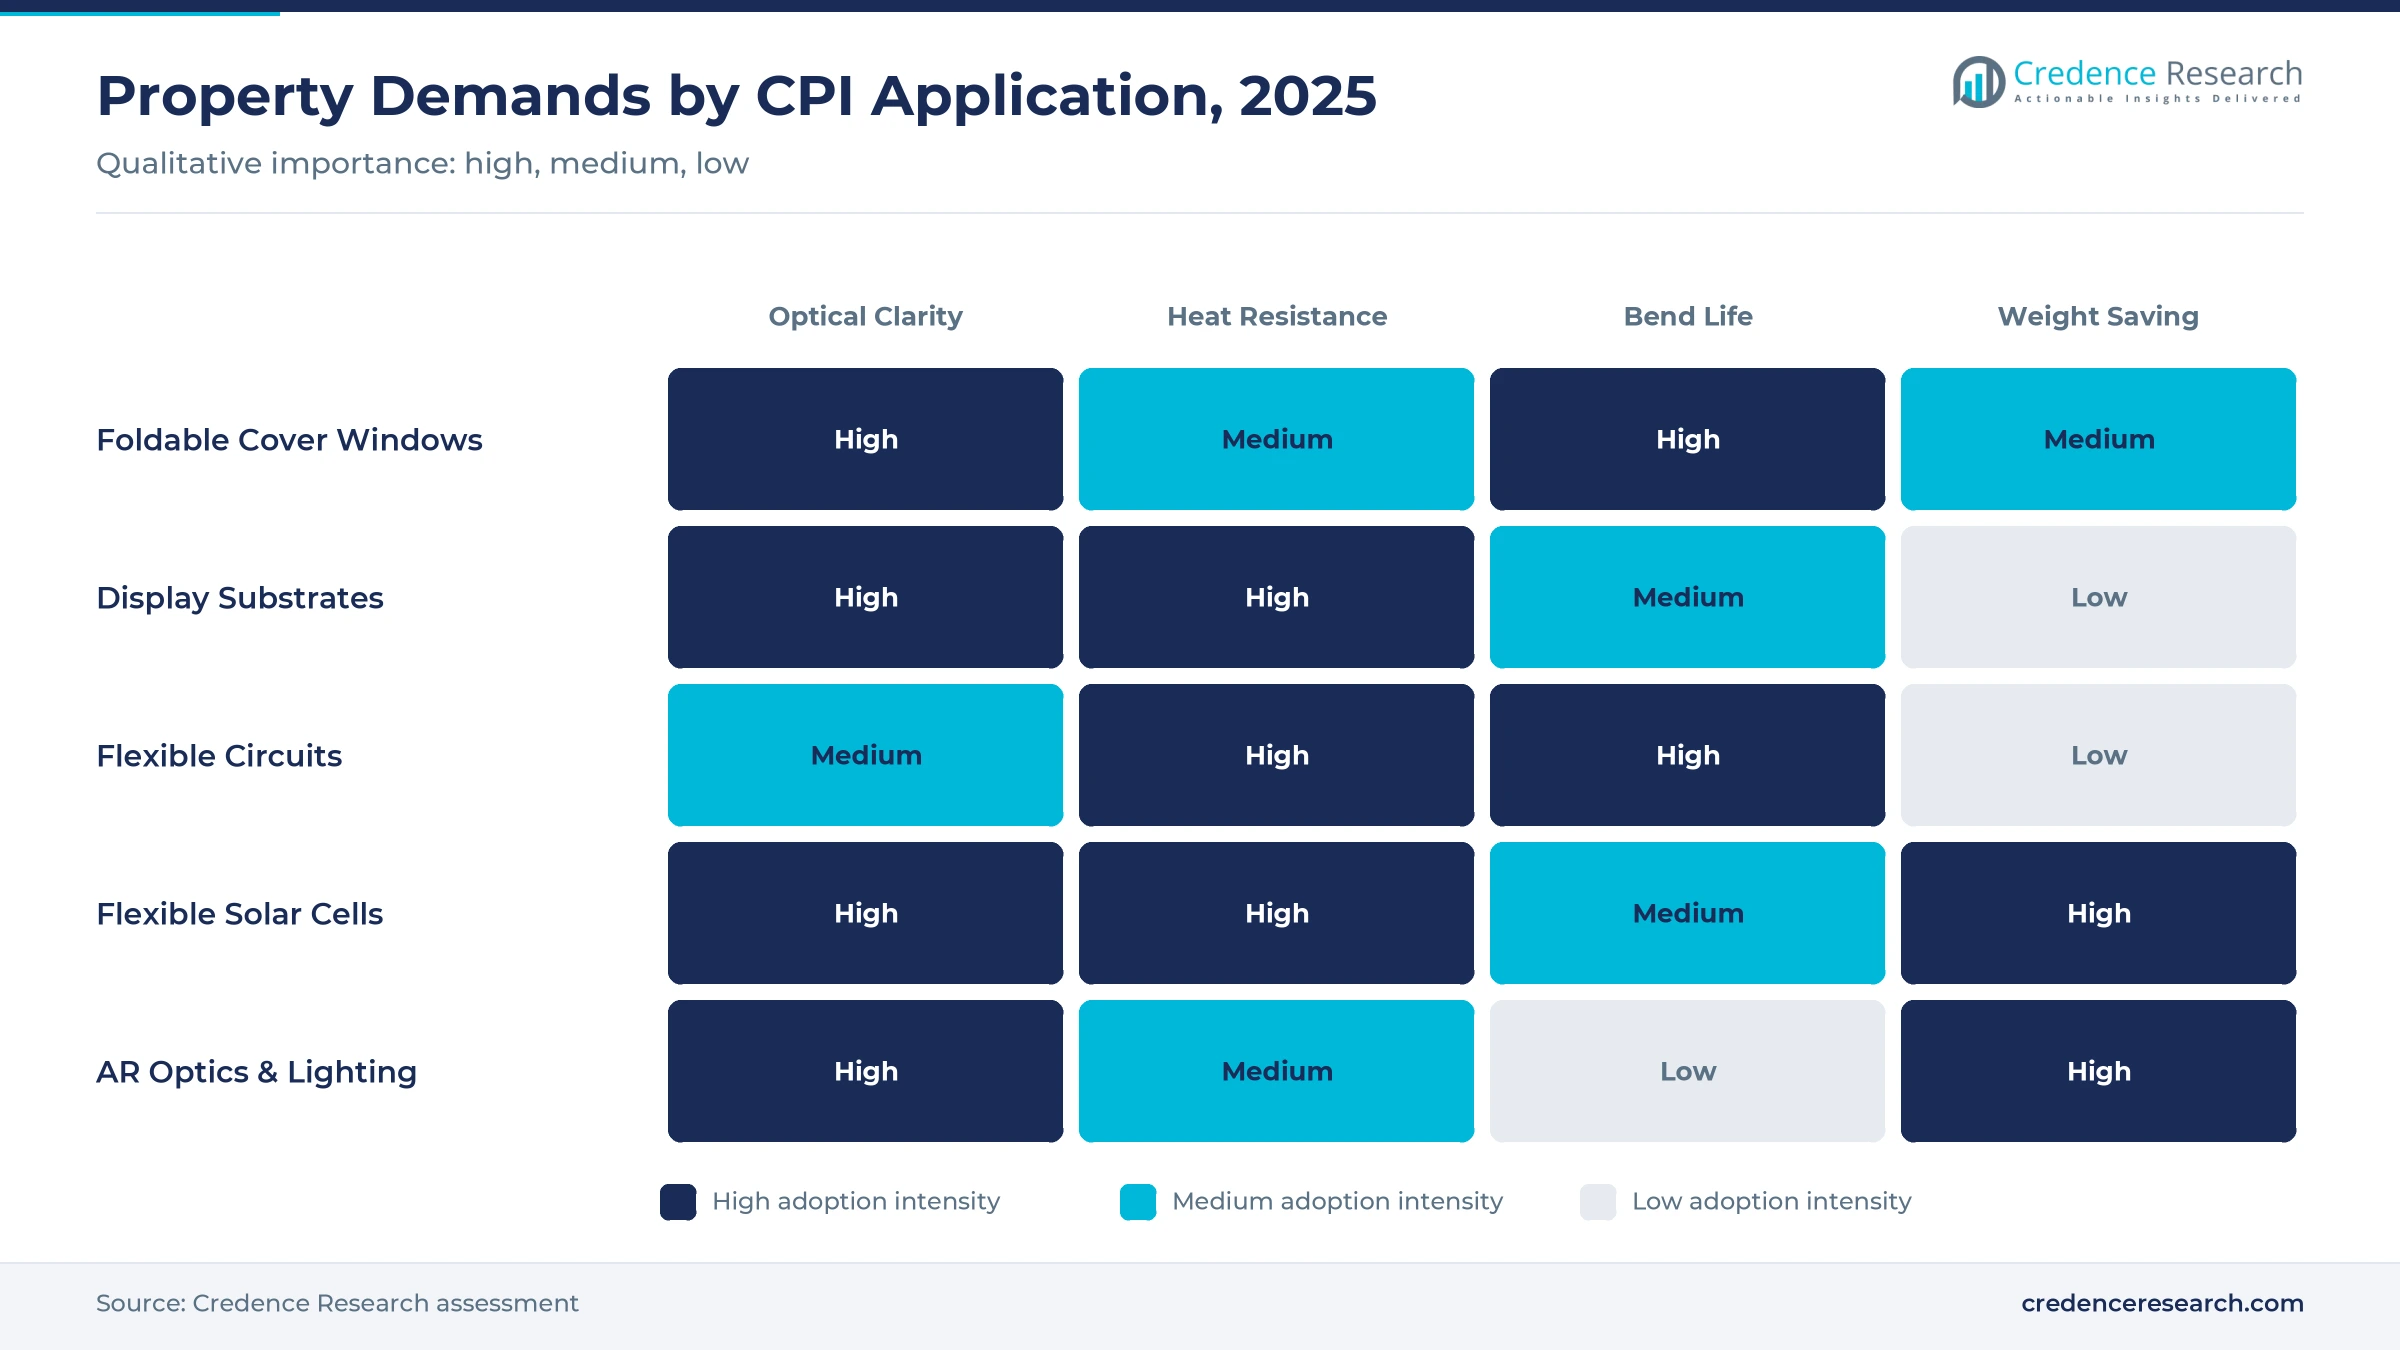
A folding screen with an ultra-thin glass window still needs a polymer layer on top to hold shards if the glass cracks and to take daily scratches, and brands replace that layer at service centers, which creates recurring aftermarket demand. Samsung unveiled the Galaxy Z Fold8 Ultra, with an 8-inch main display, plus the Fold8 and Flip8 at Galaxy Unpacked in London on July 22, 2026. Chinese brands, meanwhile, refresh book- and flip-style models every year, which keeps the foldable smartphone base growing.
Transparent, rollable and car displays need a heat-proof clear substrate
Standard polyimide is amber, which works under an emissive OLED layer but not where light must pass through. Under-panel cameras, transparent displays, rollable panels and curved car dashboards need a substrate that survives thin-film processing heat and stays clear, and CPI keeps its shape above the temperatures that soften PET. Kolon Industries lists automotive cover windows, transparent displays and head-up displays among its CPI applications. Panel makers in Korea, China and Japan carry this demand over the next 5 to 10 years.
Satellite constellations and solar sails pull space-grade film
Colorless polyimide began in space research, where NASA Langley scientists found some polyimide films nearly colorless, and the LaRC-CP1 and CP2 polymers were licensed to NeXolve of Huntsville, Alabama, according to NASA's technical reports server. A NASA paper in April 2025 found no significant embrittlement in metallized CP1 solar sail film after exposure on the International Space Station. Large satellite constellations now need light, flexible solar arrays in volume, making flexible solar cells the fastest-growing application at 19.40% a year.
Weight savings open AR glasses and flexible lighting
CPI weighs a little over half as much as glass of the same thickness and does not shatter. That matters most in AR glasses, where every gram on the nose counts, and in flexible lighting panels, so the opportunity lies in waveguide laminates, protective covers and transparent circuits. Phones show the same pressure, since the Fold8 Ultra weighs 215 grams and measures 4.1 millimeters unfolded, so every layer must justify its weight and thickness.
Hard-coated top films and thinner stacks reshape CPI supply
CPI shifts from whole cover window to hard-coated top layer
CPI was sold as the complete foldable cover window in 2019 and 2020, but by 2026 the premium phones that set volume more often use it as a thin hard-coated layer over glass or as one film in a laminated stack. As a result, film makers now compete on hard-coat chemistry and crease recovery rather than bend life alone.
Thinner display stacks reward low-gauge optical film
Samsung said in September 2026 that the layers inside its Fold8 display had to become thinner while meeting its durability standards, and it described a titanium alloy support film only tens of micrometers thick. The Fold8, with a 7.6-inch main display and a 5.5-inch cover screen, weighs 201 grams. Thinner stacks reward films that keep their optics at low gauge, which favors CPI over thicker PET, but they also cut film area per device.
Fluorine-light grades gain an opportunity as PFAS scrutiny grows
Most CPI value rests on fluorinated monomers, as fluorinated grades held 71.8% of 2025 value, and although wider PFAS restrictions in Europe and the United States do not yet target polyimide films directly, customers are asking for fluorine-light alternatives. Alicyclic CPI, the fastest-growing type at 13.60% a year, avoids part of the fluorine content, which eases cost and regulatory risk. Suppliers with qualified alicyclic and noncoplanar grades can win optical-layer and solar-cover programs, though reformulation adds cost.
Transparent circuits and LED film open an opportunity beyond the phone
Flexible circuits on amber polyimide are the default for phones and wearables, and the flexible printed circuit board industry is the largest outlet for ordinary polyimide film. A transparent base opens uses such as see-through LED film for shop windows, circuits in a camera or display light path and invisible hinge wiring. Circuit makers that qualify CPI can add value per board, though price remains a barrier.
Ultra-thin glass and costly monomers cap CPI demand
Ultra-thin glass keeps taking premium main screens
Ultra-thin glass is the biggest single risk to this market, because it feels harder, resists scratches better and keeps a premium look after many folds. Each foldable model moved from a polymer window to glass loses most of its CPI value, leaving only the top film. Cover window suppliers, serving a segment that held 37.8% of 2025 value, are most exposed, and they respond with replaceable protectors, larger foldable PCs and tablets where glass is costly and fragile, and a shift of capacity to substrates.
Costly monomers and slow casting lines keep prices high
Colorless grades use costlier monomers than amber polyimide, run on slower casting lines and need clean-room handling and optical inspection, and yields on wide, defect-free hard-coated film remain a constraint. Price is the main barrier in solar and lighting, where CPI competes with cheaper clear polyesters and fluoropolymers. Suppliers reduce cost through wider lines, higher yields and grades with fewer fluorinated monomers, while targeting uses where heat resistance justifies the premium.
Hard coats must balance fold-line cracking against scratches
Because the tough polyimide base film is soft on the surface, it needs a hard coat, yet a coat that is too brittle cracks at the fold line and one that is too soft scratches. Each new device design therefore forces another round of customer qualification, and smaller suppliers struggle to fund repeated approvals, which limits competition. Leaders rely on in-house coating chemistry and early work with panel makers on each new hinge design.
Concentrated chemistry supply still carries trade risk
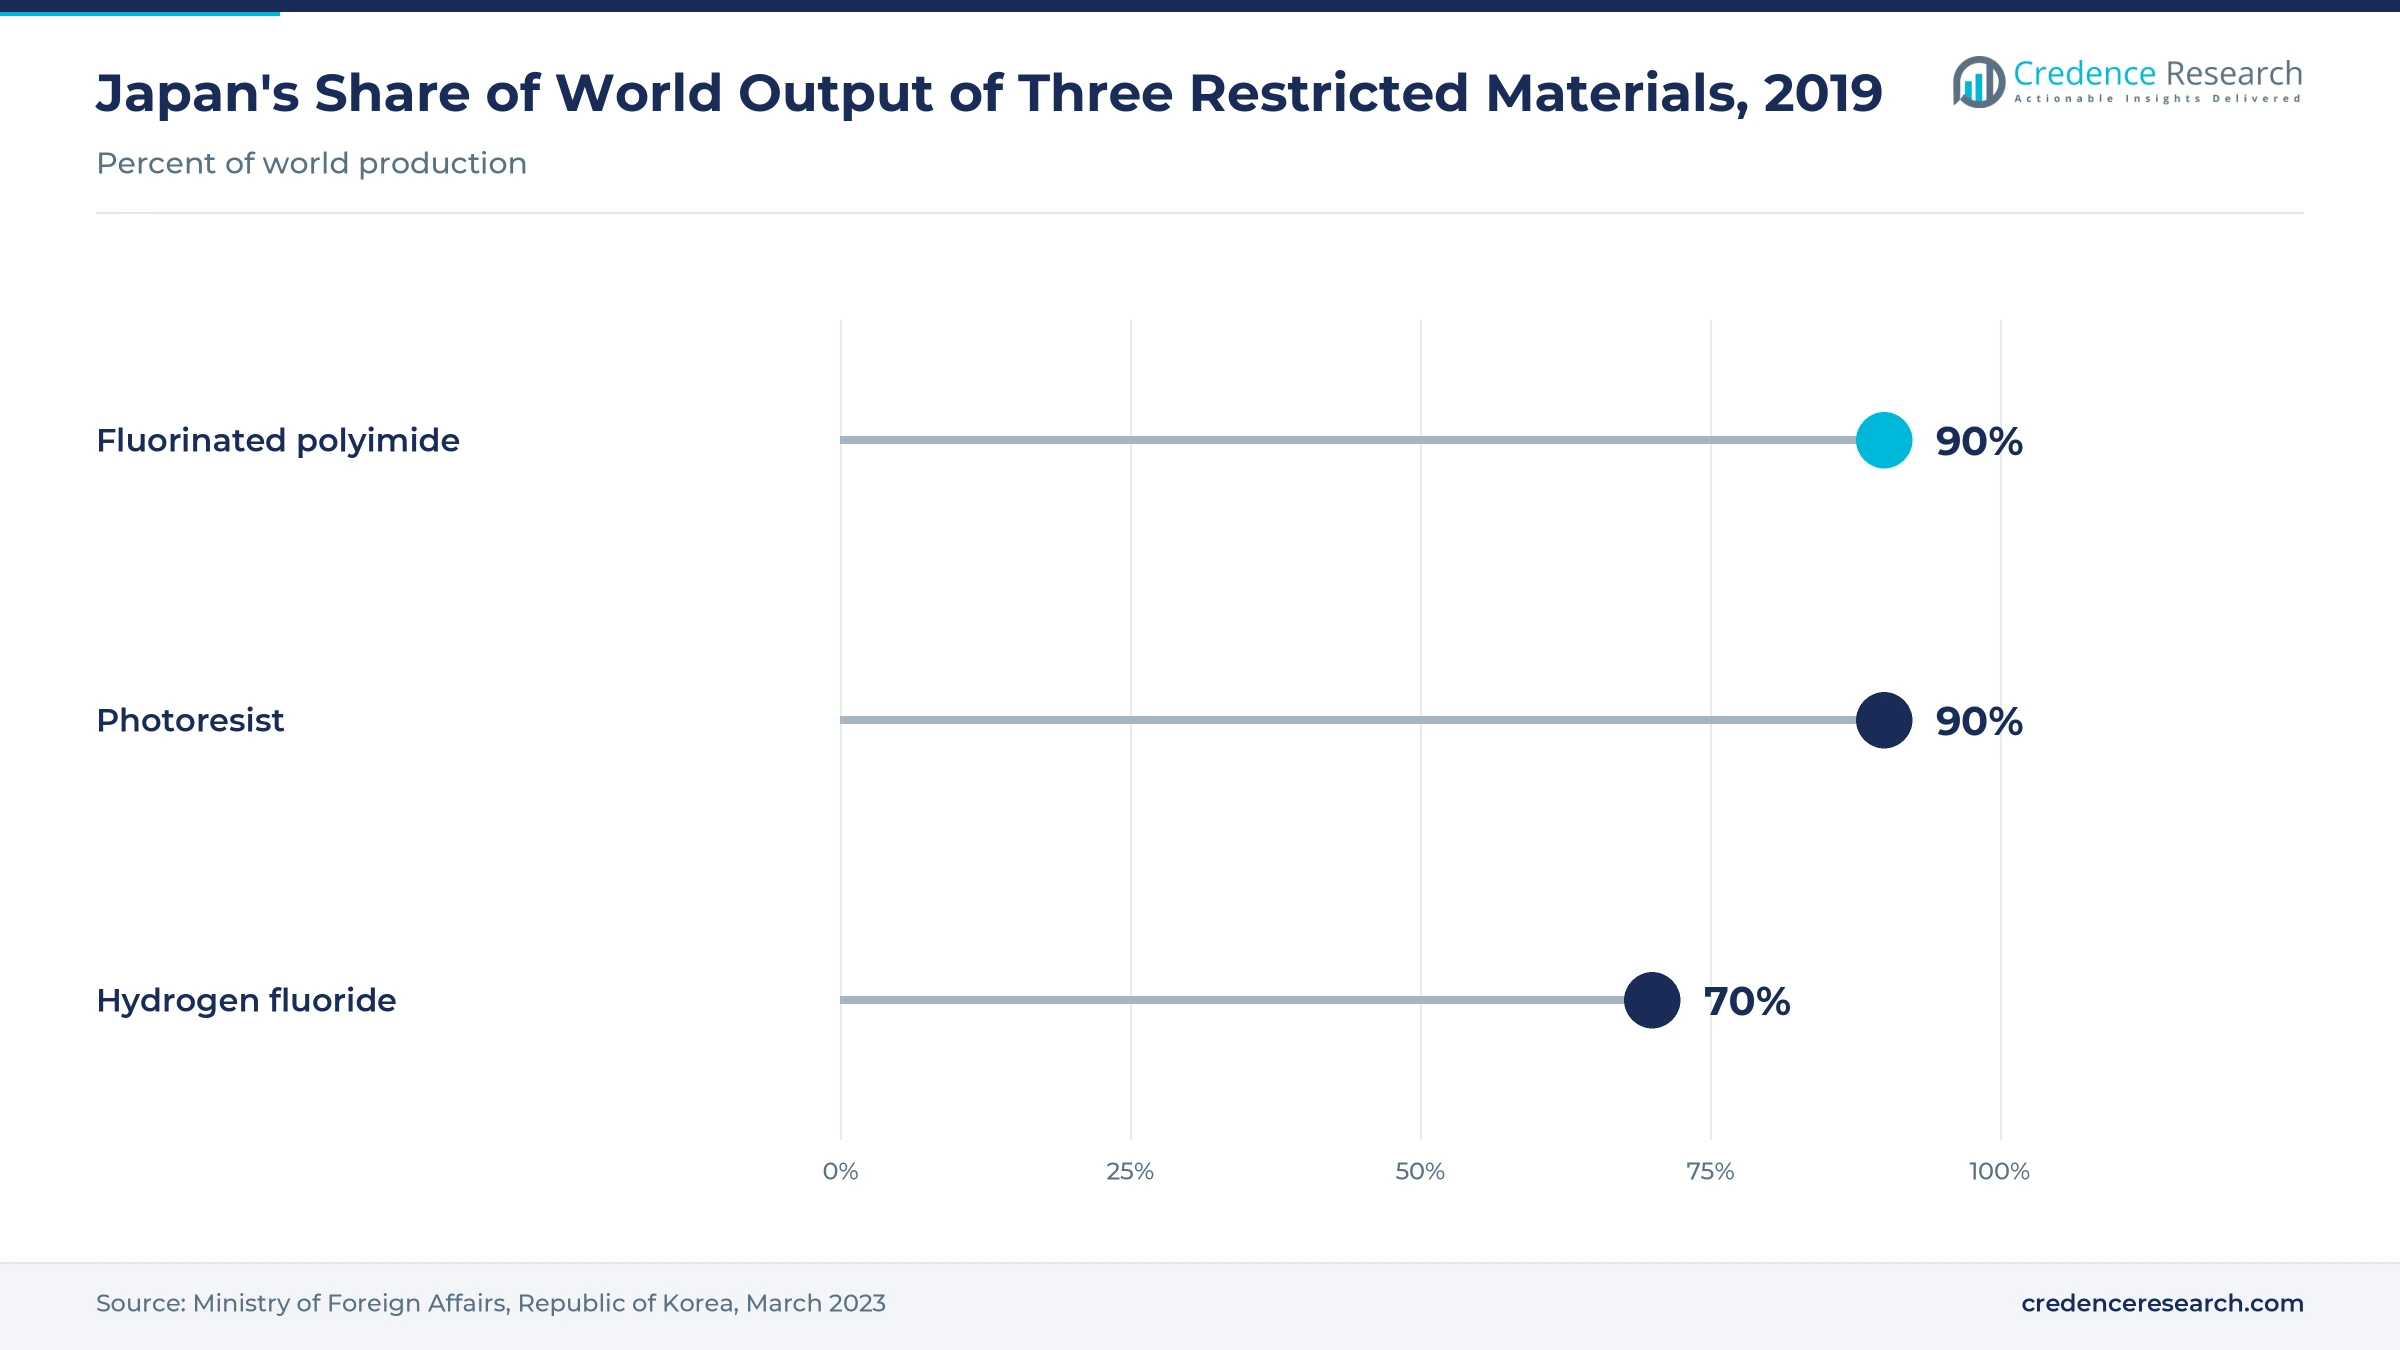
In July 2019, Japan introduced individual licenses for each shipment of fluorinated polyimide to Korea, as SEMI reported at the time. Japan scrapped those curbs in March 2023, the first easing in 44 months, but the episode showed how quickly policy can disrupt panel makers when Japan made 90% of the world's fluorinated polyimide. Korean display makers now keep local CPI suppliers on approved lists and dual-source from Korea and Japan.
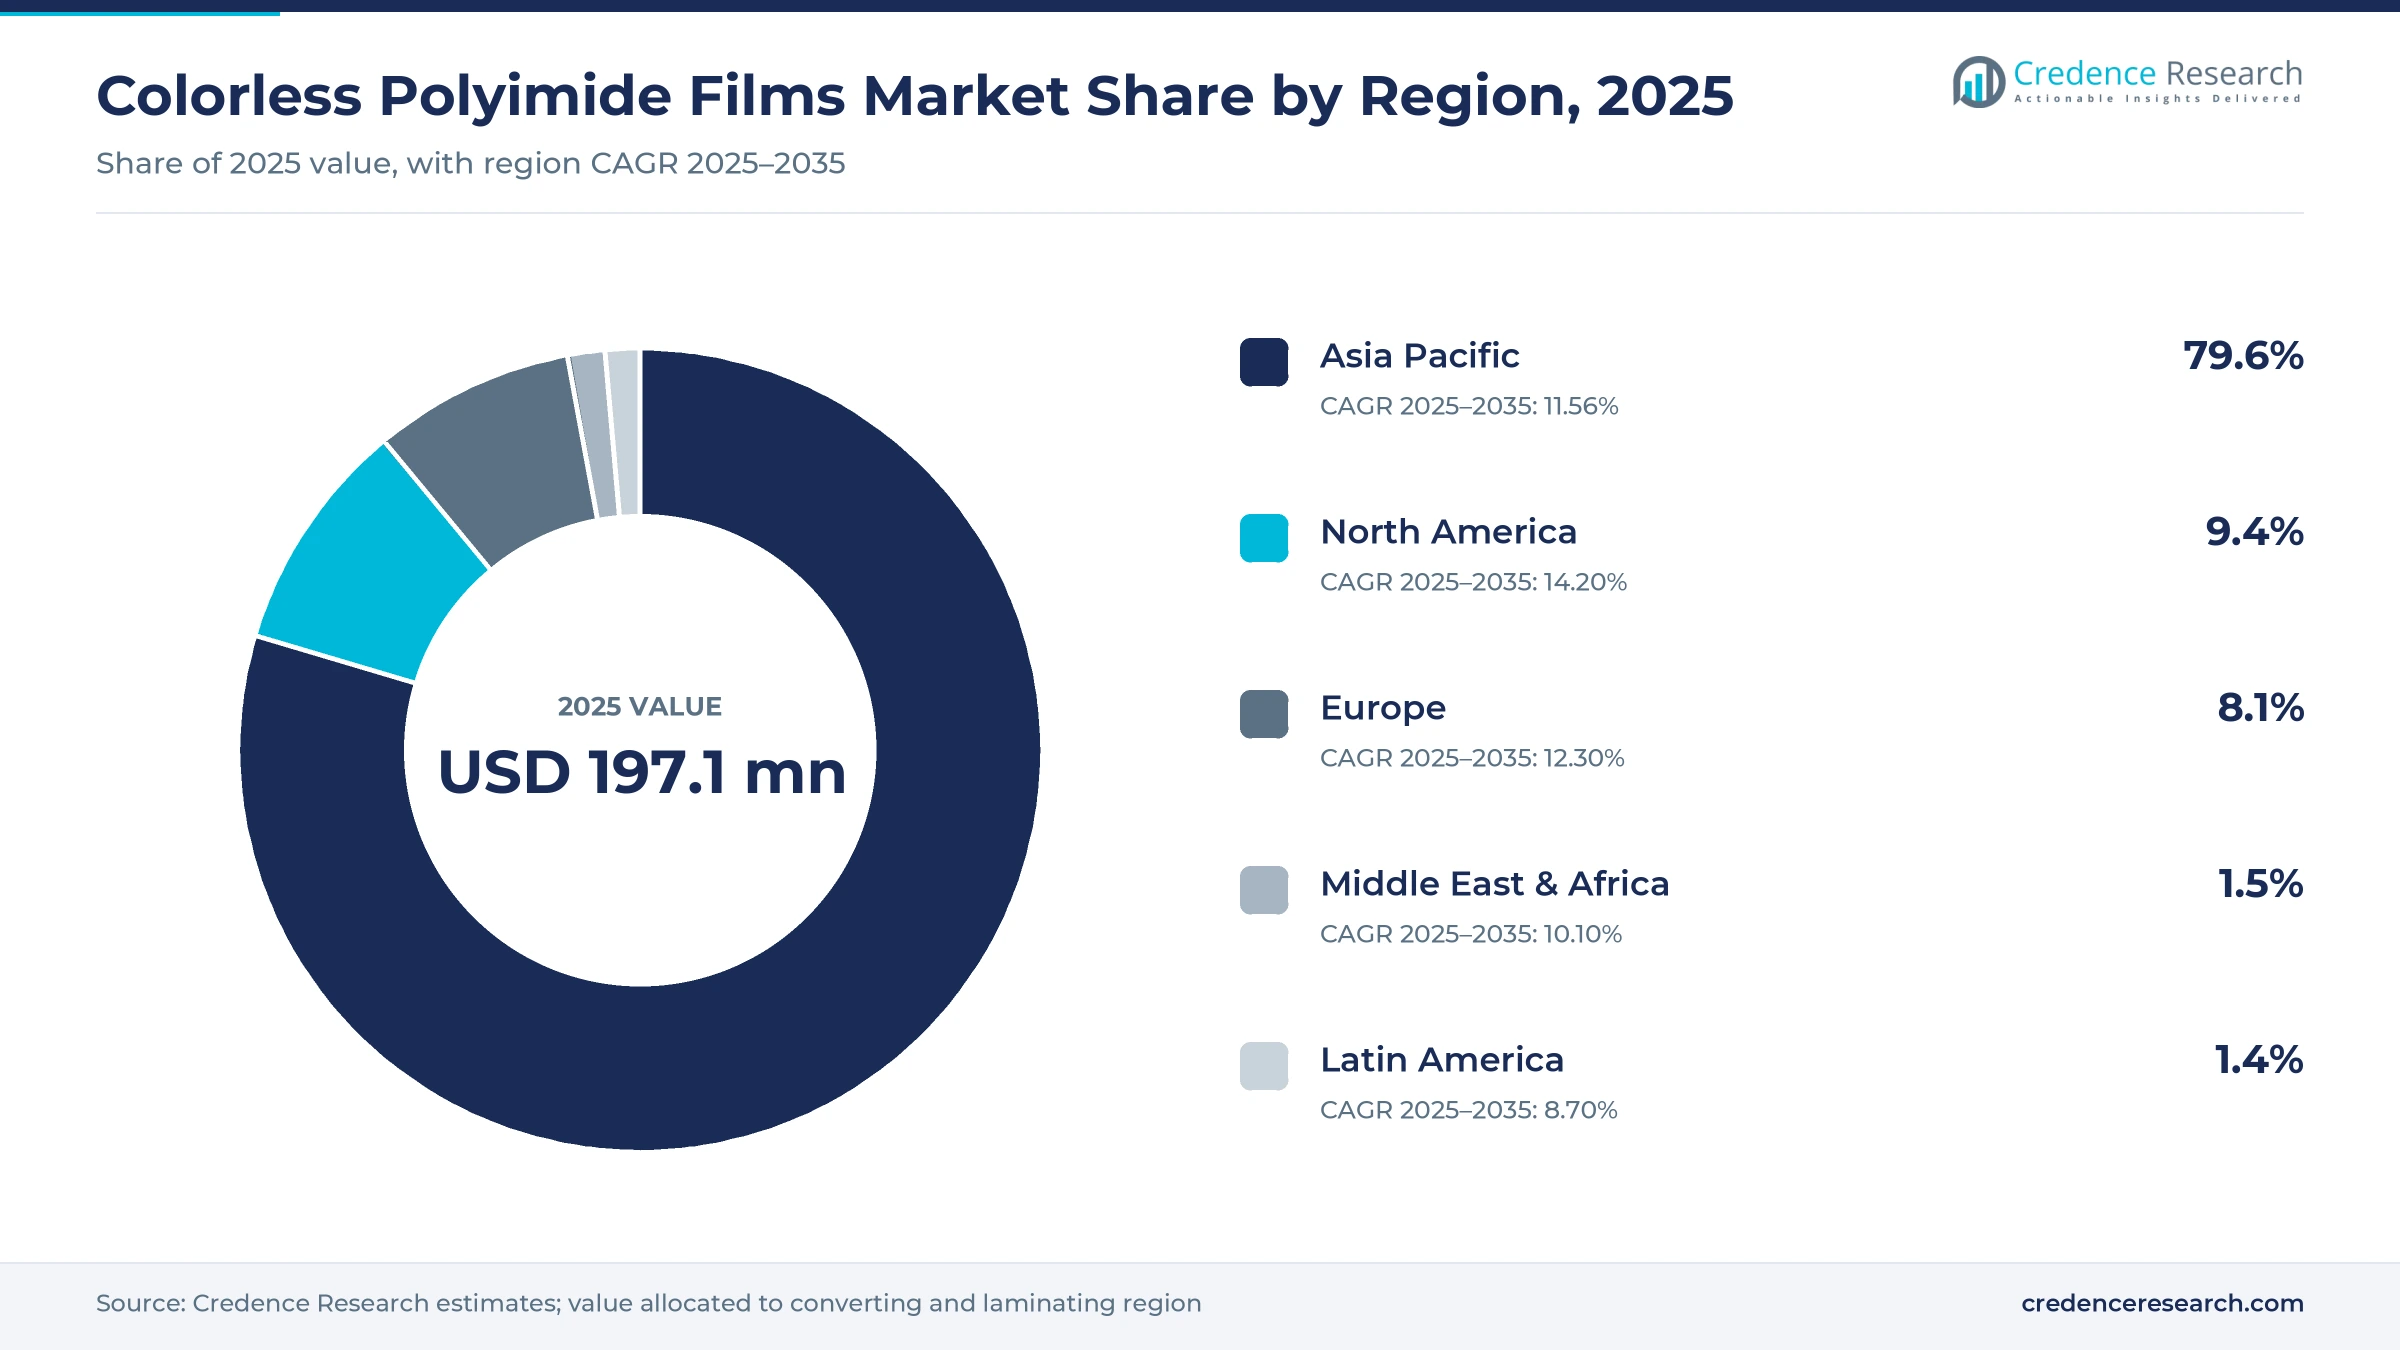
Asian converters dominate while North America grows fastest
| Region | Share, 2025 | CAGR, 2025–2035 |
|---|---|---|
| Asia Pacific | 79.6% | 11.56% |
| North America | 9.4% | 14.20% |
| Europe | 8.1% | 12.30% |
| Middle East & Africa | 1.5% | 10.10% |
| Latin America | 1.4% | 8.70% |
Asia Pacific relies on Korean and Japanese film makers feeding regional panel plants
Asia Pacific held 79.6% of 2025 value and grows at 11.56% a year. Korea and Japan host the film makers, while Korea, China and Vietnam host the panel, module and phone plants that laminate the film, and Chinese foldable brands are the main users of full polymer windows. Japan produced 90% of the world's fluorinated polyimide in 2019, according to Korea's Ministry of Foreign Affairs, which is why Korea built local lines.
North America grows fastest on space solar and AR programs
North America held 9.4% of 2025 value and is the fastest-growing region at 14.20% a year, about 2.4 percentage points above the global rate. Satellite solar arrays, space research and AR device programs drive that demand. Among suppliers, Qnity Electronics, the former DuPont electronics business that began reporting as a separate company in August 2026, lists high-transparency films within its Kapton portfolio.
Europe draws demand from car displays, space solar and perovskite research
Europe held 8.1% of 2025 value and grows at 12.30% a year. Car display makers, space solar suppliers and research institutes buying film for flexible perovskite cells make up most demand. On the supply side, Arkema completed its acquisition of a 54% stake in PI Advanced Materials on Dec. 1, 2023, according to Arkema, giving a European chemicals group control of the largest polyimide film maker.
Middle East & Africa and Latin America build on device assembly and early satellite programs
The Middle East & Africa held 1.5% of 2025 value and grows at 10.10% a year, mostly from device assembly and early satellite programs in the Gulf. Latin America held 1.4% of 2025 value and grows at 8.70% a year, led by phone and display assembly in Brazil and Mexico.
Foldable launches and a space-exposure study mark 2025–2026
| Development | Status and market relevance |
|---|---|
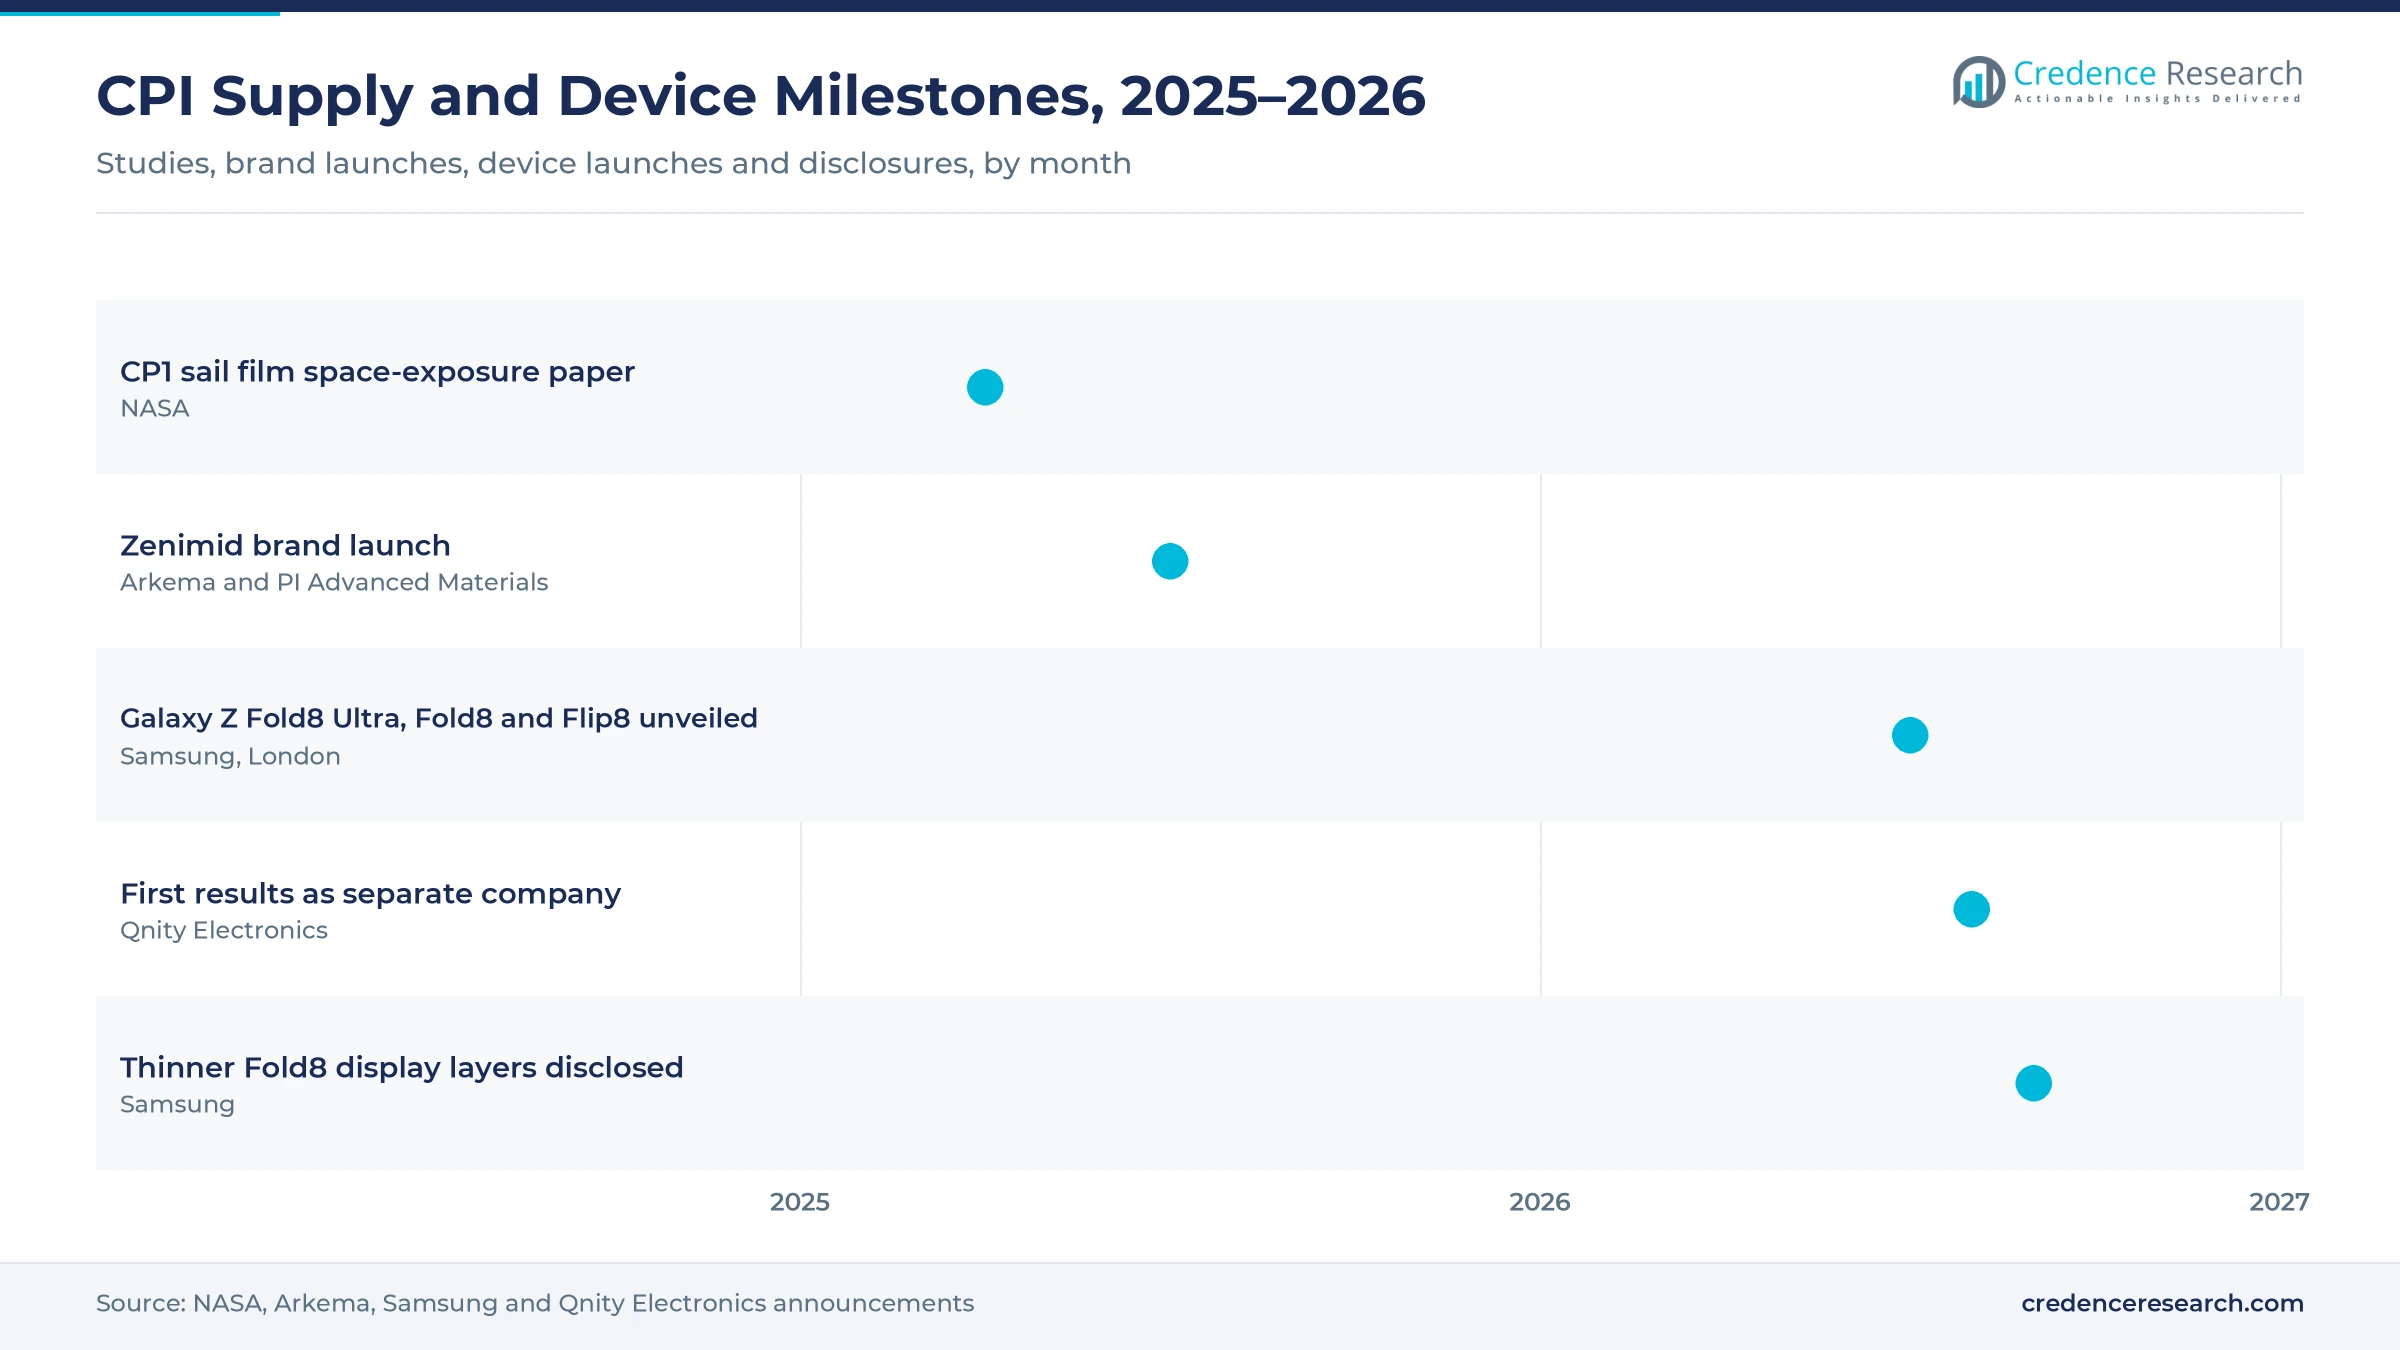
| In September 2026, Samsung said the display layers in its Galaxy Z Fold8 had to become thinner, using a titanium alloy support film tens of micrometers thick. | Disclosed. Thinner stacks favor low-gauge optical film but cut film area per device. |
| In August 2026, Qnity Electronics, the former DuPont electronics business that sells Kapton, reported second-quarter 2026 results as a separate company. | Reported. Puts a major polyimide brand inside a focused electronics materials group. |
| In July 2026, Samsung unveiled the Galaxy Z Fold8 Ultra, Fold8 and Flip8 at Galaxy Unpacked in London on July 22. | Launched. Sets the yearly foldable volume behind protective-layer demand. |
| In July 2025, Arkema and PI Advanced Materials launched the Zenimid brand for their polyimide film, varnish and stock shapes. | Launched. Signals a push to grow the polyimide platform in electronics. |
| In April 2025, a NASA paper reported no significant embrittlement in metallized CP1 solar sail film after space exposure. | Published. Supports colorless polyimide in long-life space solar uses. |
Monomer design and hard coats set the CPI technology agenda
- Fluorinated monomers such as 6FDA and TFMB break up the charge-transfer complexes that make polyimide amber.
- Alicyclic chemistry cuts fluorine content while keeping clarity, easing cost and chemicals-rule pressure.
- Hard coats must resist scratches without cracking at the fold line, and each new hinge design needs its own qualification.
- Low-gauge films gain as display stacks thin, with support films only tens of micrometers thick.
- Space durability is proven, as metallized CP1 film showed no significant embrittlement on the International Space Station.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Korean and Japanese film makers control optical-grade CPI
Few companies can make optical-grade CPI at scale, and Credence Research estimates the top five suppliers hold more than three-quarters of global value. Korean makers lead foldable windows, with Kolon Industries claiming the world's first mass-production CPI line and SK microworks developing hard-coated CPI with former parent SKC, while Sumitomo Chemical sells hard-coated transparent polyimide film to Korean panel makers. Japanese firms hold much of the chemistry, as Mitsubishi Gas Chemical sells Neopulim and Kaneka and Toray Industries develop colorless films and varnishes. Qnity Electronics offers high-transparency Kapton grades, PI Advanced Materials brings scale in amber film casting under Arkema's 54% stake, and NeXolve holds the NASA license for space-grade film. Chinese film makers are building transparent lines and are likely to win share first in lower-priced foldables and flexible circuits.
CPI film suppliers profiled and their roles
| Company | Type | Role in the market |
|---|---|---|
| Sumitomo Chemical | Display materials maker | Hard-coated transparent polyimide film for foldable screens |
| Kolon Industries | Film maker | CPI for foldable and rollable windows, car displays and head-up displays |
| SK microworks | Film maker | Hard-coated CPI for foldable covers, developed with former parent SKC |
| Mitsubishi Gas Chemical | Specialty chemicals maker | Transparent polyimide sold as Neopulim |
| Kaneka | Specialty chemicals maker | Colorless and low-color polyimide films and varnishes |
| Toray Industries | Specialty chemicals maker | Colorless and low-color polyimide films and varnishes |
| Qnity Electronics | Electronics materials maker | High-transparency films in the Kapton portfolio |
| PI Advanced Materials | Polyimide film maker | Largest polyimide film maker, Zenimid brand; transparent-grade output not confirmed |
| NeXolve | Space film specialist | NASA-licensed LaRC-CP1 and CP2 film for spacecraft and solar sails |
| Arkema | Chemicals group | Majority owner of PI Advanced Materials; direct CPI role not confirmed |
CPI has found a second career beyond the foldable window
Credence Research's view is that colorless polyimide is a specialty film with a real but narrow market, and its growth now depends on uses beyond the foldable phone window. Suppliers with hard-coat know-how, fluorine-light chemistry and approvals at Korean and Chinese panel makers are best placed. The main risk is further glass substitution; watch foldable launches and PFAS rules.
Film area, prices and supplier data anchor the CPI estimate
The report uses 2025 as the base year and forecasts to 2035, with CAGR calculated over 2025–2035. Market values come from Credence Research's market model, built from film area after yield losses and average selling prices for 6 application groups and checked against supplier disclosures and foldable launch details; application, type and regional splits are Credence Research estimates.
Substrates, circuits and space solar outgrow phone windows
Through 2035, CPI demand will shift from foldable phone windows toward display substrates, transparent circuits, AR optics and space-grade solar covers, and fluorine-light grades will gain as chemicals rules tighten. Asia Pacific, growing 11.56% a year, remains the center of conversion, while North America grows fastest at 14.20% a year and Europe follows at 12.30%, so total value roughly triples over 10 years.
Frequently Asked Questions
What was the size of the colorless polyimide films market in 2025?
What is the forecast value and CAGR of the colorless polyimide films market?
What is colorless polyimide film?
Did ultra-thin glass replace colorless polyimide in foldable phones?
Which region leads the colorless polyimide films market?
Which application of colorless polyimide film is largest?
Who are the main colorless polyimide film suppliers?
What challenges could slow the colorless polyimide films market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Foldable Cover Windows & Protective Layers
- 1.2.2 Display Substrates & Optical Layers
- 1.2.3 Flexible Printed Circuits
- 1.2.4 Touch Panels & Sensors
- 1.2.5 Flexible Solar Cells
- 1.2.6 AR Optics, Lighting & Others
- 1.3 By Type
- 1.3.1 Fluorinated CPI
- 1.3.2 Alicyclic CPI
- 1.3.3 Noncoplanar & Other CPI
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 197.1 million → 2035: USD 603.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Colorless Polyimide Films Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Colorless Polyimide Films Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Colorless Polyimide Films Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Colorless Polyimide Films Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Colorless Polyimide Films Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Colorless Polyimide Films Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Colorless Polyimide Films Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Colorless Polyimide Films Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 197.1 million → 2035: USD 603.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Colorless Polyimide Films Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Foldable Cover Windows & Protective Layers
- 12.3.7.2 Display Substrates & Optical Layers
- 12.3.7.3 Flexible Printed Circuits
- 12.3.7.4 Touch Panels & Sensors
- 12.3.7.5 Flexible Solar Cells
- 12.3.7.6 AR Optics, Lighting & Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fluorinated CPI
- 12.4.7.2 Alicyclic CPI
- 12.4.7.3 Noncoplanar & Other CPI
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Colorless Polyimide Films End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Colorless Polyimide Films Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Colorless Polyimide Films Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Colorless Polyimide Films Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sumitomo Chemical
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Kolon Industries
- 18.4 SK microworks
- 18.5 Mitsubishi Gas Chemical
- 18.6 Kaneka
- 18.7 Toray Industries
- 18.8 Qnity Electronics
- 18.9 PI Advanced Materials
- 18.10 NeXolve
- 18.11 Arkema
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

