
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Communications-Based Train Control Market Size 2024 | USD 8,050 million |
| Communications-Based Train Control Market, CAGR | 8.2% |
| Communications-Based Train Control Market Size 2032 | USD 15,122 million |
Market Overview:
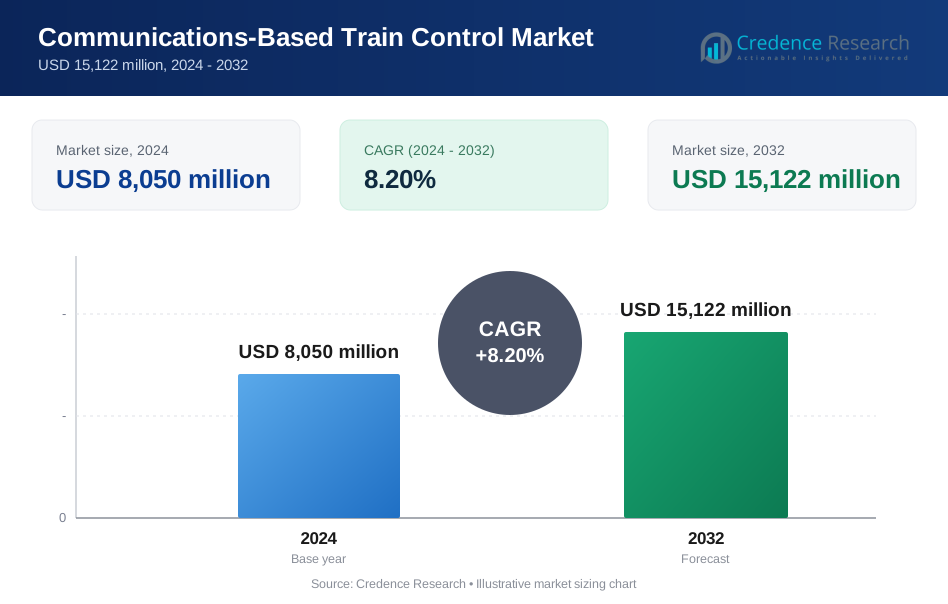
The Communications-Based Train Control (CBTC) market is projected to grow from USD 8,050 million in 2024 to USD 15,122 million by 2032, reflecting a compound annual growth rate (CAGR) of 8.2%.
The Communications-Based Train Control (CBTC) market is driven by the growing demand for efficient, safe, and reliable rail transportation systems. Increasing urbanization and the need for advanced rail infrastructure are prompting governments and transportation authorities to invest in CBTC solutions. The shift towards automation, coupled with the rise in smart cities, has further accelerated CBTC adoption, as these systems offer improved operational efficiency, reduced delays, and enhanced safety. Moreover, CBTC's ability to optimize train scheduling, increase network capacity, and enable real-time monitoring is driving its implementation across metro and light rail networks globally. Key trends include the integration of IoT and AI technologies, offering enhanced predictive maintenance and system performance. Additionally, the rising focus on environmental sustainability is pushing the adoption of energy-efficient and greener train control systems, making CBTC a vital component of modern, sustainable transportation infrastructure. These factors collectively contribute to the robust growth and innovation within the CBTC market.
The Communications-Based Train Control (CBTC) market exhibits significant regional variation, with Asia-Pacific holding the largest share due to rapid urbanization and investments in metro and high-speed rail networks, especially in China, Japan, and India. Europe follows closely, driven by robust railway infrastructure and the adoption of automated systems in cities like Paris and Berlin. North America is also a major player, with advanced metro systems in the U.S. and Canada, while the Middle East & Africa and Latin America show emerging potential due to ongoing infrastructure development. Key players such as Alstom, Thales Group, Siemens Mobility, Inc., and Mitsubishi Electric play pivotal roles in these regions, driving market growth through their technological innovations and strategic partnerships across global rail networks. These companies are well-positioned to leverage the growing demand for CBTC systems in urban and high-speed rail projects.
Market Insights:
- The Communications-Based Train Control (CBTC) market is projected to grow from USD 8,050 million in 2024 to USD 15,122 million by 2032, with a CAGR of 8.2%.
- Growing urbanization and the demand for efficient public transportation systems are key drivers for CBTC adoption.
- The shift toward automation in rail systems enhances operational efficiency, reduces human error, and increases safety, boosting CBTC implementation.
- CBTC systems are essential for improving safety and reliability by enabling real-time communication and fault detection, minimizing the risk of accidents and delays.
- Environmental sustainability is driving the adoption of energy-efficient CBTC solutions, contributing to reduced energy consumption and carbon emissions.
- The Asia-Pacific region leads the CBTC market with a 35% share in 2024, driven by rapid urbanization, smart city projects, and metro system expansions in China, Japan, and India.
- Europe and North America follow with shares of 30% and 25%, respectively, fueled by strong rail infrastructure, safety regulations, and smart city initiatives.
Market Drivers:
Growing Urbanization and Demand for Efficient Public Transport:
The increasing trend of urbanization is one of the primary drivers fueling the growth of the Communications-Based Train Control (CBTC) market. As cities continue to expand, the demand for efficient, reliable, and high-capacity public transportation systems becomes paramount. CBTC systems offer significant improvements in operational efficiency, safety, and overall performance, making them a vital solution for modern metro and rail networks. With the rising population in urban centers, transportation authorities are investing in advanced technologies like CBTC to handle growing passenger volumes and ensure smoother operations.
Shift Toward Automation in Rail Systems:
The global shift towards automation is a key market driver for CBTC solutions. Automation in transportation systems enhances efficiency by minimizing human errors, reducing operational costs, and improving safety. CBTC systems, which enable fully automated train operations, are gaining traction as they ensure better train control, real-time monitoring, and optimized scheduling. For instance, Alstom's Urbalis™ CBTC technology is integrated into 190 metro lines worldwide, including 67 driverless lines across 32 countries, safely transporting millions of passengers daily. As rail networks transition toward more automated and intelligent operations, CBTC technology plays a crucial role in providing seamless and scalable solutions that meet the demands of modern transportation infrastructure.
Focus on Safety and Reliability:
The emphasis on safety and reliability in transportation networks is another significant factor propelling the CBTC market. CBTC systems provide real-time communication between trains and control centers, allowing for better monitoring, fault detection, and the prevention of accidents. For instancce, Hitachi Rail's SelTrac™ CBTC, a digital signaling solution that utilizes train-to-ground telecommunications to support traffic management, is being deployed across new metros and for re-signaling existing networks. By offering more precise control over train operations, CBTC minimizes the risk of collisions, delays, and other operational failures, making it an attractive solution for railway operators and metro authorities worldwide. As safety regulations continue to tighten, the adoption of CBTC systems becomes essential to ensure compliance and maintain high operational standards.
Environmental Sustainability and Energy Efficiency:
With growing concerns over environmental sustainability, the CBTC market is also benefiting from the push toward energy-efficient transportation solutions. CBTC systems contribute to reducing energy consumption by optimizing train speed and minimizing unnecessary stops. Additionally, the integration of advanced technologies, such as predictive maintenance and smart scheduling, allows for more efficient use of resources and reduced carbon emissions. As governments and organizations prioritize sustainable practices, CBTC systems are becoming a critical component of green transportation strategies, further driving their adoption across global rail networks.
Market Trends:
Integration of IoT and AI Technologies:
A prominent trend in the Communications-Based Train Control (CBTC) market is the increasing integration of Internet of Things (IoT) and Artificial Intelligence (AI) technologies. These technologies enable real-time data collection, predictive maintenance, and enhanced decision-making capabilities. IoT devices embedded in trains and infrastructure facilitate continuous monitoring of system performance, while AI algorithms process vast amounts of data to optimize train operations and predict potential failures. This integration enhances the efficiency and reliability of CBTC systems, driving their adoption in metro and rail networks worldwide.
Smart Cities and Digitalization:
As cities become smarter and more digitally connected, the demand for advanced transportation systems like CBTC is rapidly increasing. The development of smart cities, which focus on enhancing the quality of life through digital technologies, has led to greater investments in modernized public transportation networks. For instance, the London Underground upgraded its Jubilee and Northern Lines to CBTC, leading to increased train frequency, reduced journey times, and enhanced service reliability for millions of commuters. CBTC systems are integral to these smart cities, providing the necessary automation, real-time monitoring, and operational efficiency. As digitalization continues to reshape urban environments, CBTC technology will be at the forefront of transforming urban mobility solutions.
Expansion of High-Speed Rail Networks:
The expansion of high-speed rail networks globally is another key trend contributing to the growth of the CBTC market. High-speed trains require advanced control systems that ensure optimal performance and safety at high speeds. CBTC technology offers the precision and reliability needed for such systems, allowing for better scheduling, increased capacity, and enhanced safety. As countries invest in high-speed rail infrastructure to improve connectivity, CBTC systems are becoming a critical component of these projects, further driving their adoption in both new and existing rail networks.
Focus on Environmental Impact Reduction:
There is a growing emphasis on reducing the environmental impact of transportation systems, and CBTC technology plays a significant role in achieving this goal. For instance, Alstom's driverless CBTC technology is set to significantly reduce travel time, traffic congestion, and CO2 emissions in Bengaluru, India. By optimizing train speeds and reducing energy consumption through efficient scheduling and real-time adjustments, CBTC systems help minimize the overall carbon footprint of rail networks. This focus on energy efficiency and sustainability aligns with global environmental goals, leading to increased interest in CBTC solutions as part of green transportation strategies.
Market Challenges Analysis:
High Initial Investment and Implementation Costs:
A significant challenge in the Communications-Based Train Control (CBTC) market is the high initial investment and implementation costs. The installation of CBTC systems necessitates substantial capital expenditure, including infrastructure upgrades, the purchase of specialized equipment, and software development. For rail operators, especially in developing regions or countries with limited budgets, this financial burden can be a major deterrent. The cost of retrofitting existing rail networks with CBTC technology adds further complexity, as it requires not only the installation of advanced communication and control systems but also the adaptation of older trains and infrastructure. For instance, Siemens Mobility in November 2023 signed a contract with the Metropolitan Transportation Authority (MTA) of New York to replace the Lexington Avenue Line with its Trainguard MT CBTC system. This extensive and expensive process can be challenging, particularly for operators who need to balance investment in technology with the maintenance and improvement of other parts of the transportation network. Although CBTC systems offer long-term benefits such as increased safety, efficiency, and capacity, the financial barriers involved in their adoption remain a significant challenge in expanding their global reach.
Technical Complexity and Integration Issues:
The technical complexity and integration issues associated with Communications-Based Train Control (CBTC) systems pose another major challenge in the market. CBTC technology demands a high level of coordination between trains, trackside equipment, and central control systems, which can be difficult to achieve, particularly in older or legacy rail networks. Many rail operators face the challenge of integrating new CBTC systems into infrastructure that may not have been designed to accommodate such advanced technology. Additionally, ensuring that these systems are compatible with different train models, signaling systems, and operational environments requires complex adjustments. The process of synchronizing data and managing communication between various components is also highly technical and requires specialized expertise. Moreover, once CBTC systems are deployed, ongoing maintenance, updates, and troubleshooting are crucial to ensure the technology functions as intended. These integration challenges can delay the widespread implementation of CBTC systems, as the effort to achieve seamless interoperability across diverse systems and networks requires both time and significant technical investment.
Market Opportunities:
The Communications-Based Train Control (CBTC) market presents several significant opportunities driven by the ongoing transformation of global transportation infrastructure. As urbanization continues to accelerate, cities are increasingly investing in smart, efficient, and sustainable public transportation systems. CBTC technology aligns perfectly with these goals, offering solutions that enhance operational efficiency, safety, and capacity. With the growing emphasis on automation and digitalization in transportation systems, CBTC offers a pathway to fully automated train operations, making it highly attractive to metro and light rail networks looking to improve service delivery and reduce operational costs. Additionally, the push for environmentally sustainable transportation systems creates opportunities for CBTC adoption, as these systems help optimize energy use, reduce emissions, and improve overall energy efficiency. As more governments prioritize green initiatives, CBTC technology will continue to play a vital role in meeting these sustainability goals.
The expansion of high-speed rail networks across regions presents another promising opportunity for CBTC systems. High-speed rail projects, particularly in Asia, Europe, and North America, require advanced signaling and control systems to ensure safe and efficient operations at higher speeds. CBTC’s ability to offer real-time communication between trains and control centers makes it ideal for such high-speed applications, enabling better scheduling, reduced delays, and enhanced safety. Furthermore, as railway operators look to modernize and upgrade legacy rail networks, the demand for CBTC systems is expected to rise. The ongoing trend toward digitalization, predictive maintenance, and real-time monitoring within transportation systems opens up new avenues for CBTC market growth, as these solutions help optimize operations, reduce costs, and improve service quality across both existing
Market Segmentation Analysis:
By Train Type
The Communications-Based Train Control (CBTC) market is segmented by train type into metros and high-speed trains. Metros dominate the market, as they require efficient control systems to handle high passenger volumes and ensure operational safety in urban environments. High-speed trains are increasingly adopting CBTC to maintain optimal speed and safety at elevated velocities, driving growth in this segment.
By Type
The market is also segmented by CBTC type into Basic CBTC and Integrated CBTC (I-CBTC). Basic CBTC offers essential train control functions, making it suitable for smaller networks and retrofitting older systems. Integrated CBTC (I-CBTC) provides advanced capabilities like real-time monitoring and predictive maintenance, making it ideal for modern, high-capacity rail networks requiring enhanced efficiency and safety.
By Automation Grade
The CBTC market is further divided by automation grade, including GoA1, GoA2, GoA3, and GoA4. GoA1 represents manual train operations, while GoA2 to GoA4 offer increasing levels of automation, with GoA4 representing fully automated operations. Higher automation grades are increasingly favored for their efficiency, safety, and ability to minimize human error, leading to greater market adoption.
Segments:
Based on Train Type
- Metros
- High-speed Trains
Based on Type
- Basic CBTC
- I-CBTC
Based on Automation Grade
- GoA1
- GoA2
- GoA3
- GoA4
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the Communications-Based Train Control (CBTC) market, with a projected market share of 25% in 2024. The region’s growth is driven by extensive investments in modernizing rail infrastructure and enhancing public transport systems, particularly in the United States and Canada. The expansion of urban metro systems and the continuous development of high-speed rail networks are major contributors to the region's demand for CBTC technology. The focus on automation, safety, and energy efficiency in North American transportation systems further fuels the adoption of CBTC systems. Additionally, government initiatives supporting smart city development and sustainable transportation systems align with the increasing deployment of CBTC solutions, bolstering the region's market share.
Europe
Europe is expected to maintain a strong presence in the CBTC market, capturing a 30% market share in 2024. The region’s robust railway network, coupled with the increasing emphasis on safety and automation, drives the demand for advanced signaling and control systems like CBTC. Countries such as the United Kingdom, Germany, and France are at the forefront of adopting CBTC solutions in both metro systems and high-speed rail projects. The European Union’s regulations and funding programs for sustainable transport infrastructure also encourage the integration of CBTC technology to improve operational efficiency and reduce environmental impact. Moreover, the growing trend toward fully automated metro systems in cities like Paris and Berlin further supports market growth in the region.
Asia-Pacific
Asia-Pacific is expected to be the dominant region in the CBTC market, holding a market share of 35% in 2024. The region’s rapid urbanization, coupled with large-scale investments in smart city projects, drives the demand for CBTC systems. Countries like China, Japan, and India are major contributors to the region’s market growth. China’s ongoing development of high-speed rail networks and India’s metro expansion projects are significant factors driving CBTC adoption. Additionally, the region’s push for automation in metro systems, coupled with a growing focus on sustainability and safety, further accelerates the demand for CBTC technology. The increasing number of metro projects and high-speed rail initiatives across Asia-Pacific ensures the region remains a dominant player in the CBTC market.
Middle East & Africa
The Middle East & Africa region is projected to capture a market share of 5% in 2024. While still emerging, the region shows significant potential due to the ongoing development of transportation infrastructure in cities like Dubai, Abu Dhabi, and Riyadh. Investment in smart city technologies and the expansion of metro and light rail networks create opportunities for CBTC adoption. The region’s growing focus on enhancing transportation efficiency and safety, especially in light of hosting major international events like the World Expo, has prompted increased interest in advanced signaling systems like CBTC. Despite its smaller share, the region’s market is expected to grow steadily over the coming years.
Latin America
Latin America is expected to hold a 5% share of the CBTC market in 2024. The region is gradually adopting advanced rail technologies, particularly in metro systems and urban transport infrastructure. Countries like Brazil, Mexico, and Argentina are increasingly focusing on upgrading existing rail networks and implementing new projects to improve safety and operational efficiency. As Latin American cities grow and develop, the demand for automation and real-time control systems like CBTC is expected to rise, contributing to gradual market expansion.
Key Player Analysis:
- Mitsubishi Electric (Japan)
- Siemens Mobility, Inc (Germany)
- Thales Group (France)
- Toshiba (Japan)
- ABB (Sweden)
- Hitachi (Japan)
- Alstom (France)
- Wabtec Corporation (U.S.)
- Argenia Railway Technologies Inc. (Canada)
- WAGO Corporation (U.S.)
Competitive Analysis:
The Communications-Based Train Control (CBTC) market is highly competitive, with key players such as Alstom, Thales Group, Wabtec Corporation, Mitsubishi Electric, Hitachi, Siemens Mobility, Inc., ABB, Argenia Railway Technologies Inc., Toshiba, and WAGO Corporation leading the charge. These companies are focused on developing innovative and efficient CBTC solutions, with advancements in automation, safety, and real-time monitoring driving their product offerings. Alstom and Siemens Mobility, Inc. are particularly prominent due to their extensive global presence and involvement in high-speed rail and metro projects. Thales Group and Wabtec Corporation are strong contenders in integrating cutting-edge technologies like AI and IoT into CBTC systems, enhancing predictive maintenance and operational efficiency. Mitsubishi Electric and Hitachi are key players in the Asian market, leveraging their expertise in automation and control systems. ABB, Toshiba, and WAGO Corporation focus on providing high-quality hardware and systems integration for CBTC solutions, ensuring seamless communication across train networks. The competition in this market is expected to intensify as these companies continue to push for technological advancements.
Recent Developments:
- In March 2023, the Metropolitan Transportation Authority (MTA) of New York awarded a contract to the Crosstown Partners consortium, comprising Thales and TC Electric (TCE), for the provision of CBTC signaling and related systems.
- In September 2023, Bharat Electronics Limited (BEL) teamed up with the Delhi Metro Corporation to develop an indigenous CBTC system, aiming to enhance rail transportation in India while reducing costs and promoting self-reliance in train control signaling technologies.
- In November 2023, Alstom announced the deployment of the next-generation CBTC signaling system on the Paris network, securing a contract worth approximately USD 327 million to develop and implement the NExTEO signaling system for France's rapid transit and hybrid rail services.
- In July 2023, Toshiba Electronic Devices & Storage Corporation launched the TRSxxx65H series, marking the third generation of its silicon carbide Schottky barrier diodes designed for industrial equipment.
- Also, in July 2023, Siemens Mobility, Inc., in partnership with ubitricity, collaborated with Redbridge Council to enhance the borough’s electric vehicle (EV) network by adding over 300 new on-street charge points.
- In June 2023, Mitsubishi Electric revealed plans to invest an additional 42.5 billion yen to build a second production facility for factory automation (FA) control-system products at its Nagoya Works campus in Owariasahi City, Aichi Prefecture.
Market Concentration & Characteristics:
The Communications-Based Train Control (CBTC) market exhibits a moderate to high level of concentration, with key players such as Alstom, Thales Group, Siemens Mobility, and Mitsubishi Electric leading the sector. These companies hold significant market shares due to their advanced technological capabilities, global presence, and ongoing investments in R&D. Market concentration is further driven by strategic collaborations, partnerships, and acquisitions, which enable these players to expand their product offerings and enhance their competitive edge in diverse regional markets. The CBTC market is characterized by high barriers to entry, primarily due to the technical complexity and substantial capital investment required to implement these systems. Additionally, demand for real-time communication, safety, and automation in rail networks continues to rise, which influences the development of more sophisticated solutions. The market is also marked by the integration of emerging technologies such as AI, IoT, and predictive maintenance, which further enhance CBTC system efficiency and functionality.
Report Coverage:
The research report offers an in-depth analysis based on Train Type, Type, Automation Grade and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for CBTC systems will continue to rise as urbanization accelerates, necessitating more efficient and reliable rail transportation.
- Automation will play a significant role in future CBTC implementations, enabling fully automated train operations across metro and high-speed rail networks.
- The integration of AI and IoT technologies will enhance CBTC systems, enabling predictive maintenance and real-time monitoring for better operational efficiency.
- Governments worldwide will increase investments in smart city projects, promoting the adoption of CBTC solutions in urban transport systems.
- Environmental sustainability initiatives will drive the demand for energy-efficient CBTC systems to reduce carbon emissions and energy consumption in rail networks.
- CBTC technology will evolve to support more advanced safety features, improving accident prevention and ensuring higher reliability in train operations.
- The market will see more collaborations and partnerships between CBTC technology providers and transportation authorities to implement customized solutions.
- Increased focus on data analytics and system optimization will help enhance train scheduling, capacity management, and real-time decision-making.
- Legacy rail networks will undergo retrofitting with CBTC systems to modernize infrastructure and improve operational efficiency.
- The market will expand in emerging regions, including Latin America, the Middle East, and Africa, as they continue to develop metro and rail infrastructure.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Urbanization and Demand for Efficient Public Transport
Rapid urbanization is increasing the need for high-capacity, reliable, and efficient public transportation systems. CBTC solutions are being adopted to handle rising passenger volumes and to improve operational efficiency and safety in expanding urban rail networks.
Shift Toward Automation in Rail Systems
The global move toward automation in transportation is driving CBTC adoption, as these systems enable fully or partially automated train operations. Automation reduces human error, enhances safety, and optimizes train scheduling, making CBTC essential for modern metro and high-speed rail projects.
Focus on Safety and Reliability
CBTC systems provide real-time communication and advanced fault detection, significantly reducing the risk of accidents and delays. As safety regulations tighten and reliability becomes paramount, rail operators are increasingly investing in CBTC to ensure compliance and high operational standards.
Environmental Sustainability and Energy Efficiency
With growing emphasis on sustainability, CBTC systems are being implemented to optimize train speeds, reduce unnecessary stops, and lower energy consumption. These benefits help rail operators meet environmental goals by minimizing carbon emissions and supporting green transportation initiatives.
Integration of IoT and AI Technologies
The adoption of IoT and AI within CBTC systems enables predictive maintenance, real-time monitoring, and data-driven decision-making. These technological advancements improve system performance, reduce downtime, and further drive the market’s growth by enhancing operational efficiency.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Communications-Based Train Control (CBTC) Market?
What factors are driving the growth of the Communications-Based Train Control (CBTC) Market?
What are some challenges faced by the Communications-Based Train Control (CBTC) Market?
Who are the major players in the Communications-Based Train Control (CBTC) Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Basic CBTC
- 1.2.2 I-CBTC
- 1.3 By Train Type
- 1.3.1 Metros
- 1.3.2 High-speed Trains
- 1.4 By Automation Grade
- 1.4.1 GoA1
- 1.4.2 GoA2
- 1.4.3 GoA3
- 1.4.4 GoA4
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8,050 million → 2032: USD 15,122 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Communications-Based Train Control Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Communications-Based Train Control Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Communications-Based Train Control Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Communications-Based Train Control Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Communications-Based Train Control Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Communications-Based Train Control Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Communications-Based Train Control Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Communications-Based Train Control Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8,050 million → 2032: USD 15,122 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Communications-Based Train Control Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Basic CBTC
- 12.3.7.2 I-CBTC
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Train Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Metros
- 12.4.7.2 High-speed Trains
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Automation Grade - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 GoA1
- 12.5.7.2 GoA2
- 12.5.7.3 GoA3
- 12.5.7.4 GoA4
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Communications-Based Train Control Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Communications-Based Train Control Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Communications-Based Train Control Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Alstom
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Siemens Mobility, Inc.
- 17.4 Thales Group
- 17.5 Mitsubishi Electric
- 17.6 Hitachi
- 17.7 ABB
- 17.8 Toshiba
- 17.9 Wabtec Corporation
- 17.10 Argenia Railway Technologies Inc.
- 17.11 WAGO Corporation
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

