
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Content Curation Software Market Size 2024 | USD 671 million |
| Content Curation Software Market, CAGR | 12.6% |
| Content Curation Software Market Size 2032 | USD 1,733.92 million |
Market Overview:
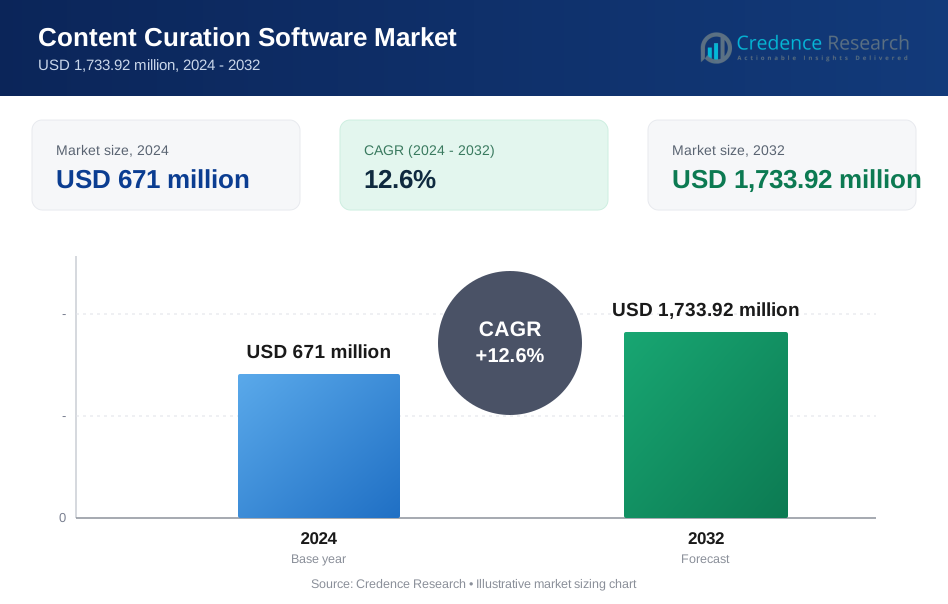
The Content Curation Software Market size was valued at USD 671 million in 2024 and is anticipated to reach USD 1,733.92 million by 2032, at a CAGR of 12.6% during the forecast period (2024-2032).
Several factors are driving the adoption of content curation software, as businesses seek efficient ways to aggregate, organize, and distribute content across multiple platforms. The increasing focus on digital marketing, content automation, and thought leadership strategies has created a strong demand for AI-powered content curation tools that enhance audience engagement and brand visibility. Companies are integrating machine learning and natural language processing algorithms to filter, categorize, and repurpose content from diverse sources, ensuring a steady stream of high-quality information across websites, social media, and email newsletters. The growing reliance on data-driven insights and predictive analytics is further accelerating adoption, as businesses aim to optimize content engagement, enhance personalization, and improve customer retention rates. Additionally, the shift toward interactive and highly targeted content experiences is increasing demand for automated curation platforms that provide customized recommendations and real-time content discovery. However, intellectual property concerns, risks of content duplication, and regulatory challenges pose obstacles, requiring businesses to ensure compliance with copyright laws and maintain content authenticity while leveraging automation.
Regionally, North America holds the largest market share, driven by high digital adoption rates, significant investments in AI-driven content solutions, and an increasing demand for marketing automation technologies. The United States dominates this region, with large enterprises, media firms, and digital marketing agencies utilizing content curation platforms to enhance engagement and audience retention strategies. Europe follows closely, with businesses in Germany, France, and the UK focusing on AI-powered content recommendation engines to support personalized marketing initiatives and industry-specific knowledge sharing. The Asia-Pacific region is experiencing the fastest growth, fueled by rapid digital transformation, expanding e-commerce ecosystems, and rising investments in content-driven branding strategies in China, India, and Japan. Emerging markets in Latin America and the Middle East & Africa are gradually adopting automated content curation, as businesses recognize its benefits for digital marketing, knowledge management, and brand positioning in high-growth industries such as retail, education, and financial services.
Market Insights:
- The content curation software market is projected to grow from USD 671 million in 2024 to USD 1,733.92 million by 2032, driven by increasing demand for automated content discovery, AI-powered recommendations, and personalized marketing strategies.
- Businesses are integrating machine learning and natural language processing to filter, categorize, and repurpose content, ensuring consistent audience engagement.
- Organizations are leveraging predictive analytics and audience segmentation tools to optimize content distribution, improve retention rates, and enhance brand storytelling.
- Copyright concerns, content duplication risks, and evolving regulatory standards pose challenges, requiring compliance-focused content curation solutions.
- The United States dominates the market, with high adoption of AI-powered content platforms across media, e-commerce, and corporate marketing sectors.
- Rising digital transformation, expanding e-commerce, and increasing investments in content-driven branding strategies are driving demand in China, India, and Japan.
- Latin America and the Middle East & Africa are witnessing gradual adoption, with businesses using automated content curation for digital marketing and industry-specific knowledge management.
Market Drivers:
Increasing Demand for AI-Driven Content Personalization:
The adoption of artificial intelligence and machine learning algorithms in content curation is transforming how businesses engage with audiences. For instance, according to recent data, 84% of marketers use AI to adapt their web content to user search intent, while 80% leverage AI for content optimization. Companies implementing AI-driven personalization have seen up to 86% increase in customer retention rates, with predictive analytics enabling up to 20% boost in B2B user engagement through tailored experiences.
Rising Adoption of Digital Marketing and Thought Leadership Strategies:
The increasing focus on digital marketing and brand positioning is driving demand for content curation software. For instance, US-based searches in Google are now "zero-click" searches, making it crucial for brands to optimize their content for featured snippets and AI overviews. Enterprise marketers are responding to this trend, with 39% increasing their marketing budgets in 2025 compared to 2024, focusing on thought leadership content that delivers unique insights and answers to customer questions.
Growing Need for Data-Driven Content Optimization:
Businesses are increasingly relying on data-driven content strategies to maximize audience engagement. For instance, personalized call-to-actions perform better than non-personalized ones, demonstrating the impact of data-driven optimization. Advanced AI tools now handle large datasets and aggregate multiple sources, enabling companies to develop targeted content strategies, as demonstrated by Universal Technical Institute's success in creating over 200 localized, SEO-optimized web pages through AI-powered data analysis.
Expansion of E-commerce and Digital Transformation:
The rapid expansion of e-commerce and digital transformation is creating new opportunities for content curation software adoption. For instance, around 2.77 billion people are expected to shop online in 2025, driving the need for unique, customized digital experiences. Companies effectively implementing digital transformation have seen revenue increases of up to 20% and improved customer satisfaction rates by 30%, with 92% of executives believing their organization must transform to remain competitive.
Market Trends:
AI-Powered Content Recommendation and Personalization:
The increasing integration of artificial intelligence and machine learning algorithms is transforming content curation software. For instance, AI-powered recommendation systems now process over 100 data points per influencer profile, achieving accuracy in predicting campaign success rates. Companies implementing data-driven personalization have seen up to 86% increase in customer retention rates, while predictive analytics enable up to 20% boost in B2B user engagement through tailored experiences.
Integration of Voice and Visual Search in Content Curation:
The rise of voice search and visual content discovery is reshaping content curation strategies. For instance, by 2025, voice search is expected to dominate search queries, with users preferring the convenience of spoken commands over traditional text-based searches. Over 8.4 billion voice assistants are predicted to be in use by the end of 2024, demonstrating the significant impact on content discovery and optimization. This shift requires businesses to adapt their content strategies for voice-based interactions and visual search capabilities.
Growth of Curated Content in E-Commerce and Social Commerce:
The e-commerce industry increasingly relies on curated content to enhance user experiences. For instance, about 86% of people made an online purchase within the last month, with 82% using social media for product discovery and research. Social commerce generated $700 billion globally in 2024, up 23% from $571 billion in 2023, with social buyers spending an average of $750.40 on social commerce in 2024. These trends demonstrate the growing importance of curated content in driving e-commerce success.
Regulatory Compliance and Ethical Content Curation:
With increasing concerns over data privacy and ethical content distribution, businesses are focusing on responsible content curation practices. For instance, by 2025, businesses that fail to comply with evolving AI regulations may face penalties of up to $7,500 per violation. According to recent surveys, 55% of respondents don't trust AI much or at all to make unbiased decisions, while 62% don't trust it to make ethical decisions. This has led to the implementation of rigorous content review processes and multi-stakeholder approaches to ensure responsible content curation.
Market Challenges Analysis:
Data Privacy Regulations and Compliance Requirements:
The increasing stringency of data privacy laws and compliance regulations poses a significant challenge to the content curation software market. Governments worldwide are enforcing strict data protection policies, affecting how companies collect, store, and distribute content. The European Union’s General Data Protection Regulation (GDPR) requires businesses to ensure data security, transparency, and user consent when curating and personalizing content. For instance, Meta was fined USD 1.3 billion in 2023 for violating GDPR’s cross-border data transfer regulations, demonstrating the financial risks associated with non-compliance. Similarly, the California Consumer Privacy Act (CCPA) mandates that companies allow users to opt out of data collection, adding complexity to AI-driven content recommendation systems. These legal frameworks force content curation software providers to continuously update security protocols and ensure compliance, increasing operational costs and limiting data accessibility.
Intellectual Property and Content Ownership Concerns:
The unauthorized use of copyrighted content remains a major restraint in the content curation industry, as businesses navigate intellectual property (IP) laws to avoid legal disputes. Automated content aggregation often involves repurposing articles, images, and videos, raising concerns over content ownership, licensing, and fair use policies. The U.S. Copyright Office has reinforced digital content protection measures, making it mandatory for businesses to obtain proper licensing for curated content. For instance, YouTube’s Content ID system detected over 800 million copyright claims in 2023, reflecting the growing challenge of managing curated digital assets. Companies using AI-driven curation tools must implement robust attribution and licensing mechanisms to ensure compliance with copyright laws, preventing potential legal conflicts.
Content Authenticity and the Rise of Misinformation:
The increasing spread of misinformation and unverified content challenges the credibility of AI-driven content curation platforms. As AI-powered systems aggregate content from various online sources, businesses must ensure fact-checking, source verification, and ethical content distribution. The U.S. Federal Trade Commission (FTC) has issued strict guidelines against false advertising and misleading content, requiring companies to implement stronger content verification protocols. For instance, Google removed over 5.2 billion misleading ads in 2023, reflecting the growing demand for automated content moderation tools. To maintain content authenticity and compliance, organizations are investing in AI-powered misinformation detection and trust-scoring algorithms, increasing the complexity and cost of content curation software development.
Market Opportunities:
The content curation software market presents significant opportunities as businesses increasingly prioritize AI-driven content strategies, personalized marketing, and data-driven decision-making. The growing adoption of machine learning and automation in content management allows organizations to efficiently filter, aggregate, and distribute high-quality content across multiple digital platforms. As brands shift towards hyper-personalized user experiences, demand for intelligent content curation solutions is rising, particularly in media, e-commerce, education, and corporate sectors. For instance, AI-powered recommendation engines used by companies like Netflix and Amazon contribute significantly to audience retention and engagement, demonstrating the potential of curated content in enhancing digital experiences. Additionally, the integration of voice and visual search technologies into content platforms offers new opportunities for AI-driven curation tools to optimize searchability and relevance.
The expansion of social commerce, e-learning, and digital knowledge management further accelerates market opportunities for content curation software providers. As businesses adopt content-driven lead generation and thought leadership strategies, the need for scalable curation platforms that automate content discovery, optimize audience engagement, and improve brand positioning is increasing. The Asia-Pacific region, Latin America, and the Middle East & Africa are witnessing rapid digital transformation, rising internet penetration, and growing investments in content-driven marketing, creating new market expansion opportunities. Additionally, regulatory advancements encouraging transparent and ethical content curation practices are pushing software providers to develop compliance-driven curation solutions, reinforcing trust and credibility in digital content strategies. As organizations continue to invest in automated, AI-powered content curation tools, the market is poised for significant growth across industries and global regions.
Market Segmentation Analysis:
By Type
The content curation software market is segmented by type into cloud-based and on-premises solutions. Cloud-based content curation platforms dominate the market, as businesses prioritize scalability, remote accessibility, and seamless integration with existing digital marketing tools. These solutions allow organizations to automate content discovery, personalize recommendations, and manage large-scale content distribution with minimal infrastructure investment. For instance, major enterprises and media houses leverage AI-powered cloud platforms to enhance real-time content aggregation and delivery across multiple channels. On-premises solutions, while preferred by organizations with stringent data security and compliance requirements, are seeing slower adoption due to higher costs and limited flexibility compared to cloud-based alternatives. However, regulated industries such as finance and healthcare continue to invest in customized, on-premises content curation systems to maintain data sovereignty and compliance with strict privacy laws.
By Application
Based on application, the market is categorized into media & entertainment, e-commerce, education, corporate marketing, and knowledge management. The media & entertainment sector holds the largest share, as companies adopt AI-driven content curation tools to enhance personalized recommendations, audience engagement, and content monetization strategies. E-commerce platforms increasingly integrate content curation software to drive product discovery, social commerce engagement, and targeted promotions. In the education sector, universities and online learning platforms are utilizing automated content aggregation tools to create personalized learning experiences and curated knowledge repositories. Corporate marketing teams use content curation software for thought leadership, lead generation, and brand positioning, while knowledge management solutions help organizations streamline internal content organization and employee learning resources, driving widespread adoption across industries.
Segmentations:
By Type:
- Cloud-Based
- On-Premises
By Application:
- Government
- Retail and e-commerce
- Healthcare and Life Sciences
- BFSI
- Transportation and Logistics
- Telecom and IT
- Manufacturing
- Others
By Region:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America holds the largest market share of 39.2%, driven by high adoption rates of AI-driven content solutions, advanced digital infrastructure, and significant investments in marketing automation technologies. The United States dominates the region, with major enterprises, media firms, and e-commerce companies leveraging AI-powered content curation platforms to optimize engagement and enhance personalized content strategies. For instance, Netflix’s recommendation engine, powered by AI-based content curation, contributes to over 80% of the platform’s watched content, showcasing the impact of curated digital experiences on audience retention. Additionally, corporate marketing teams and publishing firms in the region are actively integrating machine learning-based content aggregation tools, allowing for automated content filtering and targeted distribution. The presence of leading software providers and tech-driven enterprises in the U.S. and Canada further accelerates the growth of cloud-based content curation solutions.
Europe:
Europe accounts for 28.5% of the global market share, fueled by a growing focus on data privacy, content compliance regulations, and AI-powered content recommendation systems. The European Union’s General Data Protection Regulation (GDPR) mandates strict data usage policies, compelling organizations to invest in secure, AI-driven content curation solutions. For instance, the BBC and major European media outlets leverage AI-powered curation tools to ensure personalized content recommendations while complying with data protection laws. Additionally, countries like Germany, France, and the UK are leading the adoption of automated content curation platforms, particularly in corporate marketing and digital knowledge management. over 75% of European businesses actively use AI-based content recommendation systems, reinforcing the importance of curated content in brand engagement strategies.
Asia-Pacific:
Asia-Pacific holds 23.1% of the market share and is witnessing the fastest growth, driven by expanding digital transformation initiatives, increasing investments in AI-powered marketing, and the rapid adoption of content-driven e-commerce. China, India, and Japan are leading the region, with businesses leveraging content curation software to enhance social commerce, e-learning, and digital brand storytelling. For instance, Alibaba’s AI-driven content curation tools optimize product recommendations, contributing to higher consumer engagement and increased sales conversions in China’s booming e-commerce market. In India, the rise of edtech platforms like BYJU’S and Unacademy has accelerated demand for AI-powered content aggregation tools, enabling personalized learning experiences. Japan’s advanced AI ecosystem is further driving automated content curation for knowledge management and corporate marketing, making the region a key contributor to global market expansion.
Latin America and Middle East & Africa:
Latin America and the Middle East & Africa collectively contribute 9.2% of the global market share, experiencing gradual adoption of content curation software as businesses recognize its value in digital marketing, corporate learning, and knowledge management. For instance, Brazil’s digital marketing sector grew by 22% in 2023, according to the Brazilian Internet Association, driving demand for automated content aggregation platforms. In Mexico, rising internet penetration and the expansion of e-commerce platforms have increased the need for AI-driven content personalization to enhance customer engagement strategies. The Middle East & Africa are witnessing growth in digital learning initiatives, with government-backed investments in AI-driven knowledge-sharing platforms.
Key Player Analysis:
- Curata
- Scoop.it
- Feedly
- Anders Pink
- ContentStudio
- Trapit
- Curation Suite
- Listly
- Paper.li
Competitive Analysis:
The content curation software market is highly competitive, with key players focusing on AI-driven automation, machine learning-based content recommendations, and advanced analytics to gain market share. Leading companies such as Curata, Scoop.it, Feedly, UpContent, and ShareIt dominate the industry by offering cloud-based content aggregation, personalized recommendations, and automated distribution solutions. For instance, Curata’s AI-powered content curation platform has reported a 40% increase in adoption among corporate marketing teams, demonstrating the rising demand for intelligent content discovery tools. Companies are investing in natural language processing (NLP) and predictive analytics to enhance content personalization and audience targeting capabilities. Feedly’s AI-driven Leo engine processes over 200 million articles daily, enabling businesses to filter relevant content and improve engagement strategies. As digital transformation accelerates, competition is intensifying, with software providers expanding integrations with CRM, social media, and marketing automation platforms to enhance user experience and content performance.
Recent Developments:
- In February 2024, Curata launched an advanced AI-driven content curation platform designed to help businesses streamline their content marketing strategies. The platform incorporates sophisticated algorithms for analyzing and curating relevant content, significantly enhancing user engagement and marketing efficiency.
- In September 2023, Feedly introduced over 100 new Technology Models for diverse industries, incorporating natural language processing capabilities. The platform's AI system was upgraded to understand market concepts, context, nuances, and deeper meanings, enabling more efficient research processes for teams.
- In January 2025, Anders Pink released a new version of Complete Curation featuring generative AI capabilities. The update includes automatic generation of sub-skills lists and pre-built learning pathways, significantly reducing human intervention in the curation process.
Market Concentration & Characteristics:
The content curation software market is moderately concentrated, with a mix of established technology firms and emerging SaaS providers competing to offer AI-powered content discovery, automation, and personalization solutions. Leading companies such as Curata, Scoop.it, Feedly, and UpContent hold a significant market share due to their advanced content recommendation engines, seamless integrations, and AI-driven analytics capabilities. The market is characterized by a strong focus on automation, machine learning, and predictive content distribution, allowing businesses to enhance audience engagement and optimize marketing strategies. The growing emphasis on regulatory compliance, data privacy, and intellectual property protection is influencing market dynamics, prompting companies to invest in secure, transparent content aggregation solutions. Additionally, the rising demand for hyper-personalized content experiences across e-commerce, media, education, and corporate marketing is driving continuous innovation in AI-based content curation platforms, shaping the future of digital content management.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI-driven content curation will become more advanced, leveraging deep learning algorithms to improve content discovery, personalization.
- Predictive analytics and real-time audience insights will enhance content performance tracking, allowing businesses to optimize content distribution strategies based on data-driven decisions.
- The integration of voice search and visual content discovery will reshape content curation, enabling platforms to deliver relevant recommendations through AI-powered voice assistants and image recognition technologies.
- Social commerce and e-commerce platforms will increasingly use curated content to enhance customer engagement, driving higher conversion rates through personalized product recommendations.
- Blockchain technology will play a role in content verification and intellectual property protection, ensuring transparency and authenticity in curated digital assets.
- Data privacy regulations such as GDPR and CCPA will drive the adoption of compliance-focused content curation solutions, ensuring ethical content aggregation and distribution practices.
- The demand for multilingual and region-specific content curation will grow, prompting companies to develop AI-powered language processing tools for global content distribution.
- Media, education, and corporate sectors will continue investing in content curation software to streamline knowledge management, internal communication, and personalized learning experiences.
- Seamless integration with CRM, social media, and marketing automation tools will enhance content distribution efficiency, making AI-powered curation a core component of digital marketing strategies.
- Emerging markets in Asia-Pacific, Latin America, and the Middle East & Africa will experience rapid adoption of content curation technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
AI-Driven Content Personalization
The integration of artificial intelligence and machine learning enables businesses to deliver highly personalized content experiences, increasing audience engagement and retention. AI-powered recommendation engines and predictive analytics allow for tailored content delivery, driving adoption of advanced curation platforms.
Expansion of Digital Marketing and Thought Leadership
As brands compete for visibility in increasingly crowded digital spaces, content curation software helps organizations aggregate, organize, and distribute thought leadership and marketing content efficiently. The shift toward zero-click searches and featured snippets further incentivizes investment in curation tools to optimize digital presence.
Growth of E-commerce and Social Commerce
The rapid expansion of e-commerce and social commerce platforms requires businesses to provide curated, relevant content to enhance product discovery and customer engagement. Content curation software supports these needs by automating the aggregation and distribution of product information, reviews, and recommendations.
Data-Driven Content Optimization
Businesses are leveraging data analytics and segmentation tools within curation platforms to optimize content strategies, improve targeting, and maximize ROI. The ability to analyze large datasets and automate content selection based on performance metrics is a key driver for market growth.
Regulatory Compliance and Content Authenticity
Increasing regulatory scrutiny around data privacy and intellectual property is pushing organizations to adopt curation solutions that ensure compliance and content authenticity. Platforms with robust compliance features help businesses avoid legal risks and maintain trust with their audiences.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Content Curation Software Market?
What factors are driving the growth of the Content Curation Software Market?
Who are the major players in the Content Curation Software Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Cloud-Based
- 1.2.2 On-Premises
- 1.3 By Application
- 1.3.1 Media & Entertainment
- 1.3.2 Retail and E-commerce
- 1.3.3 Healthcare and Life Sciences
- 1.3.4 BFSI
- 1.3.5 Education
- 1.3.6 Corporate Marketing
- 1.3.7 Knowledge Management
- 1.3.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 671 million → 2032: USD 1,733.92 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Content Curation Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Content Curation Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Content Curation Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Content Curation Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Content Curation Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Content Curation Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Content Curation Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Content Curation Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 671 million → 2032: USD 1,733.92 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Content Curation Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Cloud-Based
- 12.3.6.2 On-Premises
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Media & Entertainment
- 12.4.6.2 Retail and E-commerce
- 12.4.6.3 Healthcare and Life Sciences
- 12.4.6.4 BFSI
- 12.4.6.5 Education
- 12.4.6.6 Corporate Marketing
- 12.4.6.7 Knowledge Management
- 12.4.6.8 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Content Curation Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Content Curation Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Content Curation Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Content Curation Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Curata
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Scoop.it
- 18.4 Feedly
- 18.5 Anders Pink
- 18.6 ContentStudio
- 18.7 Trapit
- 18.8 Curation Suite
- 18.9 Listly
- 18.10 Pocket
- 18.11 Paper.li
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

