
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Low-Fat Content Kefir Market Size 2024 | USD 1,303.29 Million |
| Low-Fat Content Kefir Market, CAGR | 9.20% |
| Low-Fat Content Kefir Market Size 2032 | USD 2,767.85 Million |
Market Overview
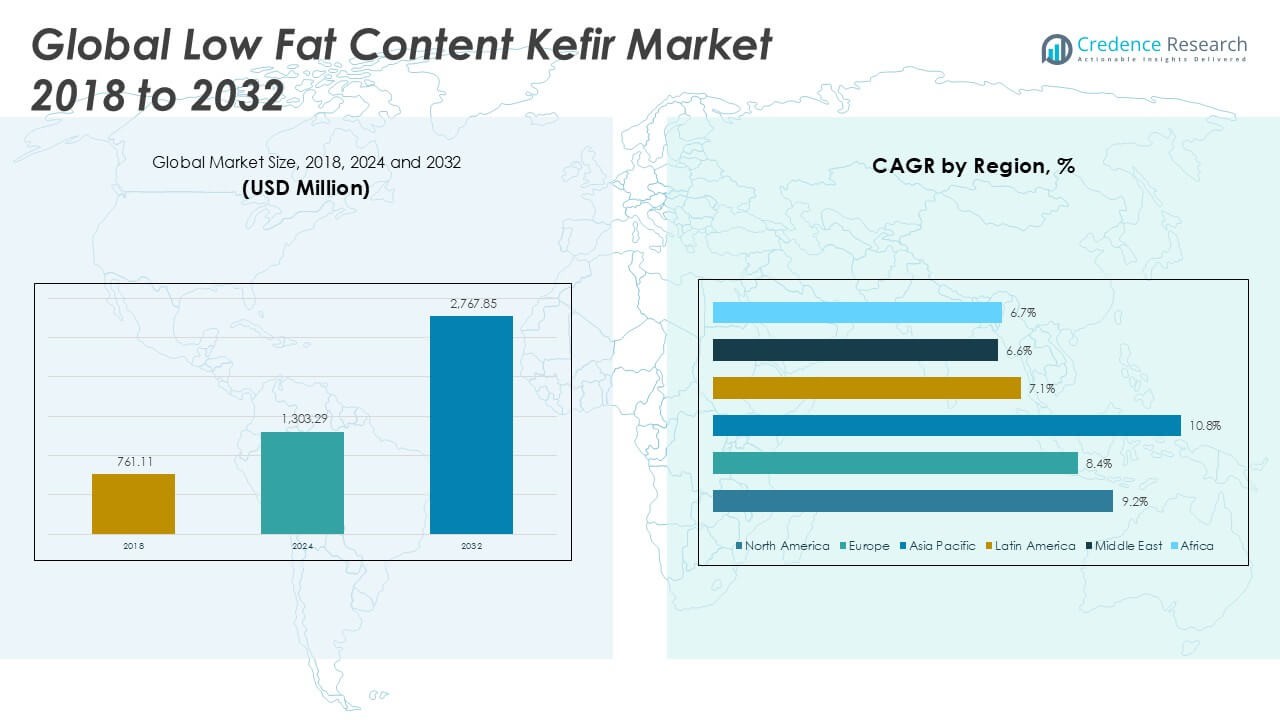
The Low-Fat Content Kefir Market size was valued at USD 761.11 million in 2018, reached USD 1,303.29 million in 2024, and is anticipated to reach USD 2,767.85 million by 2032, at a CAGR of 9.20% during the forecast period.
The Low-Fat Content Kefir Market is experiencing strong growth, driven by increasing consumer preference for healthier dairy alternatives and a rising focus on low-calorie, probiotic-rich products. Heightened awareness of digestive health benefits, coupled with the popularity of functional foods, is expanding kefir’s appeal among health-conscious populations. Manufacturers are responding to these trends by innovating with new flavors and clean-label formulations, attracting a broader customer base. Growth in urbanization, changing dietary habits, and greater availability through modern retail channels also support market expansion. However, the market faces challenges from limited consumer awareness in developing regions and competition from other fermented beverages. Despite these restraints, ongoing product development and targeted marketing strategies are expected to drive further adoption. The trend toward natural, gut-friendly foods positions low fat kefir as a staple in modern diets, reinforcing its steady market momentum worldwide.
The Low-Fat Content Kefir Market demonstrates robust growth across key regions, with North America and Europe leading in terms of consumer adoption, product innovation, and retail presence. The United States, Canada, Germany, France, and the United Kingdom have established a strong foothold due to heightened awareness of probiotic foods and widespread availability through supermarkets and specialty stores. Asia Pacific is emerging as a dynamic region fueled by rising health consciousness, rapid urbanization, and expanding modern retail infrastructure in countries such as China, Japan, and Australia. Latin America, the Middle East, and Africa are witnessing gradual market entry supported by evolving dietary preferences and increased promotional activities. Key players shaping the competitive landscape include Lifeway Foods, Inc., Danone S.A., and Biotiful Dairy Ltd., each investing in product development, clean label initiatives, and strategic distribution partnerships to capture new consumer segments and drive growth.
Market Insights
- The Low-Fat Content Kefir Market was valued at USD 761.11 million in 2018, reached USD 1,303.29 million in 2024, and is expected to reach USD 2,767.85 million by 2032, with a CAGR of 9.20%.
- Strong demand for healthier dairy alternatives and probiotic-rich beverages is fueling steady market growth worldwide.
- Trends highlight the introduction of innovative flavors, organic and plant-based options, and clean label formulations to attract health-conscious consumers.
- Leading players such as Lifeway Foods, Danone, and Nestlé focus on product innovation, expanding distribution networks, and strategic partnerships to maintain a competitive edge.
- Market restraints include limited consumer awareness in emerging regions and challenges in cold chain logistics and product shelf life.
- North America holds the largest share at 40.8%, with the U.S. and Canada driving growth, while Asia Pacific is the fastest-growing region with a CAGR of 10.8%.
- Regional dynamics show Europe as a mature market with strong organic kefir sales, Latin America and Africa presenting untapped opportunities, and the Middle East showing steady progress through expanding retail infrastructure.
Market Drivers
Rising Health Awareness and Shift Toward Functional Foods
Consumers are increasingly prioritizing health and wellness, driving demand for products that offer both nutritional value and convenience. The Low Fat Content Kefir Market benefits from this trend, as kefir is recognized for its probiotic content and digestive health benefits. The rising prevalence of lifestyle-related diseases is pushing more individuals to seek low-fat, gut-friendly options. Kefir’s association with improved immunity and weight management appeals to health-conscious consumers seeking functional foods. Product labeling that highlights live cultures and natural ingredients further supports market growth. Health campaigns and endorsements by nutritionists strengthen consumer confidence in kefir’s benefits. This heightened health awareness fuels sustained demand across different demographics.
- For instance, Lifeway Foods reported selling over 100 million servings of kefir in 2022, highlighting strong consumer adoption for probiotic-rich dairy products.
Expansion of Modern Retail Channels and Accessibility
The expansion of supermarkets, hypermarkets, and online platforms is making low fat kefir more accessible to a wider audience. Urbanization and changing lifestyles are shifting consumer preferences toward convenient shopping experiences. The Low Fat Content Kefir Market leverages modern retail distribution to reach both urban and semi-urban consumers. Promotional strategies such as in-store tastings and product sampling help increase product trials and brand loyalty. Retailers are offering a broader range of kefir products, including flavored and organic variants, to cater to diverse tastes. Improved cold chain logistics ensures product freshness and availability. Wider product accessibility drives market penetration and boosts overall sales.
- For instance, Danone’s distribution network now includes more than 120,000 retail outlets globally, significantly enhancing the reach of its kefir and fermented dairy brands.
Product Innovation and Clean Label Movement
Manufacturers are investing in product development to address evolving consumer expectations for variety and transparency. It is witnessing a surge in new flavors, organic formulations, and plant-based alternatives. The clean label movement, with its emphasis on minimal and recognizable ingredients, is shaping product innovation in the market. Companies are focusing on non-GMO, gluten-free, and additive-free options to align with consumer demands. Marketing efforts highlight the absence of artificial sweeteners and preservatives. This commitment to clean labeling builds brand trust and attracts a growing segment of health-focused buyers. Continuous product innovation keeps consumer interest high and encourages repeat purchases.
Globalization of Dietary Habits and Cross-Cultural Adoption
The globalization of dietary preferences is driving the adoption of kefir beyond its traditional markets. The Low Fat Content Kefir Market is capitalizing on increased exposure to international cuisines and wellness trends. Social media, travel, and influencer endorsements are accelerating the introduction of kefir into new regions. Consumer curiosity about global health foods promotes experimentation with low fat kefir. Strategic partnerships with distributors and local foodservice operators enhance market reach. Tailored product offerings, such as lactose-free or regionally inspired flavors, support successful market entry. The cross-cultural acceptance of kefir underpins its global market expansion.
Market Trends
Surging Demand for Probiotic-Rich and Functional Beverages
The Low-Fat Content Kefir Market is witnessing strong demand for probiotic-rich beverages as consumers increasingly prioritize gut health. It has become a preferred choice among individuals seeking products that support digestive wellness and immune function. The trend toward functional beverages, which offer added health benefits beyond basic nutrition, is driving steady market growth. Brands are positioning kefir as a daily wellness drink, targeting both general and specialized health segments. Marketing campaigns often highlight the presence of live cultures and low fat content, appealing to the wellness-conscious demographic. The proliferation of health blogs and digital media has amplified awareness and adoption rates. These trends underline kefir’s rising role in the functional beverage category.
- For instance, Biotiful Dairy sold over 18 million bottles of kefir in the UK market in 2022, reflecting widespread consumer acceptance of probiotic drinks.
Innovation in Flavors and Product Formats
Manufacturers in the Low-Fat Content Kefir Market are responding to evolving consumer tastes by expanding their product portfolios with new flavors and convenient formats. It has seen the introduction of fruit-infused, botanical, and exotic flavor variants, appealing to younger and adventurous consumers. Single-serve bottles, on-the-go pouches, and snack-sized offerings enhance portability and convenience. Companies are also developing lactose-free and plant-based kefir options to address dietary restrictions and expand the consumer base. Seasonal and limited-edition flavors further stimulate interest and trial. This innovation keeps the product category vibrant and competitive. Expanding variety and convenience ensure continued consumer engagement.
- For instance, Nestlé S.A. introduced 12 new kefir product SKUs in 2023 across Europe and Asia, expanding its lineup to include plant-based and specialty flavors.
Emphasis on Clean Labels and Transparency
The clean label trend is shaping the Low-Fat Content Kefir Market, with consumers increasingly demanding transparency in ingredient sourcing and product formulation. It reflects a strong preference for minimally processed products with natural, recognizable components. Manufacturers are highlighting the absence of artificial preservatives, sweeteners, and additives, which aligns with broader wellness trends. Labels now frequently feature certifications such as organic, non-GMO, and gluten-free to build trust. Clear communication about probiotic strains and nutritional benefits is also becoming standard practice. This focus on authenticity and transparency enhances brand loyalty and consumer confidence. Clean labeling continues to influence purchasing decisions in the kefir category.
Expansion into Emerging and Niche Markets
The Low-Fat Content Kefir Market is expanding into new geographic and demographic segments, driven by changing dietary habits and increased exposure to international foods. It is gaining traction in regions outside its traditional strongholds due to growing urban populations and the rise of modern retail infrastructure. Brands are adapting marketing strategies to target niche groups, such as athletes, vegans, and individuals with specific health concerns. Collaborations with health professionals and foodservice operators help drive awareness and adoption in emerging markets. Tailored product offerings and educational initiatives are supporting market entry and acceptance. The trend toward global and niche expansion continues to propel market growth.
Market Challenges Analysis
Limited Consumer Awareness and Market Education
The Low-Fat Content Kefir Market faces a significant challenge due to limited consumer awareness, particularly in emerging economies and non-traditional regions. Many consumers are unfamiliar with kefir’s health benefits or how it differs from other dairy products, creating a barrier to widespread adoption. It must invest in education campaigns and targeted marketing to inform consumers about its probiotic content, digestive advantages, and suitability for modern lifestyles. Retailers and brands encounter difficulties in persuading first-time buyers, as misconceptions or lack of familiarity can impact purchasing decisions. Building trust through transparent labeling and in-store promotions remains a priority. Expanding product knowledge is essential for unlocking the market’s full potential.
Supply Chain Complexity and Quality Control
The Low-Fat Content Kefir Market also encounters challenges related to supply chain management and maintaining consistent product quality. It relies on efficient cold chain logistics to preserve freshness and probiotic viability, particularly during long-distance transportation. Small-scale producers and brands in developing markets may struggle with infrastructure gaps, leading to spoilage or reduced shelf life. Stringent quality control standards are necessary to ensure product safety and consumer trust. Meeting regulatory requirements across diverse markets further adds to operational complexity. Addressing these supply chain and quality challenges is critical for sustaining growth and competitiveness.
Market Opportunities
Expansion into Health-Conscious and Niche Consumer Segments The Low-Fat Content Kefir Market holds strong opportunities by targeting health-conscious and niche consumer groups. Increasing demand for functional foods among athletes, weight-conscious individuals, and those with specific dietary preferences provides avenues for market penetration. It can benefit from developing specialized variants, such as lactose-free, vegan, or fortified kefir, to address unique nutritional needs. Marketing partnerships with nutritionists, fitness centers, and wellness influencers can drive awareness and brand loyalty. Customizing packaging and portion sizes for on-the-go consumption enhances appeal. These efforts enable brands to capture untapped segments and expand their consumer base. Targeted product innovation supports sustained growth in diverse markets.
Geographic Diversification and Emerging Market Expansion The Low-Fat Content Kefir Market can leverage opportunities through geographic diversification and expansion into emerging markets. Rising urbanization, growing middle-class populations, and the expansion of modern retail infrastructure in Asia Pacific, Latin America, and the Middle East create fertile ground for new market entry. It can build strategic alliances with local distributors and retailers to establish strong distribution networks. Educational initiatives and localized marketing campaigns are vital for increasing product awareness in these regions. Brands that adapt flavor profiles and formats to local preferences gain competitive advantage. Exploring emerging markets positions the sector for robust long-term growth and increased global presence.
Market Segmentation Analysis:
By Product Type:
The market features plain or unflavored kefir, flavored varieties, organic and conventional options, Greek-style kefir, frozen formats, and other niche products. Flavored kefir holds a significant share, appealing to consumers seeking taste variety and convenience, while organic and Greek-style options cater to the growing demand for clean label and high-protein dairy products. Frozen kefir is gaining traction in developed regions, driven by the trend toward innovative, indulgent yet healthy snacks. Plain or unflavored kefir continues to attract traditional consumers and those with dietary sensitivities.
- For instance, Wallaby Yogurt Company, Inc. expanded its kefir line to 8 unique flavors in 2022, launching 3 new varieties to target younger consumers.
By Source:
The Low-Fat Content Kefir Market includes cow milk, goat milk, sheep milk, plant-based alternatives, and other specialty bases. Cow milk-based kefir dominates due to widespread availability and consumer familiarity, but goat and sheep milk variants are seeing steady growth among health-conscious and lactose-sensitive groups. Plant-based kefir, utilizing ingredients such as coconut, almond, or soy, is expanding rapidly to meet vegan and dairy-free consumer needs. These alternatives contribute to broadening the market’s reach across demographic lines, while niche sources maintain interest among specialty and gourmet segments.
- For instance, Green Valley Creamery’s plant-based kefir sales grew to 2 million bottles in 2022, doubling volume compared to the previous year.
By Packaging Type:
The market is divided into bottles, pouches, tetra packs, cups and tubs, and others. Bottles remain the preferred packaging format, favored for their portability, convenience, and preservation of product integrity. Pouches and tetra packs are rising in popularity for on-the-go consumption and efficient storage, especially in urban environments with busy lifestyles. Cups and tubs appeal to consumers looking for single-serve or multi-portion options suitable for at-home use. Innovative packaging designs and materials are supporting differentiation and shelf appeal across retail channels. The range of packaging types enables brands to target specific consumption occasions, driving overall market growth and consumer engagement.
Segments:
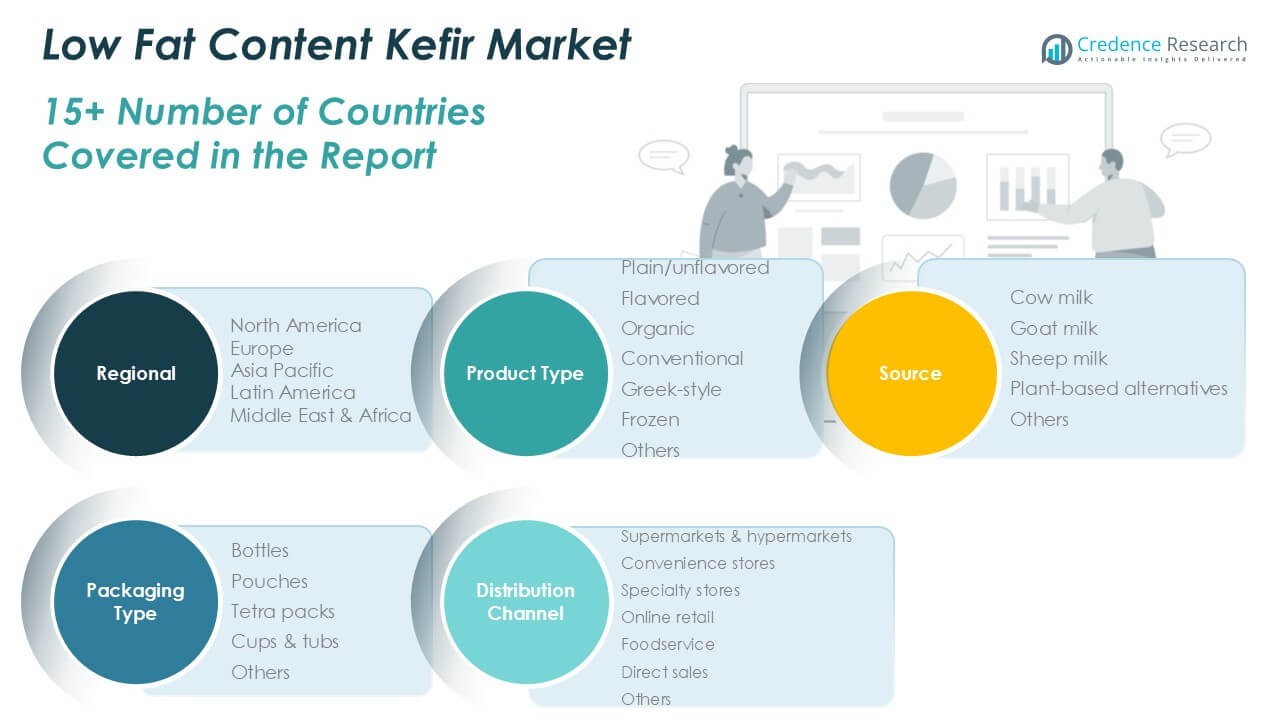
Based on Product Type:
- Plain/unflavored
- Flavored
- Organic
- Conventional
- Greek-style
- Frozen
- Others
Based on Source:
- Cow milk
- Goat milk
- Sheep milk
- Plant-based alternatives
- Others
Based on Packaging Type:
- Bottles
- Pouches
- Tetra packs
- Cups & tubs
- Others
Based on Distribution Channel:
- Supermarkets & hypermarkets
- Convenience stores
- Specialty stores
- Online retail
- Foodservice
- Direct sales
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Low-Fat Content Kefir Market
North America Low-Fat Content Kefir Market grew from USD 312.99 million in 2018 to USD 530.04 million in 2024 and is projected to reach USD 1,128.99 million by 2032, reflecting a compound annual growth rate (CAGR) of 9.2%. North America is holding a 41% market share. The United States and Canada lead the region, with strong consumer awareness of probiotics and a developed functional food sector supporting rapid market expansion. Innovation in flavors and product formats is appealing to diverse consumer groups, while a robust retail network drives accessibility. Marketing strategies that emphasize digestive health are especially effective in this region. Key industry players are investing in new product development, reinforcing the region’s leadership.
Europe Low-Fat Content Kefir Market
Europe Low-Fat Content Kefir Market grew from USD 227.24 million in 2018 to USD 375.78 million in 2024 and is forecast to reach USD 753.78 million by 2032, with a CAGR of 8.4%. Europe accounts for a 27% market share. Germany, France, and the United Kingdom represent the largest markets, fueled by rising interest in fermented dairy products and a shift toward natural, clean label foods. The popularity of organic and Greek-style kefir continues to rise among health-conscious consumers. Regional manufacturers are emphasizing sustainability and locally sourced ingredients to appeal to evolving tastes. Supermarkets and specialty stores serve as primary distribution channels, broadening consumer access.
Asia Pacific Low-Fat Content Kefir Market
Asia Pacific Low-Fat Content Kefir Market grew from USD 157.90 million in 2018 to USD 291.40 million in 2024 and is expected to reach USD 695.37 million by 2032, at a CAGR of 10.8%. Asia Pacific commands a 25% market share, led by China, Japan, South Korea, and Australia. Rapid urbanization, growing disposable incomes, and a burgeoning middle class drive demand for functional and health-oriented foods. Awareness campaigns by brands and increased availability of kefir through modern retail outlets accelerate adoption. Plant-based and lactose-free variants are particularly popular, catering to diverse dietary requirements. Regional innovation and expanding distribution networks position Asia Pacific as a key growth area.
Latin America Low-Fat Content Kefir Market
Latin America Low-Fat Content Kefir Market grew from USD 29.27 million in 2018 to USD 49.35 million in 2024 and is anticipated to reach USD 89.98 million by 2032, with a CAGR of 7.1%. Latin America holds a 3% market share. Brazil, Mexico, and Argentina are key countries, where interest in wellness and functional beverages is steadily increasing. Manufacturers are focusing on affordable options and smaller pack sizes to match local consumption patterns. Supermarkets and convenience stores support market entry, while education initiatives are helping boost consumer awareness. Regional players are introducing traditional and tropical flavors to attract a broader audience.
Middle East Low-Fat Content Kefir Market Middle East Low-Fat Content Kefir Market grew from USD 19.29 million in 2018 to USD 29.89 million in 2024 and is projected to reach USD 52.41 million by 2032, reflecting a CAGR of 6.6%. The Middle East contributes a 2% market share. Saudi Arabia and the United Arab Emirates are at the forefront, driven by rising health awareness and increasing demand for premium dairy alternatives. The market benefits from the growing expatriate population and evolving retail infrastructure. Brands are highlighting the digestive and immunity benefits of kefir to appeal to health-conscious shoppers. Distribution through supermarkets, hypermarkets, and online channels continues to grow.
Africa Low-Fat Content Kefir Market
Africa Low-Fat Content Kefir Market grew from USD 14.43 million in 2018 to USD 26.82 million in 2024 and is expected to reach USD 47.33 million by 2032, at a CAGR of 6.7%. Africa makes up 2% of the global market share. South Africa, Nigeria, and Kenya are leading markets, supported by urbanization and an expanding middle class with an interest in wellness products. Limited consumer awareness remains a challenge, but increased marketing and distribution efforts are improving access. Brands are experimenting with smaller, affordable packs to reach a wider audience. The region’s potential for growth is anchored in rising health consciousness and a gradual shift in dietary preferences.
Key Player Analysis
- Lifeway Foods, Inc.
- Danone S.A.
- Nestlé S.A.
- Green Valley Creamery
- Redwood Hill Farm & Creamery
- Wallaby Yogurt Company, Inc.
- The Icelandic Milk and Skyr Corporation
- Biotiful Dairy Ltd.
- Yeo Valley Family Farm
- Maple Hill Creamery, LLC
Competitive Analysis
The Low-Fat Content Kefir Market is highly competitive, with leading players such as Lifeway Foods, Inc., Danone S.A., Nestlé S.A., and Biotiful Dairy Ltd. actively shaping the industry’s direction. These companies command strong brand recognition and leverage advanced research and development capabilities to introduce new flavors, formulations, and functional attributes that meet evolving consumer demands. Leading companies focus on developing new flavors, clean label formulations, and functional variants to attract a diverse and health-conscious customer base. Strategic investments in research and development support the launch of organic, lactose-free, and plant-based kefir options, broadening market appeal. Companies actively pursue partnerships and distribution agreements to strengthen their presence in established and emerging markets. The competitive landscape is further intensified by effective marketing campaigns and a focus on consumer education, raising awareness about the health benefits of low-fat kefir. Operational excellence in supply chain management and responsiveness to shifting dietary trends enable market leaders to adapt quickly. Overall, the market’s competitive dynamics drive continuous improvement, enhanced product quality, and increased consumer engagement globally.
Recent Developments
- In July 2024, Maple Hill Creamery expanded its network by adding 14 new farms in Pennsylvania, reinforcing its commitment to producing high-quality, grass-fed organic dairy products. Maple Hill’s kefir lineup includes low-fat (2% reduced fat) options, and the expansion aims to strengthen the supply chain for these products.
- In September 2023, Danone announced a joint business development plan signed with bioscience company Chr. Hansen. This new plan will enable Danone to push boundaries of innovation in the dairy and plant-based categories by using Chr. Hansen’s leading bio-solutions capabilities and leveraging both companies’ extensive culture collections.
Market Concentration & Characteristics
The Low-Fat Content Kefir Market displays a moderate to high level of market concentration, with a few large, established companies holding significant influence through brand reputation, advanced production capabilities, and wide distribution networks. It is characterized by rapid product innovation, strong focus on functional and clean label ingredients, and responsiveness to evolving consumer preferences for health-oriented dairy alternatives. The market offers a broad variety of products, including flavored, organic, Greek-style, and plant-based kefir, catering to both mainstream and niche consumers. Companies invest in marketing strategies and educational campaigns to drive consumer awareness and differentiate their offerings. The market demonstrates high adaptability to regional dietary trends and regulatory requirements, ensuring continued relevance across diverse geographic segments. Competitive intensity encourages ongoing improvements in product quality, packaging, and supply chain efficiency, reinforcing the market’s dynamic and consumer-focused nature.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Source, Packaging Type, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Rising consumer demand for healthier dairy alternatives continues to drive growth in the low-fat content kefir market.
- Increasing awareness of gut health and probiotic benefits boosts product adoption globally.
- Product innovation with fruit-infused and plant-based kefir variants expands consumer base.
- Growth in lactose-intolerant and weight-conscious populations supports market expansion.
- Manufacturers focus on clean-label and organic certifications to meet evolving consumer preferences.
- Retail chains and online platforms enhance product accessibility and market penetration.
- Expanding health and wellness trends across emerging markets fuel demand for low-fat kefir.
- Partnerships between dairy cooperatives and health food brands create new marketing avenues.
- Rising investments in R&D improve flavor, texture, and shelf life of low-fat kefir products.
- Regulatory support for probiotic-rich and low-fat food categories strengthens global market potential.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Health Awareness and Functional Food Trends
Consumers are increasingly seeking foods that support digestive health and overall wellness, making low-fat kefir—rich in probiotics and low in calories—an attractive choice for health-conscious individuals.
Product Innovation and Clean Label Demand
Manufacturers are introducing new flavors, organic and plant-based options, and clean label formulations, which appeal to consumers looking for transparency, natural ingredients, and variety in their dairy alternatives.
Expansion of Modern Retail and Online Channels
The growth of supermarkets, specialty stores, and e-commerce platforms is making low-fat kefir more accessible, increasing product visibility and driving trial among new consumer segments.
Rising Urbanization and Changing Dietary Habits
Urban populations with busy lifestyles are gravitating toward convenient, ready-to-consume functional beverages like kefir, supporting market growth in both developed and emerging regions.
Globalization and Cross-Cultural Adoption
Exposure to international cuisines and wellness trends, amplified by social media and influencer marketing, is accelerating the adoption of kefir in new geographic markets beyond its traditional strongholds.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Low-Fat Content Kefir Market?
What factors are driving the growth of the Low-Fat Content Kefir Market?
What are the key segments within the Low-Fat Content Kefir Market?
What are some challenges faced by the Low-Fat Content Kefir Market?
Who are the major players in the Low-Fat Content Kefir Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Source
- 1.2.1 Cow milk
- 1.2.2 Goat milk
- 1.2.3 Sheep milk
- 1.2.4 Plant-based alternatives
- 1.2.5 Others
- 1.3 By Product Type
- 1.3.1 Plain/unflavored
- 1.3.2 Flavored
- 1.3.3 Organic
- 1.3.4 Conventional
- 1.3.5 Greek-style
- 1.3.6 Frozen
- 1.4 By Packaging Type
- 1.4.1 Bottles
- 1.4.2 Pouches
- 1.4.3 Tetra packs
- 1.4.4 Cups & tubs
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,303.29 million → 2032: USD 2,767.85 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Low-Fat Content Kefir Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Low-Fat Content Kefir Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Low-Fat Content Kefir Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Low-Fat Content Kefir Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Low-Fat Content Kefir Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Low-Fat Content Kefir Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Low-Fat Content Kefir Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Low-Fat Content Kefir Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,303.29 million → 2032: USD 2,767.85 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Low-Fat Content Kefir Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Source - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cow milk
- 12.3.7.2 Goat milk
- 12.3.7.3 Sheep milk
- 12.3.7.4 Plant-based alternatives
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Plain/unflavored
- 12.4.7.2 Flavored
- 12.4.7.3 Organic
- 12.4.7.4 Conventional
- 12.4.7.5 Greek-style
- 12.4.7.6 Frozen
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Packaging Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Bottles
- 12.5.7.2 Pouches
- 12.5.7.3 Tetra packs
- 12.5.7.4 Cups & tubs
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Low-Fat Content Kefir Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Low-Fat Content Kefir Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Low-Fat Content Kefir Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Lifeway Foods, Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Danone S.A.
- 17.4 Nestlé S.A.
- 17.5 Green Valley Creamery
- 17.6 Redwood Hill Farm & Creamery
- 17.7 Wallaby Yogurt Company, Inc.
- 17.8 The Icelandic Milk and Skyr Corporation
- 17.9 Biotiful Dairy Ltd.
- 17.10 Yeo Valley Family Farm
- 17.11 Maple Hill Creamery, LLC
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
