
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| AI Content Detection Software Market Size 2024 | USD 1765 Million |
| AI Content Detection Software Market, CAGR | 21.6 % |
| AI Content Detection Software Market Size 2032 | USD 8437.4 Million |
Market Overview:
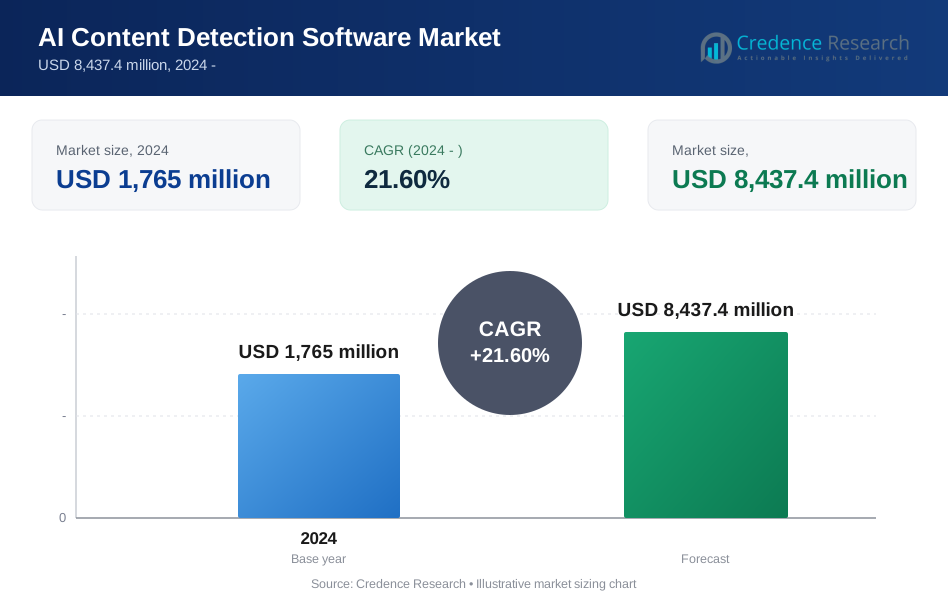
The AI Content Detection Software Market size was valued at USD 1765 million in 2024 and is anticipated to reach USD 8437.4 million by 2032, at a CAGR of 21.6 % during the forecast period (2024-2032).
Key drivers shaping the market include the proliferation of AI-generated text and media, which has increased the risk of undetected plagiarism, deepfakes, and manipulated content. Enterprises, academic institutions, and regulators are prioritizing content validation and compliance to safeguard intellectual property and maintain brand trust. The demand for real-time, automated detection tools that can efficiently analyze vast volumes of digital data—across languages and formats—is rising sharply. Advanced algorithms, natural language processing (NLP), and deep learning models underpin new detection capabilities, allowing software vendors to provide accurate, scalable, and user-friendly solutions that integrate seamlessly with content management systems and online platforms.
Regionally, North America holds the largest market share due to the rapid adoption of AI technologies, a strong regulatory environment, and significant investments from EdTech, media, and corporate sectors. Key players in the AI Content Detection Software Market include Originality.AI, Copyleaks, GPTRadar, and Willie. Europe follows closely, supported by stringent copyright laws and increased focus on academic integrity. The Asia Pacific region is emerging as a high-growth market, driven by expanding digital education, rising internet penetration, and a surge in local content creation. Latin America and the Middle East & Africa are witnessing growing demand, as governments and businesses accelerate digital transformation initiatives. Across all regions, rising awareness of content authenticity and the integration of AI tools in workflow management are fueling market expansion.
Market Insights:
- The AI Content Detection Software Market was valued at USD 1,765 million in 2024 and will reach USD 8,437.4 million by 2032.
- Demand rises sharply due to risks from AI-generated plagiarism, deepfakes, and manipulated content across sectors.
- Organizations seek real-time, automated detection tools that work across languages and digital formats.
- Strict compliance requirements and intellectual property concerns drive adoption in academia, media, and corporate environments.
- North America holds 44% market share, Europe 29%, and Asia Pacific 19%, reflecting strong adoption and investment.
- Major challenges include rapid evolution of generative AI, evasion tactics, and the need for robust data privacy.
- Key players such as Originality.AI, Copyleaks, GPTRadar, and Willie lead with advanced, scalable solutions.
Market Drivers:
Proliferation of Generative AI Technologies Increases Need for Detection Solutions:
The widespread adoption of generative AI tools has led to a dramatic increase in the creation of synthetic content across digital platforms. The AI Content Detection Software Market is expanding as organizations require solutions to differentiate between human and machine-generated material. Businesses, academic institutions, and publishers face rising risks related to misinformation, deepfakes, and AI-driven plagiarism. The increasing sophistication of AI-generated text and images pushes detection vendors to continuously update their algorithms. Companies seek software that can quickly and accurately analyze content in real time. This demand strengthens the role of AI content detection as a standard tool in digital operations.
Strict Regulatory Compliance and Intellectual Property Protection Drive Adoption:
Governments and industry regulators enforce stringent rules regarding copyright, academic integrity, and online publishing standards. Organizations must ensure their content adheres to legal requirements, avoid infringement, and protect proprietary information. The AI Content Detection Software Market benefits from these regulatory pressures, as companies adopt detection software to reduce liability and maintain compliance. Strict academic and corporate policies accelerate the implementation of verification tools. Software providers offer robust solutions to monitor large volumes of digital assets, ensuring only authentic, rights-cleared content reaches the public domain. It enables organizations to safeguard intellectual property and build trust with stakeholders.
- For instance, Copyleaks’ enterprise-level AI Content Detector supports over 30 languages and integrates with learning management systems, offering 99.12% accuracy, which enables global universities and publishers to verify content authenticity at scale.
Demand for Real-Time, Scalable, and Multilingual Content Validation:
The growing volume and diversity of digital content require automated validation tools capable of operating at scale. Organizations value AI detection software for its ability to process thousands of documents, posts, or multimedia files in real time. The global nature of digital communications increases the need for multilingual support and adaptability across content formats. The AI Content Detection Software Market addresses these requirements by integrating advanced NLP and machine learning models. Vendors provide seamless workflow integrations, allowing clients to embed detection capabilities into existing content management systems and online platforms. Scalability and accuracy remain top priorities for buyers.
- For instance, Smartcat AI Agents are capable of automatically translating and adapting content into over 280 languages, allowing enterprises to manage and validate multilingual assets across global markets without manual intervention.
Integration with Enterprise and Educational Platforms Expands Market Reach:
Many enterprises and educational institutions have embedded AI detection tools within their operational and academic systems. Integration with learning management systems, publishing software, and corporate communications platforms increases efficiency and ensures consistent content verification. The AI Content Detection Software Market grows as organizations view detection tools as essential components of quality assurance and risk mitigation strategies. Providers tailor solutions to meet industry-specific needs, further expanding adoption. Seamless integration improves user experience and drives ongoing investment in detection technology.
Market Trends:
Adoption of Advanced AI Models and Multimodal Detection Capabilities Accelerates:
Vendors are integrating advanced machine learning and natural language processing (NLP) models to improve detection accuracy and efficiency. The AI Content Detection Software Market is witnessing the rise of solutions that can analyze not only text, but also images, audio, and video for authenticity and originality. Multimodal detection tools address complex content manipulation tactics used in deepfakes and cross-media plagiarism. Companies focus on developing context-aware algorithms that can recognize subtle patterns and nuanced forms of AI-generated content. Software providers invest in continual model training and the use of large, diverse datasets to enhance reliability. This trend reflects the market’s move toward comprehensive, AI-driven validation across multiple digital content types.
- For instance, the RU-AI dataset, developed for multimodal AI content detection, contains 1,475,370 instances across text, image, and voice modalities, enabling robust model training and benchmarking for machine-generated content detection.
Cloud-Based Solutions and Seamless Workflow Integrations Gain Traction:
Organizations increasingly favor cloud-based AI detection software for scalability, flexibility, and lower infrastructure costs. Vendors offer solutions that integrate seamlessly with content management systems, digital publishing platforms, and learning management tools. The AI Content Detection Software Market grows as companies demand real-time, automated detection embedded directly into content creation and distribution processes. Custom APIs and plug-ins enable tailored deployment, while cloud platforms support instant updates and remote access. This trend enables users to streamline operations, strengthen content governance, and ensure compliance with evolving standards across global teams.
- For instance, Apify’s AI Content Detector API supports file formats such as .txt, .md, .html, and .docx, and automatically splits and analyzes large texts for content authenticity, providing detailed human and AI scores for each block of text.
Market Challenges Analysis:
Rapid Evolution of Generative AI and Evasion Techniques Hinders Detection Accuracy:
The fast-paced development of generative AI models creates challenges for detection software to keep up with new forms of synthetic content. The AI Content Detection Software Market faces persistent threats from advanced text, image, and audio generators designed to bypass standard detection algorithms. Evasion tactics, such as paraphrasing tools and adversarial attacks, make it difficult to maintain consistently high accuracy. Vendors must invest heavily in continuous research and model updates to address these challenges. This ongoing arms race between creators and detectors raises operational costs and strains development cycles. Companies require agile solutions that adapt quickly to emerging threats.
Balancing Privacy, Data Security, and User Trust in Content Analysis:
Organizations often hesitate to deploy content detection tools due to concerns about data privacy and information security. The AI Content Detection Software Market must address strict regulatory requirements and user expectations around confidentiality, especially when analyzing sensitive or proprietary content. Data handling practices and software integrations must comply with regional privacy laws such as GDPR and CCPA. Building user trust depends on transparent policies, secure data processing, and minimal intrusion into personal or confidential material. Any failure in privacy protection can undermine adoption rates and damage vendor reputations.
Market Opportunities:
Expansion into New Industry Verticals and Emerging Markets Fuels Growth:
The growing awareness of content authenticity across sectors such as healthcare, legal, finance, and government creates untapped opportunities for AI detection software providers. The AI Content Detection Software Market can expand its reach by addressing industry-specific challenges related to compliance, risk management, and data integrity. Businesses seek tailored solutions that meet unique workflow and regulatory requirements. The surge in digital transformation projects in emerging markets supports further adoption. Vendors that offer flexible and customizable platforms stand to benefit from rising demand in new geographic regions. This growth potential extends market influence well beyond traditional education and publishing sectors.
Partnerships and Integration with Leading Technology Platforms Drive Value:
Strategic alliances with major content management, e-learning, and enterprise software providers enable deeper market penetration for AI detection tools. The AI Content Detection Software Market can unlock new revenue streams through plug-ins, APIs, and value-added services that embed detection capabilities into existing digital ecosystems. Companies prioritize seamless integrations that improve user experience and operational efficiency. Ongoing collaborations with technology partners support faster innovation and broader solution adoption. The ability to offer scalable detection across diverse platforms positions vendors to capture a larger share of enterprise and institutional spending.
Market Segmentation Analysis:
By Type:
The AI Content Detection Software Market features segments such as text detection, image detection, audio detection, and video detection software. Text detection holds the largest share, driven by the widespread use of generative AI in written content across academia and media. Image, audio, and video detection segments are growing steadily as concerns over deepfakes and synthetic media manipulation increase. Software vendors respond with specialized solutions to address unique content formats. The market is expected to see robust demand across all types as organizations adopt comprehensive detection strategies.
- For instance, Winston AI’s latest model achieved a 99.98 accuracy rate in detecting AI-generated content using a dataset of 10,000 texts, including 5,000 human texts and 5,000 AI generated texts generated.
By Technology:
The market is segmented into natural language processing (NLP), machine learning, deep learning, and computer vision. NLP dominates, enabling high-precision analysis for identifying AI-generated text and plagiarism. Machine learning and deep learning power advanced detection of complex patterns, while computer vision supports visual and multimedia analysis. Vendors leverage these technologies to improve speed, scalability, and accuracy. It remains dynamic, with rapid innovation driven by evolving content creation methods.
By End-Use:
Key end-use sectors include education, media and publishing, corporate enterprises, government, and legal services. Educational institutions use AI detection to uphold academic integrity, while media and enterprises focus on content authenticity and copyright protection. Governments and legal entities deploy these solutions for information validation and regulatory compliance. It expands into new industries, reflecting the growing importance of content detection in digital governance.
- For instance, Numbers Protocol mainnet supports the verification of over 2 million digital content assets as of June 2025.
Segmentations:
By Type:
- Text Detection
- Image Detection
- Audio Detection
- Video Detection
By Technology:
- Natural Language Processing (NLP)
- Machine Learning
- Deep Learning
- Computer Vision
By End-Use:
- Education
- Media and Publishing
- Corporate Enterprises
- Government
- Legal Services
By Deployment Mode:
- Cloud-Based
- On-Premises
By Region:
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa
Regional Analysis:
North America and Europe :
North America accounts for 44% of the global AI Content Detection Software Market, while Europe holds a 29% share. Strong investments in AI research, advanced digital infrastructure, and proactive adoption among educational, media, and corporate sectors drive growth in these regions. Organizations prioritize content authenticity and compliance due to heightened concerns about misinformation, intellectual property, and academic integrity. The United States remains a major hub for both solution providers and users, benefiting from a mature technology landscape and well-defined legal frameworks. Europe supports expansion with strict regulations on copyright, digital publishing, and data protection. Key countries, including the United Kingdom, Germany, and France, invest in detection tools to meet academic standards and safeguard proprietary assets. It continues to attract global vendors that adapt solutions for diverse regulatory environments.
Asia Pacific:
Asia Pacific represents 19% of the global AI Content Detection Software Market. Rapid digitalization, increasing internet penetration, and the proliferation of online education and content creation drive accelerated growth. Countries such as China, India, Japan, and South Korea lead adoption by leveraging technology to manage academic integrity, copyright risks, and the authenticity of user-generated material. Local enterprises and educational institutions invest in scalable detection platforms to address rising volumes of digital content. The presence of a large, multilingual population requires solutions with advanced language capabilities and flexible deployment options. It benefits from government initiatives that promote digital trust and security across the region.
Latin America, Middle East, and Africa :
Latin America holds a 5% share, while the Middle East and Africa together account for 3% of the global AI Content Detection Software Market. Digital adoption is accelerating in business, government, and education, increasing demand for content detection tools. Countries in these regions face growing challenges related to plagiarism, misinformation, and copyright compliance. Market growth is supported by rising investments in IT infrastructure and increasing awareness of content validation needs. Vendors enter these markets with affordable, user-friendly, and cloud-based solutions to overcome cost and access barriers. It gains traction as organizations seek effective ways to manage digital risks and uphold standards of content quality and originality.
Key Player Analysis:
- ai,
- Hive Moderation,
- ZeroGPT
- AI
- Copyleaks,
- GPTRadar
- Willie
- On-page.ai
- Turnitin
- WordAi
Competitive Analysis:
The AI Content Detection Software Market features a competitive landscape defined by technological innovation, rapid product development, and strong customer focus. Key players such as Originality.AI, Copyleaks, GPTRadar, and Willie invest heavily in advanced algorithms and seamless integration capabilities to differentiate their offerings. It drives competition through frequent updates, ensuring detection solutions stay ahead of evolving generative AI threats and content manipulation tactics. Leading vendors prioritize user-friendly interfaces, high detection accuracy, and robust customer support. Partnerships with educational, media, and enterprise platforms help expand market reach and deepen solution adoption. The market rewards agility, technical excellence, and the ability to deliver scalable, customizable tools across diverse industry applications. It continues to attract new entrants, intensifying rivalry and accelerating innovation.
Recent Developments:
- In March 2025, Turnitin introduced "Turnitin Clarity," a platform for AI-assisted composition and academic integrity insights, announced at SXSW EDU and available as an extension to Turnitin Feedback Studio.
- In November 2024, Copyleaks launched "AI Insights," a platform for comprehensive analysis of AI-generated text.
- In March 2025, Originality.AI was awarded a patent for an all-in-one text verification system that combines multiple checks for content analysis.
Market Concentration & Characteristics:
The AI Content Detection Software Market demonstrates moderate concentration, with a mix of established technology firms and innovative startups driving competition. Leading players focus on advanced algorithms, integration capabilities, and continuous updates to maintain market relevance. The market features rapid product development cycles, strong demand for scalable cloud-based solutions, and a high degree of customization to suit varied industry needs. It is characterized by quick adaptation to evolving generative AI threats and ongoing regulatory changes. Partnerships, acquisitions, and frequent product enhancements shape competitive dynamics, making agility and technical innovation essential for long-term success.
Report Coverage:
The research report offers an in-depth analysis based on Type, Technology, End-Use, Deployment Mode and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Vendors will invest in advanced multimodal detection, expanding capabilities to identify deepfake audio, video, and synthetic text.
- It will offer industry-specific modules tailored for healthcare, finance, legal, and government verticals.
- Cloud-native deployments will dominate, enabling scalable, subscription-based access through APIs and plugins.
- Solutions will integrate real-time detection within content creation platforms and enterprise workflows.
- It will leverage contextual analytics and behavioral signals to reduce false positives and improve accuracy.
- Cross-border compliance features will grow to support varied data privacy regulations like GDPR, CCPA, and emerging frameworks.
- Partnerships with LMS, CMS, and e‑learning providers will drive embedded solutions in educational environments.
- It will adopt federated learning and on‑device processing to address privacy concerns and speed detection.
- Ongoing R&D will target counter‑evasion techniques to stay ahead of increasingly sophisticated content manipulation.
- It will introduce user dashboards with analytics and reporting for transparency, auditability, and risk management.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the AI Content Detection Software Market?
What factors are driving the growth of the AI Content Detection Software Market?
What are the key segments within the AI Content Detection Software Market?
What are some challenges faced by the AI Content Detection Software Market?
Who are the major players in the AI Content Detection Software Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 AI Content Detection Software Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global AI Content Detection Software Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 1,765 million → forecast year: USD 8,437.4 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 AI Content Detection Software Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. AI Content Detection Software Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 AI Content Detection Software Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 AI Content Detection Software Market Drivers
- 3.3 AI Content Detection Software Market Restraints & Challenges
- 3.4 AI Content Detection Software Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 AI Content Detection Software Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 AI Content Detection Software Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, AI Content Detection Software category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 AI Content Detection Software Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. AI Content Detection Software Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the AI Content Detection Software market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 AI Content Detection Software Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 AI Content Detection Software Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 AI Content Detection Software Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in AI Content Detection Software (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New AI Content Detection Software Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global AI Content Detection Software Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America AI Content Detection Software Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe AI Content Detection Software Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific AI Content Detection Software Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America AI Content Detection Software Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East AI Content Detection Software Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa AI Content Detection Software Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. AI Content Detection Software Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
