
Market Overview:
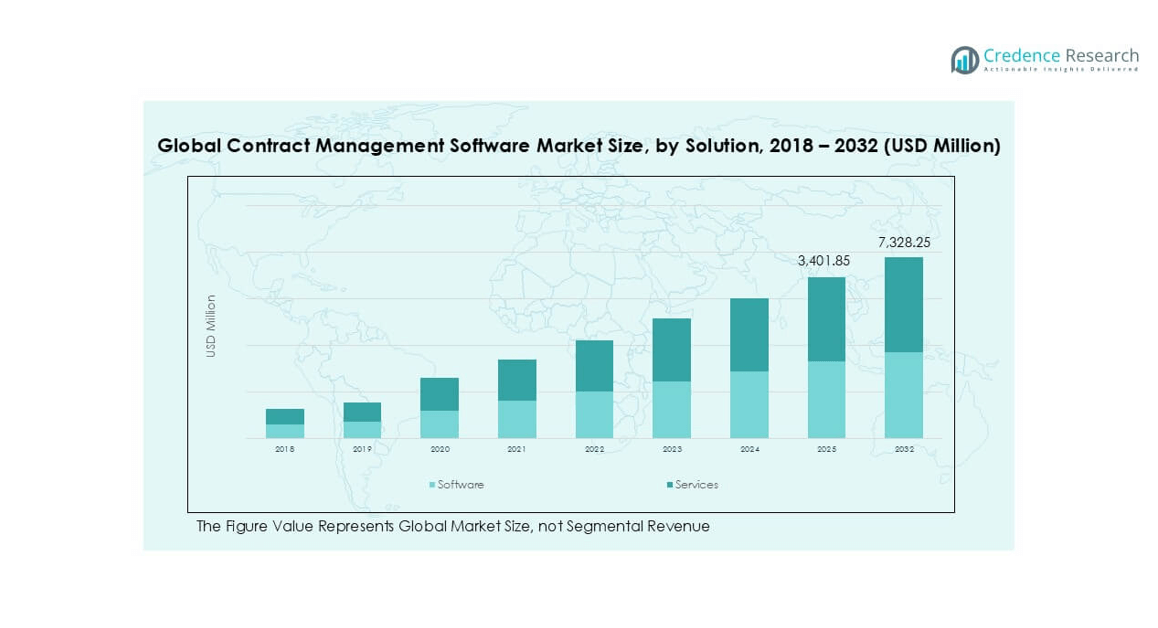
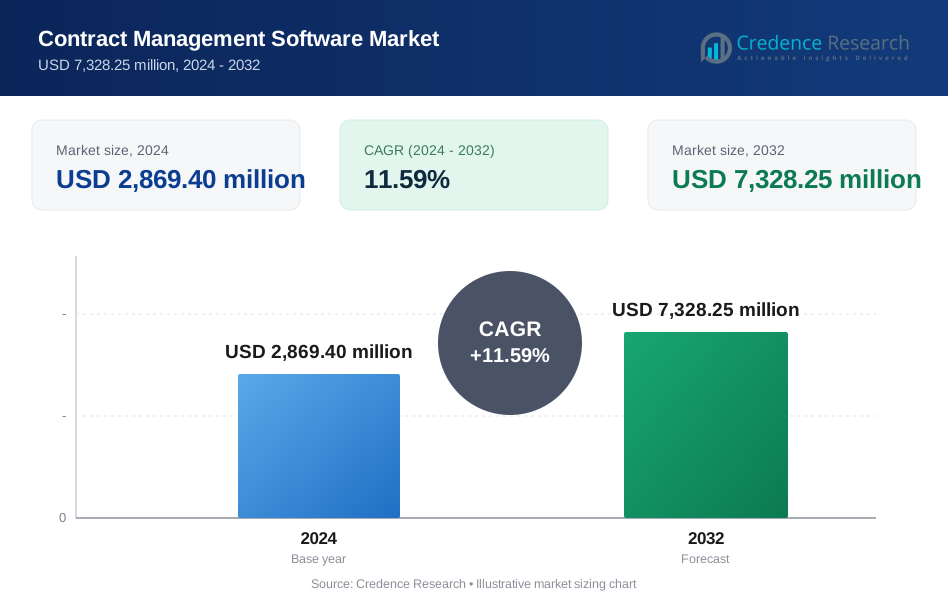
The Contract Management Software market size was valued at USD 1,525.56 million in 2018, increased to USD 2,869.40 million in 2024, and is anticipated to reach USD 7,328.25 million by 2032, growing at a CAGR of 11.59% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Contract Management Software Market Size 2024 | USD 2,869.40 million |
| Contract Management Software Market, CAGR | 11.5% |
| Contract Management Software Market Size 2032 | USD 7,328.25 million |
The Contract Management Software market is highly competitive, with leading players such as SAP, Coupa Software, Infor, ContractWorks, SirionLabs, Zycus, and Agiloft driving innovation and market expansion. These companies focus on enhancing AI integration, cloud capabilities, and user-centric design to meet growing enterprise demands for automation and compliance. North America leads the global market, accounting for 42.9% of the total market share in 2024, supported by early technology adoption, strong regulatory frameworks, and the presence of major solution providers. Asia Pacific follows as the fastest-growing region, driven by rising digitalization and SME adoption.
Market Insights
- The Contract Management Software market was valued at USD 2,869.40 million in 2024 and is projected to reach USD 7,328.25 million by 2032, growing at a CAGR of 11.59% during the forecast period.
- The market is primarily driven by the rising demand for workflow automation, increasing compliance requirements, and the growing shift toward cloud-based solutions across enterprises of all sizes.
- AI and machine learning integration in contract analytics, along with growing adoption among SMEs in emerging markets, are key trends reshaping the industry landscape.
- The market is dominated by players such as SAP, Coupa Software, Infor, ContractWorks, SirionLabs, Zycus, and Agiloft, who focus on cloud innovation, security enhancements, and global expansion; however, high implementation costs and data security concerns remain major restraints.
- North America holds the largest regional share at 42.9%, while the software segment leads by solution; Asia Pacific is the fastest-growing region with a CAGR of 12.8%.
Market Segmentation Analysis:
By Solution
The software segment holds the dominant market share in the Contract Management Software market, driven by its ability to automate contract lifecycle processes, enhance compliance, and reduce manual errors. Organizations are increasingly investing in software solutions to improve efficiency, centralize contract data, and support remote access and collaboration. The growing demand for AI-powered features, such as smart clause identification and risk analysis, further strengthens the software segment. Meanwhile, the services segment, including implementation and support, plays a crucial role in ensuring seamless integration and performance but contributes a smaller share compared to software.
- For instance, SAP’s Ariba Contract Management module processes over 100 million contracts annually across its global client base, enabling high-volume automation and structured contract lifecycle control.
By Deployment Model:
Cloud-based deployment dominates the Contract Management Software market, accounting for the largest revenue share due to its scalability, cost-efficiency, and ease of access. The rapid adoption of cloud solutions across industries stems from the increasing need for real-time collaboration, reduced IT infrastructure burden, and remote working capabilities. Businesses prefer cloud-based models for their flexibility in updates and maintenance, especially among SMEs. Although on-premises deployment offers greater control and data security, particularly for heavily regulated sectors, it has a smaller market share due to higher upfront costs and limited scalability.
- For instance, Agiloft reported that over 90% of its 600+ enterprise clients had transitioned to its cloud-based platform, facilitating contract collaboration across more than 40 \countries.
By Enterprise Size:
Large enterprises lead the Contract Management Software market in terms of market share, as they manage complex, high-volume contract portfolios that demand advanced solutions for compliance, risk management, and operational efficiency. These organizations invest in customizable, feature-rich platforms to streamline contract lifecycles across global operations. However, small and medium-sized enterprises (SMEs) are showing accelerated adoption rates, especially for cloud-based and affordable subscription-based software, driven by digital transformation trends and the growing awareness of contract automation benefits. The increasing availability of scalable, user-friendly platforms supports wider adoption across SMEs.
Market Overview
Rising Demand for Workflow Automation
The growing need to streamline complex contract workflows and reduce manual intervention is a major growth driver. Contract management software automates various stages of the contract lifecycle, including creation, negotiation, approval, and renewal. This automation significantly reduces turnaround times, improves compliance, and enhances visibility across departments. Organizations increasingly seek such solutions to manage high volumes of contracts efficiently, especially in sectors like legal, healthcare, and manufacturing, where documentation and regulatory adherence are critical. The push for operational efficiency continues to drive the adoption of automated contract management tools.
- For instance, Coupa Software’s CLM platform reduced contract cycle times by 35 days across 300 enterprise deployments through embedded workflow automation and digital signature tools.
Surge in Cloud-based Deployments
Cloud-based contract management solutions are gaining significant traction due to their flexibility, scalability, and cost-effectiveness. Businesses, particularly SMEs, prefer cloud deployment models as they minimize the need for IT infrastructure and allow easy access to contract data from any location. The increased acceptance of remote and hybrid work models further boosts this shift toward cloud platforms. Additionally, vendors are offering subscription-based pricing models and advanced features like AI-driven analytics, making cloud-based systems more attractive. This deployment model facilitates faster implementation and system upgrades, contributing to the market’s rapid growth.
- For instance, ContractWorks enabled over 50,000 users across 80+ countries to access contracts remotely, supporting over 3 million document uploads on its cloud-based system.
Increasing Focus on Regulatory Compliance and Risk Mitigation
Enterprises are facing heightened regulatory scrutiny and growing legal risks, compelling them to adopt contract management software that ensures compliance with evolving legal standards. These tools offer audit trails, standardized templates, and real-time monitoring to help businesses avoid contract breaches and penalties. Particularly in industries such as finance, pharmaceuticals, and government, maintaining compliance is crucial. As global operations expand, the complexity of cross-border agreements increases, further driving demand for centralized, compliant contract management platforms that mitigate risk and support governance.
Key Trends & Opportunities
Integration of AI and Machine Learning
Artificial Intelligence (AI) and machine learning are revolutionizing contract management by enabling smart contract analysis, anomaly detection, and predictive risk assessment. These technologies help users extract key clauses, assess contract performance, and flag non-compliance risks in real time. AI-powered contract analytics tools are becoming a differentiator for vendors, offering greater value to enterprises seeking advanced insights and automation. The adoption of natural language processing (NLP) for contract review and automated clause comparison is also expanding, presenting an opportunity for vendors to innovate and differentiate in a competitive market.
- For instance, SirionLabs’ AI engine, SirionOne, analyzes over 7 million contract clauses per month and enables clause-level deviation tracking across global supplier contracts.
Growing Demand from SMEs and Emerging Economies
Small and medium-sized enterprises and businesses in emerging markets represent a significant opportunity for market expansion. As digital transformation initiatives increase globally, SMEs are looking for cost-effective, user-friendly contract management solutions to replace manual or paper-based systems. Vendors offering modular, cloud-based platforms with affordable pricing models are well-positioned to tap into this growing segment. In regions such as Asia-Pacific and Latin America, rising regulatory frameworks and global trade activities are prompting businesses to adopt structured contract management tools, creating new growth avenues for solution providers.
Key Challenges
Data Security and Privacy Concerns
Despite the benefits of cloud-based and AI-driven platforms, concerns about data breaches, unauthorized access, and regulatory non-compliance pose major challenges. Contracts often contain sensitive business information, and any compromise can lead to legal and financial consequences. Ensuring data encryption, user authentication, and compliance with data protection regulations such as GDPR remains a priority for vendors and users alike. Organizations in sectors like finance and healthcare are particularly cautious, which can slow adoption if security concerns are not adequately addressed.
- For instance, Zycus implements AES 256-bit encryption and role-based access controls across its platform, securing over 500 terabytes of contract data for clients in the pharmaceutical and financial sectors.
High Implementation and Integration Costs
Deploying contract management software-especially for large enterprises with legacy systems-can incur high upfront costs related to customization, integration, and employee training. The complexity of aligning the software with existing enterprise resource planning (ERP) or customer relationship management (CRM) systems adds to the challenge. For many organizations, particularly in cost-sensitive markets, these expenses act as a barrier to adoption. Vendors must offer flexible pricing, robust support, and seamless integration capabilities to overcome this issue and drive broader market penetration.
User Resistance and Change Management Issues
Resistance to change remains a critical challenge during the adoption of contract management solutions. Employees accustomed to traditional, manual contract handling may resist transitioning to automated systems, fearing complexity or job redundancy. Inadequate user training and poor change management practices can lead to underutilization of the platform and reduced ROI. To address this, companies need to invest in user onboarding, provide clear communication about benefits, and involve stakeholders early in the implementation process to ensure smoother adoption and sustained usage.
Regional Analysis
North America
North America held the largest share in the Contract Management Software market, accounting for approximately 42.9% of the global market in 2024. The market grew from USD 660.75 million in 2018 to USD 1,229.78 million in 2024, and it is projected to reach USD 3,149.57 million by 2032, registering a CAGR of 11.6%. This growth is fueled by early technology adoption, widespread digital transformation, and stringent regulatory frameworks across industries such as healthcare, finance, and legal. The presence of key market players and increased demand for AI-integrated contract solutions further solidify the region’s dominance.
- For instance, Infor's Contract Lifecycle Management tool supports more than 12,000 U.S.-based hospitals and clinics with real-time compliance reporting and multi-tiered contract approval routing.
Europe
Europe accounted for around 17.7% of the global Contract Management Software market in 2024, rising from USD 285.80 million in 2018 to USD 508.21 million in 2024, with an expected value of USD 1,180.67 million by 2032, at a CAGR of 10.3%. The region’s growth is driven by increasing compliance requirements under GDPR, a growing focus on legal and procurement automation, and a steady shift towards cloud-based deployments. Industries such as manufacturing, public administration, and legal services are embracing contract management tools to enhance transparency and streamline operations.
- For instance, Agiloft expanded its European footprint by onboarding over 300 public sector and enterprise clients in Germany and the Netherlands, integrating EU data residency protocols and GDPR-aligned contract templates.
Asia Pacific
Asia Pacific is emerging as the fastest-growing region in the Contract Management Software market, with a CAGR of 12.8%, and contributed about 30.2% of the global market in 2024. The market rose from USD 436.83 million in 2018 to USD 867.92 million in 2024, and is forecasted to reach USD 2,419.16 million by 2032. The rapid expansion is supported by increasing digitization among SMEs, rising cross-border trade, and growing regulatory oversight in developing economies such as China and India. The demand for scalable, cost-effective cloud-based solutions is accelerating adoption across industries.
Latin America
Latin America represented approximately 4.8% of the global Contract Management Software market in 2024. The market expanded from USD 73.58 million in 2018 to USD 136.72 million in 2024, and is anticipated to reach USD 309.89 million by 2032, growing at a CAGR of 9.9%. Factors such as economic modernization, growth in the legal and financial sectors, and increasing awareness of compliance needs are driving market growth. Though slower compared to major regions, opportunities remain in countries like Brazil and Mexico as enterprises seek solutions to manage growing contract volumes and improve operational efficiency.
Middle East
The Middle East captured a modest 2.5% share of the global Contract Management Software market in 2024. The regional market size increased from USD 41.55 million in 2018 to USD 71.24 million in 2024, and is projected to reach USD 152.63 million by 2032, registering a CAGR of 9.1%. Growth is supported by digital transformation initiatives in the public sector and large-scale infrastructure and energy projects requiring robust contract oversight. Governments and enterprises across the UAE and Saudi Arabia are investing in automation tools to ensure compliance, minimize disputes, and improve transparency in procurement processes.
Africa
Africa accounted for the smallest share of the global market at 1.9% in 2024. The Contract Management Software market in the region grew from USD 27.05 million in 2018 to USD 55.53 million in 2024, and is expected to reach USD 116.32 million by 2032, growing at a CAGR of 8.8%. Although still nascent, market growth is supported by increasing ICT adoption, regulatory modernization, and demand for transparency in public procurement. Countries such as South Africa and Nigeria are witnessing gradual adoption, especially among financial institutions and government agencies aiming to streamline documentation and contract compliance.
Market Segmentations:
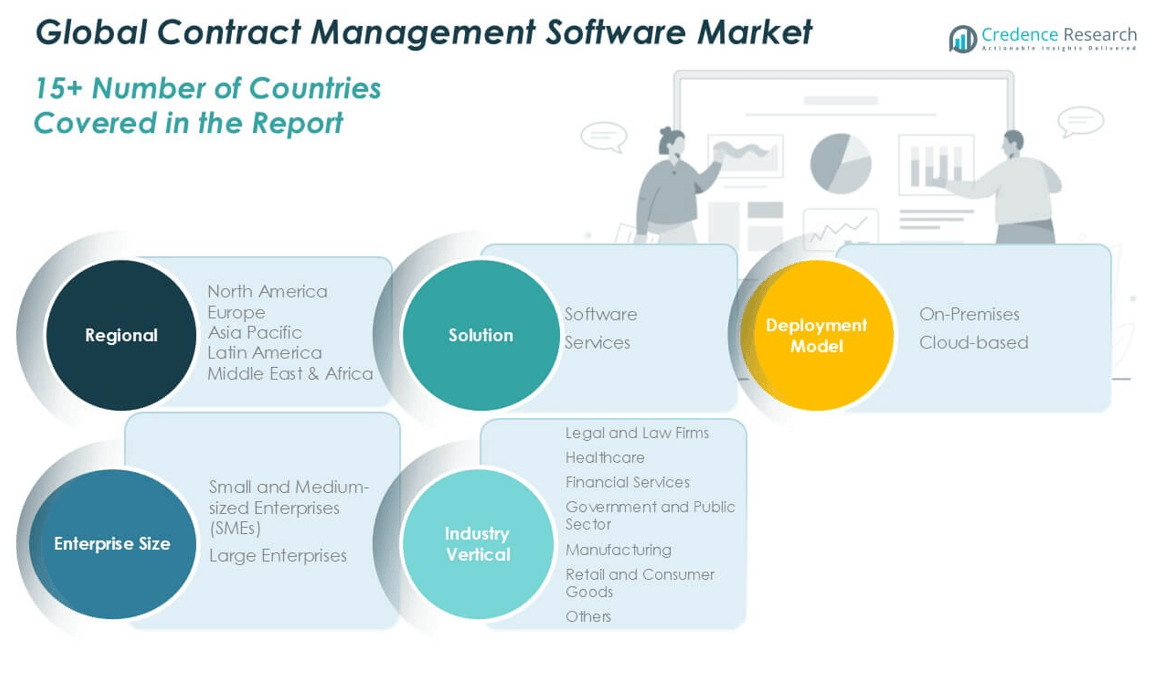
By Solution
- Software
- Services
By Deployment Model
- On-Premises
- Cloud-based
By Enterprise Size
- Small and Medium-sized Enterprises (SMEs)
- Large Enterprises
By Industry Vertical
- Legal and Law Firms
- Healthcare
- Financial Services
- Government and Public Sector
- Manufacturing
- Retail and Consumer Goods
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Contract Management Software market is characterized by intense rivalry among key players striving to expand their market presence through innovation, strategic partnerships, and product enhancements. Leading companies such as SAP, Coupa Software, Infor, ContractWorks, SirionLabs, Zycus, and Agiloft dominate the market by offering comprehensive solutions with advanced features like AI-driven analytics, cloud-based deployment, and seamless integration with enterprise systems. These firms are focused on enhancing user experience, ensuring regulatory compliance, and delivering scalable platforms to cater to diverse industry needs. Mergers, acquisitions, and global expansion remain common strategies to increase footprint and gain access to emerging markets. New entrants and regional players are also leveraging cloud technologies and competitive pricing models to challenge established vendors. As customer expectations evolve, vendors are investing heavily in R&D to maintain a competitive edge, with a strong emphasis on automation, security, and customization to address varied enterprise contract lifecycle management requirements.
- For instance, SirionLabs invested USD 25 million in AI R&D in 2023, filing 12 new patents focused on NLP-based clause risk scoring and intelligent contract negotiation
Key Player Analysis
- SAP
- Coupa Software
- Infor
- ContractWorks
- SirionLabs
- Zycus
- Agiloft
Recent Developments
- In March 2025, Coupa was recognized as a Leader in the Gartner® Magic Quadrant™ for Source-to-Pay Suites, with a strong emphasis on its AI-powered contract lifecycle management (CLM) capabilities.
- In February 2024, Agiloft's CLM platform maintained its market-leading position, lauded for its no-code configurability and expanded Salesforce AppExchange integrations. The platform's AI-powered contract management capabilities were highlighted for streamlining processes and improving efficiency by reducing inconsistencies between internal systems.
- In October 2023, SirionLabs partnered with IBM Watsonx to integrate generative AI into their CLM, enabling contract data extraction, insights, and more advanced analytics for enterprises.
Market Concentration & Characteristics
The Contract Management Software market exhibits moderate to high market concentration, with a few dominant players such as SAP, Coupa Software, Infor, ContractWorks, SirionLabs, Zycus, and Agiloft controlling a significant share of the global revenue. It remains competitive due to the presence of specialized vendors offering niche capabilities and scalable cloud solutions. The market shows strong demand from large enterprises seeking comprehensive platforms to manage complex contract workflows, ensure compliance, and reduce risk. It is characterized by rapid technological advancement, with AI, machine learning, and cloud computing driving product differentiation and functionality. Enterprises prioritize integration with existing ERP and CRM systems, security, and user experience when selecting solutions. While North America holds the largest share due to early digital adoption, Asia Pacific shows the fastest growth, led by increasing awareness and SME adoption. Vendors continue to focus on innovation, customization, and strategic alliances to expand their customer base and address diverse industry needs.
Report Coverage
The research report offers an in-depth analysis based on Solution, Deployment Model, Enterprise Size, Industry Vertical and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to grow steadily, driven by increasing digital transformation across industries.
- Cloud-based deployment models will gain more traction due to their flexibility and lower operational costs.
- AI and machine learning features will become standard components in contract management platforms.
- Small and medium-sized enterprises will adopt contract management solutions at a faster pace.
- Vendors will focus on enhancing integration capabilities with ERP, CRM, and procurement systems.
- Regulatory compliance requirements will drive demand for secure and auditable contract solutions.
- Asia Pacific will emerge as a key growth region due to rising enterprise IT investments.
- User experience and intuitive interfaces will influence purchasing decisions more than feature volume.
- Strategic partnerships and acquisitions will remain critical for market expansion and innovation.
- Industry-specific solutions will gain popularity, especially in healthcare, legal, and public sectors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Workflow Automation and Efficiency
Organizations are increasingly adopting contract management software to automate complex contract workflows, reduce manual intervention, and accelerate contract cycle times. This leads to improved compliance, reduced errors, and greater operational efficiency, especially in sectors with high documentation and regulatory demands.
Cloud-based Deployment and Remote Access
The shift toward cloud-based solutions is driven by the need for scalable, cost-effective platforms that support remote and hybrid work models. Cloud deployment reduces IT infrastructure costs, enables real-time collaboration, and allows businesses of all sizes to access contract data securely from any location.
Regulatory Compliance and Risk Mitigation
Heightened regulatory scrutiny and the complexity of cross-border agreements are pushing enterprises to adopt contract management software that ensures compliance with evolving legal standards. These platforms provide audit trails, standardized templates, and real-time monitoring to help avoid breaches and penalties.
AI and Machine Learning Integration
Vendors are embedding AI and machine learning into contract management platforms to enable smart clause identification, anomaly detection, and predictive risk assessment. These advanced analytics capabilities help organizations extract insights, flag risks, and automate contract review processes, driving adoption among enterprises seeking greater value.
SME Digital Transformation and Emerging Market Adoption
Small and medium-sized enterprises, particularly in emerging economies, are rapidly adopting contract management solutions to replace manual or paper-based processes. Affordable, modular, and user-friendly cloud platforms are making it easier for SMEs to streamline contract lifecycles and improve compliance, fueling market growth in these segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Contract Management Software market?
What factors are driving the growth of the Contract Management Software market?
What are the key segments within the Contract Management Software market?
What are some challenges faced by the Contract Management Software market?
Who are the major players in the Contract Management Software market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Solution
- 1.2.1 Software
- 1.2.2 Services
- 1.3 By Enterprise Size
- 1.3.1 Small and Medium-sized Enterprises (SMEs)
- 1.3.2 Large Enterprises
- 1.4 By Deployment Model
- 1.4.1 On-Premises
- 1.4.2 Cloud-based
- 1.5 By Industry Vertical
- 1.5.1 Legal and Law Firms
- 1.5.2 Healthcare
- 1.5.3 Financial Services
- 1.5.4 Government and Public Sector
- 1.5.5 Manufacturing
- 1.5.6 Retail and Consumer Goods
- 1.5.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,869.40 million → 2032: USD 7,328.25 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Contract Management Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Contract Management Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Contract Management Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Contract Management Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Contract Management Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Contract Management Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Contract Management Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Contract Management Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,869.40 million → 2032: USD 7,328.25 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Contract Management Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Solution - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Software
- 12.3.6.2 Services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Enterprise Size - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Small and Medium-sized Enterprises (SMEs)
- 12.4.6.2 Large Enterprises
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment Model - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 On-Premises
- 12.5.6.2 Cloud-based
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Industry Vertical - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Legal and Law Firms
- 12.6.6.2 Healthcare
- 12.6.6.3 Financial Services
- 12.6.6.4 Government and Public Sector
- 12.6.6.5 Manufacturing
- 12.6.6.6 Retail and Consumer Goods
- 12.6.6.7 Others
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Contract Management Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Contract Management Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Contract Management Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Contract Management Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 SAP
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Coupa Software
- 18.4 Infor
- 18.5 ContractWorks
- 18.6 SirionLabs
- 18.7 Zycus
- 18.8 Agiloft
- 18.9 Icertis
- 18.10 DocuSign
- 18.11 Conga
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

