
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Cooling Management System Market Size 2024 | USD 3652 million |
| Cooling Management System Market, CAGR | 15.3% |
| Cooling Management System Market Size 2032 | USD 11406.83 million |
Market Overview:
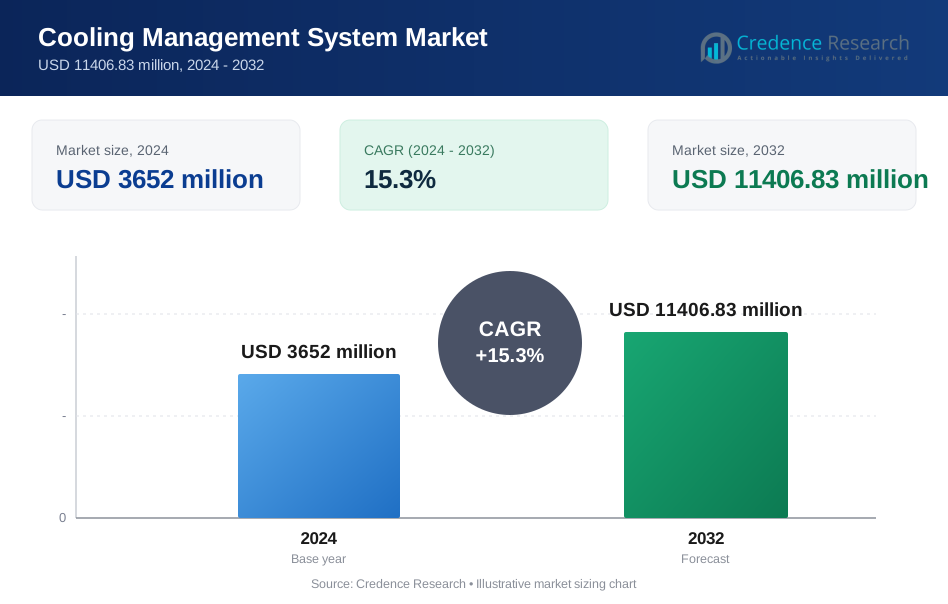
The Cooling Management System Market size was valued at USD 3652 million in 2024 and is anticipated to reach USD 11406.83 million by 2032, at a CAGR of 15.3% during the forecast period (2024-2032).
Key drivers of the Cooling Management System market include the increasing adoption of data centers, which require advanced cooling technologies to handle the rising computational power and energy consumption. As the demand for cloud computing, big data analytics, and artificial intelligence grows, so does the need for reliable and efficient cooling solutions. Additionally, the automotive industry's shift towards electric vehicles (EVs) is propelling demand for efficient thermal management systems, as these systems are crucial for maintaining battery performance and longevity. The integration of electric vehicle charging stations and increased production of electric vehicles globally is expected to further drive market growth. The growing awareness of energy conservation, combined with government regulations promoting sustainable practices, is accelerating the shift toward energy-efficient cooling solutions. Energy-efficient technologies not only reduce operational costs but also contribute to the overall reduction in carbon emissions. Furthermore, advancements in smart technologies, including AI and IoT, are contributing to the development of more optimized, intelligent cooling management systems, enhancing overall system efficiency.
Regionally, North America holds a significant share in the Cooling Management System market, driven by the presence of key players in the technology and data center industries. The United States, in particular, is a major consumer of cooling management solutions, with increasing demand from the data center sector and the automotive industry. Europe represents a key market, driven by robust industrialization and regulations aimed at reducing carbon emissions. The European Union’s stringent energy efficiency standards and sustainability initiatives are expected to promote the adoption of advanced cooling systems in various sectors. In Asia-Pacific, the growing industrial and automotive sectors, particularly in countries like China and India, are expected to drive rapid growth in the cooling management system market. The increasing focus on expanding renewable energy infrastructure in these nations will create new opportunities for market players.
Market Insights:
- The Cooling Management System market is projected to grow significantly, reaching USD 11406.83 million by 2032 from USD 3652 million in 2024.
- The increasing demand for data centers driven by cloud computing, big data, and AI is a key driver of market growth.
- The shift to electric vehicles (EVs) is creating strong demand for efficient thermal management systems to regulate battery performance.
- Rising energy conservation awareness and government regulations are accelerating the adoption of energy-efficient cooling solutions.
- North America holds the largest market share, fueled by the growth of data centers and the automotive sector.
- Europe is seeing increased demand due to strict energy efficiency standards and sustainability initiatives.
- Asia-Pacific is experiencing rapid growth, driven by industrial expansion and the growing adoption of EVs in China and India.
Market Drivers:
Increasing Demand for Data Centers
The rapid expansion of data centers is one of the most significant drivers of the Cooling Management System market. As data centers experience increased demand due to the rise of cloud computing, big data analytics, and artificial intelligence (AI), the need for efficient and reliable cooling systems has become more critical. These facilities, often running 24/7, require advanced thermal management to maintain optimal operating conditions, as rising computational power and energy consumption exacerbate heat generation. For instance, Schneider Electric provides a variety of cooling solutions like precision air conditioning units and modular options that are suited to various data center layouts. Efficient cooling solutions not only enhance operational performance but also help mitigate potential risks such as system failures and equipment damage caused by overheating..
Automotive Industry Shift to Electric Vehicles (EVs)
The transition to electric vehicles (EVs) has also significantly contributed to the rising demand for cooling management systems. EVs require highly efficient thermal management systems to ensure battery performance, longevity, and safety. As the production of electric vehicles accelerates, cooling management systems that regulate the temperature of battery packs and electronic components become crucial. Additionally, the infrastructure for EV charging stations demands thermal management solutions that enhance performance and prevent overheating. For instance, VOSS Automotive provides thermal management solutions that include the design and manufacture of battery cooling systems, line assemblies, and their components for EV markets. As automakers continue to invest in electric vehicle technologies, the market for cooling systems tailored to this sector is poised for considerable growth.
Energy Conservation and Regulatory Compliance
The growing awareness of energy conservation, coupled with strict government regulations promoting sustainable practices, is another driving factor for the Cooling Management System market. Governments worldwide are increasingly mandating energy efficiency standards for industrial and commercial operations, pushing organizations to adopt cooling solutions that reduce energy consumption. These regulations, along with the global push for carbon footprint reduction, encourage companies to explore energy-efficient cooling options that help reduce operating costs while maintaining compliance. For instance, MAHLE develops holistic thermal management solutions for electric vehicles and refines the management of heat flows, which is the foundation for the performance, range, and service life of electric vehicles. Cooling technologies that support energy savings are not only essential for meeting regulatory requirements but also for enhancing operational efficiency.
Advancements in Smart Technologies
Advancements in smart technologies, including artificial intelligence (AI), Internet of Things (IoT), and machine learning, are further driving the growth of the Cooling Management System market. These technologies enable the development of intelligent cooling systems capable of real-time monitoring, predictive maintenance, and system optimization. The ability to predict potential cooling failures or maintenance needs before they occur leads to improved system reliability and lower operational costs. For instance, Fujitsu provides environmentally conscious cooling solutions designed specifically for data centers, emphasizing sustainability with sophisticated algorithms that deliver efficient thermal management and greatly diminish energy consumption. As organizations increasingly look for automated solutions, the demand for such smart cooling technologies is expected to rise, further propelling the market forward.
Market Trends:
Integration of Smart Cooling Technologies
One of the most prominent trends in the Cooling Management System market is the integration of smart technologies, including artificial intelligence (AI) and the Internet of Things (IoT). These technologies allow for the development of advanced, real-time monitoring systems that optimize cooling processes based on specific operational needs. AI-driven systems can adjust cooling parameters automatically, improving efficiency and reducing energy consumption. For instance, HCLTech's Business Gift and Entertainment Policy demonstrates the company's dedication to ethical practices, which can be mirrored in the adoption of transparent and accountable AI-driven cooling systems. IoT-enabled solutions allow for remote monitoring, predictive maintenance, and enhanced fault detection, ensuring continuous, optimized performance of cooling systems.
Sustainability and Energy Efficiency
As industries continue to prioritize sustainability, there is an increasing demand for energy-efficient cooling solutions. For instance, the U.S. Department of Energy launched an initiative in 2021 to support the development of more energy-efficient heat dissipation technologies in industrial applications. Companies are adopting cooling systems that minimize energy consumption while maintaining high performance. This trend is driven by both environmental concerns and government regulations aimed at reducing carbon emissions. Green technologies, such as liquid cooling and evaporative cooling, are becoming more popular due to their ability to reduce energy usage. Moreover, organizations are increasingly focusing on low-carbon cooling systems, which contribute to energy conservation and align with corporate sustainability goals.
Focus on Thermal Management in Electric Vehicles (EVs)
The rise of electric vehicles (EVs) is creating a shift in cooling management technologies, particularly in the automotive industry. EV manufacturers are focusing on improving battery cooling technologies to enhance battery life, charging speed, and safety. Thermal management is critical in EVs, especially in high-performance vehicles, where efficient cooling systems are necessary to ensure optimal operation. For instance, the ARAI (Automotive Research Association of India) is working on the development of new and renewable energy technologies including hydrogen and fuel cells. As EV production increases, innovations in thermal management solutions, such as battery cooling systems and thermal barriers, are expected to become more widespread.
Adoption of Liquid Cooling Systems
There is a growing trend toward the adoption of liquid cooling systems as a more efficient alternative to traditional air-cooled systems. For instance, in July 2024, Airedale by Modine launched the Cooling System Optimizer as a sustainable and secure cooling solution in the U.S. for data centers. Liquid cooling offers superior heat dissipation capabilities and is increasingly used in high-performance applications such as data centers, high-performance computing (HPC), and industrial processes. This trend is driven by the need for more effective cooling solutions that can handle the increasing heat output of modern computing systems and industrial equipment.
Market Challenges Analysis:
High Initial Costs and Infrastructure Complexity
One of the primary challenges in the Cooling Management System market is the high initial cost associated with the implementation of advanced cooling technologies. The installation of state-of-the-art cooling systems, particularly those utilizing liquid cooling or AI-based solutions, often requires significant capital investment. In addition to the upfront cost of equipment, businesses must also invest in the necessary infrastructure to support these systems, including upgraded electrical systems and cooling units. The complexity of integrating these systems into existing facilities, especially in industries with legacy infrastructure, can further increase implementation costs. Small and medium-sized enterprises (SMEs) may find it challenging to justify such significant investments, potentially limiting the widespread adoption of advanced cooling solutions.
Technological Integration and Maintenance
Another challenge faced by the Cooling Management System market is the complexity of technological integration and ongoing maintenance. As businesses increasingly adopt smart technologies, such as AI and IoT for cooling management, ensuring seamless integration with existing systems can be difficult. These advanced systems require specialized expertise for both installation and maintenance, which may not be readily available in all regions. Additionally, while intelligent cooling systems offer enhanced efficiency, they also necessitate continuous monitoring and frequent software updates to ensure optimal performance. Organizations may face challenges in maintaining these systems, especially in remote or underdeveloped areas where technical support is limited. The demand for highly skilled personnel to manage, maintain, and troubleshoot these systems can also strain resources, making long-term system sustainability a challenge for many companies.
Market Opportunities:
The Cooling Management System market presents significant opportunities driven by advancements in technology and the increasing demand for energy-efficient solutions. As industries continue to adopt smart cooling technologies, including AI and IoT, there is an opportunity to develop more optimized, automated systems that reduce operational costs and improve efficiency. The integration of predictive maintenance and real-time monitoring capabilities can help prevent system failures and enhance the overall performance of cooling systems. This presents an opportunity for companies to innovate and introduce cooling solutions that offer both operational and energy savings. Additionally, as industries such as data centers, automotive, and electronics continue to grow, there is a rising need for cooling management systems tailored to meet the specific needs of these sectors, creating new markets for specialized solutions.
Furthermore, the global shift towards sustainability and the increasing focus on energy conservation open up vast opportunities in the market. Government regulations promoting green technologies and low-carbon emissions are pushing businesses to adopt energy-efficient cooling systems, creating demand for innovative solutions that align with regulatory standards. This trend is particularly evident in the automotive sector, where the growth of electric vehicles (EVs) is driving the need for efficient thermal management systems. As the adoption of liquid cooling and other advanced cooling technologies increases, companies that can provide energy-efficient, sustainable solutions stand to capitalize on this growing demand across various industries, expanding their market reach and establishing themselves as leaders in the cooling management space.
Market Segmentation Analysis:
By Type of Cooling The Cooling Management System market is categorized by the type of cooling technology employed, including air cooling, liquid cooling, and evaporative cooling systems. Air cooling systems, being cost-effective and easy to implement, hold the largest market share, particularly in small-scale operations. However, liquid cooling systems are gaining popularity in sectors that demand high-performance cooling, such as data centers and high-performance computing environments, due to their superior heat dissipation efficiency. Evaporative cooling is also emerging as a key solution in industrial applications, driven by its ability to offer an energy-efficient alternative for large-scale cooling needs.
By Solution Type The market is also segmented by solution type, with hardware and software solutions being the primary categories. Hardware solutions include physical cooling units, such as fans, cooling towers, and pumps, and dominate the market due to the demand for reliable, high-performance cooling systems in industries such as automotive, electronics, and data centers. On the other hand, software solutions are increasingly sought after for their ability to optimize cooling management through real-time monitoring, predictive maintenance, and system integration. The adoption of smart cooling technologies is fostering significant growth in this segment, particularly for industries focused on energy efficiency and automation.
By User Type The market also includes segmentation by user type, which encompasses residential, commercial, and industrial users. The industrial sector holds the largest share due to the critical need for cooling systems in large-scale manufacturing processes, power plants, and industrial machinery. As industries continue to scale operations and integrate advanced technologies, the demand for robust cooling management systems is expected to grow substantially.
Segmentations:
By Type of cooling:
- Liquid cooling
- In-row cooling
- Overhead cooling
- Rear door cooling
- In-rack cooling
By Solution type:
- Cooling towers
- Economizers
- Air conditioning
- Servers cooling
- Chillers
By The user type:
- Cloud provider
- Colocation provider
- Enterprises
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the Cooling Management System market, accounting for 35% of the global market. This dominance is driven by the significant presence of major players in the technology and data center industries. The demand for efficient cooling systems is particularly high in the United States, where the expansion of data centers, cloud computing, and high-performance computing systems is intensifying the need for advanced thermal management solutions. Additionally, the automotive sector's transition to electric vehicles (EVs) in North America has created a new avenue for cooling management systems, as effective thermal management is crucial for battery performance and longevity. North America also benefits from high levels of investment in research and development, contributing to the region's leadership in cooling technology innovation.
Europe
Europe holds the second-largest market share, accounting for 28% of the global market. The region's market growth is driven by robust industrialization and stringent environmental regulations aimed at reducing energy consumption and carbon emissions. The European Union's energy efficiency standards and sustainability initiatives encourage the adoption of energy-efficient cooling systems across industries, including data centers, automotive, and manufacturing. Countries like Germany, the UK, and France are witnessing increased demand for cooling management solutions, particularly in industries focused on reducing their carbon footprints and improving operational efficiency. The growing adoption of smart cooling technologies and the move toward liquid cooling further propel the market in this region.
Asia-Pacific
The Asia-Pacific region is experiencing the fastest growth in the Cooling Management System market, capturing 25% of the global market share. This rapid growth is driven by the expansion of industrialization and the rising adoption of electric vehicles (EVs) in countries like China, India, and Japan. As these countries ramp up manufacturing capabilities and the demand for electric vehicles grows, the need for advanced cooling management systems has increased significantly. Additionally, the region’s increasing focus on improving energy efficiency and renewable energy infrastructure creates further opportunities for the adoption of cooling systems that minimize energy consumption. As Asia-Pacific becomes a hub for manufacturing and technological innovation, the demand for sophisticated cooling management solutions continues to rise.
Key Player Analysis:
- Emerson Electric Co.
- Black Box Corporation
- Rittal GmbH Co. KG
- Stulz GmbH
- Vigilant Corporation
- Schneider Electric
- Airedale International Air Conditioning Ltd.
- Siemens AG
- Johnson Controls Inc.
- IT Aire
Competitive Analysis:
The Cooling Management System market is highly competitive, with key players like Emerson Electric Co., Rittal GmbH Co. KG, Schneider Electric, and Siemens AG leading the market. Emerson Electric Co. offers advanced thermal management solutions, focusing on energy efficiency and sustainable technologies, positioning itself as a major player in both industrial and data center sectors. For instance, the U.S. Department of Energy launched an initiative in 2021 to support the development of more energy-efficient heat dissipation technologies in industrial applications. Rittal GmbH Co. KG specializes in integrated cooling solutions, with a strong presence in the industrial and IT infrastructure markets, delivering innovative modular cooling systems. Schneider Electric leads with its energy-efficient, smart cooling solutions, leveraging IoT and AI for optimized thermal management. Siemens AG also plays a significant role by providing comprehensive cooling systems for industrial and automotive applications, enhancing operational efficiency through automation and smart technologies. These companies continue to innovate to stay ahead in a rapidly evolving market.
Recent Developments:
- In December 2024, Schneider Electric is collaborating with Nvidia to create designs for data center cooling systems, which will be used in data centers using Nvidia's flagship server containing 72 of its most powerful AI chips.
- In November 2023, Vertiv unveiled the Smart Max CW, a prefabricated modular data center, to meet the rising demand for rapid computing deployment.
- In 2024, Black Box Corporation specializes in data infrastructure and networking services, excelling in precision cooling solutions for data centers.
- In September 2023, Johnson Controls unveiled Cooling as a Service (CaaS), a solution covering the entire cooling lifecycle from equipment upgrade to ongoing operation, service, and maintenance. It is a pay-per-use model where customers pay only for what they use.
Market Concentration & Characteristics:
The Cooling Management System market exhibits moderate to high concentration, with key players such as Emerson Electric Co., Rittal GmbH Co. KG, Schneider Electric, and Siemens AG dominating the market. These companies hold substantial market share due to their extensive product portfolios, technological innovation, and strong industry presence across multiple sectors, including data centers, automotive, and industrial manufacturing. The market is characterized by a high level of competition, with companies focusing on advancing energy-efficient, smart cooling technologies and integrating IoT and AI capabilities into their systems. The presence of large multinational players also leads to significant R&D investments aimed at developing sustainable and cost-effective solutions. As a result, the market is driven by continuous innovation, with established companies striving to maintain their competitive edge through product differentiation and enhanced system efficiency.
Report Coverage:
The research report offers an in-depth analysis based on Type of Cooling, Solution Type, User-Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for energy-efficient cooling solutions will continue to rise as industries focus on reducing operational costs and meeting sustainability goals.
- Smart cooling technologies, integrating AI and IoT, will play a key role in optimizing system performance and minimizing energy consumption.
- Liquid cooling systems will gain prominence, particularly in data centers and high-performance computing applications, due to their superior heat dissipation capabilities.
- As electric vehicles (EVs) become more prevalent, the need for efficient thermal management systems in the automotive sector will drive innovation in cooling technologies.
- Regulatory pressures to reduce carbon emissions and improve energy efficiency will encourage the adoption of advanced cooling solutions across various industries.
- The demand for modular cooling systems will grow as companies seek scalable, customizable solutions for diverse applications.
- Data centers will remain a dominant driver, with growing infrastructure requirements fueled by cloud computing, AI, and big data analytics.
- The Asia-Pacific region will see rapid growth due to industrialization and increasing adoption of cooling systems in manufacturing and automotive sectors.
- AI-powered predictive maintenance will become a standard feature, reducing downtime and improving system reliability.
- The market will witness increased competition, with companies striving for differentiation through technological advancements and sustainable solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Data Centers and Cloud Computing
The proliferation of data centers to support cloud computing, big data analytics, and AI applications is driving demand for advanced cooling management systems that can efficiently handle high heat loads and ensure system reliability.
Growth of Electric Vehicles (EVs) and Charging Infrastructure
The automotive industry's shift toward electric vehicles is increasing the need for sophisticated thermal management systems to maintain battery performance, safety, and longevity, as well as for cooling solutions in EV charging stations.
Regulatory Push for Energy Efficiency and Sustainability
Stringent government regulations and sustainability initiatives are compelling organizations to adopt energy-efficient cooling solutions, reducing operational costs and supporting global efforts to lower carbon emissions.
Advancements in Smart and Automated Cooling Technologies
The integration of AI, IoT, and machine learning into cooling management systems enables real-time monitoring, predictive maintenance, and system optimization, enhancing efficiency and reducing downtime.
Industrialization and Infrastructure Growth in Emerging Markets
Rapid industrial expansion and infrastructure development in regions like Asia-Pacific are fueling the adoption of modern cooling management systems across manufacturing, automotive, and technology sectors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Cooling Management System market in 2024?
What are the key drivers of market growth?
Which regions are driving the growth of the Cooling Management System market?
How are smart technologies impacting the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By User Type
- 1.2.1 Cloud provider
- 1.2.2 Colocation provider
- 1.2.3 Enterprises
- 1.3 By Solution Type
- 1.3.1 Cooling towers
- 1.3.2 Economizers
- 1.3.3 Air conditioning
- 1.3.4 Servers cooling
- 1.3.5 Chillers
- 1.4 By Type of Cooling
- 1.4.1 Liquid cooling
- 1.4.2 In-row cooling
- 1.4.3 Overhead cooling
- 1.4.4 Rear door cooling
- 1.4.5 In-rack cooling
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3652 million → 2032: USD 11406.83 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cooling Management System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cooling Management System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cooling Management System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cooling Management System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cooling Management System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cooling Management System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cooling Management System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cooling Management System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3652 million → 2032: USD 11406.83 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cooling Management System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By User Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cloud provider
- 12.3.7.2 Colocation provider
- 12.3.7.3 Enterprises
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Solution Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cooling towers
- 12.4.7.2 Economizers
- 12.4.7.3 Air conditioning
- 12.4.7.4 Servers cooling
- 12.4.7.5 Chillers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of Cooling - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Liquid cooling
- 12.5.7.2 In-row cooling
- 12.5.7.3 Overhead cooling
- 12.5.7.4 Rear door cooling
- 12.5.7.5 In-rack cooling
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cooling Management System Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cooling Management System Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cooling Management System Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Emerson Electric Co.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Black Box Corporation
- 17.4 Rittal GmbH Co. KG
- 17.5 Stulz GmbH
- 17.6 Vigilant Corporation
- 17.7 Schneider Electric
- 17.8 Airedale International Air Conditioning Ltd.
- 17.9 Siemens AG
- 17.10 Johnson Controls Inc.
- 17.11 IT Aire
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

