
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Canada Multimode Dark Fiber Market Size 2024 | USD 100.79 million |
| Canada Multimode Dark Fiber Market, CAGR | 6.03% |
| Canada Multimode Dark Fiber Market Size 2032 | USD 160.97 million |
Market Overview
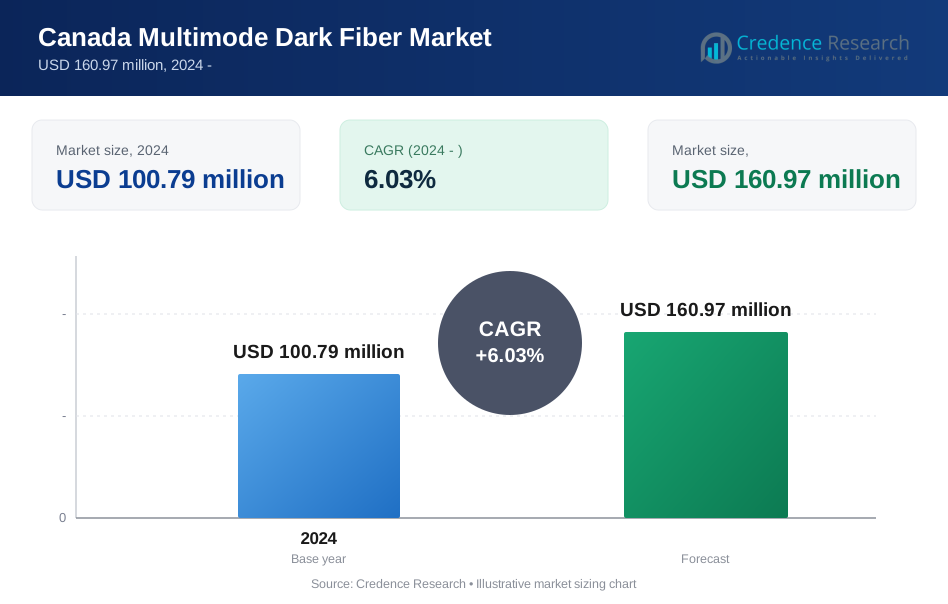
The Canada Multimode Dark Fiber Market is projected to grow from USD 100.79 million in 2024 to an estimated USD 160.97 million by 2032, with a compound annual growth rate (CAGR) of 6.03% from 2025 to 2032. This growth is driven by increasing demand for high-speed data transmission, expansion of data centers, and the proliferation of cloud-based services across various industries.
Key drivers propelling the market include the rising adoption of cloud computing, the surge in internet bandwidth requirements, and the deployment of 5G networks. Additionally, government initiatives aimed at enhancing digital infrastructure and promoting broadband connectivity are fostering market growth. The trend towards virtualization and the need for scalable network solutions are further augmenting the demand for multimode dark fiber.
Geographically, urban centers such as Toronto, Vancouver, and Montreal are witnessing substantial investments in dark fiber infrastructure to support the growing data traffic. Leading players in the Canadian market include Bell Canada, Rogers Communications, Shaw Communications, and Zayo Group Holdings, Inc., all of which are actively expanding their dark fiber offerings to cater to the escalating needs of enterprises and service providers across the country
Market Insights
- The Canada Multimode Dark Fiber Market is projected to grow from USD 100.79 million in 2024 to USD 160.97 million by 2032, at a CAGR of 6.03% from 2025 to 2032.
- The global multimode dark fiber market is expected to grow from USD 3,652.64 million in 2024 to USD 6,242.00 million by 2032, with a CAGR of 6.93% from 2025 to 2032.
- The increasing reliance on cloud computing, 5G networks, and higher internet bandwidth demands are driving the adoption of multimode dark fiber.
- The proliferation of data centers, particularly in urban hubs like Toronto and Vancouver, is pushing the demand for reliable, high-capacity fiber infrastructure.
- Multimode dark fiber is constrained by its relatively short transmission distance, making it less suitable for long-haul networks compared to single-mode fiber.
- The upfront capital required for fiber installation, including infrastructure development and permits, can be a significant barrier for smaller players.
- Eastern Canada, particularly Ontario and Quebec, leads the market due to its strong economic activity, urban development, and telecom infrastructure investments.
- Western Canada, driven by regions like British Columbia and Alberta, sees increasing demand for multimode dark fiber to support expanding telecom networks and industrial sectors.
Market Drivers
Growing Demand for High-Speed and High-Bandwidth Connectivity
The increasing reliance on high-speed internet services across business, government, and residential sectors is a key driver of the Canada Multimode Dark Fiber Market. As enterprises adopt digital-first strategies, data consumption has surged due to advancements in cloud computing, big data analytics, IoT applications, and remote working environments. Multimode dark fiber, known for supporting high data transmission over shorter distances at lower costs compared to single-mode fiber, is becoming the preferred choice for intra-building or intra-campus network solutions. This trend is particularly evident in industries such as finance, healthcare, education, and media, where uninterrupted data flow and minimal latency are critical. Additionally, the growing adoption of 4K and 8K video content, virtual conferencing, and interactive media underscores the need for infrastructure capable of handling larger data volumes. For instance, industries prioritizing uninterrupted data flow are increasingly integrating multimode dark fiber into their network architecture, positioning it as a vital component of Canada's evolving digital ecosystem.
Rapid Data Center Expansion and Cloud Adoption
The rapid growth of cloud computing and the corresponding demand for data center infrastructure are significantly shaping the dark fiber market in Canada. Hyperscale data centers and colocation providers are increasingly deploying multimode dark fiber to connect facilities within campuses and link core switches and servers internally. Cloud service providers require robust and scalable connectivity solutions to ensure secure and low-latency access to applications and data. Multimode fiber is particularly suited for short-range environments, offering an economical and efficient solution for high-density network setups. Furthermore, as businesses transition to cloud platforms, the demand for secure, dedicated, and high-bandwidth connections has intensified. Dark fiber enables organizations to lease unused fiber optic lines to create private, high-capacity connections between their data hubs. For instance, cloud service providers often rely on multimode dark fiber for intra-campus connectivity to enhance network performance, resilience, and security.
Supportive Government Initiatives and Smart City Projects
Federal and provincial governments in Canada are investing heavily in broadband expansion projects, smart city development, and digital infrastructure upgrades. Programs such as the Universal Broadband Fund (UBF) and the Connect to Innovate initiative are specifically designed to extend high-speed internet services to underserved and remote communities. These government-backed efforts often require high-capacity fiber infrastructure to connect public institutions, schools, healthcare facilities, and municipal networks. Multimode dark fiber, being cost-effective and relatively easy to deploy for short distances, plays a crucial role in building the underlying network for smart city applications such as intelligent traffic management, public safety systems, smart lighting, and environmental monitoring. Additionally, the emphasis on digital equity and inclusion underpins the push to extend broadband infrastructure, opening up new revenue streams for telecom providers and dark fiber network developers.
Advancement of 5G Infrastructure and Edge Computing
The deployment of 5G networks across Canada is accelerating, and with it comes an unprecedented demand for robust, low-latency backhaul infrastructure. Multimode dark fiber is instrumental in building the fronthaul and midhaul components of 5G architecture, especially within urban clusters where small cell deployment is dense and geographically concentrated. The low-cost deployment of multimode fiber for these short-range, high-speed links makes it a practical choice for connecting base stations, antennas, and central units. In parallel, the rise of edge computing—where data is processed closer to the source rather than in centralized data centers—necessitates high-capacity local network infrastructure. Multimode dark fiber supports the latency-sensitive and high-throughput requirements of edge computing nodes, which are becoming increasingly important in sectors such as autonomous transportation, manufacturing automation, and augmented reality. As Canada continues to scale its 5G infrastructure and embrace decentralized computing, the demand for flexible and future-ready fiber networks, particularly multimode dark fiber, will continue to grow.
Market Trends
Rise of Private Optical Networks Among Enterprises
One of the most notable trends in the Canada Multimode Dark Fiber Market is the increasing adoption of private optical networks by enterprises. Businesses across sectors—including finance, education, healthcare, and media—are seeking secure, high-capacity, and scalable network infrastructures to meet growing bandwidth requirements. Rather than relying solely on shared public internet services, many organizations are now leasing dark fiber to build private networks, offering greater control, lower latency, and enhanced data security. For instance, multimode dark fiber is particularly favored for short-distance networking within campuses, data centers, and business parks. It allows organizations to future-proof their infrastructure by enabling upgrades to higher transmission technologies without replacing the fiber itself. With increasing concerns about data privacy, cybersecurity, and uninterrupted digital operations, private fiber networks provide a cost-effective solution for ensuring business continuity and operational excellence.
Integration of Multimode Fiber with Data Center Interconnect (DCI) Solutions
The demand for Data Center Interconnect (DCI) solutions is rising in Canada, fueled by the proliferation of cloud services and the need for real-time data replication across geographically distributed facilities. For instance, multimode dark fiber is emerging as a key enabler for short-distance DCI, especially within campus-style data centers and urban colocation hubs. These environments require high-throughput, low-latency fiber links to ensure synchronization, redundancy, and fast workload mobility. Multimode fiber is being deployed between racks, rooms, and adjacent facilities to support optical transport technologies that offer high-speed data movement over shorter ranges. As Canadian organizations increasingly adopt hybrid IT environments—combining on-premise infrastructure with public and private cloud services—the need for agile and scalable interconnectivity is growing. This trend is expected to continue as enterprises demand greater performance from their IT backbones, pushing data center operators to enhance intra-facility connectivity using cost-efficient multimode dark fiber solutions.
Growing Investment in Smart City Infrastructure
Canada’s ongoing investment in smart city infrastructure is contributing significantly to the growth of multimode dark fiber deployments. Municipalities are modernizing urban infrastructure to enable intelligent services such as adaptive traffic signals, public safety surveillance, energy-efficient lighting, environmental monitoring, and citizen engagement platforms. These services depend heavily on a robust and high-speed communication backbone. Multimode dark fiber, with its ability to support high-capacity data transmission over short distances, is becoming a preferred choice for connecting various elements of smart city ecosystems. In dense urban settings, where connectivity is needed across short but frequent intervals—such as between traffic control units, smart poles, and security cameras—multimode fiber offers an economical and easily implementable solution. Additionally, government-backed projects and public-private partnerships are accelerating fiber network expansion in key Canadian cities, reinforcing this trend. With the integration of 5G, IoT, and AI into urban systems, the need for resilient, scalable, and secure data infrastructure is becoming more urgent, driving municipalities to adopt dark fiber as the foundational layer of smart city development.
Shift Toward High-Density Multimode Connectivity in Edge Computing
Edge computing is redefining the data processing paradigm by bringing computation and storage closer to data sources, thereby reducing latency and enhancing real-time processing capabilities. This shift is driving the need for localized, high-density fiber networks, particularly in sectors like manufacturing, healthcare, autonomous transportation, and retail. Multimode dark fiber is playing a crucial role in enabling these localized networks, especially within confined environments where the distance between devices and edge nodes is limited. Its lower cost and ease of deployment make it ideal for connecting edge computing infrastructure such as micro data centers, network access points, and IoT hubs. In Canada, where urbanization and the adoption of Industry 4.0 technologies are accelerating, this trend is gaining momentum. Organizations are deploying edge solutions to improve responsiveness, reduce bandwidth costs, and support mission-critical applications. As a result, multimode dark fiber is witnessing increased usage in edge computing architectures, strengthening its presence in the Canadian connectivity landscape.
Market Challenges
Limited Long-Distance Transmission Capability and Technological Constraints
The challenges in the Canada Multimode Dark Fiber Market are indeed significant. Multimode fiber's limited transmission distance, typically up to a few hundred meters depending on speed and fiber type, restricts its use in scenarios requiring long-distance data transmission. For instance, this makes it less viable for national networks, rural deployments, and inter-city communication without the addition of costly repeaters or signal boosters. Furthermore, while multimode fiber is effective for lower bandwidth needs in confined spaces, it struggles to meet the growing demand for higher transmission speeds like 40G, 100G, and 400G. Compatibility issues with emerging high-speed optical transceivers, which are often optimized for single-mode fibers, further exacerbate these challenges. These limitations hinder the scalability of multimode dark fiber networks, particularly in advanced applications such as AI-based data processing, high-performance computing, and ultra-low latency environments. As Canadian enterprises increasingly digitize, the performance gap between multimode and single-mode solutions could pose a barrier to the broader adoption of multimode dark fiber in high-demand settings.
High Initial Capital Expenditure and Complex Deployment Procedures
Despite its cost-efficiency in operation, the initial deployment of multimode dark fiber networks involves substantial capital investment. Laying fiber-optic cables requires specialized labor, right-of-way permissions, and extensive infrastructure planning. In urban areas, existing underground utilities and dense construction can complicate installation, driving up deployment timelines and expenses. Meanwhile, in remote or rural regions, the lack of pre-existing fiber infrastructure further increases the financial burden and logistical challenges. These factors make it difficult for small and mid-sized enterprises (SMEs) and new market entrants to justify or afford the upfront costs associated with dark fiber projects. Moreover, the technical complexity of integrating dark fiber with existing network architectures requires advanced engineering expertise and network management capabilities. Fiber splicing, connector compatibility, and the calibration of optical equipment must be executed with precision to ensure optimal performance. These technical and financial barriers slow the pace of market penetration, particularly among organizations that lack the resources or strategic incentives to build private fiber networks. As a result, despite its long-term benefits, the adoption of multimode dark fiber remains constrained by the high capital and operational hurdles in its early deployment stages.
Market Opportunities
Rising Demand for Scalable Connectivity in Urban Infrastructure and Enterprise Networks
As Canadian cities embrace digital transformation through smart infrastructure, the demand for scalable, high-bandwidth connectivity solutions is expected to rise significantly. Multimode dark fiber offers a cost-effective alternative for high-speed data transmission across short distances, making it ideal for intra-building links, campus networks, and localized data center interconnects. Enterprises operating in sectors such as finance, healthcare, education, and media are increasingly seeking dedicated fiber infrastructure to support growing bandwidth requirements, data security, and real-time operations. This presents a strategic opportunity for service providers and infrastructure developers to offer customized dark fiber solutions tailored to dense urban environments and high-traffic commercial zones.
Expansion of 5G and Edge Computing Creating Fiber-Backhaul Opportunities
Canada’s ongoing 5G rollout and the rapid proliferation of edge computing are creating substantial backhaul infrastructure needs—particularly in metro areas where dense small cell deployments are required. Multimode dark fiber can serve as an essential component for short-range, high-speed connections between 5G radio units, edge data centers, and core networks. As mobile operators and enterprises invest in decentralized computing environments to enhance responsiveness and minimize latency, there is a growing opportunity for multimode fiber deployment in supporting localized data aggregation and processing. Providers capable of delivering reliable and scalable multimode dark fiber networks will be well-positioned to capture market share within this evolving digital infrastructure landscape, especially in support of advanced applications such as IoT, autonomous vehicles, and real-time analytics.
Market Segmentation Analysis
By Fiber Type
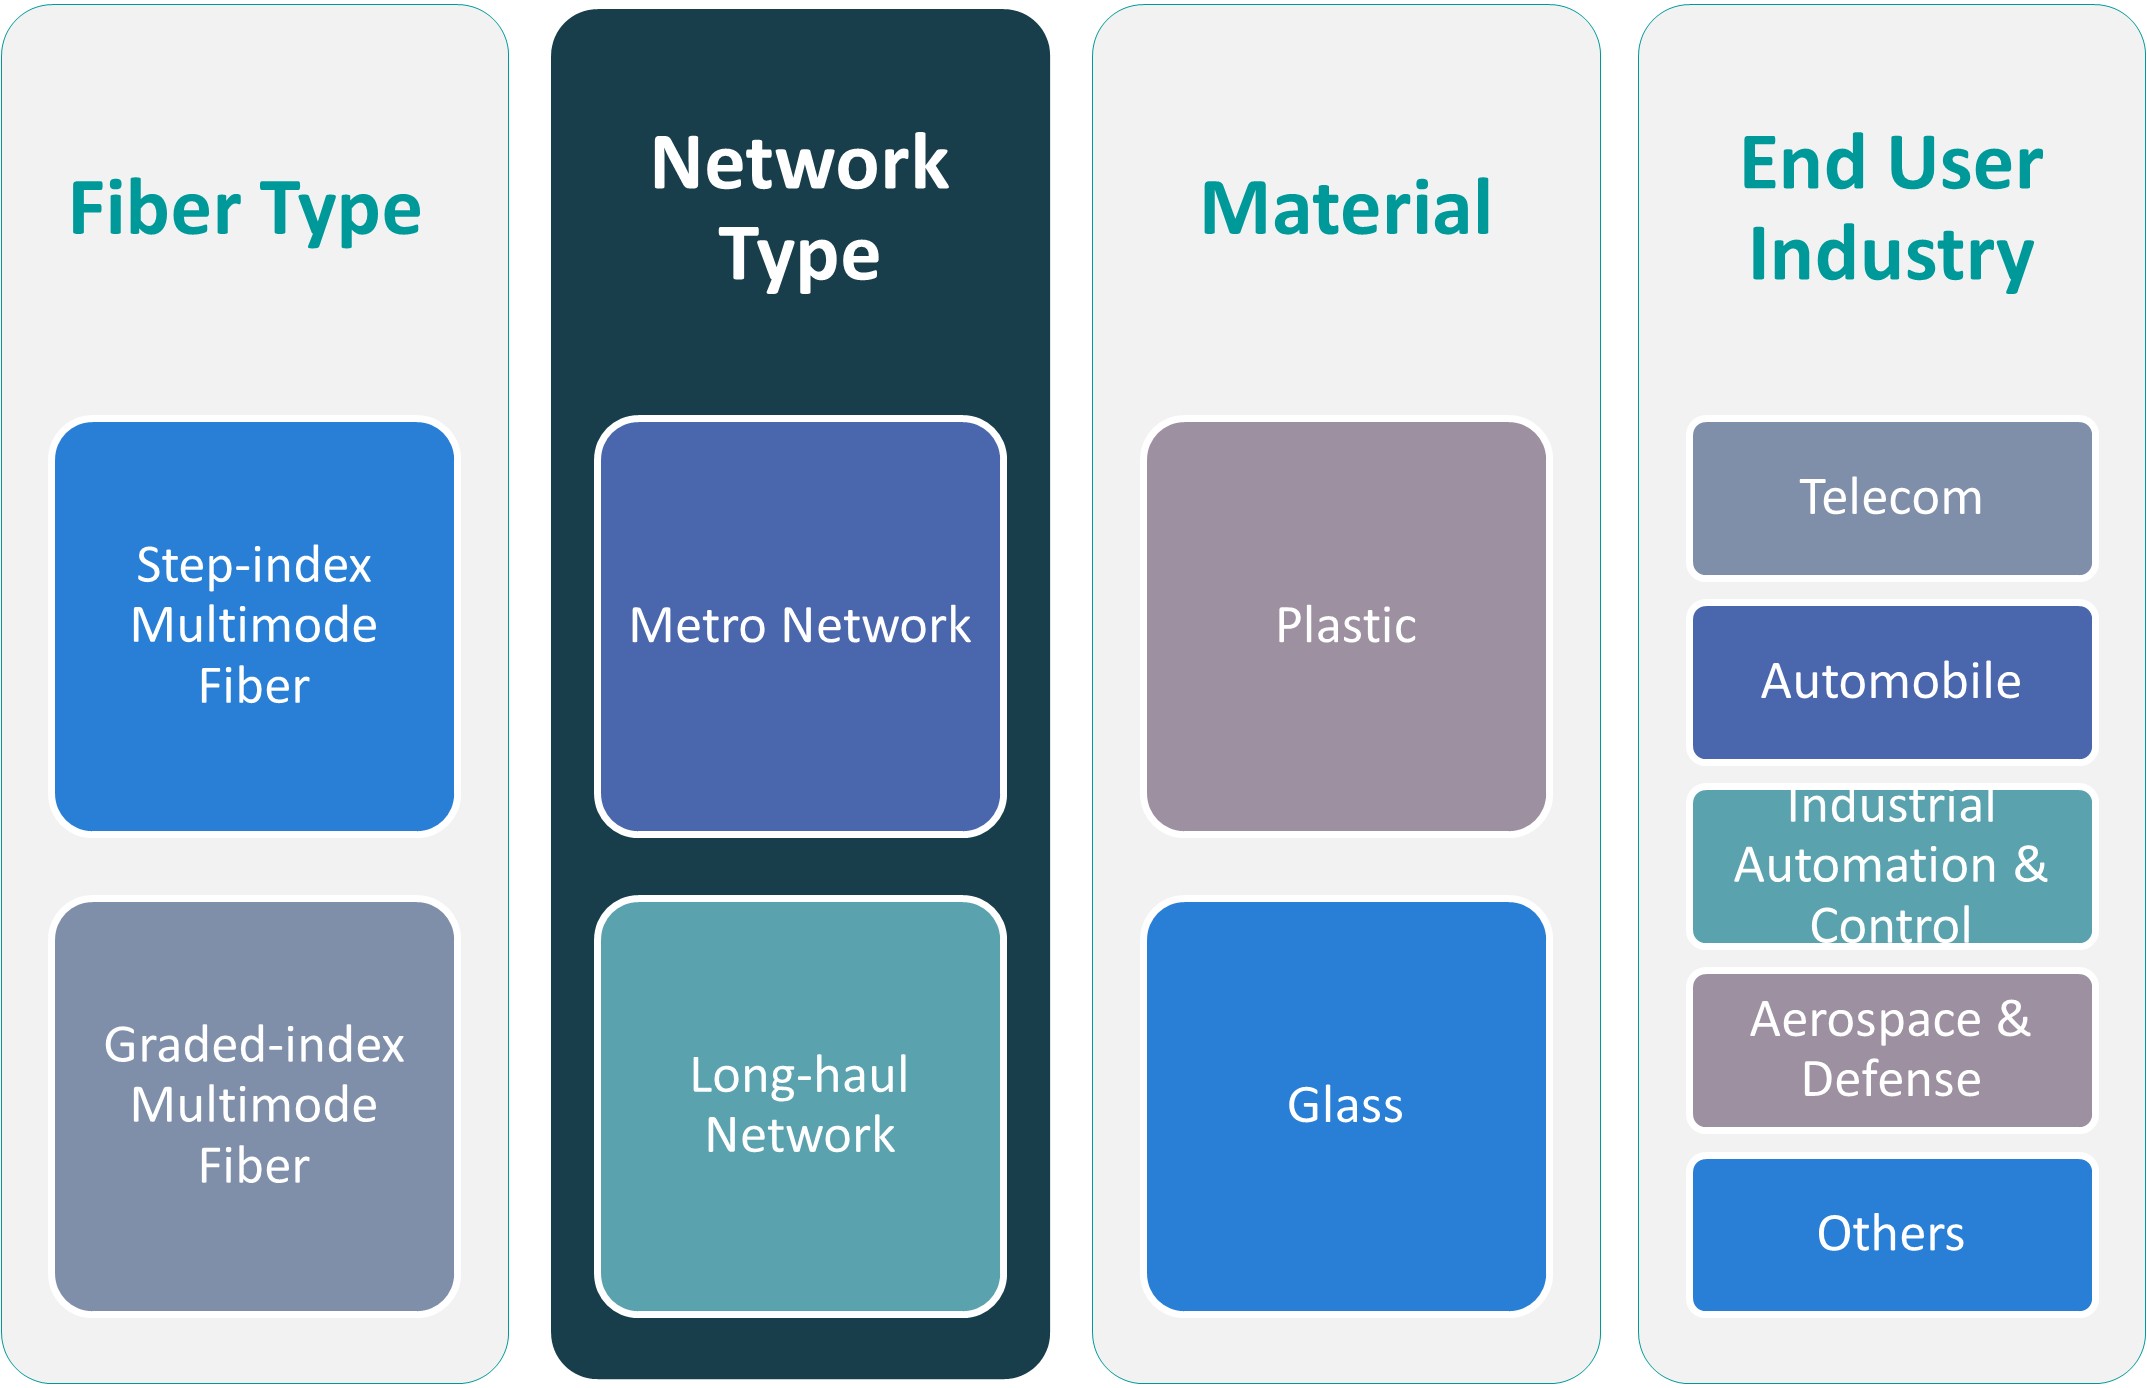
The market is bifurcated into Step-index Multimode Fiber and Graded-index Multimode Fiber. Step-index fiber, while cost-effective, offers limited bandwidth and distance capabilities, making it suitable for simple, low-data-rate applications. Graded-index fiber, on the other hand, dominates the segment due to its superior performance in minimizing modal dispersion, enabling higher transmission speeds over longer distances within multimode parameters. It is widely adopted in campus networks, data centers, and enterprise LANs, where both cost efficiency and high data throughput are critical.
By Network Type
The market is segmented into Metro Network and Long-haul Network. Metro networks represent a significant share, fueled by the growing demand for high-speed connectivity in urban areas and the deployment of data centers and smart city projects. While multimode fiber is inherently suited for shorter distances, it finds considerable use in metro infrastructure due to its cost-effectiveness and high bandwidth. Long-haul networks typically rely more on single-mode fiber, but multimode is still relevant in the last-mile and intra-node connections within the long-haul ecosystem
Segments
Based on Fiber Type
- Step-index Multimode Fiber
- Graded-index Multimode Fiber
Based on Network Type
- Metro Network
- Long-haul Network
Based on Material Type
- Plastic
- Glass
Based on End User
- Telecom
- Automobile
- Industrial Automation & Control
- Aerospace & Defense
- Others
Based on Region
- Ontario
- Quebec
- British Columbia
Regional Analysis
Eastern Canada (45%)
Eastern Canada, encompassing Ontario and Quebec, leads the multimode dark fiber market with approximately 45% of the national share. This dominance is attributed to the region's robust economic landscape, housing major urban centers like Toronto and Montreal, which are hubs for finance, technology, and education. The high concentration of data centers, corporate headquarters, and research institutions drives the demand for high-speed, low-latency connectivity solutions. Moreover, ongoing investments in expanding metro and long-haul networks further bolster the region's market position.
Western Canada (35%)
Western Canada, including provinces such as British Columbia and Alberta, holds approximately 35% of the market share. Cities like Vancouver and Calgary are experiencing a surge in demand for advanced network infrastructure to support their growing technology sectors. British Columbia, for instance, boasts one of the highest rates of broadband internet adoption in the country. Additionally, Alberta's oil and gas industry necessitates reliable, high-capacity communication networks for remote operations, contributing to the region's substantial share in the dark fiber market.
Key players
- Bell Canada Enterprises
- Telus Communications
- Rogers Communications
- Shaw Communications
- Hydro On
Competitive Analysis
The Canada Multimode Dark Fiber Market features a competitive landscape dominated by leading telecom and utility providers. Bell Canada Enterprises holds a significant market position, leveraging its expansive infrastructure, diverse service portfolio, and consistent investment in fiber network expansion. Telus Communications and Rogers Communications also maintain robust market presence, supported by their focus on advanced connectivity solutions and strategic deployment in high-demand urban zones. Shaw Communications has established itself strongly in Western Canada, benefiting from its regional market strength and consumer base. Hydro One, primarily known for its electricity transmission operations, is entering the telecommunications sector by utilizing its existing infrastructure to offer fiber-based services, creating additional competitive pressure. These companies are intensifying efforts to differentiate through network reliability, data security, and regional reach, while also responding to evolving customer needs by integrating scalable, low-latency fiber solutions suitable for cloud services, 5G, and smart infrastructure applications.
Recent Developments
- In June 2024, Telstra InfraCo's intercity fiber network project completed approximately 1,800 kilometers of fiber construction, enhancing connectivity across Australia.
- As of June 2023, TPG Group held a wholesale market share of around 22% of Australian National Broadband Network services.
- As of June 2023, Optus had a wholesale market share of approximately 13% of Australian National Broadband Network residential broadband services.
- In August 2024, Lumen Technologies entered a two-year agreement with Corning Incorporated, securing 10% of Corning’s global fiber capacity to interconnect AI-enabled data centers. This deal is Lumen’s largest cable purchase to date and will more than double its U.S. intercity fiber miles, enhancing capacity for cloud data centers and high-bandwidth applications driven by AI workloads.
- In February 2025, Deutsche Telekom praised T-Systems for its improved performance in FY24, reflecting the company's strategic focus on enhancing its dark fiber services for enterprise customers.
- In December 2024, the GCC Sustainability Innovation Hub, which includes Etisalat, released a white paper outlining pathways for telecom operators to achieve net-zero emissions, drive renewable adoption, and foster regional collaboration.
- In 2024, Claro Argentina reported an operating profit of 706 billion pesos, a 10.1% growth compared to 2023, indicating strong performance in its telecom operations, including dark fiber services.
Market Concentration and Characteristics
The Canada Multimode Dark Fiber Market exhibits a moderately concentrated structure, dominated by a few major telecom providers such as Bell Canada, Telus, Rogers, and Shaw Communications. These key players control a substantial portion of the fiber infrastructure, leveraging their extensive network assets, financial strength, and customer base to maintain competitive advantages. The market is characterized by high capital intensity, strategic metro-area deployments, and a strong focus on enterprise and data center connectivity. Multimode dark fiber is primarily deployed in short-distance, high-capacity environments such as urban campuses, intra-facility links, and localized network backbones. Market dynamics are shaped by increasing demand for low-latency, high-bandwidth services, government-supported broadband initiatives, and the growing role of cloud computing and 5G networks. Although entry barriers remain high due to infrastructure costs and regulatory considerations, opportunities exist for niche providers and public-private partnerships targeting underserved regions and specialized applications.
Report Coverage
The research report offers an in-depth analysis based on Fiber Type, Network Type, Material Type, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The increasing reliance on cloud services across various sectors will continue to drive the demand for high-speed, reliable multimode dark fiber solutions. As businesses adopt hybrid IT models, fiber infrastructure will be crucial for data transmission.
- The ongoing deployment of 5G infrastructure in Canada is expected to fuel the need for fiber-optic connectivity, including multimode dark fiber, to support small cell backhaul and high-capacity network needs.
- Edge computing’s growth, driven by low-latency requirements for applications like IoT and autonomous vehicles, will create substantial demand for localized fiber infrastructure. Multimode dark fiber will be key in enabling edge data centers.
- The growing number of smart city projects across Canada will enhance the demand for efficient and high-capacity data transmission systems. Multimode fiber’s role in supporting these projects will expand as urban infrastructure becomes increasingly digital.
- Telecom providers will continue investing in fiber optic networks to meet the increasing bandwidth requirements of consumers and enterprises. This trend will enhance the adoption of multimode dark fiber solutions in urban and suburban areas.
- Government initiatives aimed at improving broadband access in rural and underserved areas will likely lead to a rise in the deployment of dark fiber infrastructure, increasing the market footprint in these regions.
- As data security remains a top priority, businesses will increasingly turn to private fiber networks. The use of multimode dark fiber will expand as a secure, dedicated solution for sensitive data transmission.
- The rapid integration of AI and IoT technologies will create demand for high-speed fiber infrastructure capable of handling massive data volumes. Multimode dark fiber will play a critical role in supporting these technologies.
- Collaborations between public institutions and private companies will accelerate the development of national fiber networks. This partnership will drive the widespread availability of multimode dark fiber, especially in underserved regions.
- Ongoing advancements in fiber optics and networking technologies will drive improvements in multimode dark fiber solutions, offering enhanced performance and cost-efficiency for enterprises and telecom providers alike.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Canada Multimode Dark Fiber Market in 2023 and 2032?
What are the key drivers of the Canada Multimode Dark Fiber Market?
What are the benefits of using multimode dark fiber?
Who are the key players in the Canada Multimode Dark Fiber Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Canada Multimode Dark Fiber Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Canada Multimode Dark Fiber Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 100.79 million → forecast year: USD 160.97 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Canada Multimode Dark Fiber Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Canada Multimode Dark Fiber Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Canada Multimode Dark Fiber Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Canada Multimode Dark Fiber Market Drivers
- 3.3 Canada Multimode Dark Fiber Market Restraints & Challenges
- 3.4 Canada Multimode Dark Fiber Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Canada Multimode Dark Fiber Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Canada Multimode Dark Fiber Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Canada Multimode Dark Fiber category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Canada Multimode Dark Fiber Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Canada Multimode Dark Fiber Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Canada Multimode Dark Fiber market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Canada Multimode Dark Fiber Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Canada Multimode Dark Fiber Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Canada Multimode Dark Fiber Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Canada Multimode Dark Fiber (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Canada Multimode Dark Fiber Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Canada Multimode Dark Fiber Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Canada Multimode Dark Fiber Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Canada Multimode Dark Fiber Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Canada Multimode Dark Fiber Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Canada Multimode Dark Fiber Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Canada Multimode Dark Fiber Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Canada Multimode Dark Fiber Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Canada Multimode Dark Fiber Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
