
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Data Centric Security Market Size 2024 | USD 7,359 Million |
| Data Centric Security Market, CAGR | 23% |
| Data Centric Security Market Size 2032 | USD 38,553.13 Million |
Market Overview:
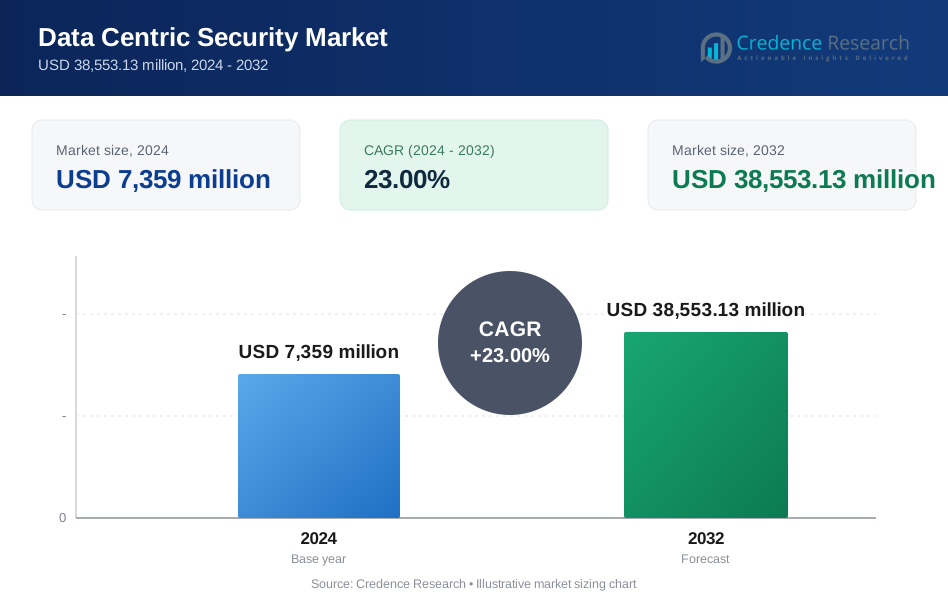
The Data Centric Security Market is projected to grow from USD 7,359 million in 2024 to USD 38,553.13 million by 2032, with a compound annual growth rate (CAGR) of 23%.
The growth of the Data Centric Security Market is driven by increasing concerns over data privacy, stringent regulatory frameworks like GDPR and CCPA, and the rapid adoption of cloud-based services across industries. As organizations store sensitive data in multiple environments, including on-premises and cloud, the need for advanced security measures to protect data at its source has escalated. The rise in cyber threats, data breaches, and insider attacks further underscores the demand for robust data-centric security solutions. Additionally, growing awareness about the value of data protection, along with advancements in AI-driven security technologies, is fostering market growth. Trends include the integration of encryption, data masking, and access control solutions, as well as a shift towards decentralized data protection strategies. Businesses are prioritizing security solutions that enable real-time data monitoring, classification, and anomaly detection to ensure comprehensive data governance and compliance across hybrid IT environments. These factors collectively contribute to the expansion of the data-centric security market.
The Data Centric Security Market shows diverse growth patterns across regions. North America leads with around 40% market share in 2024, driven by strict data privacy regulations and a high adoption rate of advanced security technologies. Europe follows with approximately 30%, spurred by GDPR and increasing data governance needs in countries like Germany and the UK. Asia Pacific, holding 20% market share, sees rapid growth due to digital transformation and rising cloud adoption in China, India, and Japan. Latin America and the Middle East & Africa account for smaller shares, around 5% each, driven by increasing awareness and government initiatives in cybersecurity. Key players like IBM Corporation, Broadcom, Varonis Systems, and Orange Cyberdefense operate across these regions, driving competition and innovation.
Market Insights:
- The Data Centric Security Market is projected to grow from USD 7,359 million in 2024 to USD 38,553.13 million by 2032, with a CAGR of 23%.
- Increasing concerns over data privacy, stringent regulations like GDPR and CCPA, and rising cyber threats are driving the demand for data-centric security solutions.
- The rapid adoption of cloud services across industries is pushing organizations to protect sensitive data in both on-premises and cloud environments.
- Advancements in AI-driven security technologies are enabling real-time data monitoring, anomaly detection, and enhanced data governance.
- Key trends include the integration of encryption, data masking, and access control to protect data throughout its lifecycle.
- North America holds the largest market share of 40% in 2024, followed by Europe with 30% and Asia Pacific with 20%, driven by regulatory requirements and cloud adoption.
- Leading players like IBM, Broadcom, Varonis Systems, and Orange Cyberdefense are driving innovation and competition across the global market.
Market Drivers:
Increasing Data Privacy Concerns and Regulatory Compliance:
A major driver for the Data Centric Security Market is the growing concern over data privacy, fueled by rising incidents of data breaches and unauthorized access. Organizations are increasingly under pressure to protect sensitive information and prevent its misuse. Companies like Symantec and McAfee offer advanced data protection frameworks tailored to meet GDPR and CCPA requirements, helping businesses comply with stringent regulations. These regulations require organizations to implement solutions that ensure data security and privacy, leading to higher demand for data-centric security solutions.
Adoption of Cloud-Based Technologies:
The rapid adoption of cloud computing and other cloud-based services has significantly influenced the need for data-centric security solutions. As enterprises migrate more of their critical operations and data to the cloud, they encounter new challenges in securing distributed and hybrid environments. For instance, Microsoft Azure and AWS offer data-centric security tools to protect cloud-based operations, ensuring consistent levels of security regardless of where the data resides. This shift has driven organizations to adopt data-centric security models that focus on protecting the data itself, rather than the network.
Rise in Cybersecurity Threats:
With the increasing sophistication of cyberattacks, the need for data-centric security solutions has become more pronounced. Organizations across all industries are witnessing a rise in the number and complexity of cyber threats, including ransomware, phishing, and insider threats. For instance, Palo Alto Networks provides solutions that integrate encryption and real-time threat detection to safeguard sensitive data, mitigating risks associated with attacks. These challenges necessitate a proactive approach to safeguarding data, where encryption, data masking, and other advanced measures are essential.
Advancements in AI and Automation Technologies:
The incorporation of artificial intelligence (AI) and automation technologies into security frameworks has also contributed to the growth of the Data Centric Security Market. IBM Security uses AI-powered tools to analyze data anomalies and detect threats in real-time, enabling swift responses to potential breaches. Automation further enhances efficiency by streamlining security operations and ensuring consistent data protection measures across organizational infrastructure.
Market Trends:
Increased Focus on Data Encryption and Masking:
A key trend in the Data Centric Security Market is the growing adoption of data encryption and masking techniques. For instance, IBM offers encryption solutions that secure sensitive data across hybrid environments, ensuring protection from unauthorized access. Encryption ensures that even if data is intercepted, it remains unreadable without the appropriate decryption keys. Data masking further protects sensitive information by substituting real data with fictional values in non-production environments, helping businesses maintain data integrity while complying with regulatory requirements.
Expansion of Cloud-Native Security Solutions:
The shift towards cloud-native security solutions is another prominent trend shaping the market. For instance, Microsoft Azure provides cloud-native tools designed to secure hybrid ecosystems, offering centralized control and real-time monitoring. These solutions allow businesses to implement automated responses to security threats, ensuring data is secure regardless of its location.
Integration of AI and Machine Learning:
Artificial intelligence (AI) and machine learning (ML) technologies are being integrated into data-centric security frameworks to enhance threat detection and response. Palo Alto Networks uses AI to detect anomalies and mitigate risks in real time, enabling proactive threat management. These advanced technologies process large data volumes, identify patterns, and predict potential risks to provide continuous protection.
Adoption of Zero Trust Security Models:
The adoption of zero trust security models is becoming increasingly prevalent in the Data Centric Security Market. Google implements zero trust frameworks that enforce strict user verification, limiting data exposure and mitigating insider threats. This approach continuously validates user identities and applies least-privilege access policies, ensuring sensitive data is protected against advanced cyberattacks.
Market Challenges Analysis:
Complex Implementation and Integration Challenges:
One of the significant challenges in the Data Centric Security Market is the complexity involved in implementing and integrating data-centric security solutions within existing IT infrastructures. Organizations often operate with legacy systems and diverse data environments, which make it difficult to deploy comprehensive security measures across all platforms and maintain consistency in protection. For instance, "organizations use 29 different cloud services on average" according to the 2020 Thales Data Threat Report - Global Edition, highlighting the complexity of modern IT environments. The process of integrating data-centric security tools with various applications, databases, and cloud environments requires extensive customization, testing, and resources to ensure they work seamlessly. Additionally, organizations may lack the technical expertise or experienced personnel needed to manage the complexities of encryption, tokenization, and data masking, leading to operational inefficiencies and increased costs. The complexity of implementation can also result in delays in adoption, especially for small to mid-sized enterprises that may not have the financial resources or technical capabilities to support such advanced solutions. This creates a gap between the market’s potential and the actual deployment of data-centric security measures.
Balancing Data Security with Performance and Usability:
Another challenge facing the Data Centric Security Market is finding the balance between ensuring robust data security and maintaining system performance and usability. Implementing encryption, data masking, and other data protection techniques can sometimes introduce latency and degrade system performance, especially in environments that process large volumes of data in real time. This can be particularly problematic in industries that rely on real-time analytics or high-speed transactions, where delays could result in operational inefficiencies, lost revenue, or degraded customer experiences. Businesses must find ways to optimize data protection mechanisms to reduce any negative impact on system speed or responsiveness. Furthermore, ensuring that security solutions do not interfere with legitimate access to data is critical. Organizations must design and implement security measures that protect sensitive data without hindering authorized users' ability to access the information they need for decision-making, collaboration, or customer service. Achieving this balance remains a key challenge, as businesses need solutions that offer both strong protection and seamless, efficient performance across increasingly complex data ecosystems.
Market Opportunities:
The Data Centric Security Market presents significant opportunities as organizations increasingly prioritize data protection in response to growing regulatory pressures and cyber threats. With stringent compliance requirements like GDPR, CCPA, and other global data protection laws, businesses are seeking more advanced solutions to ensure data privacy and security across complex environments. This demand opens doors for solution providers to offer tailored security services that integrate seamlessly with diverse IT infrastructures. As more companies move toward hybrid and multi-cloud strategies, the need for scalable, cloud-native data security solutions is growing. Vendors that can deliver flexible, cloud-compatible tools for encryption, data masking, and real-time monitoring are well-positioned to capitalize on this trend, especially as cloud adoption continues to rise globally.
The emergence of artificial intelligence (AI) and machine learning (ML) technologies also presents significant opportunities within the Data Centric Security Market. By leveraging AI and ML, security providers can offer more sophisticated solutions capable of real-time threat detection, anomaly identification, and automated response. These intelligent systems can adapt to evolving cyber threats, providing businesses with more robust and proactive data protection. Additionally, the rising importance of zero-trust security models presents an opportunity for companies to deliver solutions that enable organizations to adopt a "trust no one" approach, ensuring that access to sensitive data is continuously monitored and validated. The combination of AI-driven technologies, cloud-native solutions, and zero-trust models offers a vast market potential for companies that can address the growing security needs of businesses in an increasingly digital and data-driven world.
Market Segmentation Analysis:
By Component
The Data Centric Security Market is segmented by component into solutions and services. Solutions include encryption, data masking, and tokenization tools, while services comprise consulting, implementation, and support services. As organizations adopt comprehensive data security strategies, the demand for integrated solutions and specialized services continues to rise, particularly in highly regulated industries.
By Deployment
Deployment models in the Data Centric Security Market are segmented into on-premise and cloud-based solutions. The growing adoption of cloud technologies is driving demand for cloud-native security solutions, offering scalability, flexibility, and cost-effectiveness. However, industries with strict compliance requirements, such as finance and healthcare, continue to prefer on-premise solutions for greater control over sensitive data.
By Enterprise Size
The market is also segmented by enterprise size into small and medium-sized enterprises (SMEs) and large enterprises. Large enterprises dominate market share due to their extensive data protection needs, while SMEs are increasingly adopting data-centric security solutions driven by growing cybersecurity risks and the need to comply with evolving regulatory standards.
Segments:
Based on Component
- Software & Solution
- Data Discovery & Classification
- Data Protection
- Data Governance & Compliance
- Others
- Services
-
- Professional
- Managed
Based on Deployment
- On-premise
- Cloud
Based on Enterprise Size
- Large Enterprises
- SMEs
Based on Industry Vertical
- BFSI
- IT & Telecom
- Government & Defense
- Healthcare
- Retail
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America is expected to hold the largest market share in the Data Centric Security Market in 2024, accounting for 40% of the global market. The region's dominance is attributed to the high adoption of advanced technologies, strict regulatory requirements such as the General Data Protection Regulation (GDPR) and California Consumer Privacy Act (CCPA), and the presence of key market players. The United States, in particular, leads in implementing data-centric security solutions, driven by its large number of data-sensitive industries such as finance, healthcare, and government. Additionally, the increasing number of cyber threats and data breaches in the region has further accelerated the demand for robust data protection measures, making North America a critical hub for innovation and adoption in the data-centric security space.
Europe
Europe is anticipated to capture 30% of the Data Centric Security Market share in 2024, largely due to the stringent data privacy regulations implemented by the European Union, particularly GDPR. European organizations are under considerable pressure to comply with these regulations, which emphasize the protection of personal data. As a result, the region is experiencing strong demand for encryption, data masking, and real-time monitoring solutions. Countries like Germany, France, and the UK are at the forefront of adopting these technologies, especially in industries such as banking, healthcare, and telecommunications. The increasing focus on data governance and the growing frequency of cyberattacks have further driven the adoption of data-centric security solutions across Europe.
Asia Pacific
The Asia Pacific region is projected to account for 20% of the Data Centric Security Market share in 2024. This growth is being fueled by the rapid digital transformation and increasing adoption of cloud services across countries such as China, India, and Japan. As businesses in the region increasingly migrate their data to cloud platforms, the need for data-centric security solutions has intensified. Additionally, government initiatives aimed at enhancing cybersecurity frameworks and data protection regulations, such as India's Personal Data Protection Bill, are pushing organizations to adopt more advanced security measures. While the region is still in the early stages of implementing comprehensive data privacy laws compared to North America and Europe, its increasing focus on cybersecurity presents significant growth opportunities for market players.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa are expected to hold smaller portions of the Data Centric Security Market, with each region capturing 5% of the market share in 2024. In Latin America, the increasing digitalization of businesses and the growing number of cyber threats are driving the need for more comprehensive data security measures. Countries like Brazil and Mexico are leading the region in adopting data-centric security solutions, particularly in finance and government sectors. In the Middle East & Africa, while the market is still in its nascent stages, there is a growing awareness of data security, especially in the wake of increased cyberattacks targeting critical infrastructure. Government initiatives to enhance cybersecurity, along with the rising adoption of cloud-based services, are expected to contribute to market growth in these regions.
Key Player Analysis:
- Orange Cyberdefense
- IBM Corporation
- Egnyte
- Micro Focus
- Varonis Systems
- Netwrix
- Infogix
- Informatica
- Broadcom
- Sophos
- Virtru
Competitive Analysis:
The Data Centric Security Market is highly competitive, with several leading players driving innovation and adoption across various industries. Companies like IBM Corporation, Broadcom, Informatica, Varonis Systems, and Sophos are at the forefront, offering advanced data protection solutions such as encryption, data masking, and real-time threat detection. These organizations differentiate themselves by leveraging artificial intelligence (AI) and machine learning (ML) to enhance the effectiveness of their security frameworks. Varonis Systems integrates AI to detect anomalies and protect sensitive data, making their offerings highly effective. Firms like Netwrix, Virtru, Egnyte, and Micro Focus are also key contenders, focusing on compliance management and secure collaboration tools that meet stringent data privacy regulations such as GDPR and CCPA. Orange Cyberdefense and Infogix play a pivotal role in offering end-to-end security services and data governance solutions. The competition in the market is further fueled by the rapid adoption of cloud-based technologies and the increasing need for scalable, cloud-native security solutions that protect data across hybrid and multi-cloud environments.
Recent Developments:
- In March 2023, Broadcom launched Symantec Data Loss Prevention (DLP) 16.0, an enhanced version of its DLP solution offering improved data classification, anomaly detection, and user activity monitoring capabilities.
- In March 2024, Symantec unveiled advancements in their endpoint security solutions that incorporate real-time data monitoring and anomaly detection to prevent insider threats.
- In April 2024, Israel Aerospace Industries (IAI) and Aerotor Unmanned Systems signed a Memorandum of Understanding (MoU) to collaborate on improving unmanned aircraft system technologies. IAI will use its expertise in aviation and unmanned platforms, while Aerotor will incorporate its Apus multicopter, featuring a core heavy-fuel propulsion system and a variable pitch mechanism. This combination enhances the Apus by increasing payload capacity, endurance, and agility.
Market Concentration & Characteristics:
The Data Centric Security Market exhibits a moderately fragmented structure, with key players dominating significant portions of the market. Major companies like IBM Corporation, Broadcom, Informatica, and Varonis Systems hold a strong presence, contributing to innovation and technological advancements. These market leaders drive competition by offering comprehensive data protection solutions, including encryption, data masking, and real-time monitoring tools. However, a range of small and mid-sized players, focusing on niche solutions or specific industries, also contribute to the market’s growth and diversification. The market is characterized by rapid technological evolution, fueled by the increasing adoption of cloud technologies and growing concerns over data privacy and regulatory compliance. Organizations are seeking scalable, flexible solutions that integrate seamlessly into complex IT environments. As cybersecurity threats continue to evolve, the demand for advanced, AI-driven security tools further shapes the market landscape, creating opportunities for new entrants to offer innovative and specialized solutions.
Report Coverage:
The research report offers an in-depth analysis based on Component, Deployment, Enterprise Size, Industry Vertical and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing data privacy concerns will drive the adoption of data-centric security solutions across industries.
- The rise in cyber threats and insider attacks will continue to push organizations to strengthen their data protection strategies.
- AI and machine learning technologies will play a crucial role in enhancing data security capabilities.
- Cloud-based data security solutions will see growing demand as organizations migrate more operations to hybrid and multi-cloud environments.
- Regulatory frameworks like GDPR and CCPA will lead to increased compliance and governance efforts globally.
- Real-time data monitoring and anomaly detection solutions will become essential for proactive threat management.
- Businesses will increasingly prioritize data security measures that support seamless integration with existing IT infrastructures.
- The need for decentralized data protection strategies will grow as organizations handle more distributed and diverse data environments.
- The Asia Pacific region will see significant growth due to rapid digital transformation and increased cloud adoption.
- New market entrants will introduce specialized solutions catering to industry-specific data security needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Data Privacy Regulations
Regulations such as GDPR in Europe and CCPA in the US are compelling organizations to adopt advanced data-centric security solutions to ensure compliance and avoid hefty penalties, driving market growth.
Rapid Adoption of Cloud-Based Services
As enterprises migrate sensitive data to cloud and hybrid environments, the need for robust, scalable data-centric security solutions that protect data regardless of its location is increasing significantly.
Rising Cybersecurity Threats and Data Breaches
The growing frequency and sophistication of cyberattacks, including ransomware and insider threats, are pushing organizations to implement data-centric security measures to safeguard critical information assets.
Advancements in AI-Driven Security Technologies
The integration of artificial intelligence and machine learning into security frameworks enables real-time data monitoring, anomaly detection, and automated threat response, enhancing the effectiveness and appeal of data-centric security solutions.
Growing Awareness of Data Value and Governance
Organizations are increasingly recognizing the strategic value of data and the importance of comprehensive data governance, leading to higher investments in solutions that ensure data integrity, privacy, and compliance across complex IT environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Data Centric Security Market?
What factors are driving the growth of the Data Centric Security Market?
What are the key segments within the Data Centric Security Market?
What are some challenges faced by the Data Centric Security Market?
Who are the major players in the Data Centric Security Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Software & Solution
- 1.2.2 Services
- 1.3 By Deployment
- 1.3.1 On-premise
- 1.3.2 Cloud
- 1.4 By Enterprise Size
- 1.4.1 Large Enterprises
- 1.4.2 SMEs
- 1.5 By Industry Vertical
- 1.5.1 BFSI
- 1.5.2 IT & Telecom
- 1.5.3 Government & Defense
- 1.5.4 Healthcare
- 1.5.5 Retail
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,359 million → 2032: USD 38,553.13 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Data Centric Security Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Data Centric Security Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Data Centric Security Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Data Centric Security Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Data Centric Security Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Data Centric Security Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Data Centric Security Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Data Centric Security Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,359 million → 2032: USD 38,553.13 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Data Centric Security Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Software & Solution
- 12.3.7.2 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Deployment - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 On-premise
- 12.4.7.2 Cloud
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Enterprise Size - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Large Enterprises
- 12.5.7.2 SMEs
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Industry Vertical - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 BFSI
- 12.6.7.2 IT & Telecom
- 12.6.7.3 Government & Defense
- 12.6.7.4 Healthcare
- 12.6.7.5 Retail
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Data Centric Security End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Data Centric Security Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Data Centric Security Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Data Centric Security Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IBM Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Broadcom
- 18.4 Varonis Systems
- 18.5 Orange Cyberdefense
- 18.6 Informatica
- 18.7 Sophos
- 18.8 Netwrix
- 18.9 Micro Focus
- 18.10 Egnyte
- 18.11 Virtru
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

