
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
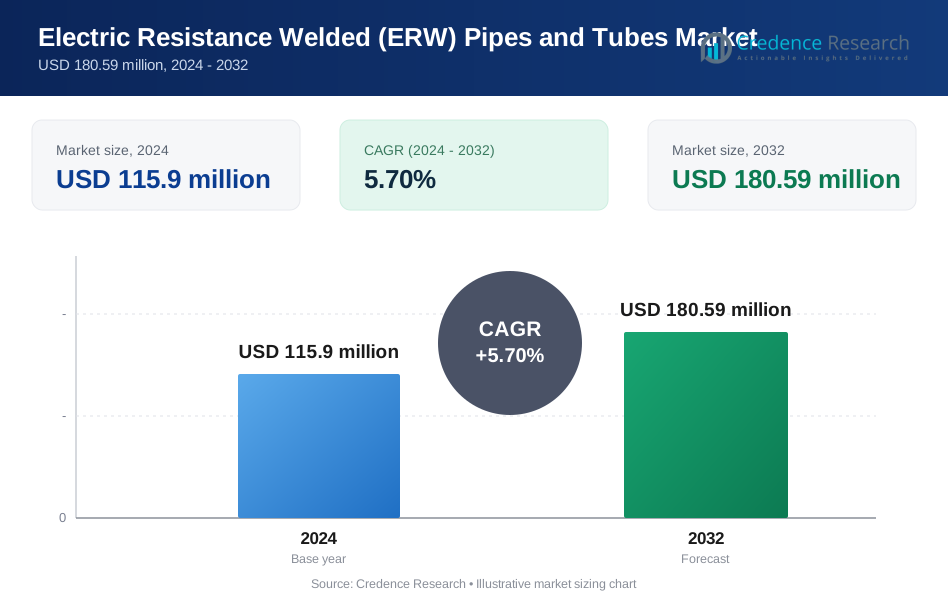
| Electric Resistance Welded (ERW) Pipes and Tubes Market Size 2024 | USD 115.9 million |
| Electric Resistance Welded (ERW) Pipes and Tubes Market , CAGR | 5.7% |
| Electric Resistance Welded (ERW) Pipes and Tubes Market Size 2032 | USD 180.59 million |
Market Overview:
The Electric Resistance Welded (ERW) Pipes and Tubes market is projected to grow from USD 115.9 million in 2024 to USD 180.59 million by 2032, at a CAGR of 5.7% during the forecast period.
The Electric Resistance Welded (ERW) Pipes and Tubes market is driven by increasing infrastructure development, rapid urbanization, and rising demand from the construction, automotive, and oil & gas industries. Governments worldwide are investing in pipeline networks for water distribution and energy transportation, further boosting market growth. The adoption of advanced manufacturing technologies enhances product quality, efficiency, and durability, contributing to higher demand. Sustainability concerns are pushing manufacturers toward eco-friendly production processes and recyclable materials. Additionally, the expansion of renewable energy projects, particularly in wind and solar power, is increasing the need for ERW pipes in structural applications. Emerging economies, particularly in Asia-Pacific, are witnessing high demand due to industrial expansion and urban infrastructure projects. However, fluctuating raw material prices and competition from seamless pipes pose challenges to market growth. Despite this, increasing R&D investments in corrosion-resistant coatings and lightweight materials are shaping industry trends, making ERW pipes and tubes more adaptable to evolving market needs.
The Electric Resistance Welded (ERW) Pipes and Tubes Market is geographically diverse, with Asia-Pacific holding the largest share, driven by rapid industrialization and infrastructure development in countries like China, India, and Japan. North America follows with strong demand from the oil & gas and automotive sectors, while Europe focuses on energy transition and sustainable construction. Latin America is expanding in the oil & gas and infrastructure sectors, though economic fluctuations present challenges. The Middle East & Africa sees growing demand in energy and water infrastructure development. Leading players like ArcelorMittal, Nippon Steel Corporation, JFE Steel Corporation, Tenaris S.A., Vallourec S.A., Tata Steel, and others are strategically positioned across these regions to capitalize on local opportunities and expand their global presence. Their investments in advanced technology and sustainability initiatives further enhance their market competitiveness.
Market Insights:
- The Electric Resistance Welded (ERW) Pipes and Tubes Market is projected to grow from USD 115.9 million in 2024 to USD 180.59 million by 2032, with a CAGR of 5.7%.
- Key growth drivers include increasing infrastructure development, rapid urbanization, and rising demand from construction, automotive, and oil & gas industries.
- Governments are investing heavily in pipeline networks for water distribution and energy transportation, boosting market growth.
- Technological advancements, including advanced manufacturing processes, enhance the quality and durability of ERW pipes, making them more efficient.
- Sustainability concerns are driving manufacturers toward eco-friendly production processes and recyclable materials.
- Emerging economies in the Asia-Pacific region, particularly China, India, and Japan, are witnessing high demand due to industrial expansion and infrastructure projects.
- Fluctuating raw material prices and competition from seamless pipes pose challenges, but ongoing R&D investments in corrosion-resistant coatings and lightweight materials are helping manufacturers stay competitive.
Market Drivers:
Infrastructure Development and Urbanization:
The increasing demand for Electric Resistance Welded (ERW) Pipes and Tubes is largely driven by rapid urbanization and expanding infrastructure projects worldwide. Governments and private sector investments in roads, bridges, residential complexes, and commercial buildings necessitate durable and cost-effective piping solutions. For instance, Tata Steel and Welspun Corp became the first Indian companies to produce ERW pipes for hydrogen transportation after developing hydrogen-compliant API X65 grade pipes that passed tests for transporting 100% pure gaseous hydrogen at high pressure. ERW pipes, known for their strength and efficiency, play a critical role in water distribution, sewage systems, and structural frameworks. The growing need for smart cities and sustainable urban planning further accelerates demand, making ERW pipes a preferred choice in modern construction.
Expansion in the Oil & Gas and Energy Sectors:
The oil & gas industry remains a significant driver of ERW pipe demand, with increasing exploration, drilling, and pipeline transportation activities. The expansion of natural gas and crude oil pipelines, along with rising energy consumption, fuels the need for high-quality welded pipes. For instance, Hi-Tech Pipes, an Indian steel tubes and pipes manufacturer, secured a ₹105 crore project to supply ERW steel pipes for renewable energy projects. Additionally, the transition toward cleaner energy sources, such as wind and solar power, has increased the adoption of ERW tubes in structural applications. As countries invest in energy security and efficiency, the demand for ERW pipes in power plants, refineries, and renewable energy projects continues to grow.
Technological Advancements and Material Innovations:
Advancements in manufacturing technologies have improved the precision, durability, and cost-efficiency of ERW pipes. The integration of automation and quality control measures ensures enhanced product consistency and performance. Additionally, the development of corrosion-resistant coatings and high-strength alloys extends the lifespan of ERW tubes, making them suitable for harsh environmental conditions. Innovations in lightweight materials further support demand across industries, particularly in automotive and aerospace applications, where weight reduction and fuel efficiency are critical.
Increasing Demand from the Automotive and Industrial Sectors:
The automotive industry relies on ERW pipes for chassis components, exhaust systems, and structural reinforcements. With the push toward electric vehicles (EVs) and lightweight materials, ERW tubes are gaining traction due to their strength-to-weight ratio. Furthermore, industrial applications, including machinery, agricultural equipment, and manufacturing plants, require ERW pipes for fluid transportation and structural integrity. The continuous expansion of these industries, particularly in emerging economies, strengthens the market outlook for ERW pipes and tubes.
Market Trends:
Growing Adoption of Advanced Manufacturing Technologies:
The Electric Resistance Welded (ERW) Pipes and Tubes market is witnessing significant advancements in manufacturing technologies, leading to improved product quality and efficiency. Automation and precision welding techniques are enhancing consistency in pipe dimensions, reducing defects, and increasing production rates. For instance, Tube Trading Co. utilizes High-Frequency Induction Welding (HFIW) that employs high-frequency alternating current (AC) to create a clean and strong weld seam. The integration of artificial intelligence and real-time monitoring systems ensures better control over welding parameters, resulting in stronger and more durable pipes. These technological improvements are enabling manufacturers to meet the growing demand for high-performance pipes across industries.
Rising Demand for Corrosion-Resistant and High-Strength Materials:
With increasing applications in industries such as oil & gas, construction, and automotive, there is a strong demand for ERW pipes made from corrosion-resistant and high-strength materials. The development of advanced coatings and alloy compositions is improving the durability of ERW pipes, making them suitable for harsh environments. This trend is particularly evident in offshore drilling, chemical processing, and water treatment plants, where exposure to corrosive substances requires enhanced material performance.
Surge in Sustainable and Eco-Friendly Production Practices:
Sustainability is becoming a key focus in the ERW pipes and tubes market, with manufacturers adopting eco-friendly production methods. The use of recyclable materials, energy-efficient welding techniques, and waste reduction strategies are gaining traction. Governments and regulatory bodies are enforcing stringent environmental standards, pushing companies to invest in cleaner manufacturing processes. For instance, Utkarsh India ensures minimal waste during the ERW pipe manufacturing process, which directly reduces their environmental impact. This shift toward sustainability not only reduces the carbon footprint of ERW pipe production but also enhances the overall market appeal for environmentally conscious consumers.
Expanding Applications in Renewable Energy and Infrastructure Projects:
The growing emphasis on renewable energy and infrastructure development is driving demand for ERW pipes in wind farms, solar power installations, and smart city projects. As countries invest in modern energy grids and sustainable urban planning, ERW pipes are being increasingly used for structural support, fluid transportation, and underground piping networks. This trend underscores the market’s pivotal role in the global transition toward cleaner energy and smarter infrastructure solutions.
Market Challenges Analysis:
Fluctuating Raw Material Prices and Supply Chain Disruptions:
The Electric Resistance Welded (ERW) Pipes and Tubes market faces significant challenges due to the volatility of raw material prices, particularly steel, which is a primary component. Global fluctuations in steel prices, driven by supply-demand imbalances, trade restrictions, and geopolitical uncertainties, directly impact the production costs of ERW pipes. Rising costs of raw materials increase the overall manufacturing expenses, forcing companies to either absorb the financial burden or pass it on to consumers, which can reduce market competitiveness. For instance, JFE Steel, a Japanese manufacturer, has an extensive portfolio including high-strength and corrosion-resistant ERW pipes. Additionally, supply chain disruptions caused by transportation bottlenecks, labor shortages, and fluctuating demand patterns further complicate procurement processes. The recent global crises, such as the COVID-19 pandemic and geopolitical tensions, have highlighted the vulnerability of supply chains, leading manufacturers to rethink sourcing strategies, invest in local suppliers, and explore alternative materials to stabilize production costs and maintain profitability.
Competition from Alternative Pipe Technologies and Regulatory Challenges:
The ERW pipes and tubes market is also challenged by growing competition from alternative pipe manufacturing technologies, particularly seamless pipes. Seamless pipes, known for their superior strength and pressure resistance, are preferred in critical applications such as high-pressure pipelines, aerospace, and power generation. Although ERW pipes offer cost-effective solutions for many industries, the perception of seamless pipes as higher-quality alternatives poses a competitive threat. To address this challenge, ERW pipe manufacturers are investing in advanced welding techniques and material innovations to enhance product reliability and expand application areas. Moreover, stringent regulatory requirements and industry standards related to safety, environmental impact, and product quality add another layer of complexity for market players. Compliance with evolving industry norms requires continuous investment in quality assurance, testing facilities, and environmental sustainability measures. Companies must navigate these regulatory landscapes while maintaining cost-effectiveness and production efficiency, which can be a challenging balance in a competitive market. Despite these obstacles, ongoing technological advancements, strategic partnerships, and an increasing focus on sustainability provide opportunities for ERW pipe manufacturers to strengthen their market position and drive long-term growth.
Market Opportunities:
The Electric Resistance Welded (ERW) Pipes and Tubes market presents significant growth opportunities driven by increasing infrastructure development and expanding industrial applications. Governments and private investors worldwide are heavily investing in smart cities, modern transportation networks, and large-scale construction projects, creating a strong demand for durable and cost-effective piping solutions. ERW pipes, widely used in water supply systems, structural frameworks, and underground utilities, stand to benefit from this surge in urbanization. Additionally, the growing need for efficient oil & gas transportation, coupled with rising investments in pipeline networks, further supports the market’s expansion. As countries transition to cleaner energy sources, ERW pipes are also gaining traction in renewable energy projects, including wind and solar power installations, where they are used for structural support and energy transmission systems.
Technological advancements and innovation in material science are opening new doors for ERW pipe manufacturers. The development of corrosion-resistant coatings, high-strength alloys, and lightweight materials enhances the durability and versatility of these pipes, making them suitable for diverse applications, including automotive, aerospace, and industrial machinery. Furthermore, the rising focus on sustainability and eco-friendly manufacturing practices presents an opportunity for companies to differentiate themselves by adopting greener production techniques and recyclable materials. With increasing regulatory support for sustainable infrastructure, manufacturers investing in environmentally responsible processes stand to gain a competitive advantage. Emerging economies, particularly in Asia-Pacific and Latin America, offer untapped market potential due to their rapid industrialization and infrastructure expansion. By leveraging strategic partnerships, investing in R&D, and focusing on product innovation, companies can capitalize on these opportunities and strengthen their foothold in the evolving ERW pipes and tubes market.
Market Segmentation Analysis:
By Material Type
The Electric Resistance Welded (ERW) Pipes and Tubes market is segmented based on material type, including carbon steel, stainless steel, and alloy steel. Carbon steel ERW pipes dominate due to their cost-effectiveness and high durability, making them ideal for construction and infrastructure projects. Stainless steel and alloy steel variants are gaining traction in industries requiring corrosion resistance, such as oil & gas and chemical processing.
By Application
ERW pipes serve various applications, including structural support, fluid transportation, and mechanical engineering. Their extensive use in water distribution, gas pipelines, and industrial machinery highlights their versatility. Increasing demand for lightweight and high-strength materials in automotive and aerospace sectors is further driving innovations in ERW pipe manufacturing.
By End User
Key end-user industries for ERW pipes include construction, oil & gas, automotive, and manufacturing. Infrastructure development and energy sector expansion continue to be primary growth drivers. Additionally, rising adoption in industrial machinery and transportation networks strengthens market demand, particularly in emerging economies undergoing rapid urbanization and industrialization.
Segments:
Based on Material Type
- Carbon Steel
- Stainless Steel
- Alloy Steel
- Others
Based on Application
- Oil & Gas
- Automotive
- Infrastructure & Construction
- Mechanical Engineering
- Others
Based on End-User
- Residential
- Commercial
- Industrial
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
In 2024, North America holds 25% of the global Electric Resistance Welded (ERW) Pipes and Tubes market share, driven by a strong industrial base and continued infrastructure investments. The region's well-established oil & gas sector, particularly in the United States and Canada, fuels the demand for ERW pipes used in pipeline transportation and drilling applications. Additionally, government initiatives to modernize water distribution networks and expand renewable energy projects contribute to market growth. The automotive and construction industries also support demand, with increasing adoption of lightweight and high-strength ERW pipes.
Europe
Europe accounts for 20% of the global market share in 2024, with significant demand coming from the energy sector and sustainable construction projects. Countries such as Germany, France, and the United Kingdom are investing heavily in renewable energy infrastructure, where ERW pipes are used in wind farms, solar installations, and hydrogen transportation. Stringent environmental regulations drive the adoption of corrosion-resistant and recyclable materials in pipe manufacturing. The region's commitment to reducing carbon emissions and enhancing energy efficiency further stimulates demand for ERW pipes in industrial and commercial applications.
Asia-Pacific
Asia-Pacific leads the global ERW pipes and tubes market with a 35% market share in 2024, fueled by rapid industrialization, urbanization, and large-scale infrastructure projects. China, India, and Japan are key contributors, with expanding oil & gas exploration, power generation, and construction activities. The region's booming automotive sector and increasing investments in high-speed rail networks and smart cities further drive demand. Government-backed initiatives to enhance water supply systems and develop industrial corridors provide additional market opportunities. The presence of major steel producers and cost-effective manufacturing further strengthens Asia-Pacific’s dominance.
Latin America
Latin America holds 10% of the global market share in 2024, supported by growing oil & gas exploration activities in Brazil, Mexico, and Argentina. Rising investments in infrastructure projects, such as highways, ports, and water distribution systems, contribute to demand for ERW pipes. However, economic fluctuations and political instability in some countries pose challenges to sustained market growth.
Middle East & Africa
With a 10% market share in 2024, the Middle East & Africa region presents emerging opportunities in oil & gas, construction, and water infrastructure development. Major pipeline expansion projects in the Gulf countries and Africa's increasing focus on industrialization drive demand for ERW pipes. Government initiatives for desalination plants and modernized water supply networks further contribute to market growth.
Key Player Analysis:
- Welspun Corp Ltd.
- SeAH Steel Corporation
- Tenaris S.A.
- United States Steel Corporation
- TMK Group
- Nippon Steel Corporation
- Vallourec S.A.
- ChelPipe Group
- JFE Steel Corporation
- EVRAZ North America
- Tata Steel
- ArcelorMittal
Competitive Analysis:
The Electric Resistance Welded (ERW) Pipes and Tubes Market is highly competitive, with leading players such as ArcelorMittal, Nippon Steel Corporation, JFE Steel Corporation, Tenaris S.A., Vallourec S.A., Tata Steel, United States Steel Corporation, Welspun Corp Ltd., ChelPipe Group, TMK Group, SeAH Steel Corporation, and EVRAZ North America dominating the global landscape. These companies are strategically focusing on expanding their production capabilities, enhancing product quality, and diversifying their product portfolios to meet the growing demand across various sectors, including oil & gas, automotive, and construction. Investments in advanced manufacturing technologies, such as automation and corrosion-resistant coatings, are allowing these players to offer high-performance ERW pipes suitable for challenging applications. Additionally, they are capitalizing on the shift towards sustainability by adopting eco-friendly production processes and offering recyclable solutions. Strategic mergers, acquisitions, and collaborations are also helping these companies to strengthen their market position, expand geographical reach, and achieve economies of scale.
Recent Developments:
- In April 2023, Nippon Steel Corporation published the EcoLeaf Environmental Product Declaration (*) for steel sheet piles, including the NS-PACTM Sheet Piles. This program is managed by the Sustainable Management Promotion Organization (SuMPO).
- In December 2023, Nippon Steel Corporation announced plans to integrate its operations in the North American region with a United States Steel Corporation (U.S. Steel).
Market Concentration & Characteristics:
The Electric Resistance Welded (ERW) Pipes and Tubes Market exhibits moderate market concentration, with a few large players holding a significant share, while smaller companies continue to contribute to regional demand. Major manufacturers like ArcelorMittal, Nippon Steel Corporation, JFE Steel Corporation, and Tenaris S.A. dominate the market, leveraging their advanced production capabilities, established brand reputation, and global reach. These players have a competitive advantage through continuous technological innovations, such as automation, high-strength alloys, and corrosion-resistant coatings, which enhance the durability and performance of ERW pipes. The market characteristics include strong competition, with price sensitivity influencing demand, especially in cost-sensitive industries like construction and automotive. As a result, companies focus on cost-efficient production methods and strategic partnerships to enhance their market share. With growing sustainability concerns, manufacturers are increasingly adopting eco-friendly and recyclable materials, ensuring long-term growth and aligning with regulatory trends.
Report Coverage:
The research report offers an in-depth analysis based on Material Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for Electric Resistance Welded (ERW) Pipes and Tubes will continue to grow due to ongoing infrastructure development globally.
- Urbanization and the expansion of smart cities will drive the need for durable and cost-effective piping solutions.
- Technological advancements in manufacturing processes will enhance the quality and efficiency of ERW pipes, making them more attractive to industries.
- The oil & gas industry will remain a key driver, with increasing exploration and pipeline expansion activities fueling demand for ERW pipes.
- Growing investments in renewable energy projects, particularly in wind and solar power, will increase the adoption of ERW pipes for structural applications.
- Emerging economies in the Asia-Pacific region will continue to be a significant source of market growth, driven by rapid industrialization.
- Manufacturers will increasingly adopt sustainable production methods, focusing on eco-friendly materials and processes.
- The automotive sector will see rising demand for lightweight ERW pipes used in vehicle components and systems, especially for electric vehicles.
- Fluctuating raw material prices will remain a challenge, requiring companies to explore alternative sourcing strategies and materials.
- Competition from seamless pipes will persist, pushing ERW pipe manufacturers to innovate and improve product performance to maintain market share.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Electric Resistance Welded (ERW) Pipes and Tubes Market?
What factors are driving the growth of the Electric Resistance Welded (ERW) Pipes and Tubes Market?
What are some challenges faced by the Electric Resistance Welded (ERW) Pipes and Tubes Market?
Who are the major players in the Electric Resistance Welded (ERW) Pipes and Tubes Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Electric Resistance Welded (ERW) Pipes and Tubes Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Electric Resistance Welded (ERW) Pipes and Tubes Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 115.9 million → 2032: USD 180.59 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Electric Resistance Welded (ERW) Pipes and Tubes Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Electric Resistance Welded (ERW) Pipes and Tubes Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Electric Resistance Welded (ERW) Pipes and Tubes Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Electric Resistance Welded (ERW) Pipes and Tubes Market Drivers
- 3.3 Electric Resistance Welded (ERW) Pipes and Tubes Market Restraints & Challenges
- 3.4 Electric Resistance Welded (ERW) Pipes and Tubes Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Electric Resistance Welded (ERW) Pipes and Tubes Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Electric Resistance Welded (ERW) Pipes and Tubes Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Electric Resistance Welded (ERW) Pipes and Tubes category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Electric Resistance Welded (ERW) Pipes and Tubes Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Electric Resistance Welded (ERW) Pipes and Tubes Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Electric Resistance Welded (ERW) Pipes and Tubes market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Electric Resistance Welded (ERW) Pipes and Tubes Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Electric Resistance Welded (ERW) Pipes and Tubes Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Electric Resistance Welded (ERW) Pipes and Tubes Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Electric Resistance Welded (ERW) Pipes and Tubes (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Electric Resistance Welded (ERW) Pipes and Tubes Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Electric Resistance Welded (ERW) Pipes and Tubes Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Electric Resistance Welded (ERW) Pipes and Tubes Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Electric Resistance Welded (ERW) Pipes and Tubes Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Electric Resistance Welded (ERW) Pipes and Tubes Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Electric Resistance Welded (ERW) Pipes and Tubes Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Electric Resistance Welded (ERW) Pipes and Tubes Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Electric Resistance Welded (ERW) Pipes and Tubes Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Electric Resistance Welded (ERW) Pipes and Tubes Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
