
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Epoxy Resins Paints Market Size 2024 | USD 38,764.5 million |
| Epoxy Resins Paints Market, CAGR | 4% |
| Epoxy Resins Paints Market Size 2032 | USD 53,051.89 million |
Market Overview:
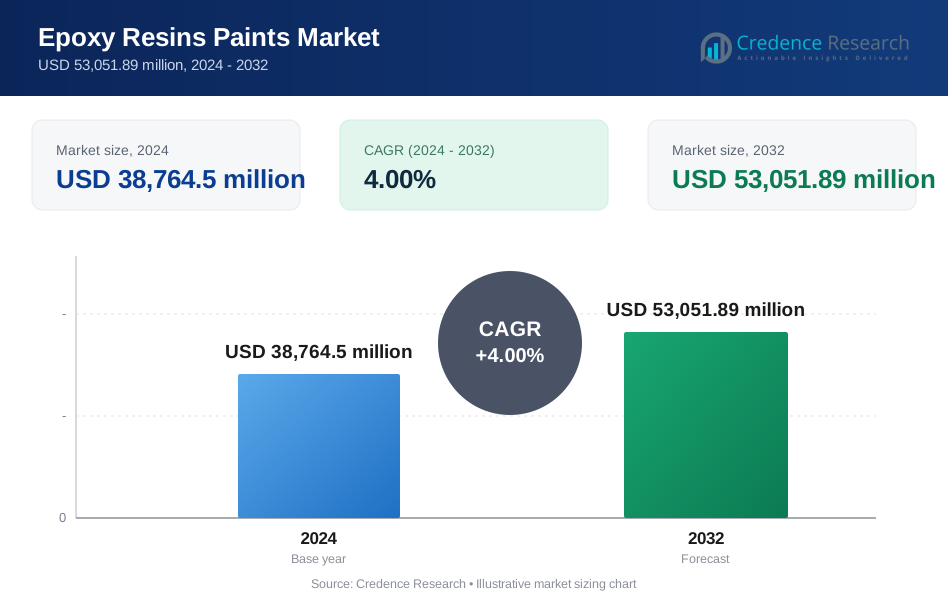
The global epoxy resins paints market size was valued at USD 38,764.5 million in 2024 and is anticipated to reach USD 53,051.89 million by 2032, at a CAGR of 4% during the forecast period (2024-2032).
This growth is driven by the rising demand for epoxy resins in various applications, including paints and coatings, construction, and automotive industries. The market's expansion is further supported by the increasing adoption of advanced epoxy resin technologies and the need for high-performance materials in industrial applications. Several key drivers are propelling the growth of the epoxy resins paints market. The increasing demand for durable and high-performance coatings in the construction and automotive sectors is a major factor driving market growth. Epoxy resins offer exceptional adhesion, chemical resistance, and mechanical strength, making them ideal for protective coatings in harsh environments. Additionally, the growing focus on infrastructure development and renovation projects, particularly in emerging economies, is boosting the demand for epoxy resins. Technological advancements in epoxy resin formulations, such as waterborne and low-VOC (volatile organic compound) resins, are also contributing to market growth by addressing environmental concerns and regulatory requirements.
Regionally, Asia-Pacific dominates the epoxy resins paints market, accounting for the largest share due to the rapid industrialization and urbanization in countries like China and India. The region's expanding construction and automotive industries are driving significant demand for epoxy resins. North America and Europe are also key regions, with the United States and Germany contributing substantially to the market. The increasing demand for high-quality coatings in these regions, coupled with stringent environmental regulations, is driving the adoption of advanced epoxy resin technologies. Additionally, the Middle East and Africa are expected to witness steady growth, driven by infrastructure development and the rising demand for durable coatings in the oil and gas industry.
Market Insights:
- The global epoxy resins paints market is expected to grow from USD 38,764.5 million in 2024 to USD 53,051.89 million by 2032, registering a CAGR of 4%.
- Increasing adoption in automotive, construction, and aerospace industries is driving market growth due to high durability and corrosion resistance.
- Stringent VOC emission laws in North America and Europe are promoting the shift toward low-VOC and water-based epoxy coatings.
- High raw material costs and fluctuations in crude oil prices are restraining market expansion and impacting profit margins.
- China, India, and Japan lead the market, supported by rapid urbanization, infrastructure projects, and strong automotive production.
- Adoption of eco-friendly coatings and technological advancements in high-performance epoxy resins drive demand.
- Advancements in nanotechnology-based epoxy coatings enhance abrasion resistance and lifespan, boosting market penetration.
Market Drivers:
Surging Demand from the Paints and Coatings Sector:
The increasing demand for paints and coatings is a primary driver for the expansion of the epoxy resins market. Epoxy resins enhance the durability, strength, and chemical resistance of coatings, making them ideal for various applications. They offer quick-drying properties, excellent adhesion, abrasion resistance, and superior water resistivity, which are essential for protecting metal and other surfaces. For instance, the paints and coatings market are seeing increased investments to meet rising demand. Berger Paints India announced plans to invest over INR 1,000 crore in a new greenfield composite plant in Odisha, focusing on both decorative and industrial paints, which is expected to further catalyze the demand for paints and coatings. This illustrates the proactive measures key players are taking to meet the escalating needs of the market.
Growth in Construction and Infrastructure Development:
The robust growth of the construction industry significantly drives the epoxy resins market. Epoxy resins are used to enhance the aesthetic and protective properties of residential, commercial, and industrial structures. For instance, the Indian construction industry is predicted to become the third-largest globally, reaching nearly USD 1 trillion by the end of the forecast period. This growth is further supported by government initiatives such as the Smart Cities project and the Housing for All initiative, along with regulatory reforms like the Real Estate Act, GST, and REITs, which expedite approvals and enhance the building sector. These developments directly impact the demand for epoxy coatings, essential in construction for protecting cementitious materials, enhancing structural durability, and creating high-performance flooring solutions.
Expansion of the Electrical and Electronics Industries:
The expansion of the electrical and electronics industries is another key driver for the epoxy resins market. Epoxy resins are crucial in these sectors due to their high-performance and long-lasting properties, making them ideal for adhesives and paints. For instance, the Indian electronics market is projected to reach USD 400 billion by 2025. Government initiatives like the Digital India initiative and the Production Linked Incentive (PLI) scheme have accelerated domestic electronics production, creating new demand channels for epoxy resins in circuit board manufacturing and electronic component assembly. These schemes have attracted significant investments in local manufacturing facilities, particularly in semiconductor and consumer electronics production, further boosting the demand for epoxy resins.
Increasing Demand for Sustainable and Eco-Friendly Products:
There is a notable industry-wide shift towards environmentally sustainable and recyclable thermosetting resins, driven by increasing environmental consciousness and regulatory requirements. Manufacturers are investing in the research and development of bio-based epoxy polymers and exploring innovative recycling technologies for thermoset polymers. The industry is witnessing increased adoption of waterborne high-performance resins systems, which offer reduced volatile organic compound (VOC) emissions while maintaining performance standards. For instance, waterborne epoxy paints are gaining traction as environmental regulations become more stringent and consumers demand sustainable products. This trend is expected to continue as both regulatory pressures and consumer preferences drive the demand for more eco-friendly options in the epoxy resins market.
Market Trends:
Growing Adoption of Bio-Based Epoxy Resins:
A significant trend in the epoxy resins market is the increasing demand for bio-based epoxy resins, driven by growing environmental consciousness and regulatory pressures. Manufacturers are actively investing in the research and development of epoxy resins derived from renewable resources to reduce their carbon footprint and dependence on fossil fuels. For instance, the industry is witnessing increased efforts to utilize natural resources for synthesizing bio-based epoxies and their curing agents. The development of bio-based epoxy resins allows companies to offer environmentally friendly alternatives without compromising on the performance characteristics of traditional epoxy resins.
Advancements in Epoxy Resin Technology:
Technological advancements are leading to the development of epoxy resins with enhanced properties, catering to demanding and evolving industrial environments. Nanotechnology, for example, has facilitated the creation of epoxy resins with improved strength, durability, and resistance to chemicals and temperature extremes. Similarly, innovations in curing agents and additives have enabled faster curing times and enhanced adhesion properties. For instance, the development of fast-curing compounds can shorten epoxy resin curing times, increasing output and cutting expenses. These advancements enable businesses to gain a competitive edge by offering high-performance epoxy resins suitable for a wide range of applications.
Increasing Use of Waterborne Epoxy Resins:
The rising popularity of waterborne epoxy resins is another notable trend in the market. Waterborne epoxy resins offer reduced volatile organic compound (VOC) emissions, making them an environmentally friendly alternative to solvent-based systems. For instance, in response to increasing environmental regulations aimed at limiting VOC emissions, the market share of waterborne coating systems has significantly increased. The development of waterborne epoxy-based resins incorporated with materials like modified natural rubber (NR) latex further enhances their performance, offering improved adhesion and mechanical properties. This trend aligns with the broader industry shift towards sustainable and eco-friendly products.
Expanding Applications in Composites and Electronics:
Epoxy resins are increasingly utilized in composite materials to enhance their durability, strength, and stiffness. This is particularly evident in industries such as wind energy, aerospace, and automotive, where the demand for high-performance materials is growing. For instance, the composite segment is experiencing rapid growth due to increasing investments in wind energy projects worldwide. Additionally, epoxy resins are finding new applications in electronics, such as chip encapsulation and printed circuit boards, owing to their superior electrical insulating capabilities and thermal stability. The growing electronics manufacturing ecosystem, supported by initiatives like Digital India and the Production Linked Incentive (PLI) scheme, is further driving the demand for epoxy resins in this sector. This expansion signifies the versatility and adaptability of epoxy resins in meeting the evolving needs of diverse industries.
Market Challenges Analysis:
Health and Environmental Concerns:
A significant restraint on the epoxy resins market stems from health and environmental concerns associated with exposure to epoxy resins and their components. These resins can emit harmful fumes that irritate the eyes and lungs, potentially causing breathing problems, especially for individuals with asthma. Overexposure to unhealthy epoxy chemicals can lead to skin allergies, asthma, and irritations of the eyes, nose, and throat. For instance, regulatory bodies such as the European Union (EU) have implemented stringent regulations like REACH (Registration, Evaluation, Authorization, and Restriction of Chemicals) to manage the risks associated with chemical substances, pushing manufacturers to innovate and produce safer epoxy resin formulations. These regulations can limit the use of certain raw materials and formulations, leading to a shift towards eco-friendly and compliant products.
Fluctuating Raw Material Prices and Supply Chain Disruptions:
The epoxy resin market faces challenges related to fluctuating raw material prices and potential supply chain disruptions. The production of epoxy resins relies heavily on raw materials such as bisphenol A (BPA) and epichlorohydrin, the prices of which are subject to volatility due to supply-demand dynamics, geopolitical issues, and fluctuations in crude oil prices. For instance, plant closures, extreme weather conditions, and logistics issues can cause scarcity of supply, forcing downstream manufacturers to delay production or find alternatives. These fluctuations can significantly impact the cost of manufacturing epoxy resins, affecting the overall profitability of producers and potentially leading to price volatility in the market.
Trade and Economic Protectionism:
Trade and economic protectionism pose additional challenges to the epoxy resins market. Anti-dumping investigations and measures targeting foreign epoxy resins producers, particularly in Asia, by the EU and the United States aim to protect domestic production and trade. For instance, the US Department of Commerce and the US International Trade Commission initiated a probe into epoxy resin producers in China, South Korea, Taiwan, India, and Thailand following complaints from domestic companies. These measures can lead to increased trade barriers, affecting the availability and pricing of epoxy resins in different regions, and creating uncertainty for market participants.
Market Opportunities:
The epoxy resins paints market presents significant growth opportunities, driven by the increasing adoption of sustainable and high-performance coatings across various industries. With stringent environmental regulations promoting low-VOC and water-based epoxy paints, manufacturers have the potential to develop eco-friendly formulations that comply with global emission standards while maintaining durability and performance. The rising demand for high-performance protective coatings in marine, aerospace, and industrial applications is further expanding the market landscape. Additionally, the growing trend of smart coatings with self-healing, anti-corrosive, and anti-microbial properties is opening new avenues for innovation and product differentiation.
The Asia-Pacific region, particularly China, India, and Japan, offers substantial market potential due to rapid urbanization, infrastructure development, and expanding automotive production. The construction industry is experiencing increased demand for epoxy-based floor coatings, driven by the growth of commercial and residential projects. Meanwhile, North America and Europe present opportunities in advanced coating technologies, with industries investing in nanotechnology-enhanced epoxy coatings that improve abrasion resistance, chemical stability, and lifespan. The surge in renewable energy projects, especially wind energy, is also creating demand for epoxy-based protective coatings used in wind turbine blades and components. As the industry shifts towards sustainable solutions and technological advancements, companies investing in R&D and product innovation are well-positioned to capitalize on emerging market opportunities.
Market Segmentation Analysis:
By Epoxy Resins Raw Material:
The market is categorized into DGBEA (Bisphenol A), DGBEF (Bisphenol F), Novolac, Aliphatic, and Glycidylamine. DGBEA dominates the market due to its widespread use in various applications, offering excellent mechanical properties and chemical resistance. Novolac resins are gaining traction for their superior thermal stability and chemical resistance, making them ideal for high-performance coatings. Aliphatic and Glycidylamine resins are also significant, providing unique properties such as flexibility and improved adhesion, catering to specific industrial needs.
By Epoxy Resins Application:
The market is segmented into paints and coatings, adhesives, composites, electrical and electronics, and others. Paints and coatings hold the largest share, driven by the demand for durable and high-performance coatings in construction, automotive, and industrial sectors. Epoxy resins are preferred for their exceptional adhesion, chemical resistance, and mechanical strength, making them ideal for protective coatings. The adhesives segment is also significant, with epoxy resins being used in various bonding applications due to their strong adhesive properties. Composites and electrical and electronics applications are growing, driven by the need for lightweight, high-strength materials and advanced electronic components.
Segmentations:
By Epoxy Resins Raw Material:
- DGBEA (Bisphenol A and ECH)
- DGBEF (Bisphenol F and ECH)
- Novolac (Formaldehyde and Phenols)
- Aliphatic (Aliphatic Alcohols)
- Glycidylamine (Aromatic Amines and ECH)
- Other Raw Materials
By Epoxy Resins Application:
- Paints and Coatings
- Adhesives and Sealants
- Composites
- Grouts & Mortars
- Electrical and Electronics
- Other Applications
By End-use:
- Aerospace
- Automotive & Transportation
- Building & Construction
- Electrical & Electronics
- Marine
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific:
Asia-Pacific holds the largest share in the epoxy resins paints market, accounting for 45% of global revenue. The region's growth is fueled by rapid industrialization, urbanization, and increasing infrastructure investments in China, India, and Japan. For instance, China alone contributes nearly 35% of global automotive production, significantly driving demand for high-performance epoxy coatings in vehicle manufacturing. The push for sustainable and low-VOC coatings, supported by regulatory initiatives like China’s Blue-Sky Protection Campaign, further propels market expansion. China’s National Green Development Policy mandates a 10% reduction in VOC emissions in coatings by 2025, encouraging widespread adoption of eco-friendly epoxy formulations. The growing demand for marine and industrial coatings, particularly in Japan and South Korea, also contributes to the region's dominance.
North America:
North America holds 22% of the global epoxy resins paints market, driven by the adoption of advanced coating technologies, stringent environmental regulations, and strong industrial demand. For instance, the U.S. automotive sector, valued at USD 104.1 billion in 2023, remains a major consumer of epoxy-based coatings to enhance vehicle longevity and corrosion resistance. Environmental policies set by the U.S. EPA and Canada’s Green Building initiatives are accelerating the shift toward water-based and powder-based epoxy coatings, reducing the industry’s carbon footprint. Canada’s LEED-certified construction projects have increased by over 50% in the last five years, boosting the use of low-VOC epoxy coatings. Aerospace applications in North America, particularly in the U.S. and Canada, are driving the adoption of nanotechnology-enhanced epoxy coatings, ensuring improved abrasion and weather resistance. Boeing and Lockheed Martin have integrated nano-enhanced epoxy coatings to improve fuel efficiency and reduce maintenance costs for aircraft.
Europe:
Europe accounts for 20% of the global epoxy resins paints market, with strong contributions from Germany, France, and the UK. the European automotive coatings market surpassed USD 5 billion in 2023, with epoxy-based coatings playing a crucial role in vehicle protection and fuel efficiency improvements. For instance, the European Commission’s 2030 Green Deal aims to cut industrial emissions by 55%, pushing manufacturers to develop bio-based epoxy coatings. The growing demand for renewable energy solutions has further increased the application of epoxy coatings in wind turbines and solar panels, supporting market growth. Europe’s wind energy capacity reached 255 GW in 2023, with epoxy coatings enhancing the durability of turbine blades and structural components.
Middle East & Africa and Latin America:
The Middle East & Africa (MEA) and Latin America together hold 13% of the global market, with growth driven by expanding construction and industrial projects. For instance, the Gulf Cooperation Council (GCC) countries, led by Saudi Arabia and the UAE, have over USD 1 trillion in ongoing infrastructure projects, boosting demand for durable and weather-resistant epoxy coatings. In Latin America, Brazil and Mexico are key contributors, benefiting from a growing automotive industry, valued at USD 80 billion in Mexico alone. Mexico’s vehicle production exceeded 3.5 million units in 2023, increasing the use of epoxy coatings in auto body protection. Brazil’s offshore oil drilling projects, with investments surpassing USD 40 billion, rely heavily on epoxy coatings for corrosion resistance in deep-sea pipelines.
Key Player Analysis:
- BASF SE
- E I DuPont de Nemours and Company
- Dow Chemical Company
- Huntsman Corporation
- 3M Company
- Kukdo Chemicals
- Nan Ya Plastics Corporation
- Hexion Inc.
- Olin Corporation
- Cytec Solvay Group
Competitive Analysis:
The epoxy resins paints market is highly competitive, with key players focusing on technological advancements, sustainability, and product innovation to strengthen their market position. Industry leaders such as PPG Industries, AkzoNobel, Sherwin-Williams, and BASF collectively account for over 40% of the global market share, leveraging their extensive R&D investments, which exceed USD 1.5 billion annually, to develop low-VOC and high-performance coatings that comply with strict environmental regulations. Companies are increasingly investing in nanotechnology-based epoxy coatings, which enhance abrasion resistance by up to 30% and extend lifespan by 40%, making them ideal for aerospace, automotive, and industrial applications. For instance, AkzoNobel's Interpon D2525 eco-efficient powder coatings have seen a 20% rise in adoption across Europe due to their environmental benefits and compliance with the EU's Green Deal objectives. Moreover, strategic mergers and acquisitions are shaping the competitive landscape, with Sherwin-Williams acquiring Valspar for USD 11.3 billion, expanding its global footprint and product portfolio. As sustainability regulations tighten worldwide, firms investing in bio-based and waterborne epoxy solutions are positioned to gain a competitive edge in the evolving market.
Recent Developments:
- In January 2025, BASF's Performance Materials division switched all its European plants to renewable electricity. This move supports the company's goal of enabling customers' green transformation and achieving climate targets.
- In February 2025, Huntsman announced it would unveil a new coating system with circular content at the European Coatings Show (ECS). The POLYRESYST® S4010C system contains up to 20% circular content and is developed for protective coating applications. It combines bio-based and recycled materials, improving elongation compared to existing standard systems.
- In July 2024, Hexion and Clariant announced a strategic collaboration to advance high-performance intumescent coatings.
Market Concentration & Characteristics:
The epoxy resins paints market is moderately concentrated, with a mix of global leaders and regional players competing through technological advancements, product innovation, and sustainability initiatives. Top manufacturers, including PPG Industries, AkzoNobel, Sherwin-Williams, and BASF, control a significant market share, collectively exceeding 40% of global sales. The market is characterized by high entry barriers due to extensive R&D requirements, stringent environmental regulations, and capital-intensive production processes. Companies are increasingly focusing on low-VOC, waterborne, and bio-based epoxy coatings to comply with global sustainability mandates. Regulatory frameworks like the EU’s REACH and the U.S. EPA’s VOC restrictions have accelerated the shift toward eco-friendly formulations. Additionally, mergers, acquisitions, and strategic partnerships are shaping market dynamics, allowing companies to expand their product portfolios and regional reach. As demand for high-performance coatings grows, innovation in nanotechnology and corrosion-resistant formulations will remain a key differentiator.
Report Coverage:
The research report offers an in-depth analysis based on Type, Technology, Application, and End-use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Sustainable coatings will drive market growth, with increasing demand for low-VOC, waterborne, and bio-based epoxy resins to comply with global environmental regulations.
- Advanced nanotechnology formulations will gain traction, enhancing durability, chemical resistance, and self-healing properties for high-performance applications in automotive, aerospace, and industrial sectors.
- Rising infrastructure development projects, especially in Asia-Pacific and the Middle East, will fuel demand for epoxy-based protective coatings in commercial and residential construction.
- Automotive and aerospace industries will expand their use of epoxy coatings, leveraging their high corrosion resistance, mechanical strength, and lightweight properties to improve fuel efficiency and longevity.
- Stringent environmental policies in North America and Europe will push manufacturers toward innovative, eco-friendly formulations, accelerating the transition from solvent-based to waterborne epoxy coatings.
- Mergers, acquisitions, and strategic partnerships will shape market dynamics, with key players expanding their portfolios and regional footprints to gain a competitive edge.
- The marine sector will increase adoption of epoxy coatings, driven by strict anti-corrosion standards and rising demand for durable coatings in shipbuilding.
- Renewable energy projects, particularly wind power, will drive demand for epoxy coatings, essential for enhancing the lifespan of wind turbine blades.
- Technological advancements in UV-curable and powder epoxy coatings will create new opportunities, offering faster curing times and improved environmental sustainability.
- Digitalization and AI-driven innovations in coating formulations and application processes will optimize efficiency, cost reduction, and product customization across industries.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the epoxy resins paints market?
What factors are driving the growth of the epoxy resins paints market?
Who are the major players in the epoxy resins paints market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Epoxy Resins Paints Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Epoxy Resins Paints Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 38,764.5 million → 2032: USD 53,051.89 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Epoxy Resins Paints Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Epoxy Resins Paints Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Epoxy Resins Paints Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Epoxy Resins Paints Market Drivers
- 3.3 Epoxy Resins Paints Market Restraints & Challenges
- 3.4 Epoxy Resins Paints Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Epoxy Resins Paints Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Epoxy Resins Paints Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Epoxy Resins Paints category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Epoxy Resins Paints Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Epoxy Resins Paints Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Epoxy Resins Paints market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Epoxy Resins Paints Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Epoxy Resins Paints Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Epoxy Resins Paints Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Epoxy Resins Paints (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Epoxy Resins Paints Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Epoxy Resins Paints Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Epoxy Resins Paints Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Epoxy Resins Paints Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Epoxy Resins Paints Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Epoxy Resins Paints Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Epoxy Resins Paints Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Epoxy Resins Paints Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Epoxy Resins Paints Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
