
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Epoxy Tooling Board Market Size 2024 | USD 205.2 million |
| Epoxy Tooling Board Market, CAGR | 4.7% |
| Epoxy Tooling Board Market Size 2032 | USD 296.31 million |
Market Overview:
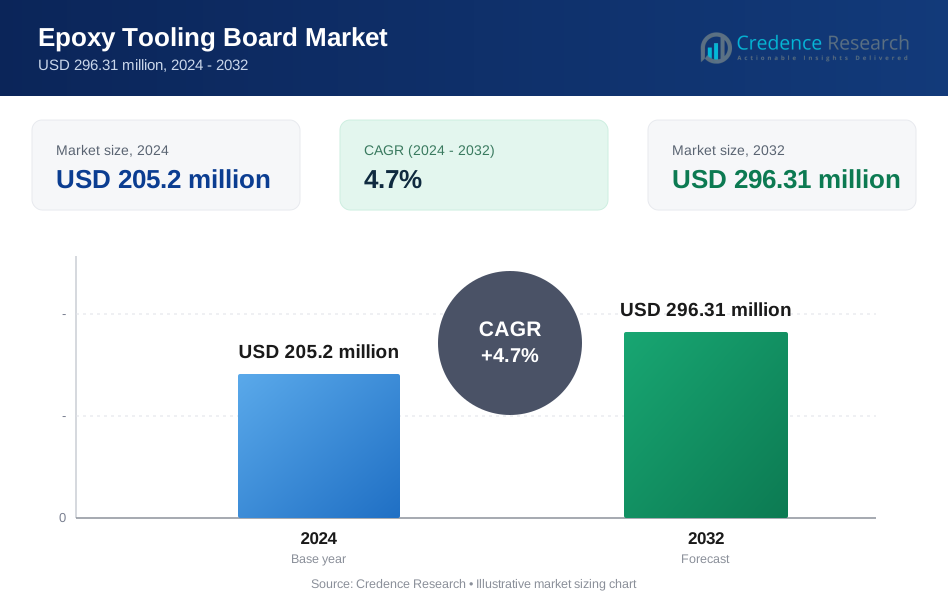
Epoxy Tooling Board Market size was valued at USD 205.2 million in 2024 and is anticipated to reach USD 296.31 million by 2032, at a CAGR of 4.7% during the forecast period (2024-2032).
Several factors contribute to the increasing demand for epoxy tooling boards. The aerospace and defense sectors utilize these boards for producing lightweight, high-strength components, enhancing fuel efficiency and performance. Furthermore, the emphasis on reducing material wastage and improving the accuracy of prototypes has led manufacturers to adopt epoxy tooling boards extensively. In the automotive industry, the shift towards electric vehicles has intensified the need for durable and precise tooling materials to support rapid prototyping and production processes. Additionally, the wind energy sector employs epoxy tooling boards in the manufacturing of turbine blades, owing to their excellent dimensional stability and resistance to environmental factors. The versatility and adaptability of epoxy tooling boards in diverse manufacturing processes further strengthen their demand across key industries.
Regionally, North America holds a significant share of the epoxy tooling board market, attributed to its well-established aerospace and automotive industries. The region's focus on advanced manufacturing technologies has further propelled the adoption of epoxy tooling boards. Additionally, government initiatives promoting sustainable manufacturing practices have encouraged the use of durable and efficient materials. Europe also demonstrates substantial market presence, driven by technological advancements and a robust automotive sector. The increasing demand for lightweight and eco-friendly materials supports the market's growth in this region. The Asia-Pacific region is expected to witness rapid growth, fueled by industrialization and expansion in the electronics and automotive manufacturing sectors. Increasing foreign investments and a surge in infrastructure development projects contribute significantly to the market’s expansion in this region.
Market Insights:
- The epoxy tooling board market is projected to grow at a CAGR of 4.7% during the forecast period (2024-2032), reaching USD 296.31 million by 2032.
- Rising demand from the aerospace and defense sectors is boosting market growth due to the need for lightweight, high-strength components that enhance fuel efficiency and performance.
- The shift towards electric vehicles in the automotive industry is increasing the demand for durable and precise tooling boards to support rapid prototyping and production processes.
- The wind energy sector is adopting epoxy tooling boards for manufacturing turbine blades, benefiting from their excellent dimensional stability and resistance to environmental factors.
- North America holds a significant market share due to its established aerospace and automotive industries, along with government initiatives promoting sustainable manufacturing.
- Europe demonstrates strong growth, driven by technological advancements, the demand for lightweight and eco-friendly materials, and expansion in the automotive sector.
- The Asia-Pacific region is witnessing rapid growth, supported by industrialization, expanding electronics and automotive manufacturing sectors, and increasing foreign investments.
Market Drivers:
Increasing Demand for Lightweight and High-Performance Materials
The global epoxy tooling board market is experiencing significant growth, primarily driven by the escalating demand for lightweight and high-performance materials across various industries. In sectors such as aerospace, automotive, and marine, manufacturers are increasingly adopting epoxy tooling boards to enhance fuel efficiency and overall performance. These boards offer exceptional dimensional stability, low thermal expansion, and excellent machinability, making them ideal for producing precise and complex components. For instance, Boeing has reported substantial weight reductions in their aircraft components by utilizing epoxy tooling boards in their manufacturing processes, leading to improved fuel efficiency and reduced emissions. The trend towards weight reduction without compromising structural integrity has positioned epoxy tooling boards as a preferred choice for tooling and prototyping applications.
Advancements in Manufacturing Technologies
Technological advancements in manufacturing processes have significantly contributed to the growth of the epoxy tooling board market. The integration of Computer Numerical Control (CNC) machining and 3D printing technologies has enabled manufacturers to produce intricate designs with high precision, thereby reducing production time and costs. Epoxy tooling boards are particularly compatible with these advanced techniques due to their superior machinability and ability to maintain dimensional accuracy under varying thermal conditions. For instance, Airbus has successfully implemented advanced CNC machining techniques with epoxy tooling boards to create complex molds for their A350 XWB aircraft components, resulting in faster production cycles and improved part quality. This synergy between material properties and manufacturing capabilities has led to increased adoption of epoxy tooling boards in industries aiming for rapid prototyping and efficient production workflows.
Expansion of Renewable Energy Sector
The burgeoning renewable energy sector, especially wind energy, has emerged as a significant driver for the epoxy tooling board market. Epoxy tooling boards are extensively used in the fabrication of wind turbine blades, where precision and durability are paramount. Their ability to withstand high temperatures and environmental factors ensures the longevity and efficiency of turbine components.. As global initiatives towards sustainable energy intensify, the demand for epoxy tooling boards in the production of renewable energy infrastructure is expected to rise, thereby propelling market growth.
Focus on Cost-Effective and Sustainable Solutions
Industries are increasingly focusing on cost-effective and sustainable manufacturing solutions, further driving the adoption of epoxy tooling boards. These boards offer a cost-efficient alternative to traditional metal molds, reducing material wastage and energy consumption during production. Additionally, the development of eco-friendly and recyclable epoxy tooling boards aligns with global sustainability goals, attracting manufacturers committed to reducing their environmental footprint. This shift towards sustainable practices not only enhances corporate responsibility but also meets the growing consumer demand for environmentally conscious products, thereby fostering market expansion.
Market Trends:
Integration of Advanced Manufacturing Technologies
The epoxy tooling board market is witnessing a significant trend toward the integration of advanced manufacturing technologies. The adoption of Computer Numerical Control (CNC) machining and 3D printing has enhanced the precision and efficiency of tooling board fabrication. For instance, Base Materials has introduced the BE890 high-performance, toughened epoxy tooling board designed for thermoforming and vacuum forming processes, which creates minimal dust during machining. These technologies enable the production of complex geometries with high accuracy, reducing material wastage and production time. The compatibility of epoxy tooling boards with these advanced methods has made them a preferred choice for industries aiming to streamline their prototyping and production processes.
Emphasis on Sustainability and Eco-Friendly Materials
There is a growing emphasis on sustainability within the epoxy tooling board market. Manufacturers are developing eco-friendly and recyclable tooling boards to align with global environmental goals. For instance, Trelleborg has introduced TC760X, an eco-friendly, dust-free tooling board that flakes rather than chips during machining, reducing airborne particles and environmental impact. The incorporation of bio-based resins and recyclable materials in tooling boards reduces environmental impact while maintaining performance standards. This shift towards sustainable materials reflects the industry's commitment to reducing its carbon footprint and meeting the increasing demand for environmentally responsible products.
Diversification of Application Sectors
The application scope of epoxy tooling boards is diversifying beyond traditional sectors. While aerospace and automotive industries remain significant consumers, there is increasing utilization in renewable energy, particularly in wind turbine manufacturing. The boards' properties, such as dimensional stability and thermal resistance, make them suitable for creating molds for turbine blades. This diversification into new sectors underscores the versatility of epoxy tooling boards and opens new avenues for market growth.
Regional Market Expansion
The epoxy tooling board market is experiencing notable regional expansion. North America maintains a significant market share due to its established aerospace and automotive industries. Europe is witnessing growth driven by technological advancements and a robust automotive sector. The Asia-Pacific region is emerging as a rapidly growing market, propelled by industrialization and expansion in electronics and automotive manufacturing. This regional expansion reflects the global demand for epoxy tooling boards across diverse industrial landscapes.
Market Challenges Analysis:
High Production Costs
The epoxy tooling board market faces significant challenges due to the high cost of raw materials, such as epoxy resins and reinforcement agents. These materials are critical for producing tooling boards with the desired properties, including high thermal resistance and dimensional stability. Fluctuations in global raw material prices, driven by supply chain disruptions and geopolitical factors, often translate into increased production costs for manufacturers. Additionally, the energy-intensive nature of epoxy tooling board production further escalates operational expenses, impacting profit margins. This can make epoxy tooling boards less competitive compared to alternatives like urethane tooling boards, particularly for small-scale manufacturers or industries with tight budgets. Manufacturers must explore cost-efficient production techniques and source sustainable raw materials to mitigate these challenges and enhance market competitiveness.
Environmental and Regulatory Concerns
The production and disposal of epoxy resins involve certain environmental impacts, and stricter regulations on the use of chemicals and waste management can affect the market. The presence of hazardous emissions during production, along with difficulties in recycling epoxy materials, poses environmental risks that require strategic mitigation. Manufacturers need to invest in sustainable production processes and develop eco-friendly alternatives to address these concerns and comply with regulations. Moreover, evolving international standards for environmental safety add complexity to compliance, requiring continuous adaptation and monitoring. Failure to adapt to these environmental and regulatory challenges can result in increased operational costs and limit market growth. Therefore, a proactive approach towards environmental stewardship and regulatory compliance will be essential for long-term sustainability in the epoxy tooling board market.
Market Opportunities:
The epoxy tooling board market presents significant growth opportunities driven by increasing demand from emerging sectors such as renewable energy, aerospace, and electric vehicles. As the global focus on sustainable energy intensifies, the wind energy sector is witnessing rapid expansion, creating a substantial demand for durable and high-precision tooling materials. Epoxy tooling boards, known for their excellent thermal stability and dimensional accuracy, are ideal for manufacturing wind turbine components, offering manufacturers a reliable solution to meet evolving industry requirements. Similarly, the aerospace industry’s emphasis on lightweight and high-strength materials opens opportunities for the extensive use of epoxy tooling boards in prototyping and component production. The automotive sector, particularly with the growing shift towards electric vehicles, also presents a fertile market for epoxy tooling boards. These materials facilitate efficient prototyping and production, aligning with the industry's push for innovative and sustainable manufacturing processes.
Another promising opportunity lies in the advancement of manufacturing technologies and the rising adoption of automation. The integration of CNC machining and additive manufacturing processes offers new prospects for epoxy tooling boards, enabling faster, more efficient production while reducing material waste. Furthermore, the development of eco-friendly and recyclable epoxy formulations aligns with the global trend towards sustainability, creating avenues for market expansion. As industries increasingly prioritize environmentally responsible practices, the demand for sustainable tooling solutions is likely to surge. Manufacturers investing in research and innovation to develop advanced, cost-effective, and sustainable epoxy tooling boards will be well-positioned to capitalize on these emerging opportunities and expand their market presence.
Market Segmentation Analysis:
By Density
Epoxy tooling boards are categorized based on their density, typically into three segments: 600–800 kg/m³, 800–1000 kg/m³, and above 1000 kg/m³. The 600–800 kg/m³ segment is anticipated to experience the fastest growth, attributed to its suitability for a wide range of temperatures, making it ideal for creating master models and patterns across various industries. Boards within the 800–1000 kg/m³ range offer a balance between strength and machinability, catering to applications requiring both durability and ease of processing. High-density boards, exceeding 1000 kg/m³, are preferred in scenarios demanding exceptional mechanical strength and thermal resistance, such as high-temperature composite molding processes.
By Application
The application spectrum of epoxy tooling boards encompasses several key industries, including aerospace and defense, automotive, wind energy, and marine sectors. The aerospace and defense segment is projected to witness substantial growth, driven by the escalating need for cost-effective, dimensionally stable, and high-temperature resistant tooling solutions capable of replacing more expensive metal and wooden molds. In the automotive industry, epoxy tooling boards facilitate greater design flexibility and innovation, supporting rapid prototyping and the development of lightweight components. The wind energy sector utilizes these boards in the fabrication of turbine blades, benefiting from their excellent dimensional stability and resistance to environmental factors. The marine industry also employs epoxy tooling boards for producing durable and precise molds for various marine components.
Segmentations:
By Density
- 600–800 kg/m³
- 800–1000 kg/m³
- Above 1000 kg/m³
By Application
- Aerospace and Defense
- Automotive
- Wind Energy
- Marine
- Industrial Equipment
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds 19% of the global epoxy tooling board market share, driven by its well-established aerospace and automotive industries. This region extensively utilizes epoxy tooling boards for prototyping and manufacturing processes. The United States, in particular, has a robust aerospace sector, with manufacturers relying on these boards for creating precise molds and models. Additionally, the region's focus on advanced manufacturing technologies and rapid prototyping further bolsters demand. The presence of key market players and continuous investments in research and development contribute to sustained growth within this region. The increasing adoption of electric vehicles is also creating a greater need for high-precision and lightweight tooling solutions. Furthermore, government initiatives supporting advanced manufacturing technologies are expected to strengthen the regional market.
Europe
Europe accounts for 34% of the global epoxy tooling board market share, supported by a strong automotive industry and a focus on lightweight and fuel-efficient vehicles. Countries like Germany, France, and the United Kingdom are leaders in adopting these boards for designing and testing automotive components. Moreover, Europe's stringent environmental regulations encourage the adoption of materials that facilitate sustainable manufacturing practices. The aerospace sector in Europe also significantly contributes to the market, with epoxy tooling boards used for developing advanced aircraft components. Technological advancements and a skilled workforce further enhance the region’s market position. Additionally, the growing emphasis on reducing carbon emissions is driving innovation in sustainable materials. The rise in renewable energy projects, especially wind energy, is expected to further stimulate demand for epoxy tooling boards in the region.
Asia-Pacific
Asia-Pacific holds 29% of the global epoxy tooling board market share, emerging as a rapidly growing region due to rapid industrialization and the expansion of electronics and automotive manufacturing sectors. Countries such as China, Japan, and India are experiencing increased production activities, leading to higher demand for efficient prototyping and tooling solutions. The region's dynamic market conditions and substantial investments in infrastructure development further drive market growth. Additionally, the growing focus on renewable energy sources, particularly wind energy, is accelerating the demand for epoxy tooling boards used in manufacturing turbine components. The increasing presence of global manufacturing hubs and cost-effective production processes is making the region attractive for investment. Moreover, government policies promoting local manufacturing and technological advancement are expected to further propel market growth.
Key Player Analysis:
- Huntsman Corporation
- Base Group
- Sika AG
- RAMPF Group Inc.
- Axson Technologies
- Trelleborg AB
- General Plastics Manufacturing Company
- Alro Plastics
- Demacq Recycling Company
- Coastal Enterprises Inc.
Competitive Analysis:
The epoxy tooling board market is characterized by intense competition, with key players focusing on innovation, product development, and strategic partnerships to strengthen their market presence. Companies are investing in advanced manufacturing technologies and sustainable product solutions to meet evolving industry demands. The market is also witnessing a trend towards the development of eco-friendly and recyclable epoxy boards, addressing increasing environmental concerns.
Competitive strategies include expanding production capacities, enhancing product portfolios, and establishing strong distribution networks to increase global reach. For instance, Huntsman Corporation has introduced a range of bio-based products for the automotive industry, including ACOUSTIFLEX® HR BIO, RUBIFLEX® HR BIO, RUBIFLEX® H BIO, and RUBITRIM® SR BIO, which align with the growing demand for sustainable solutions in manufacturing. Additionally, firms are emphasizing research and development to create high-performance tooling boards that offer superior thermal stability and durability. Price competitiveness, quality assurance, and customization options play crucial roles in maintaining a competitive edge. As the demand for precision tooling solutions grows across industries like aerospace, automotive, and renewable energy, companies are striving to differentiate their offerings and expand their market share through technological advancements and customer-centric strategies.
Recent Developments:
- In August 2022, Trelleborg AB, a Swedish engineering company, announced a cash acquisition of Minnesota Rubber and Plastics for USD 1 billion. Minnesota Rubber and Plastics was previously acquired by KKR in 2018 from Norwest Equity Partners.
- In August 2022, Huntsman Corporation finalized a definitive agreement with Archroma, a company owned by SK Capital Partners, to divest its Textile Effects division. The transaction was valued at USD 718 million, which included the assumption of net underfunded pension liabilities totaling USD 125 million as of December 31, 2021.
Market Concentration & Characteristics:
The epoxy tooling board market is moderately concentrated, with a mix of established global players and regional manufacturers contributing to market dynamics. Key characteristics of the market include a strong focus on product innovation, technological advancements, and sustainable manufacturing practices. Companies prioritize the development of high-performance, durable, and eco-friendly epoxy tooling boards to meet evolving industry demands, particularly in sectors such as aerospace, automotive, and renewable energy. The market is also defined by significant investments in research and development to enhance product quality and performance. Competitive differentiation is driven by factors such as product customization, superior thermal stability, and precision in prototyping. Additionally, strategic collaborations, mergers, and acquisitions are common approaches for expanding market reach and strengthening competitive positions. The presence of stringent environmental regulations and the growing demand for sustainable solutions further shape the market's characteristics, encouraging manufacturers to innovate and adopt eco-conscious production practices.
Report Coverage:
The research report offers an in-depth analysis based on Density, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The epoxy tooling board market is expected to witness steady growth driven by increasing demand from industries such as aerospace, automotive, and renewable energy.
- Advancements in manufacturing technologies, including CNC machining and additive manufacturing, will enhance precision and efficiency, supporting market expansion.
- The growing emphasis on sustainable and eco-friendly manufacturing solutions will encourage the development of recyclable and bio-based epoxy tooling boards.
- Increased investment in research and development will drive innovation, leading to the production of advanced tooling boards with enhanced thermal stability and durability.
- The automotive industry's shift towards electric vehicles will boost demand for lightweight and high-performance tooling materials for prototyping and production.
- Rising infrastructure development, particularly in emerging economies, will create new opportunities for the use of epoxy tooling boards in industrial applications.
- The expansion of the wind energy sector will further increase the demand for epoxy tooling boards used in the production of turbine blades.
- Manufacturers are likely to focus on enhancing supply chain efficiencies to meet growing demand and minimize production delays.
- Strategic partnerships and collaborations will be key strategies for companies seeking to expand their global presence and strengthen competitive advantage.
- Regulatory pressures for sustainable practices will influence product innovation, pushing manufacturers towards eco-conscious production processes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the epoxy tooling board market?
Why is the automotive sector adopting epoxy tooling boards?
Which region holds a significant share of the epoxy tooling board market?
Which region is expected to witness the fastest market growth?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Epoxy Tooling Board Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Epoxy Tooling Board Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 205.2 million → 2032: USD 296.31 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Epoxy Tooling Board Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Epoxy Tooling Board Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Epoxy Tooling Board Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Epoxy Tooling Board Market Drivers
- 3.3 Epoxy Tooling Board Market Restraints & Challenges
- 3.4 Epoxy Tooling Board Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Epoxy Tooling Board Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Epoxy Tooling Board Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Epoxy Tooling Board category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Epoxy Tooling Board Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Epoxy Tooling Board Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Epoxy Tooling Board market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Epoxy Tooling Board Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Epoxy Tooling Board Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Epoxy Tooling Board Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Epoxy Tooling Board (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Epoxy Tooling Board Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Epoxy Tooling Board Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Epoxy Tooling Board Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Epoxy Tooling Board Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Epoxy Tooling Board Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Epoxy Tooling Board Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Epoxy Tooling Board Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Epoxy Tooling Board Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Epoxy Tooling Board Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
