
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| F-Style Jugs Market Size 2024 | USD 151502 million |
| F-Style Jugs Market, CAGR | 4.1% |
| F-Style Jugs Market Size 2032 | USD 208941 million |
Market Overview:
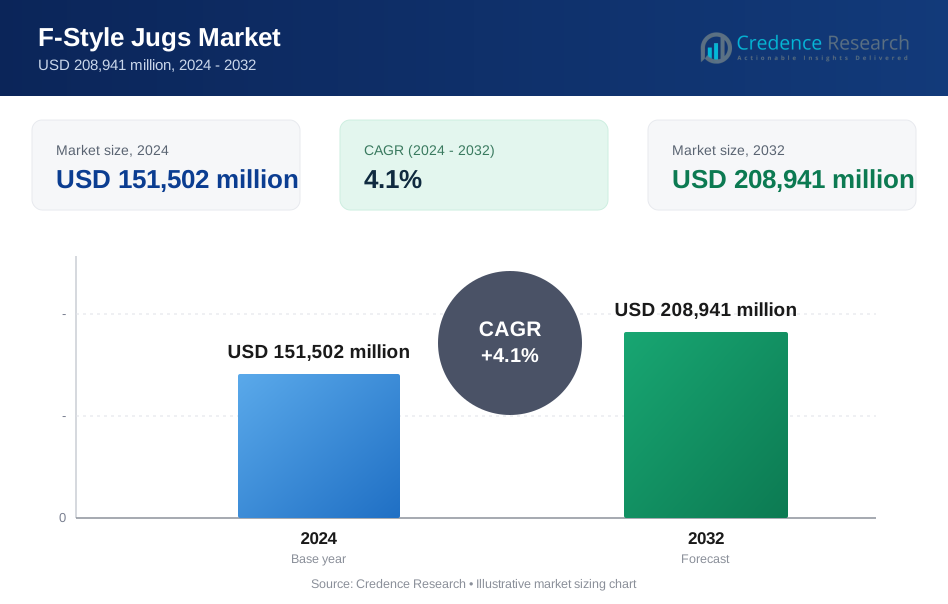
The F-Style Jugs Market is projected to grow from USD 151502 million in 2024 to an estimated USD 208941 million by 2032, with a compound annual growth rate (CAGR) of 4.1% from 2024 to 2032.
The primary drivers of the F-Style jugs market include their versatile usage, structural efficiency, and evolving material innovations. F-Style jugs are widely used for storing and transporting liquids including oils, syrups, detergents, industrial chemicals, and cleaning agents. Their rectangular shape, integrated handle, and tight-sealing cap offer advantages in handling, stacking, and controlled pouring—key factors for logistics and end-user convenience. Industries prefer them over round containers for their space-saving form and leak-resistant construction. Another important growth factor is the increasing use of lightweight and recyclable plastic materials like HDPE and PP, which help reduce both manufacturing and transport costs. This aligns with broader sustainability goals and compliance with plastic regulations. Manufacturers are also investing in advanced barrier technologies, such as fluorinated HDPE, to improve chemical resistance for sensitive contents. These innovations expand the applicability of F-Style jugs to sectors requiring stringent packaging standards. Growing awareness of sustainability and regulatory measures such as extended producer responsibility (EPR) programs further encourage the use of recyclable and reusable packaging solutions, adding momentum to the market.
Regionally, North America and Europe currently dominate the F-Style jugs market due to their mature manufacturing sectors and widespread adoption in regulated industries such as food processing, pharmaceuticals, and chemicals. These regions have well-established packaging standards and environmental policies, prompting companies to adopt durable, tamper-evident, and sustainable packaging designs. North American manufacturers, in particular, are investing in fluorinated and barrier-enhanced jugs to meet specialized chemical handling requirements. Europe’s strong focus on circular economy practices has also led to increased demand for jugs made with recycled or bio-based plastic resins. Meanwhile, the Asia-Pacific region is expected to exhibit the fastest growth over the next decade, driven by rapid industrialization, urban expansion, and rising demand from agriculture, food, and industrial chemical sectors. Competitive manufacturing costs and an expanding consumer base further boost the region’s potential. Latin America and the Middle East & Africa are emerging markets, where adoption is increasing gradually in line with improvements in industrial infrastructure and regulatory environments.
Market Insights:
- The F style jugs market is projected to grow from USD 151,502 million in 2024 to USD 208,941 million by 2032, registering a CAGR of 4.1% during the forecast period, driven by rising demand across industrial and consumer sectors.
- Versatile usage in storing and transporting liquids such as oils, syrups, detergents, chemicals, and cleaners supports broad adoption across food, agriculture, automotive, and household product industries.
- Manufacturers are investing in lightweight and recyclable plastics like HDPE and PP to reduce costs, improve logistics, and align with growing environmental and regulatory expectations.
- Fluorinated HDPE and other barrier technologies are enabling increased chemical resistance, extending the applicability of F style jugs in hazardous and high-performance environments.
- The rectangular design of F style jugs enhances handling, stacking, and storage efficiency, which benefits logistics, warehousing, and industrial distribution systems.
- Challenges include raw material price volatility and global supply chain disruptions, which pressure profit margins and complicate manufacturing consistency for smaller players.
- North America and Europe lead in adoption due to established industries and environmental regulations, while Asia-Pacific is set to grow fastest due to rapid industrial expansion and favorable manufacturing economics.
Market Drivers:
Rising Demand Across Industrial and Consumer Sectors:
The F style jugs market is gaining traction due to growing demand from a wide range of end-use industries. Food and beverage, automotive, agriculture, household chemicals, and industrial chemical sectors rely on these jugs for packaging, storage, and transportation of liquid products. Their sturdy build, convenient handles, and controlled pouring features make them ideal for both bulk and retail packaging. In the consumer space, applications include motor oils, cleaners, and detergents, while industries use them for solvents, lubricants, and agrochemicals. The jugs’ compatibility with various viscosities and chemical compositions supports their use across sectors. This widespread adoption is a key factor driving market expansion.
- For instance, The Cary Company reported in 2024 that its F style jugs were used by over 500 industrial clients for packaging more than 20 million gallons of automotive fluids and chemicals in a single year.
Shift Toward Lightweight, Recyclable, and Sustainable Packaging:
Sustainability and regulatory compliance are shaping product development and material selection in the F style jugs market. Manufacturers are responding to growing pressure to reduce environmental impact by using recyclable plastics such as HDPE and polypropylene. Lightweight resin formulations reduce transportation costs and carbon emissions, offering a cost-effective solution to distributors. Regulatory policies such as extended producer responsibility (EPR) are prompting producers to introduce reusable and recyclable formats. Bio-based and post-consumer recycled (PCR) plastics are also gaining attention. These trends position the F style jug as a viable and compliant packaging option for environmentally conscious companies.
- For instance, Berlin Packaging introduced a lightweight F style jug in 2024 that reduced plastic usage by 15%, resulting in an annual reduction of over 150 metric tons of virgin plastic.
Improved Handling, Storage, and Transportation Efficiency:
Design efficiency is another critical factor fueling growth in the F style jugs market. The rectangular shape of these jugs allows for efficient stacking and space optimization during storage and shipping. Ergonomic handles facilitate ease of use for end consumers and workers handling bulk volumes. Tamper-evident closures and leak-resistant caps enhance safety and usability in transit. This design adaptability lowers damage risk and supports streamlined distribution processes. It helps businesses cut down on warehousing and freight costs while ensuring product integrity. This performance edge makes the format increasingly popular for industrial and commercial supply chains.
Advancement in Barrier Technologies and Application Versatility:
Technical innovation continues to drive product evolution in the F style jugs market. Barrier enhancements such as fluorinated HDPE provide increased chemical resistance, extending jug life and expanding usability in harsh environments. This capability is crucial for applications involving solvents, agrochemicals, and reactive compounds. Customization options in spouts, closures, and labeling also help businesses tailor packaging for different market segments. It enables compatibility with automated filling lines, enhancing manufacturing efficiency. These advancements reinforce the jug’s role in maintaining safety, quality, and compliance across critical industries.
Market Trends:
Growing Focus on Sustainable and Circular Packaging Solutions:
Sustainability continues to dominate packaging trends, shaping product choices and design innovations in the F style jugs market. Companies are adopting eco-friendly practices by incorporating recycled content, bio-based resins, and reusable formats into their jug offerings. High-density polyethylene (HDPE) remains the most used material, but demand for post-consumer recycled (PCR) HDPE is increasing steadily. Brands and manufacturers aim to align with regulations targeting single-use plastics and carbon footprint reduction. Packaging buyers prioritize solutions that balance durability, recyclability, and cost-effectiveness. This trend supports the long-term transition toward circular economy packaging models across sectors.
- For instance, according to the U.S. Environmental Protection Agency, the recycling rate for HDPE containers reached 31% in 2023, and SKS Bottle & Packaging reported that over 40% of its F style jugs shipped in 2024 contained PCR content.
Integration of Smart Packaging Features for Tracking and Compliance:
The need for traceability, quality assurance, and compliance is encouraging the adoption of smart packaging technologies. In the F style jugs market, companies are integrating features such as QR codes, RFID tags, and tamper-evident indicators. These features help monitor product movement, verify authenticity, and support inventory management. Industries handling chemicals, lubricants, and pharmaceuticals benefit from improved safety and traceability during storage and transportation. Smart packaging enhances supply chain transparency and regulatory compliance without altering jug structure. It adds value to the product by improving user experience and operational efficiency.
- For instance, F style jugs market, companies are integrating features such as QR codes, RFID tags, and tamper-evident indicators.
Customizable Design Options Supporting Brand Differentiation:
Customization is emerging as a key trend in packaging, especially for brands seeking market differentiation. The F style jugs market reflects this shift with a wide range of options in color, closure type, handle configuration, and label design. Businesses in retail and industrial segments use custom jugs to create a recognizable brand presence and ensure functionality for specific contents. Labeling options now support both compliance and marketing needs, combining regulatory details with visual appeal. Embossed logos, matte finishes, and printed graphics increase shelf visibility in competitive product categories. Custom design flexibility helps manufacturers address niche demands without compromising performance.
Adoption of Barrier and Multi-Layer Technologies for Performance Enhancement:
The performance demands of modern applications are driving the use of barrier-enhancing technologies. In the F style jugs market, multi-layer construction and fluorinated inner surfaces help preserve product quality and extend shelf life. This trend is prominent in industries dealing with corrosive chemicals, volatile solvents, and sensitive agricultural liquids. Barrier technologies prevent leaching, permeation, and structural degradation under pressure or temperature variation. Manufacturers gain access to broader end-use markets with these improvements, including pharmaceuticals and industrial chemicals. It enables packaging solutions to meet strict safety and quality standards across global supply chains.
Market Challenges Analysis:
Volatility in Raw Material Prices and Supply Chain Disruptions:
One of the key challenges in the F style jugs market is the volatility of raw material prices, particularly for plastics such as HDPE and polypropylene. Fluctuations in crude oil prices directly impact production costs, creating uncertainty for manufacturers and suppliers. Supply chain disruptions, including transportation delays and resin shortages, further complicate procurement and lead to longer delivery timelines. Small and mid-sized manufacturers face greater strain in maintaining profit margins under these conditions. It creates pressure on pricing strategies and reduces flexibility in meeting sudden demand surges. This instability hampers production planning and limits growth for cost-sensitive segments.
Stringent Environmental Regulations and Recycling Infrastructure Gaps:
The F style jugs market must also navigate tightening environmental regulations and gaps in global recycling infrastructure. Policies targeting single-use plastics, emissions reduction, and extended producer responsibility increase compliance burdens for manufacturers. While demand for recyclable and sustainable packaging grows, many regions still lack the necessary facilities to collect, sort, and process post-consumer plastic waste effectively. It restricts the adoption of recycled-content jugs and raises questions about actual sustainability performance. Companies must invest in material innovation and supply chain collaboration to meet evolving compliance standards. Balancing regulatory expectations with operational feasibility presents an ongoing challenge for industry stakeholders.
Market Opportunities:
Expansion into Emerging Markets with Industrial Growth Potential:
Rapid industrialization and urban development in emerging economies present strong growth prospects for the F style jugs market. Countries across Asia-Pacific, Latin America, and Africa are experiencing rising demand for safe, efficient liquid packaging in agriculture, automotive, construction, and chemicals. Local manufacturers seek durable and cost-effective containers for bulk distribution, creating new demand across mid-tier industrial supply chains. It supports regional expansion for global players and offers opportunities for joint ventures and localized production. Increasing government investment in infrastructure and agriculture further fuels packaging needs. Companies that adapt product lines to regional specifications can capture untapped market share.
Rising Demand for Eco-Friendly and Functional Packaging Solutions:
Sustainability trends continue to reshape purchasing behavior and product development, offering innovation opportunities in the F style jugs market. Brands and end-users are looking for packaging that meets both environmental goals and performance expectations. High-purity applications such as pharmaceuticals, agrochemicals, and personal care call for enhanced barrier protection without compromising recyclability. It opens pathways for advanced materials, multi-layer jugs, and closed-loop packaging systems. Companies that invest in R&D for lightweight, reusable, and biodegradable formats can create long-term differentiation. Collaborations with recycling firms and material scientists support product diversification aligned with green packaging objectives.
Market Segmentation Analysis:
By Material
The F style jugs market is largely driven by plastic variants, especially those made from high-density polyethylene (HDPE) due to their durability, cost efficiency, and recyclability. Metal containers, such as aluminum and steel-based F-style cans, cater to industrial applications requiring high chemical resistance or extended shelf life.
- For instance, Metal containers, such as aluminum and steel-based F-style cans, cater to industrial applications requiring high chemical resistance or extended shelf life.
By Application/End-Use Industry
It serves diverse industries including food and beverage, chemicals, agriculture, pharmaceuticals, and automotive. High usage in storing oils, detergents, coolants, and liquid medicines makes these jugs critical in logistics and product preservation. The chemical and agriculture sectors remain key volume drivers due to the safe containment of hazardous liquids.
- For instance, Kaufman Container supplied F style jugs to agricultural chemical companies in 2024.
By Packaging Type
F Style Jugs dominate retail and industrial markets for plastic-based liquids, while F Style Cans, typically metal, are favored in chemical, personal care, and lubricant packaging due to their rigid structure and secure sealing properties.
By Feature/Design
Demand for stackable, tamper-proof, and ergonomic designs enhances operational convenience and consumer safety. Customization options in shape, labelling, and size help brands differentiate in competitive shelf environments.
By Sustainability
Recyclable HDPE and metals align with regulatory trends and corporate sustainability goals. Emerging use of biodegradable plastics signals innovation and responsiveness to environmental concerns.
By Distribution Channel
Online retail is expanding due to growing e-commerce penetration, though traditional wholesale remains strong in industrial and agricultural supply networks.
Segmentation:
By Material
- Plastic (primarily High-Density Polyethylene, HDPE)
- Metal (including aluminum and steel, especially for F-style cans)
By Application/End-Use Industry
- Food and Beverage
- Chemical Industry
- Automotive Industry
- Pharmaceuticals
- Agriculture
- Cleaning Products
- Personal Care
By Packaging Type
- F Style Jugs
- F Style Cans
By Feature/Design
- Stackable and easy to transport
- Tamper-proof seals and ergonomic spouts
- Customization options (size, shape, printing/branding)
By Sustainability
- Recyclable and eco-friendly materials
- Biodegradable plastics
By Distribution Channel
- Online retail and e-commerce
- Traditional retail and wholesale
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America and Europe Maintain Dominant Market Share
North America and Europe collectively account for over 55% of the global market share in the F style jugs market. These regions benefit from advanced manufacturing infrastructure, strict regulatory frameworks, and high demand across industrial and consumer sectors. The United States, Canada, Germany, France, and the United Kingdom represent key consumption centers driven by usage in food processing, chemicals, pharmaceuticals, and automotive maintenance. Strong environmental regulations encourage the use of recyclable and tamper-resistant packaging solutions, pushing manufacturers to innovate with barrier-enhanced and lightweight formats. Companies in these regions are also early adopters of fluorinated HDPE jugs and other performance-focused technologies. The market remains highly competitive due to a strong presence of multinational packaging firms and high-value product lines.
Asia-Pacific Emerges as the Fastest-Growing Region
Asia-Pacific holds approximately 30% of the F style jugs market share and is projected to record the fastest CAGR during the forecast period. Growth in this region is fueled by rapid industrialization, expanding urban populations, and rising demand for cost-effective packaging in sectors such as agriculture, food processing, and chemicals. China, India, Japan, and Southeast Asian countries are investing in domestic production capacity and upgrading logistics infrastructure. The region’s competitive labor costs and favorable trade policies support large-scale manufacturing of plastic containers. Manufacturers are responding to sustainability mandates by adopting recyclable and lightweight materials. It is quickly evolving into a global supply base for high-volume packaging formats.
Latin America and Middle East & Africa Offer Long-Term Potential
Latin America and the Middle East & Africa currently represent a smaller combined share of around 15% in the F style jugs market. Adoption rates remain moderate due to infrastructural limitations and fragmented industrial ecosystems. However, increasing investment in agriculture, construction, and chemicals is creating new demand for durable, cost-efficient jugs for bulk transport and storage. Brazil, Mexico, South Africa, and the UAE are key countries showing consistent year-on-year growth. Import reliance is slowly decreasing as regional players ramp up local manufacturing to serve domestic markets. It has the potential to capture more share over time with better regulatory alignment and technology adoption.
Key Player Analysis:
- The Cary Company
- L. Smith
- General Bottle Supply
- SKS Bottle & Packaging
- TricorBraun
- Berlin Packaging
- Kaufman Container
Competitive Analysis:
The F style jugs market features a moderately fragmented competitive landscape, with key players focusing on product customization, material innovation, and supply chain efficiency to maintain their market positions. Companies such as The Cary Company, C.L. Smith, General Bottle Supply, SKS Bottle & Packaging, TricorBraun, Berlin Packaging, and Kaufman Container serve a broad range of industries with both stock and custom packaging solutions. These firms compete on the basis of product variety, container durability, regulatory compliance, and fulfillment speed. The F style jugs market continues to attract investment in recyclable and barrier-enhanced containers to meet sustainability and performance demands. It reflects a growing emphasis on bulk packaging, private-label capabilities, and partnerships with end-use industries. Manufacturers are also expanding their digital sales channels to improve access for small- and mid-sized buyers. Competitive differentiation increasingly depends on value-added services such as labeling, closures, and logistics support.
Recent Developments:
- In June 2024, Berlin Packaging introduced a lightweight F Style jug that reduces plastic usage by 15% compared to previous models, supporting sustainability goals for clients in the cleaning and agricultural sectors.
- In January 2025, TricorBraun completed the acquisition of a regional packaging distributor specializing in industrial containers, significantly expanding its F Style jug offerings and market reach in North America.
Market Concentration & Characteristics:
The F style jugs market shows moderate market concentration, with a mix of established packaging giants and regional suppliers catering to varied industrial and commercial needs. It is characterized by strong product standardization in core applications and growing demand for customizable, value-added solutions in niche markets. The market favors companies with vertically integrated capabilities, broad distribution networks, and expertise in plastic molding or metal can manufacturing. Demand is driven by functionality, cost-efficiency, and regulatory compliance, which shapes both product design and material selection. The market maintains stable demand across sectors such as chemicals, automotive, agriculture, and food, making it resilient to short-term economic fluctuations. It exhibits low entry barriers in terms of manufacturing but highly competitive pressure in terms of volume pricing, supply reliability, and sustainability compliance.
Report Coverage:
The research report offers an in-depth analysis based on By Material, By Application/End-Use Industry, By Packaging Type, By Feature/Design, By Sustainability, By Distribution Channel and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The F style jugs market is expected to maintain steady growth driven by consistent demand in chemical, agricultural, and automotive sectors.
- Sustainability initiatives will encourage wider adoption of recyclable and biodegradable materials in jug production.
- Asia-Pacific will lead volume growth due to expanding manufacturing capacity and rising industrial consumption.
- E-commerce and digital procurement platforms will increase visibility and sales opportunities for mid-sized suppliers.
- Customization in shape, color, and closure types will become a competitive differentiator across retail and industrial packaging.
- Investment in advanced barrier technologies will support usage in high-performance and hazardous material applications.
- Regulatory pressure will drive innovation in tamper-evident and eco-compliant packaging formats.
- Automation in filling and packaging lines will raise demand for jugs compatible with high-speed equipment.
- Raw material volatility may push manufacturers to diversify resin sourcing and explore alternative substrates.
- Strategic partnerships between packaging firms and end-use industries will foster long-term supply agreements and product development.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the F Style Jugs market?
What factors are driving the growth of the F Style Jugs market?
What are the key segments within the F Style Jugs market?
Who are the major players in the F Style Jugs market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 F-Style Jugs Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global F-Style Jugs Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 151,502 million → 2032: USD 208,941 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 F-Style Jugs Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. F-Style Jugs Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 F-Style Jugs Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 F-Style Jugs Market Drivers
- 3.3 F-Style Jugs Market Restraints & Challenges
- 3.4 F-Style Jugs Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 F-Style Jugs Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 F-Style Jugs Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, F-Style Jugs category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 F-Style Jugs Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. F-Style Jugs Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the F-Style Jugs market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 F-Style Jugs Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 F-Style Jugs Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 F-Style Jugs Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in F-Style Jugs (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New F-Style Jugs Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global F-Style Jugs Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America F-Style Jugs Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe F-Style Jugs Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific F-Style Jugs Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America F-Style Jugs Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East F-Style Jugs Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa F-Style Jugs Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. F-Style Jugs Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
