
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| India 5G Fixed Wireless Access (FWA) Market Size 2024 | USD 863.30 million |
| India 5G Fixed Wireless Access (FWA) Market, CAGR | 29.21% |
| India 5G Fixed Wireless Access (FWA) Market Size 2032 | USD 11,725.46 million |
Market Overview
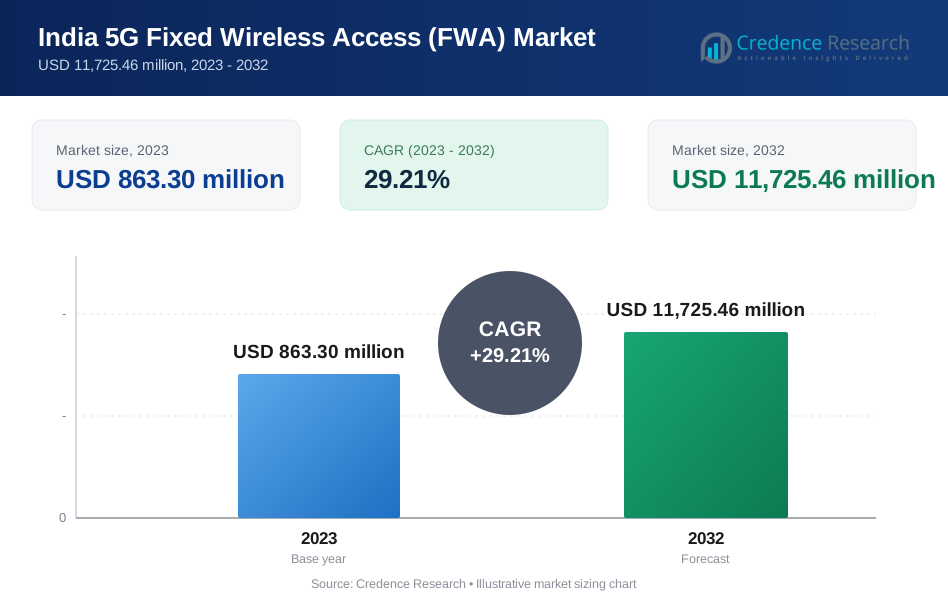
The India 5G Fixed Wireless Access (FWA) Market is projected to grow from USD 863.30 million in 2023 to an estimated USD 11,725.46 million by 2032, with a compound annual growth rate (CAGR) of 29.21% from 2024 to 2032. This robust growth is driven by the increasing demand for high-speed internet connectivity across urban and rural regions, fueled by advancements in 5G technology.
Key drivers of the India 5G FWA market include the increasing adoption of 5G networks, rising demand for high-speed internet, and the growing need for seamless connectivity in remote areas. The market is also influenced by technological trends such as the deployment of 5G infrastructure, the proliferation of IoT devices, and government initiatives supporting digital connectivity. Additionally, innovations in 5G FWA technology are enhancing data speeds and reducing latency, which is further boosting market growth.
Geographically, the market is witnessing strong growth across urban centers and expanding to semi-urban and rural areas where traditional broadband infrastructure is limited. Key players in the India 5G FWA market include major telecom operators such as Bharti Airtel, Reliance Jio, Vodafone Idea, and global network equipment providers like Ericsson, Nokia, and Huawei. These players are actively involved in 5G network deployment and the development of fixed wireless solutions to cater to the growing demand.
Market Insights
- The India 5G Fixed Wireless Access (FWA) market is projected to grow from USD 863.30 million in 2023 to USD 11,725.46 million by 2032, driven by a CAGR of 29.21%.
- The growing need for faster and more reliable internet services in both urban and rural areas is a key driver of FWA adoption.
- Digital India and other government initiatives are fueling demand for broadband connectivity, especially in underserved regions, boosting the 5G FWA market.
- Innovations in 5G technology, such as faster speeds and reduced latency, are enhancing the appeal of FWA as a cost-effective alternative to traditional broadband.
- High deployment costs and regulatory hurdles in rural areas can slow down the widespread adoption of 5G FWA services, posing a market restraint.
- The market is witnessing strong growth in urban centers, while rural and semi-urban areas represent significant untapped potential for FWA services.
- Key players such as Bharti Airtel, Reliance Jio, and global providers like Ericsson and Nokia are driving the market’s expansion with innovative solutions and network deployments.
Market Drivers
Rising Demand for High-Speed Internet Connectivity
The demand for high-speed internet connectivity has been increasing significantly across India, driven by the growing consumption of digital content, streaming services, online gaming, and cloud-based applications. As the country undergoes a digital transformation, both businesses and consumers are increasingly reliant on fast and stable internet connections. Traditional broadband technologies, such as DSL and fiber-optic connections, often fail to meet the speed and reliability requirements of modern users. For instance, as of February 2024, India recorded 39.4 million wired broadband subscribers, reflecting a notable increase in the overall subscriber base from 392 million in February 2018 to 916 million in February 2024. This surge highlights the growing reliance on digital services and the need for robust internet infrastructure to support activities such as streaming, online gaming, and cloud applications.Fixed Wireless Access (FWA) powered by 5G technology addresses this challenge by offering ultra-fast speeds, low latency, and enhanced reliability. By delivering fiber-like connectivity without the need for physical infrastructure, 5G FWA presents a cost-effective and scalable solution for meeting high-speed internet demand across urban, suburban, and rural areas. This widespread demand for faster internet, coupled with the evolving nature of digital services, is one of the key drivers of the India 5G FWA market.
Government Support and Policy Initiatives
The Indian government has been actively working towards improving digital connectivity across the country. The National Digital Communications Policy (NDCP) 2018 and the Digital India initiative aim to transform India into a digitally empowered society by enhancing access to high-speed internet in rural and remote areas. To achieve this goal, the government is encouraging telecom operators to deploy 5G networks and expand internet access. Additionally, by April 2024, 95.15% of villages had access to internet services via 3G or 4G mobile connectivity, illustrating the government's commitment to bridging the digital divide between urban and rural areas. The BharatNet project, aimed at connecting all Gram Panchayats with Optical Fibre Cable (OFC), has made substantial progress, with 2.13 lakh Gram Panchayats already service-ready.The 5G spectrum auction in India, which took place in 2022, was an important milestone in paving the way for 5G deployment. With the allocation of airwaves for 5G networks, the government has laid the foundation for the expansion of 5G-based services such as FWA. These policy initiatives, along with government subsidies and incentives for telecom infrastructure development, play a crucial role in promoting the adoption of 5G FWA solutions in India. This ongoing governmental push is a significant driver of market growth, particularly in underserved areas.
Rapid Expansion of 5G Network Infrastructure
The rapid expansion of 5G network infrastructure in India is a fundamental driver of the FWA market. Telecom operators such as Bharti Airtel, Reliance Jio, and Vodafone Idea are aggressively rolling out 5G services across the country. This large-scale deployment is expected to significantly increase the availability of high-speed wireless broadband services. Fixed Wireless Access, which leverages 5G infrastructure, offers an attractive alternative to wired broadband—especially in areas where it is difficult to lay fiber-optic cables or other fixed-line infrastructure.The ongoing rollout of 5G technology is set to provide consumers and businesses with improved performance and reduced latency. As more regions get connected to the 5G network, the demand for 5G FWA services is expected to surge as consumers and businesses seek to leverage enhanced performance and faster speeds that 5G offers.
Increasing Adoption of Internet of Things (IoT) Devices and Smart Solutions
The proliferation of Internet of Things (IoT) devices and smart solutions across various industries—including manufacturing, healthcare, and agriculture—is driving the demand for high-speed, low-latency wireless internet connections. IoT applications require fast and stable internet connectivity to function efficiently, and 5G FWA is poised to address this need by offering the necessary bandwidth and reliability.From smart homes with connected appliances to industrial IoT systems and smart agriculture solutions, the widespread adoption of IoT is creating a surge in demand for advanced connectivity solutions. Fixed Wireless Access plays a crucial role in enabling these IoT-based systems with its ability to support a large number of connected devices simultaneously. Moreover, 5G networks provide ideal infrastructure for future growth in IoT applications.As IoT adoption continues to rise across India, driven by both consumer needs and technological advancements, the need for 5G-based FWA services is expected to grow significantly—thereby driving market expansion.
Market Trends
Expansion of 5G Infrastructure Across Urban and Rural Areas
One of the most prominent trends in the India 5G Fixed Wireless Access (FWA) market is the aggressive expansion of 5G infrastructure, not just in urban centers, but also in rural and semi-urban regions. Telecom giants such as Reliance Jio, Bharti Airtel, and Vodafone Idea are actively deploying 5G networks to cater to the increasing demand for high-speed internet. Traditionally, urban areas have had better access to high-speed broadband services; however, the 5G FWA model is now making it possible to extend this connectivity to underserved areas. For instance, the Indian government is investing approximately $30 billion to ensure that 5G networks reach every village, aiming to create a "rural digital India" where high-speed internet becomes accessible to all. This initiative is vital, as rural areas, which make up about 70% of India, have historically lagged in broadband access compared to urban centers. The implementation of 5G technology is expected to significantly enhance sectors like agriculture, education, and healthcare in these regions by providing reliable and fast internet services.5G offers the advantage of being able to deliver fast internet without the need for extensive fiber-optic cabling, which is often expensive and challenging to deploy in rural regions. As telecom providers continue to roll out 5G infrastructure and FWA solutions, connectivity is becoming increasingly ubiquitous, bridging the digital divide between urban and rural India. This trend is enabling consumers and businesses in remote areas to benefit from high-speed internet, which previously might have been unavailable or unreliable. The widespread availability of 5G FWA is fostering the development of smart cities, remote working, and digital education in rural regions, marking a significant shift in the country’s broadband landscape.
Integration of IoT and Smart Technologies
Another key trend in the India 5G FWA market is the integration of Internet of Things (IoT) devices and smart technologies with 5G connectivity. The adoption of IoT-based systems across various sectors, including agriculture, healthcare, transportation, and industrial automation, is on the rise. These IoT devices require ultra-reliable, high-speed internet connections to operate effectively. For example, smart agriculture solutions such as precision farming require reliable connectivity to support IoT sensors and automated machinery. With the deployment of 5G networks, these technologies are becoming increasingly viable. This connectivity allows farmers to optimize their operations through real-time monitoring of soil conditions and leveraging advanced data analytics and automation. Similarly, in industrial IoT (IIoT), factories and warehouses are leveraging 5G FWA to enhance productivity through automation and real-time monitoring. As the demand for smart homes, connected devices, and autonomous systems increases, the need for robust 5G FWA solutions is growing. This trend is further fueling the adoption of 5G networks and Fixed Wireless Access services as a key enabler of the IoT ecosystem, ensuring that large numbers of devices can stay connected and operate efficiently.
Focus on Network Slicing and Enhanced Service Quality
With the rollout of 5G technology, network slicing has emerged as a significant trend in the India 5G FWA market. Network slicing enables telecom operators to create multiple virtual networks on a single physical 5G infrastructure, each customized to meet the specific requirements of different industries or services. This is particularly useful in the FWA market, where various user segments—such as residential, business, and industrial clients—require different levels of service quality.For instance, residential users may demand high-speed internet for entertainment and work-from-home purposes, while businesses may require low-latency connections for mission-critical applications. By adopting network slicing, telecom operators can deliver differentiated services to meet the varied demands of their customers. This ensures that consumers experience high levels of service quality with consistent speeds and reliability even during periods of high network congestion. As 5G networks become more widely deployed, the ability to offer tailored services through network slicing is expected to play a key role in the success of 5G FWA solutions.
Increase in Government and Private Sector Collaborations
The collaboration between the Indian government and private telecom companies is another key trend that is shaping the growth of the 5G FWA market. The Indian government is actively working to provide financial and regulatory support to facilitate the deployment of 5G technology across the country. This includes spectrum auctions, spectrum sharing agreements, and policies designed to encourage private sector investment in telecom infrastructure.Public-private partnerships (PPPs) are gaining traction as both sectors come together to address the challenges of connectivity—especially in rural and underserved areas. Telecom operators are receiving support in the form of incentives such as tax breaks and subsidies to deploy 5G infrastructure and expand broadband access. For example, initiatives like Digital India aim to ensure that every citizen has access to high-speed internet. As part of this initiative, the government works closely with telecom providers to accelerate the rollout of 5G networks and provide affordable internet services.
Market Challenges
High Deployment Costs and Infrastructure Challenges
One of the major challenges facing the India 5G Fixed Wireless Access (FWA) market is the significant cost involved in deploying 5G infrastructure, especially in rural and remote areas. The rollout of 5G networks requires substantial investment in upgrading existing telecom infrastructure and acquiring new spectrum licenses. While 5G FWA offers a cost-effective alternative to traditional broadband solutions, the upfront cost for telecom operators to build the necessary infrastructure, including the installation of 5G base stations and small cells, can be prohibitively high. In addition, the process of securing permissions and overcoming regulatory hurdles to install towers and other essential equipment in rural or densely populated areas can delay network deployment. This challenge is exacerbated in rural regions, where existing broadband infrastructure is limited, and the cost of deploying 5G networks may outweigh the immediate return on investment. Telecom operators need to find ways to reduce deployment costs, such as through public-private partnerships or leveraging existing infrastructure, to ensure the widespread adoption of 5G FWA services across the country.
Limited Spectrum Availability and Regulatory Constraints
Another significant challenge facing the India 5G FWA market is the limited availability of spectrum and the regulatory constraints that come with it. The Indian government has allocated spectrum for 5G, but the competition for airwaves has led to high auction prices, making it expensive for telecom operators to secure the necessary frequencies. This can hinder the rapid rollout of 5G networks and FWA services, particularly in underserved areas. Additionally, the regulatory environment surrounding spectrum sharing and usage remains complex and may slow down the deployment of 5G infrastructure. Telecom operators are also constrained by the existing infrastructure and bandwidth limits, which may not fully support the capabilities of 5G FWA in high-demand scenarios. Overcoming these regulatory and spectrum limitations is essential for ensuring the growth and scalability of 5G FWA services in India.
Market Opportunities
Expanding Internet Access in Rural and Remote Areas
One of the most significant opportunities in the India 5G Fixed Wireless Access (FWA) market lies in addressing the digital divide between urban and rural regions. A large portion of India’s rural population still lacks reliable access to high-speed internet, limiting their participation in the digital economy. 5G FWA offers a cost-effective solution to extend broadband services to underserved areas without the need for extensive fiber-optic infrastructure. As telecom operators expand their 5G networks, FWA can bridge this connectivity gap by providing rural consumers with high-speed internet access. With the government’s push for digital inclusion through initiatives like Digital India, 5G FWA has the potential to accelerate the adoption of e-learning, telemedicine, and e-commerce services in these regions, fostering economic growth and improving quality of life.
Enterprise Connectivity and Smart Solutions
The rapid growth of IoT, smart cities, and industrial automation presents a significant market opportunity for 5G FWA in India. Businesses across sectors such as manufacturing, logistics, healthcare, and agriculture are increasingly adopting smart solutions that require high-speed, low-latency connectivity. 5G FWA, with its ability to deliver consistent, reliable broadband services without the need for wired infrastructure, is an ideal solution for enterprises looking to optimize their operations. As industries embrace digital transformation, the demand for robust connectivity solutions for IoT devices, automated systems, and smart applications will rise, creating a lucrative opportunity for telecom providers to cater to enterprise needs with 5G-powered FWA services.
Market Segmentation Analysis
By Offering
The India 5G Fixed Wireless Access (FWA) market is divided into two key segments: hardware and services. The hardware segment includes the physical infrastructure necessary for 5G FWA, such as routers, gateways, antennas, and network devices, which are essential for establishing reliable internet connections. The services segment encompasses managed services, installation, maintenance, troubleshooting, data management, network optimization, and technical support, ensuring the smooth operation of FWA networks. As 5G infrastructure continues to expand across regions, the demand for both hardware and services is expected to grow, driving further market development.
By Operating Frequency
The India 5G Fixed Wireless Access (FWA) market is segmented based on the operating frequency of the 5G network. The Sub 6GHz frequency range is expected to dominate due to its wider coverage and better penetration, making it suitable for both urban and rural areas. The 24-39 GHz millimeter-wave (mmWave) frequency range is used for higher data transmission speeds, particularly in dense urban areas with high bandwidth demand. Frequencies above 39GHz offer extremely high-speed connectivity, although their limited penetration makes them ideal for short-range applications in densely populated environments. As 5G infrastructure evolves, the use of higher frequencies is anticipated to increase to support the growing demand for faster internet services.
Segments
Based on Offering
- Hardware
- Services
Based on Operating Frequency
- Sub 6GHz
- 24-39 GHz
- Above 39GHz
Based on Application
- Residential
- Commercial
- Industrial
- Government
Regional Analysis
Urban Regions (50%)
Urban areas account for the largest market share of the India 5G FWA market, with an estimated 50% share. These regions experience the highest demand for high-speed internet, driven by dense populations, advanced digital infrastructure, and the proliferation of smart devices. Major cities such as Delhi, Mumbai, Bangalore, Hyderabad, and Chennai are at the forefront of 5G deployment. The demand for FWA in urban centers is primarily driven by the need for seamless connectivity in residential, commercial, and business sectors, especially as remote work and digital services continue to expand. The availability of 5G infrastructure in urban areas facilitates the growth of FWA solutions, catering to both consumers and businesses seeking faster, more reliable internet services.
Semi-Urban Regions (25%)
Semi-urban regions contribute approximately 25% to the India 5G FWA market. These areas are seeing a rapid digital transformation, with an increasing number of businesses and residents demanding better internet connectivity. As the semi-urban population grows, there is an increasing reliance on digital tools for business operations, education, and e-commerce. Telecom operators are focusing on expanding 5G infrastructure in these areas to meet the growing demand for fast internet access. The relatively lower cost of deploying 5G FWA infrastructure in semi-urban regions, compared to fully rural areas, makes them an attractive target for service expansion.
Key players
- Huawei Technologies Co., Ltd.
- Telefonaktiebolaget LM Ericsson
- Nokia
- Samsung
- Inseego Corp.
- Qualcomm Technologies, Inc.
- Intel Corporation
- MediaTek Inc.
- COMMSCOPE
- Verizon Communications Inc.
Competitive Analysis
The India 5G Fixed Wireless Access (FWA) market is highly competitive, with key players focusing on expanding their technological capabilities and enhancing service offerings. Huawei Technologies and Ericsson lead the market with their extensive 5G network solutions, providing infrastructure that supports both urban and rural deployments. Nokia and Samsung are also strong contenders, offering integrated solutions and innovative 5G technologies. Companies like Qualcomm and Intel contribute with their advanced chipset solutions that enable efficient 5G connectivity, while MediaTek is increasingly gaining attention for its competitive pricing and IoT-related products. Inseego Corp. and COMMSCOPE focus on delivering FWA solutions, including routers and antennas, specifically tailored for 5G networks. Verizon Communications strengthens its position through collaborations and investments in expanding 5G infrastructure. As the market evolves, these companies are focusing on technological innovation, strategic partnerships, and scalability to maintain competitive advantages.
Recent Developments
- In November 2024, Huawei announced its strategic partnership with Indian telecom operators to enhance 5G FWA capabilities, focusing on rural connectivity solutions.
- In October 2024, Ericsson reported significant progress in its 5G FWA deployments across India, collaborating with local telecom providers to improve broadband access in underserved regions. They estimate that FWA will facilitate connections for up to 100 million homes by 2030.
- In September 2024, Nokia launched its new FWA solution tailored for the Indian market, emphasizing its ability to deliver highInspeed internet in rural areas without the need for extensive fiber infrastructure.
- In November 2024, Samsung unveiled its latest 5G FWA devices designed for Indian consumers, featuring enhanced performance metrics aimed at supporting high data consumption rates, which have reportedly reached up to 600 GB per month.
- In October 2024, Inseego announced the launch of its new line of 5G FWA routers in India, targeting both residential and enterprise customers to enhance connectivity options across the country.
- In October 2024, Qualcomm highlighted its increased production of chipsets for FWA applications in India, noting a significant rise in demand as telecom operators like Jio and Airtel expand their services.
- In November 2024, Intel introduced new technologies aimed at optimizing network performance for 5G FWA applications in collaboration with Indian telecom operators to support the growing subscriber base.
- In September 2024, MediaTek launched a series of chipsets specifically designed for enhancing the performance of 5G FWA solutions in India, focusing on affordability and efficiency.
- In November 2024, Verizon entered into a strategic alliance with Indian telecom providers to share technology and expertise in deploying FWA solutions, aiming to leverage its experience from markets like the U.S. to accelerate growth in India.
Market Concentration and Characteristics
The India 5G Fixed Wireless Access (FWA) market is moderately concentrated, with a few large players dominating the space, particularly global telecom equipment providers such as Huawei Technologies, Ericsson, Nokia, and Samsung. These companies hold a significant share of the market due to their extensive 5G network solutions and infrastructure capabilities. However, the market also features a mix of specialized players, including Inseego Corp., Qualcomm, and MediaTek, which focus on providing essential components like routers, chipsets, and antennas for FWA services. The market is characterized by rapid technological advancements, high competition in pricing and service delivery, and the ongoing rollout of 5G networks across urban, semi-urban, and rural areas. This has led to a dynamic landscape, where companies are continuously innovating to meet the demand for high-speed, reliable internet solutions while ensuring scalability and efficient network management.
Report Coverage
The research report offers an in-depth analysis based on Offering, Operating Frequency, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The deployment of 5G networks in urban and rural areas will accelerate, driving widespread adoption of FWA solutions. Telecom operators will continue expanding coverage, enabling seamless connectivity across India.
- As the demand for faster internet grows due to digitalization, 5G FWA will become a preferred solution for high-speed broadband access. This will fuel market growth, particularly in underserved areas.
- The Indian government’s push for digital inclusion through initiatives like Digital India will enhance the demand for 5G FWA in rural and remote regions. These policies will promote widespread adoption of FWA services.
- The increasing adoption of IoT devices and smart technologies across industries will drive the need for reliable, high-speed internet. 5G FWA’s ability to support IoT applications will play a pivotal role in this transformation.
- Telecom operators will adopt network slicing to offer tailored FWA services for different customer segments, improving service quality and meeting diverse demand for bandwidth and latency requirements.
- Ongoing advancements in 5G FWA equipment, such as routers, antennas, and chipsets, will enhance the performance and reliability of the technology. This will support faster and more efficient service delivery.
- As the 5G FWA market grows, telecom operators will intensify competition, driving innovation and lowering service costs. This will benefit consumers, leading to better service quality and affordability.
- The continued urbanization of India and the ongoing digital transformation will create a substantial market for 5G FWA. Businesses and consumers in cities will increasingly rely on FWA for connectivity.
- India’s rural and remote regions will become key focus areas for 5G FWA deployment, addressing the digital divide and providing internet access where traditional broadband infrastructure is limited.
- The future of the India 5G FWA market will see an increase in collaborations between telecom operators, technology providers, and governments. Strategic partnerships will enable faster and more efficient network rollouts and service delivery.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the India 5G Fixed Wireless Access (FWA) market in 2023 and 2032?
What are the key drivers of the India 5G Fixed Wireless Access (FWA) market?
Which regions are experiencing the highest growth in the India 5G FWA market?
Who are the key players in the India 5G Fixed Wireless Access (FWA) market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India 5G Fixed Wireless Access (FWA) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global India 5G Fixed Wireless Access (FWA) Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 863.30 million → 2032: USD 11,725.46 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India 5G Fixed Wireless Access (FWA) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India 5G Fixed Wireless Access (FWA) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India 5G Fixed Wireless Access (FWA) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 India 5G Fixed Wireless Access (FWA) Market Drivers
- 3.3 India 5G Fixed Wireless Access (FWA) Market Restraints & Challenges
- 3.4 India 5G Fixed Wireless Access (FWA) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India 5G Fixed Wireless Access (FWA) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India 5G Fixed Wireless Access (FWA) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India 5G Fixed Wireless Access (FWA) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India 5G Fixed Wireless Access (FWA) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. India 5G Fixed Wireless Access (FWA) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the India 5G Fixed Wireless Access (FWA) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India 5G Fixed Wireless Access (FWA) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 India 5G Fixed Wireless Access (FWA) Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 India 5G Fixed Wireless Access (FWA) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India 5G Fixed Wireless Access (FWA) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New India 5G Fixed Wireless Access (FWA) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global India 5G Fixed Wireless Access (FWA) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America India 5G Fixed Wireless Access (FWA) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe India 5G Fixed Wireless Access (FWA) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific India 5G Fixed Wireless Access (FWA) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America India 5G Fixed Wireless Access (FWA) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East India 5G Fixed Wireless Access (FWA) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa India 5G Fixed Wireless Access (FWA) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. India 5G Fixed Wireless Access (FWA) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
