
Market Overview:
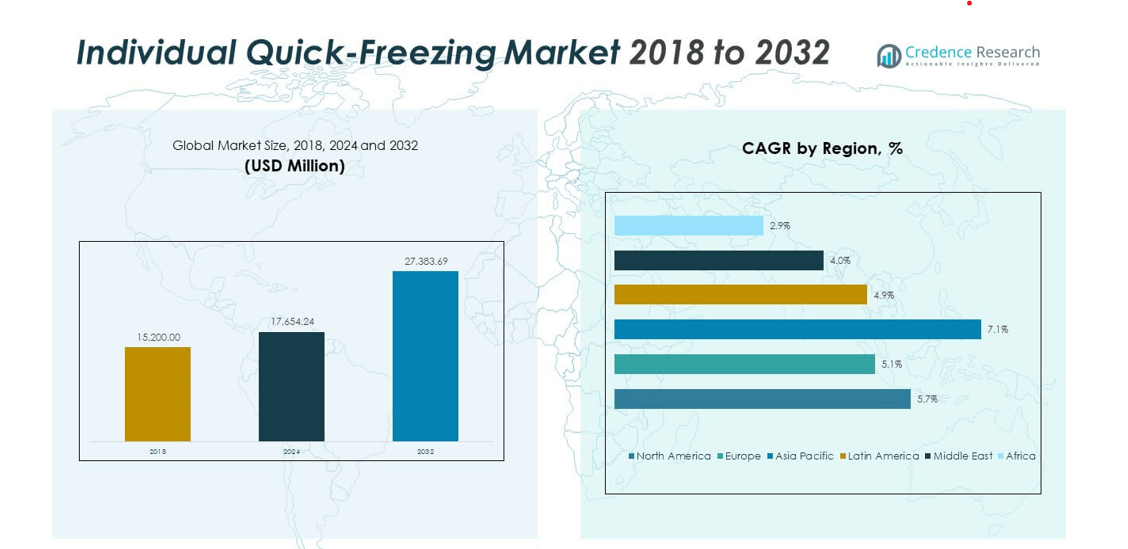
The Global Individual Quick Freezing Market size was valued at USD 15,200.00 million in 2018 to USD 17,654.24 million in 2024 and is anticipated to reach USD 27,383.69 million by 2032, at a CAGR of 5.73% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Individual Quick Freezing Market Size 2024 | USD 17,654.24 million |
| Individual Quick Freezing Market, CAGR | 5.73% |
| Individual Quick Freezing Market Size 2032 | USD 27,383.69 million |
Strong momentum comes from higher demand for preserved foods with better texture and taste. Food processors rely on IQF systems to retain moisture and shape during rapid freezing. Manufacturers focus on clean-label frozen foods that match fresh-quality expectations. Rising consumption of ready-to-cook meals supports wider technology adoption. Seafood, fruits, and vegetable exporters gain value from reduced drip loss and longer shelf stability. Continuous upgrades in freezer design help firms handle diverse product formats with greater ease.
Regional demand shows strong traction in North America and Europe due to established frozen food intake and modern cold-chain networks. Asia Pacific emerges as the fastest-growing region with rising urbanization and higher packaged food use. China, India, and Southeast Asia expand capacity due to large-scale processing clusters. Latin America strengthens adoption in fruit and vegetable exports. The Middle East and Africa gain steady growth supported by improving refrigeration infrastructure and growing retail penetration.
Market Insights:
- The market grew from USD 15,200.00 million in 2018 to USD 17,654.24 million in 2024 and is forecast to reach USD 27,383.69 million by 2032, advancing at a CAGR of 5.73%.
- North America (36.33%), Europe (27.42%), and Asia Pacific (23.82%) dominate due to strong processing capacity, advanced cold-chain systems, and high frozen food consumption.
- Asia Pacific, holding 82%, is the fastest-growing region supported by rising export volumes, expanding infrastructure, and higher adoption of frozen products in urban areas.
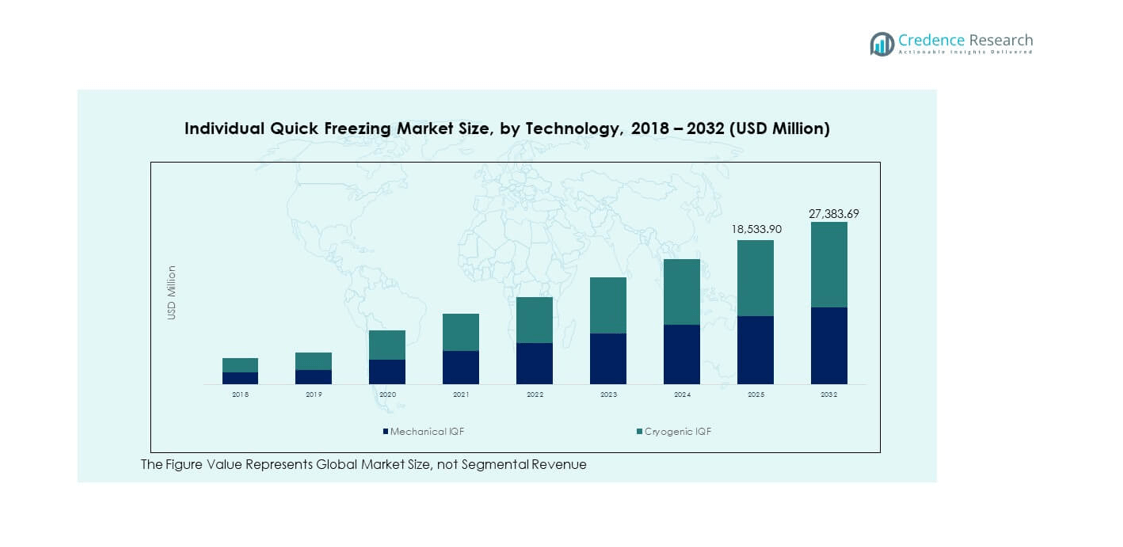
- Mechanical IQF represents roughly 30–35% of technology usage, reflecting strong suitability for continuous high-volume production.
- Cryogenic IQF accounts for around 65–70%, driven by demand for rapid, uniform freezing and improved handling of delicate food items.
Market Drivers:
Rising Demand for High-Quality Frozen Foods Across Large Processing Networks
The Global Individual Quick Freezing Market gains strong traction through rising demand for premium frozen foods across major processing hubs. Consumer preference for clean-label meals supports wider integration of IQF systems in fruit, vegetable, and seafood plants. Companies invest in fast-cycle freezing to protect product color and natural structure. Modern equipment lowers dehydration loss during rapid temperature drop. Brands target higher texture retention to strengthen trust in frozen meals. Exporters use IQF technology to secure uniform quality across long routes. Food processors push upgrades that improve batch consistency. The technology supports faster output for plants that handle mixed product lines.
- For instance, Marel reports spiral freezers that handle up to 6 tons of poultry per hour while freezing products to −18°C, supporting high-throughput lines that protect product quality.
Growing Focus on Shelf Stability and Fresh-Like Preservation Benefits
Rising interest in safe and long-lasting packaged foods supports strong deployment of IQF solutions in many factories. The Global Individual Quick Freezing Market benefits from advanced freezing that locks nutrients without extra additives. Many producers adopt IQF lines to manage seasonal supply variation. Frozen product demand grows in regions with limited access to fresh produce. Companies aim to meet higher retail standards linked to food safety. Better ice crystal control improves flavor retention across storage periods. IT-based monitoring improves accuracy in cycle control. It helps processors maintain the same quality across multiple production shifts.
- For instance, Enfield Farms in the United States installed a GEA IQF tunnel freezer that operates at a suction temperature of −31°F and delivers significant energy savings while maintaining high berry quality.
Expansion of Cold-Chain Infrastructure Across Developing and Mature Economies
Many countries upgrade cold-chain networks to meet expanding distribution needs. The Global Individual Quick Freezing Market grows when governments and private firms build efficient storage systems. Retailers demand frozen food pipelines that support stable year-round supply. Logistic operators adopt new equipment that manages temperature precision in long routes. Producers increase volumes due to better regional storage grids. Integrated freezing lines help teams reduce handling losses during peak demand seasons. It allows exporters to reach distant markets with stronger stability. Large plants raise investment in equipment that works well with modern cold-chain plans.
Shift Toward Automation and High-Capacity Freezing Lines in Large-Scale Facilities
More factories prefer automated IQF systems that reduce manual work and improve accuracy. The Global Individual Quick Freezing Market expands when companies target higher throughput to meet rising retail and foodservice orders. Producers install lines that support flexible product switching. High-capacity freezers offer cleaner operating environments and faster defrost routines. Many plants deploy smart sensors that track temperature and airflow control. These systems help maintain uniform freezing across each unit. Firms push automation to meet strict safety rules and reduce downtime. It creates stronger demand for advanced freezing platforms.
Market Trends:
Growing Integration of Energy-Efficient Freezing Systems in Processing Facilities
Energy efficiency pushes new design choices in many processing plants. The Global Individual Quick Freezing Market sees strong interest in systems that lower operational costs. Engineers focus on motors and compressors that consume less power. Many firms adopt solutions with heat recovery modules. Improved airflow layouts support faster cycles without excess load. Plants explore greener refrigerant gases to align with global standards. Newer models reduce frost buildup and support longer running hours. It encourages companies to adopt sustainable freezing solutions.
- For instance, GEA’s A-series IQF tunnel freezers use ammonia at −32°C and deliver more than 20% energy savings compared with operation at −40°C, while DSI Dantech reports CO₂ reductions of at least 22% from its energy-saving tunnel designs certified under EU Taxonomy rules.
Expansion of Ready-to-Cook and Ready-to-Eat Segments Across Global Retail Chains
Retail growth strengthens demand for IQF products that support fast meal preparation. The Global Individual Quick Freezing Market benefits from higher acceptance of frozen snacks, meal kits, and processed seafood. Consumers choose items that offer reduced cooking time. Brands increase product lines that use IQF to hold shape and freshness. Business models shift toward direct-to-home frozen meal delivery. Manufacturers develop blends that freeze well without texture damage. Strong uptake in urban households drives stability. It positions IQF technology as a core element of modern food retail.
Adoption of Advanced Conveyor and Fluidized Bed Technologies to Enhance Output Quality
Many plants upgrade conveyor and fluidized bed systems to improve precision. The Global Individual Quick Freezing Market responds to demand for uniform freezing across irregular product sizes. Better belt airflow improves particle separation during freezing. Multi-stage chillers deliver cleaner surfaces and smoother handling. Plants adopt equipment with lower vibration to protect delicate items. Engineers redesign freezer interiors for easy sanitation. Firms target smoother line flow to reduce clog issues. It supports consistent product quality across batches.
Growing Use of IQF Technology in Niche Segments Such as Plant-Based Foods
Plant-based food expansion drives interest in controlled freezing quality. The Global Individual Quick Freezing Market aligns well with demand for clean-label plant proteins. Frozen vegan snacks need stable structure to maintain appeal. IQF improves bite texture in meat substitutes. Producers adopt tailored freezing cycles for grain mixes and legumes. Retailers increase shelf space for plant-based frozen packs. Facilities adjust airflow patterns for new recipes. It expands the role of IQF within emerging food formats.
Market Challenges Analysis:
High Operational Costs and Energy Pressure Across Large and Mid-Scale Plants
The Global Individual Quick Freezing Market faces rising operational pressures due to high energy consumption linked to rapid cooling cycles. Many facilities struggle to manage peaks in power demand during extended production hours. Complex systems require skilled teams that many regions lack. Plants face wear issues when handling continuous volumes across harsh conditions. Maintenance schedules remain tight due to frost buildup concerns. Smaller firms hesitate to invest in premium IQF machinery due to high capital needs. It creates an uneven adoption pattern across regions. Many operators face compliance challenges linked to refrigerant rules.
Infrastructure Gaps and Uneven Supply Chain Capabilities in Developing Regions
Limited cold-chain grids restrict access to IQF technology in emerging markets. The Global Individual Quick Freezing Market sees slow progress in areas with weak transport networks. Many locations lack stable electricity supply needed for advanced freezers. Exporters face high spoilage risk due to inadequate storage. Plants struggle to scale due to shortage of qualified technicians. Companies delay expansion due to regulatory hurdles around safety standards. Import dependency raises equipment cost for many buyers. It slows technology penetration across underserved markets.
Market Opportunities:
Rising Scope for IQF Adoption in Expanding Food Export Ecosystems
The Global Individual Quick Freezing Market gains strong potential from the growth of fruit, vegetable, seafood, and poultry exports. Many exporting countries aim to improve product grade through advanced freezing. Firms seek reliable freezing cycles that reduce damage during long-distance travel. Export zones upgrade storage to meet global retail expectations. Producers in emerging regions invest in IQF to access new buyers. The method helps maintain shape and taste across diverse climates. It supports stronger trade flows across continents. Buyers respond well to high-quality frozen items.
Increasing Interest in Automation and Digital Monitoring Tools Across Processing Lines
Automation improves productivity and opens new opportunities in many factories. The Global Individual Quick Freezing Market benefits when plants integrate sensors and digital dashboards. Teams use real-time data to control airflow patterns and cycle speed. Predictive tools help detect faults early and reduce waste. Advanced controls support higher throughput with stable quality. Many producers shift toward connected equipment that tracks performance. It encourages wider modernization of production units. The trend supports long-term expansion for IQF suppliers.
Market Segmentation Analysis:
By Equipment Type
The Global Individual Quick Freezing Market shows strong use of spiral, tunnel, box, and other freezer formats that support diverse processing needs. Spiral models handle high throughput for large plants that run continuous cycles. Tunnel freezers appeal to processors that need steady airflow for uniform treatment across products with varied shapes. Box units support compact operations that manage smaller batches. Many firms choose flexible systems that reduce floor load and improve sanitation routines. It helps producers match equipment choices with production goals. Plants adopt hybrid designs that support mixed product lines.
- For instance, JBT’s Frigoscandia GYRoCOMPACT spiral freezers use a patented self-stacking belt and have more than 4,000 installations worldwide, while GEA IQF tunnel freezers cover capacities from 0.5 to 25 tons per hour to serve different plant sizes.
By Application
The Global Individual Quick Freezing Market supports wide adoption across fruits, vegetables, seafood, meat, poultry, dairy products, and convenience foods. Frozen produce gains steady traction due to rising demand for clean-label products. Seafood processors use IQF to protect delicate texture. Meat and poultry teams depend on cycle precision to retain moisture. Dairy products require stable freezing for long shelf life. Convenience food growth drives new launches that favor uniform quality. It supports strong use across retail and foodservice networks.
- For instance, Foodhills AB in Sweden runs an FPS IQF tunnel that processes a little over 200 tons of peas per day, with peak production reaching 260 tons, supporting large-scale frozen vegetable supply to retail and foodservice customers.
By Processing Stage, Technology, and Capacity
The Global Individual Quick Freezing Market aligns with pre-processing, freezing, and packaging stages that define modern plant design. Pre-processing units prepare products for steady flow across lines. Freezing remains the core stage that delivers quality retention. Packaging units protect product shape during storage. Mechanical IQF leads due to its wide capability across many food categories. Cryogenic IQF supports delicate items that need rapid temperature drop. Capacity choices span small, medium, and large units that match the scale of each facility. It helps producers expand in line with demand patterns.
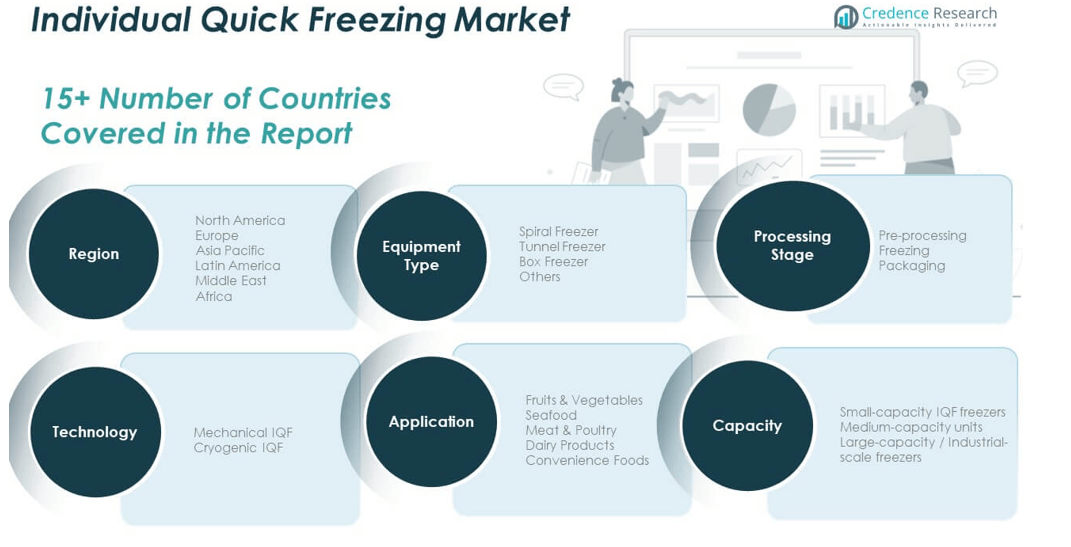
Segmentation:
By Equipment Type
- Spiral Freezer
- Tunnel Freezer
- Box Freezer
- Others
By Application
- Fruits & Vegetables
- Seafood
- Meat & Poultry
- Dairy Products
- Convenience Foods
By Processing Stage
- Pre-processing
- Freezing
- Packaging
By Technology
- Mechanical IQF
- Cryogenic IQF
By Capacity
- Small-capacity IQF Freezers
- Medium-capacity Units
- Large-capacity / Industrial-scale Freezers
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Individual Quick Freezing Market size was valued at USD 5,586.00 million in 2018 to USD 6,410.15 million in 2024 and is anticipated to reach USD 9,929.37 million by 2032, at a CAGR of 5.7% during the forecast period. North America holds a market share of 36.33% in 2024. North America leads the Global Individual Quick Freezing Market due to strong frozen food consumption and advanced processing capabilities. The region invests in efficient cold-chain networks that support large product volumes year-round. Processors use IQF systems to secure uniform texture in fruits, vegetables, meat, and seafood. Retail chains expand frozen meal options that require reliable freezing quality. Facilities upgrade machinery to improve energy control and output stability. Seafood processors in coastal areas rely on fast-cycle freezing to protect delicate items. Meat producers strengthen capacity to match rising protein demand. It stays a dominant region due to strong manufacturing scale and high technology adoption.
Europe
The Europe Individual Quick Freezing Market size was valued at USD 4,324.40 million in 2018 to USD 4,842.07 million in 2024 and is anticipated to reach USD 7,126.68 million by 2032, at a CAGR of 5.1% during the forecast period. Europe holds a market share of 27.42% in 2024. Europe maintains a strong position in the Global Individual Quick Freezing Market supported by strict food safety rules and structured processing lines. Producers adopt IQF systems to retain color, taste, and nutrients in seasonal produce. Frozen bakery and dairy items push stable equipment demand across many countries. Northern Europe records high frozen food intake among busy households. Eastern Europe increases output through new processing plants and export-led farming. Seafood producers in coastal nations use IQF to maintain grade consistency. Packaging units integrate precise chilling cycles that prepare retail-ready packs. It remains a stable market due to mature technology use and wide product diversity.
Asia Pacific
The Asia Pacific Individual Quick Freezing Market size was valued at USD 3,458.00 million in 2018 to USD 4,207.81 million in 2024 and is anticipated to reach USD 7,251.22 million by 2032, at a CAGR of 7.1% during the forecast period. Asia Pacific holds a market share of 23.82% in 2024. Asia Pacific records the fastest growth in the Global Individual Quick Freezing Market due to large agriculture output and expanding food processing clusters. China and India strengthen cold-chain systems to support frozen fruits and vegetables. Seafood exporters in Thailand, Vietnam, and Indonesia depend on IQF lines for export compliance. Growing urban populations drive interest in frozen snacks and ready meals. Local factories scale production to align with global retail demand. Technology upgrades focus on airflow optimization and energy control. Packaging units handle large loads linked to international buyers. It grows rapidly through strong upstream supply and rising household adoption.
Latin America
The Latin America Individual Quick Freezing Market size was valued at USD 1,098.96 million in 2018 to USD 1,265.63 million in 2024 and is anticipated to reach USD 1,839.36 million by 2032, at a CAGR of 4.9% during the forecast period. Latin America holds a market share of 7.17% in 2024. Latin America expands its role in the Global Individual Quick Freezing Market due to strong fruit and vegetable export activity. Producers adopt IQF systems to maintain shape and texture during long transit periods. Countries strengthen agricultural supply chains to meet international standards. Berries, avocados, and poultry items gain wide export traction. Growing urbanization increases demand for frozen meal components. Cold-chain infrastructure improves gradually across major production zones. Plants invest in flexible IQF systems that support varied crop cycles. It advances through export-led momentum and rising domestic adoption.
Middle East
The Middle East Individual Quick Freezing Market size was valued at USD 471.20 million in 2018 to USD 504.80 million in 2024 and is anticipated to reach USD 687.48 million by 2032, at a CAGR of 4.0% during the forecast period. The Middle East holds a market share of 2.86% in 2024. The Middle East secures steady progress within the Global Individual Quick Freezing Market due to high demand for imported frozen foods. Retail expansion across major cities drives interest in frozen meat, vegetables, and ready meals. Quick-service restaurants depend on IQF meat products for menu consistency. Local processors invest in modern systems to produce value-added food lines. Gulf countries upgrade cold storage to stabilize food supply. Energy concerns push firms toward efficient freezer models. Strict quality expectations influence wider adoption of controlled freezing lines. It grows through food import dependency and rising consumption.
Africa
The Africa Individual Quick Freezing Market size was valued at USD 261.44 million in 2018 to USD 423.77 million in 2024 and is anticipated to reach USD 549.57 million by 2032, at a CAGR of 2.9% during the forecast period. Africa holds a market share of 2.40% in 2024. Africa shows gradual improvement within the Global Individual Quick Freezing Market supported by expanding retail networks. Urban populations increase demand for frozen vegetables, poultry, and ready-to-cook foods. Processing capabilities remain limited but continue to grow in key countries. Export-focused producers adopt IQF systems to meet global buyer standards. Infrastructure gaps restrict technology penetration in rural areas. Governments promote investments focused on food safety and storage. Energy instability encourages adoption of compact and stable freezer designs. It moves forward through slow but consistent modernization.
Key Player Analysis:
- Marel
- JBT Corporation
- GEA Group
- The Linde Group
- Air Products & Chemicals
- Air Liquide
- Messer Group
- OctoFrost Group
- Cryogenic Systems Equipment (CSE)
- Starfrost
- Scanico A/S
- PATKOL
Competitive Analysis:
The Global Individual Quick Freezing Market features strong competition among global equipment manufacturers and freezing technology providers that supply advanced systems for high-volume processing. Major players focus on automation upgrades, energy control, and improved airflow designs to secure product quality. Producers invest in flexible models that manage mixed product loads and tighter hygiene standards. Firms compete through wider service networks and faster installation support. Many companies expand regional presence to capture demand from emerging food processing clusters. It gains further momentum from players that introduce compact freezers for smaller facilities. Innovation around refrigerant choices strengthens brand positioning. The competitive landscape remains active due to continuous technology shifts.
Recent Developments:
- In August 2025, GEA Group completed the acquisition of the Flocmix brand, broadening its portfolio for water and wastewater treatment. Flocmix, known for advanced mixing and sensor technology, brings enhanced efficiency and automation in municipal and industrial treatment, which aligns with GEA’s existing decanter centrifuge capabilities. The acquisition is intended to benefit operators worldwide by fostering more sustainable and reliable plant operations, further strengthening GEA’s role in support of global food and beverage processing ecosystems.
- Also in May 2025, GEA Group entered into a strategic partnership with EEW Group, a major waste-to-energy operator, to support the integration of state-of-the-art CO₂ capture technology into the operation of thermal waste recycling plants. Through the partnership, EEW acquired a mobile test plant from GEA, enabling the evaluation of carbon capture solutions at multiple sites starting in Delfzijl, Netherlands. The collaboration is expected to accelerate the adoption of scalable CO₂ capture, promoting decarbonization in energy-intensive industries.
- In January 2025, JBT Corporation announced the successful completion of its voluntary takeover offer of Marel hf, culminating in the merger of the two entities under the new name JBT Marel Corporation. The offer, which expired on December 20, 2024, resulted in the combined company’s shares beginning to trade under the ticker “JBTM” on both the New York Stock Exchange and Nasdaq Iceland. This milestone merger brings together JBT’s global technology solutions in food processing and Marel’s complementary equipment and automation expertise, establishing a strengthened foothold within the IQF and food processing sectors. Executives from both sides highlighted that the new corporation aims to enhance customer value, operational continuity, and innovation, with integration of systems and expanded global reach as immediate priorities.
- On October 1, 2024, GEA Group divested its North American Freezing Business to DSI Dantech, marking a significant step in partnering for new freezer sales and aftermarket services in the region. DSI Dantech acquired the intellectual property for new machines within North America, integrating relevant GEA employees and cementing itself as GEA’s exclusive partner for these offerings, thus improving service, innovation, and customer engagement for IQF solutions.
Report Coverage:
The research report offers an in-depth analysis based on Equipment Type, Application, Processing Stage, Technology, and Capacity. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing demand for high-quality frozen foods will accelerate technology adoption.
- Energy-efficient freezer models will gain strong preference among processors.
- Automation integration will improve accuracy across large production lines.
- Rising exports of fruits and seafood will push wider IQF deployment.
- Cryogenic technology will expand within delicate product categories.
- Compact IQF units will support small and mid-size processing plants.
- Improved cold-chain infrastructure will strengthen adoption in emerging regions.
- Manufacturers will design freezers that support mixed product formats.
- Digital monitoring tools will enhance cycle stability and reduce waste.
- Sustainability goals will influence equipment design and refrigerant choices.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Premium Frozen Food Demand
Consumers increasingly seek high-quality frozen foods with fresh-like texture and taste, prompting food processors to adopt IQF systems that preserve product integrity and nutritional value.
Expansion of Cold-Chain Infrastructure
Investments in modern cold storage and logistics networks, especially in emerging markets, enable wider distribution and adoption of IQF technology by ensuring product quality throughout the supply chain.
Growth in Ready-to-Cook and Convenience Foods
Rising urbanization and busy lifestyles drive demand for ready-to-cook and ready-to-eat meals, encouraging manufacturers to use IQF for consistent quality and faster meal preparation.
Technological Advancements and Automation
Continuous improvements in freezer design, energy efficiency, and automation allow processors to handle diverse product formats at higher throughput, reducing operational costs and improving product consistency.
Export Growth in Fruits, Vegetables, and Seafood
Exporters leverage IQF technology to maintain product quality during long-distance shipping, meeting international standards and expanding access to global markets.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Individual Quick Freezing (IQF) market?
At what Compound Annual Growth Rate is the Global Individual Quick Freezing Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Individual Quick Freezing (IQF) market?
What are some challenges faced by the Individual Quick Freezing (IQF) market?
Who are the major players in the Individual Quick Freezing (IQF) market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Mechanical IQF
- 1.2.2 Cryogenic IQF
- 1.3 By Application
- 1.3.1 Fruits & Vegetables
- 1.3.2 Seafood
- 1.3.3 Meat & Poultry
- 1.3.4 Dairy Products
- 1.3.5 Convenience Foods
- 1.4 By Equipment Type
- 1.4.1 Spiral Freezer
- 1.4.2 Tunnel Freezer
- 1.4.3 Box Freezer
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 17,654.24 million → 2032: USD 27,383.69 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Individual Quick Freezing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Individual Quick Freezing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Individual Quick Freezing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Individual Quick Freezing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Individual Quick Freezing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Individual Quick Freezing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Individual Quick Freezing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Individual Quick Freezing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 17,654.24 million → 2032: USD 27,383.69 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Individual Quick Freezing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Mechanical IQF
- 12.3.7.2 Cryogenic IQF
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fruits & Vegetables
- 12.4.7.2 Seafood
- 12.4.7.3 Meat & Poultry
- 12.4.7.4 Dairy Products
- 12.4.7.5 Convenience Foods
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Equipment Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Spiral Freezer
- 12.5.7.2 Tunnel Freezer
- 12.5.7.3 Box Freezer
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Individual Quick Freezing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Individual Quick Freezing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Individual Quick Freezing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Individual Quick Freezing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Marel
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 JBT Corporation
- 18.4 GEA Group
- 18.5 The Linde Group
- 18.6 Air Products & Chemicals
- 18.7 Air Liquide
- 18.8 Messer Group
- 18.9 OctoFrost Group
- 18.10 DSI Dantech
- 18.11 Scanico A/S
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

