
Market Overview:
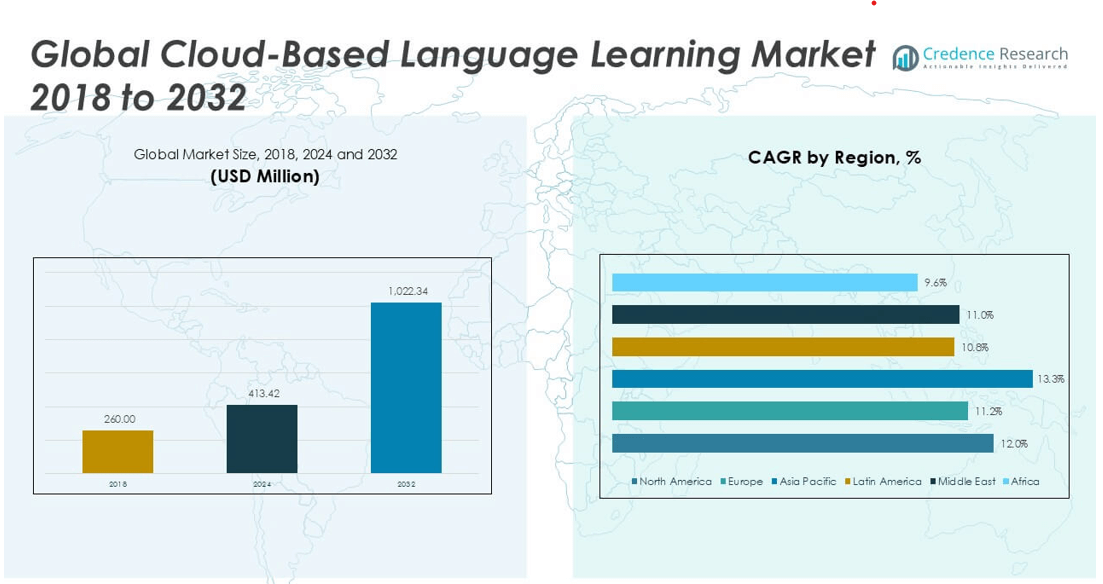
The Cloud-Based Language Learning market size was valued at USD 260.00 million in 2018, increased to USD 413.42 million in 2024, and is anticipated to reach USD 1,022.34 million by 2032, at a CAGR of 12.03% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cloud-Based Language Learning Market Size 2024 | USD 413.42 million |
| Cloud-Based Language Learning Market, CAGR | 12.3% |
| Cloud-Based Language Learning Market Size 2032 | USD 1,022.34 million |
The cloud-based language learning market is led by prominent players such as Duolingo, Babbel, Busuu, Voxy, and EF Education First Ltd., which have established strong global user bases through mobile-first platforms, AI integration, and personalized learning paths. Traditional education providers like Cambridge University Press, Pearson Plc, and Cengage Learning Holdings II Inc. have also strengthened their digital presence, offering scalable solutions for academic institutions and enterprises. Regionally, North America holds the largest market share at 34.1% in 2024, driven by high digital adoption, corporate demand, and advanced e-learning infrastructure. Asia Pacific, with a 28.7% share, follows closely due to rising internet penetration, education reforms, and growing demand for English proficiency across emerging economies.
Market Insights
- The cloud-based language learning market was valued at USD 413.42 million in 2024 and is projected to reach USD 1,022.34 million by 2032, growing at a CAGR of 12.03% during the forecast period.
- Growth is driven by increasing globalization, rising demand for multilingual employees, and the widespread adoption of mobile and e-learning platforms across educational institutions and corporate sectors.
- AI integration, gamified content, and personalized learning paths are key trends enhancing user engagement and retention, especially among younger and working-age learners.
- Duolingo, Babbel, Busuu, EF Education First, and Pearson Plc are leading players; they compete through innovation, content diversity, and expansion into emerging markets.
- North America holds the largest regional share at 34.1%, followed by Asia Pacific at 28.7% and Europe at 24.5%; English remains the dominant language segment due to global business demand, while access limitations in Africa and digital divide issues act as market restraints.
Market Segmentation Analysis:
By Language
The English segment dominates the cloud-based language learning market, accounting for the largest market share due to its global acceptance in business, education, and international communication. The increasing emphasis on English proficiency in non-native regions, particularly in Asia-Pacific and Latin America, is driving demand. Additionally, rising internet penetration and mobile-based learning platforms have made English learning more accessible and scalable. Other languages such as Spanish and Chinese are also gaining traction, fueled by cultural exchange programs, travel, and global trade, though they still lag behind English in terms of adoption and market penetration.
- For instance, Duolingo reported that over 66% of its 74.1 million monthly active users in Q1 2024 were learning English, with the highest engagement from India, Brazil, and Mexico.
By End-User:
Corporate training represents the leading end-user segment in the cloud-based language learning market, contributing significantly to overall revenue. This dominance is attributed to the growing need for multilingual communication in multinational companies and the increasing investment in employee skill development. Companies are adopting cloud-based platforms for their scalability, cost efficiency, and ease of integration into corporate training modules. K12 and higher education segments also show strong growth, supported by digital learning initiatives, government funding in education technology, and the need for early-age language acquisition.
- For instance, Rosetta Stone Enterprise Solutions trained more than 2,000 employees at Siemens AG across 12 countries in 2023, deploying its cloud-based platform within 45 days of contract initiation.
Market Overview
Increasing Globalization and Cross-Border Communication Needs
As businesses continue to expand internationally, the need for effective cross-border communication is driving the adoption of cloud-based language learning solutions. Multinational corporations are investing in multilingual training to enhance collaboration, customer service, and global competitiveness. This demand is especially evident in sectors like IT, finance, and tourism, where English and other international languages serve as operational necessities. The flexibility of cloud-based platforms allows organizations to offer accessible, scalable, and cost-effective training, enabling employees to learn at their own pace while meeting enterprise-wide language proficiency goals.
- For instance, Busuu partnered with Puma in 2024 to train over 600 retail staff in 8 different languages across Europe using its corporate platform.
Rising Adoption of E-Learning and Mobile Learning Platforms
The rapid digitization of education and training has significantly accelerated the adoption of cloud-based language learning. Educational institutions and enterprises alike are turning to e-learning and mobile platforms for their convenience, interactive features, and real-time progress tracking. Smartphones and tablets have become key enablers, especially in emerging markets where traditional classroom-based learning may be limited. This shift is further supported by advancements in AI-driven personalization and gamified content, which enhance engagement and learning outcomes. As a result, digital language learning is becoming an integral component of modern education and workforce development.
- For instance, Babbel’s mobile app recorded over 10 million active downloads in 2024 across Android and iOS platforms, with mobile users completing over 1 billion exercises throughout the year.
Government and Institutional Support for Multilingual Education
Various governments and educational authorities are actively promoting multilingual education as part of national development and inclusion strategies. Initiatives such as digital literacy programs, foreign language requirements in school curricula, and funding for educational technology have boosted the growth of cloud-based language learning. Public-private partnerships are also facilitating the integration of these solutions into national education systems. This support not only enhances accessibility in underserved regions but also drives innovation and competitiveness in the language learning technology sector, making it a key growth catalyst in both developed and developing countries.
Key Trends & Opportunities
Integration of Artificial Intelligence and Personalized Learning
The integration of artificial intelligence (AI) is transforming the cloud-based language learning landscape by enabling highly personalized and adaptive learning experiences. AI algorithms analyze user performance and behavior to tailor content, provide instant feedback, and optimize learning paths. Features such as speech recognition, real-time correction, and chatbots enhance language fluency and learner engagement. This trend is creating new opportunities for solution providers to develop advanced, user-centric platforms that cater to diverse learning styles, thereby improving retention rates and expanding their market reach.
- For instance, Pearson’s AI-driven English learning platform “Mondly by Pearson” introduced real-time speech recognition and feedback in 2024, processing over 21 million spoken exercises in six months.
Expansion into Non-English Language Markets
While English remains dominant, there is a growing opportunity in non-English language learning markets such as Mandarin, Spanish, French, and Arabic. Increased interest in cultural exchange, international travel, and trade relations is fueling demand for language skills beyond English. Cloud-based platforms are now diversifying their content libraries to support these languages, offering localized experiences to attract regional users. This expansion is especially promising in Asia, the Middle East, and Latin America, where economic growth and digital infrastructure improvements are opening new avenues for market penetration and revenue generation.
- For instance, HelloChinese surpassed 20 million downloads in 2024, with over 7 million active users globally learning Mandarin, making it one of the most downloaded Mandarin learning apps.
Key Challenges
Data Privacy and Security Concerns
Cloud-based platforms often require personal data for registration, progress tracking, and content customization, raising significant concerns around data privacy and cybersecurity. Educational institutions and enterprises handling sensitive user information must comply with stringent regulations like GDPR and other regional data protection laws. A breach or misuse of data can damage brand reputation and erode user trust. This challenge necessitates ongoing investment in secure infrastructure, encryption technologies, and transparent data practices, which can be resource-intensive for small and mid-sized providers.
Unequal Access to Digital Infrastructure
Despite growing internet penetration, disparities in digital infrastructure remain a significant barrier, especially in developing regions. Limited access to high-speed internet, affordable devices, and electricity hinders the widespread adoption of cloud-based language learning. Rural areas, in particular, face challenges in integrating digital education tools into mainstream learning. Addressing this issue requires coordinated efforts from governments, private companies, and NGOs to improve digital accessibility and bridge the urban-rural digital divide, which is crucial for inclusive market growth.
Engagement and Retention Issues Among Users
One of the persistent challenges in the cloud-based language learning market is maintaining user engagement and long-term retention. While initial enrollment may be high, many users drop off due to lack of motivation, poor user experience, or insufficient progress tracking. Platforms must continuously innovate to keep content interactive, adaptive, and aligned with user goals. Gamification, live tutor support, and social learning features are being employed to address these issues, but sustaining user interest remains a critical challenge in ensuring long-term platform success.
Regional Analysis
North America North America held the largest share in the cloud-based language learning market in 2024, accounting for approximately 34.1% of the global revenue with a market size of USD 140.81 million, up from USD 89.70 million in 2018. The region is projected to reach USD 347.70 million by 2032, growing at a CAGR of 12.0%. This growth is driven by high digital literacy, advanced e-learning infrastructure, and strong demand for multilingual corporate training. The United States, in particular, leads due to widespread adoption of AI-driven learning platforms and corporate investments in employee upskilling across multiple languages.
Europe
Europe contributed a significant 24.5% to the global cloud-based language learning market in 2024, with its market size rising from USD 66.20 million in 2018 to USD 101.03 million. It is expected to reach USD 235.50 million by 2032 at a CAGR of 11.2%. The region benefits from multilingual diversity, educational reforms promoting language acquisition, and integration of language platforms in school curricula. Countries like Germany, France, and the UK are major contributors. The demand is further fueled by increased migration, cross-border employment, and the rising need for language certification in both academic and professional settings.
Asia Pacific
Asia Pacific emerged as one of the fastest-growing regions in the cloud-based language learning market, holding 28.7% of the global share in 2024 with a market value of USD 118.67 million, up from USD 71.81 million in 2018. Forecasts project the market to reach USD 320.50 million by 2032, expanding at a robust CAGR of 13.3%. Growth in this region is driven by increasing smartphone penetration, government-led education digitization initiatives, and a rising middle-class population investing in English and other foreign language skills. Key countries contributing to this growth include China, India, Japan, and South Korea.
Latin America
Latin America accounted for around 5.2% of the cloud-based language learning market in 2024, with revenues rising from USD 13.68 million in 2018 to USD 21.49 million. The market is projected to grow to USD 48.53 million by 2032, registering a CAGR of 10.8%. Growth is fueled by rising interest in English proficiency, increasing digital infrastructure, and educational reforms across countries like Brazil, Mexico, and Argentina. The region is also witnessing increased adoption of mobile-based learning solutions, making language education more accessible, particularly in remote and underserved areas where traditional institutions are limited.
Middle East
The Middle East captured 4.9% of the global market share in 2024, with its cloud-based language learning market growing from USD 12.66 million in 2018 to USD 19.14 million, and is forecasted to reach USD 43.76 million by 2032, at a CAGR of 11.0%. The region’s growth is driven by expanding education technology adoption, government support for e-learning, and increased demand for English and French proficiency in business and academia. Countries such as the UAE and Saudi Arabia are spearheading investment in digital education platforms, aligning with their national visions for innovation and digital transformation.
Africa
Africa held the smallest share in the cloud-based language learning market in 2024, contributing 3.0% globally with a market size of USD 12.28 million, up from USD 5.95 million in 2018. It is expected to grow to USD 26.34 million by 2032, reflecting a CAGR of 9.6%. Despite infrastructure challenges, growing internet penetration, mobile phone access, and donor-backed educational programs are helping drive market growth. Demand for English, French, and Arabic is particularly strong across educational institutions and among youth seeking global employment. However, disparities in digital access remain a key constraint to broader market expansion.
Market Segmentations:
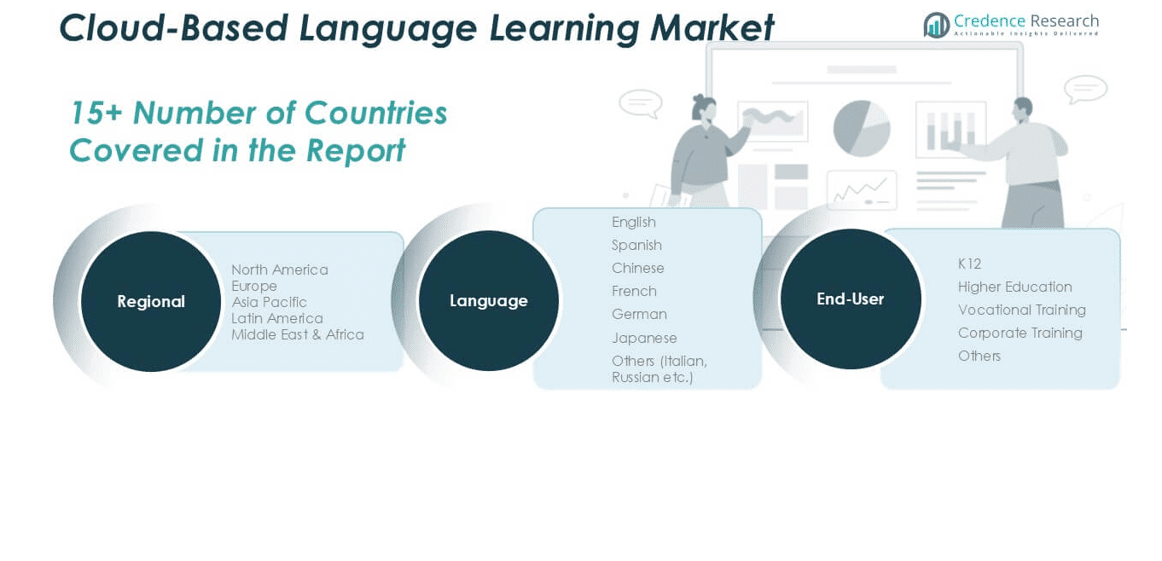
By Language:
- English
- Spanish
- Chinese
- French
- German
- Japanese
- Others (Italian, Russian, etc.)
By End-User:
- K12
- Higher Education
- Vocational Training
- Corporate Training
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the cloud-based language learning market is characterized by a mix of established education providers, edtech startups, and publishing giants, all striving to capture market share through technological innovation and global reach. Key players such as Duolingo, Babbel, Busuu, and Voxy dominate the market with user-friendly interfaces, gamified content, and AI-driven personalization that enhance learner engagement. Traditional institutions like Cambridge University Press, Pearson Plc, and Cengage Learning have also expanded their digital offerings to stay competitive. Additionally, companies like Sanako, Linguatronics, and EF Education First focus on institutional solutions catering to schools and corporate clients. Strategic partnerships, product innovation, and international expansion remain core growth strategies. The market also sees frequent mergers, acquisitions, and funding rounds, particularly for mobile-first platforms. With rising demand across both consumer and enterprise segments, competition is intensifying, pushing companies to continuously upgrade content, integrate analytics, and offer multilingual support to maintain their market position.
Key Player Analysis
- Linguatronics
- Sanako
- Okpanda
- Livemocha
- Duolingo
- Busuu
- Babbel
- 50 Languages
- Voxy
- Apollo Global Management Inc.
- Cambridge University Press
- Cengage Learning Holdings II Inc.
- EF Education First Ltd.
- Houghton Mifflin Harcourt Co.
- eSplice Ltd.
- New Oriental Education and Technology Group Inc.
- Pearson Plc
Recent Developments
- In 2025, Busuu continues its emphasis on cloud-based language learning for both individuals and businesses, offering flexible, scalable online and live classes. Busuu's focus is on providing accessible and effective language learning experiences through its platform.
- In February 2025, Houghton Mifflin Harcourt (HMH) is expected to be a prominent player in the market for digital/cloud-based English learning solutions, as the industry is rapidly shifting towards cloud-based resources with a focus on mobile learning, personalized learning paths, and the integration of artificial intelligence (AI) and analytics for language acquisition.
- In March 2023, Duolingo, the online learning platform, announced a new product “Duolingo Max” powered by OpenAI, the leading AI research and deployment company. With early access to GPT-4, Duolingo has developed new AI-driven features to provide language learners with conversation practice and in-depth explanations on answers. These features are part of the new, higher subscription tier called Duolingo Max, which is available now for iOS in the US and other select markets.
Market Concentration & Characteristics
The Cloud-Based Language Learning Market displays moderate to high market concentration, with a few global players commanding a significant share. Companies such as Duolingo, Babbel, Busuu, and EF Education First have built strong brand recognition through scalable platforms, user-focused innovation, and diverse language offerings. It remains highly competitive, with new entrants introducing AI-driven features and mobile-first solutions to differentiate their services. The market features both B2C and B2B characteristics, targeting individual learners, educational institutions, and corporate clients. Consumer demand is shifting toward flexible, self-paced learning supported by gamified content and real-time progress tracking. The presence of traditional publishers and edtech startups creates a dynamic mix of content quality, pedagogy, and technological capability. Strong regional growth, especially in Asia Pacific and Latin America, reflects rising digital adoption and interest in English and other global languages. Pricing strategies vary widely, with many companies offering freemium models to attract and retain users. Enterprise customers prioritize scalability, performance analytics, and integration with internal training systems. The market's structure supports rapid innovation cycles, driven by evolving learner preferences, mobile device usage, and institutional digitization.
Report Coverage
The research report offers an in-depth analysis based on Language, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness strong growth due to increasing demand for multilingual skills in global business and education.
- AI-driven personalization and adaptive learning features will become standard across major platforms.
- Mobile-first learning solutions will dominate user engagement, especially among younger demographics.
- Corporate training adoption will expand as companies focus on global workforce development.
- Emerging markets in Asia Pacific and Latin America will drive the next wave of user growth.
- Partnerships between tech firms and educational institutions will enhance platform credibility and reach.
- Freemium and subscription-based pricing models will continue to attract and retain diverse learners.
- Gamified content and real-time feedback will increase retention and user satisfaction.
- Data privacy and compliance with regional regulations will remain a critical focus for providers.
- Cloud-based platforms will increasingly integrate with formal education systems and enterprise training programs.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Cloud-Based Language Learning Market?
What factors are driving the growth of the Cloud-Based Language Learning Market?
What are some challenges faced by the Cloud-Based Language Learning Market?
Who are the major players in the Cloud-Based Language Learning Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cloud-Based Language Learning Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cloud-Based Language Learning Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 413.42 million → 2032: USD 1,022.34 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cloud-Based Language Learning Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cloud-Based Language Learning Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cloud-Based Language Learning Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cloud-Based Language Learning Market Drivers
- 3.3 Cloud-Based Language Learning Market Restraints & Challenges
- 3.4 Cloud-Based Language Learning Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cloud-Based Language Learning Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cloud-Based Language Learning Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cloud-Based Language Learning category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cloud-Based Language Learning Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Cloud-Based Language Learning Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Cloud-Based Language Learning. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cloud-Based Language Learning Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cloud-Based Language Learning Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Cloud-Based Language Learning Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cloud-Based Language Learning (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Cloud-Based Language Learning
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cloud-Based Language Learning Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Cloud-Based Language Learning Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cloud-Based Language Learning Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cloud-Based Language Learning Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cloud-Based Language Learning Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cloud-Based Language Learning Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cloud-Based Language Learning Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cloud-Based Language Learning Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
