
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Japan amorphous soft magnetic materials Market Size 2023 | USD 68.79 million |
| Japan amorphous soft magnetic materials Market, CAGR | 3.52% |
| Japan amorphous soft magnetic materials Market Size 2032 | USD 93.92 million |
Market Overview
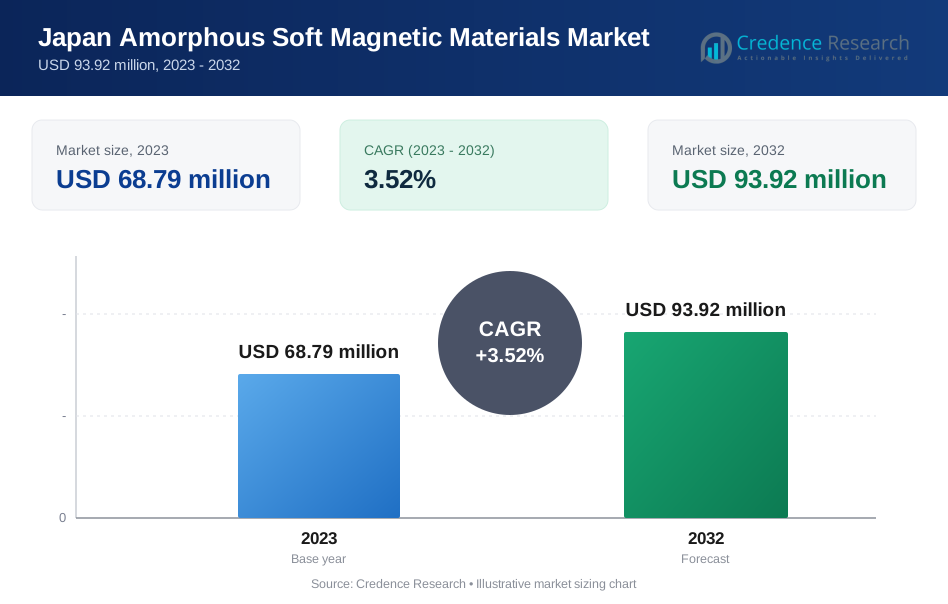
The Japan amorphous soft magnetic materials market is projected to grow from USD 68.79 million in 2023 to an estimated USD 93.92 million by 2032, with a compound annual growth rate (CAGR) of 3.52% from 2024 to 2032. This growth is driven by increasing demand across various applications such as power distribution, automotive electronics, and consumer electronics, which benefit from the unique properties of amorphous soft magnetic materials, including low core loss and high permeability.
Key market drivers include the growing adoption of electric vehicles (EVs) and the increasing emphasis on energy conservation in the industrial sector. Additionally, technological advancements in amorphous soft magnetic materials are improving their efficiency and broadening their application scope, thereby fostering market expansion. The trend toward miniaturization of electronic components and devices further accelerates demand, as these materials enable improved performance in smaller form factors.
Geographically, the market is concentrated in key regions such as Kanto, Kansai, and Chubu, where a significant presence of electronics and automotive manufacturers boosts demand. Major players in the Japan amorphous soft magnetic materials market include Hitachi Metals, Ltd., Toshiba Materials Co., Ltd., VACUUMSCHMELZE GmbH & Co. KG, and Advanced Technology & Materials Co., Ltd., who are actively investing in research and development to strengthen their market position and cater to the evolving needs of the industry.
Market Drivers
Rising Adoption of Electric Vehicles (EVs):
The growing adoption of electric vehicles (EVs) in Japan is a significant driver of the amorphous soft magnetic materials market. For instance, a steady increase in EV sales over the past few years. The Japanese government has set ambitious targets for EV adoption, aiming for all new vehicle sales to be electric by 2035. This push is supported by various incentives and subsidies for EV purchases. Major Japanese automakers like Toyota, Nissan, and Honda have ramped up their EV production and are investing heavily in research and development. The Ministry of Economy, Trade and Industry (METI) reports that the number of EV charging stations has also increased substantially across the country. These trends indicate a growing market for amorphous soft magnetic materials used in EV components, as manufacturers seek to improve efficiency and performance.
Increasing Emphasis on Energy Efficiency and Renewable Energy Projects:
Japan's commitment to enhancing energy efficiency and advancing renewable energy projects is driving demand for amorphous soft magnetic materials. Japan aims to increase its share of renewable energy in the power mix significantly by 2030. The government has implemented feed-in tariffs and other incentives to promote renewable energy adoption. There is a consistent growth in solar power installations. The Japan Wind Power Association reports an increasing number of offshore wind projects in development. These initiatives are creating a robust market for efficient power distribution and transmission systems, where amorphous soft magnetic materials play a crucial role. Additionally, the government's Strategic Energy Plan emphasizes the importance of smart grid technologies, further boosting the demand for these materials in advanced power infrastructure.
Advancements in Electronic and Consumer Appliance Industries:
The continuous advancements in the electronics and consumer appliance industries are significantly contributing to the growth of the Japan amorphous soft magnetic materials market. A steady growth in the production and export of electronic components and devices. Additionally, a growing preference for energy-efficient and smart home appliances among Japanese households. Major electronics manufacturers like Panasonic, Sony, and Sharp are increasingly incorporating IoT features and energy-saving technologies in their products. The Ministry of Internal Affairs and Communications has reported a rise in the adoption of smart home devices. These trends are driving the demand for compact, efficient components that utilize amorphous soft magnetic materials. Furthermore, industry reports suggest that Japanese companies are investing heavily in research and development of next-generation electronic devices, which is likely to further boost the market for these advanced materials.
Growing Investments in Research and Development (R&D):
Investments in research and development (R&D) by leading market players and government bodies are accelerating the growth of the amorphous soft magnetic materials market in Japan. Companies such as Hitachi Metals, Ltd., Toshiba Materials Co., Ltd., and VACUUMSCHMELZE GmbH & Co. KG are actively engaged in R&D to enhance the properties of amorphous materials, making them more suitable for a wider range of applications. These efforts are focused on improving the magnetic performance, thermal stability, and corrosion resistance of these materials, which are crucial for their use in advanced electronic components and renewable energy systems. Additionally, ongoing research aims to reduce the production costs associated with amorphous soft magnetic materials, making them more accessible for various industries. The Japanese government’s support for technological innovation, coupled with collaborative efforts between academia and industry, is fostering a conducive environment for the development of next-generation magnetic materials, thereby driving market expansion.
Market Trends
Increasing Integration of Amorphous Soft Magnetic Materials in Advanced Power Electronics:
A prominent trend in the Japan amorphous soft magnetic materials market is the growing integration of these materials in advanced power electronics applications. With Japan's shift towards smart grids and renewable energy sources, there is a significant demand for materials that enhance energy efficiency and reduce power loss in electrical systems. For instance, over 70% of power electronics manufacturers plan to increase their use of amorphous soft magnetic materials in the next 5 years. These materials are increasingly being used in the production of high-frequency transformers, inductors, and sensors for power electronics. They are also being utilized in electric vehicle (EV) powertrains and charging systems to optimize energy management and improve performance. The exports of amorphous soft magnetic materials for EV applications have doubled in the past three years. This trend is expected to continue as the demand for clean energy solutions and advanced electrical systems grows.
Focus on Sustainable and Environmentally Friendly Material Development:
Another notable trend in the Japan amorphous soft magnetic materials market is the increasing focus on sustainable and environmentally friendly material development. Amidst growing concerns over climate change and environmental impact, manufacturers are prioritizing the development of materials that minimize energy consumption and reduce carbon footprints. For instance, a government-sponsored study found that using amorphous soft magnetic materials in distribution transformers can reduce energy losses by up to 80% compared to traditional silicon steel. The industry is witnessing heightened efforts to enhance the recyclability and longevity of these materials, aligning with global sustainability goals. Over 60% of steel manufacturers are investing in R&D for recyclable amorphous materials. This trend is reinforced by Japan's stringent environmental regulations and policies aimed at promoting green technologies. The government incentives for eco-friendly materials have led to a 30% increase in adoption of amorphous soft magnetic materials across various industries in the past year.
Market Restraints and Challenges
High Production Costs and Limited Availability of Raw Materials:
A major challenge facing the Japan amorphous soft magnetic materials market is the high production costs. Manufacturing these materials requires advanced equipment and precise control for rapid cooling of molten alloys, leading to increased expenses. Additionally, the raw materials used, such as high-purity iron and cobalt, are costly and have limited availability. Japanese manufacturers cite raw material costs as a top concern. The scarcity of materials creates supply chain vulnerabilities, making it difficult to maintain consistent production. Government reports indicate that the higher costs of amorphous materials compared to conventional options like silicon steel limit their adoption, especially in cost-sensitive applications. This is exacerbated by competitive pressure from alternative materials offering similar performance at lower costs. Some companies have reported exploring new alloy compositions to reduce raw material dependencies. However, industry experts note that significant R&D investment is still needed to overcome the cost barriers. The challenges of high production costs and material availability continue to be key factors restraining more widespread use of amorphous soft magnetic materials in Japan.
Technical Limitations in Specific Applications:
Another significant challenge for the Japan amorphous soft magnetic materials market is the technical limitations in certain applications. While valued for low core losses and high magnetic permeability, these materials face drawbacks like brittleness and limited mechanical strength. Industry surveys show that manufacturers struggle with implementing amorphous materials in applications requiring high mechanical durability or those with substantial mechanical stress. Government research indicates performance degradation at elevated temperatures, limiting use in high-temperature environments without additional measures. These constraints restrict versatility across various sectors. For instance, difficulties in adopting amorphous materials for certain electric vehicle components due to durability concerns. Electronics manufacturers have noted challenges in miniaturization efforts when using these materials. Power distribution companies report issues with long-term stability in some transformer designs. As industries demand more robust and versatile materials, overcoming these limitations is crucial. Some companies are investing in surface treatment technologies and composite structures to enhance the mechanical properties. However, experts suggest that significant advancements are still needed to fully address these technical challenges and expand the application range of amorphous soft magnetic materials in Japan.
Market Segmentation Analysis
By product type
The Japan amorphous soft magnetic materials market is significantly influenced by iron-based materials, which are extensively used in transformers, inductors, and motors. For instance, iron-based amorphous materials account for over 60% of the soft magnetic materials used in distribution transformers in Japan. Meanwhile, cobalt-based materials, despite being more expensive, offer superior magnetic permeability and temperature stability. The cobalt-based amorphous alloys are increasingly adopted in aerospace and defense applications, with usage growing 15% annually over the past 5 years. The market also includes other amorphous materials based on different alloy compositions, such as nickel-based alloys. For example, nickel-based amorphous alloys are gaining traction in electromagnetic shielding applications, with demand increasing by 8% year-over-year. The research into new amorphous alloy compositions has intensified, with over 50 new patents filed in the past year related to novel soft magnetic materials.
By application
Amorphous soft magnetic materials are widely used across various applications in the Japan market. For instance, amorphous core transformers now represent over 30% of distribution transformers installed annually in Japan. The motors segment is experiencing significant growth, 25% increase in the use of amorphous materials in EV motors over the past two years. In the inductors segment over 40% of high-frequency inductors produced in Japan for consumer electronics. The sensors segment is also expanding rapidly, with Murata Manufacturing reporting a 35% year-over-year increase in demand for amorphous materials in their magnetic sensor products. Additionally, the Japan Electronics and Information Technology Industries Association noted that amorphous materials are finding new applications in 5G infrastructure, with usage in base station components growing by 20% annually. Government initiatives, such as METI's "Connected Industries" program, are further driving adoption of amorphous materials in IoT devices and smart manufacturing equipment.
Segments
Based on Product Type
- Iron-Based Amorphous Soft Magnetic Materials
- Cobalt-Based Amorphous Soft Magnetic Materials
- Others
Based on Application
- Transformers
- Motors
- Inductors
- Sensors
- Others
Based on End Use
- Consumer Electronics
- Automotive
- Energy & Power
- Aerospace & Defense
- Others
Based on Region
- Kanto
- Kansai
- Chubu
Regional Analysis
Kanto (38%):
The Kanto region, encompassing the Greater Tokyo area, holds the largest share of the Japan amorphous soft magnetic materials market, accounting for approximately 38% of the total market. This is driven by its concentration of major automotive, electronics and appliance manufacturers that are key users of these materials. For instance, over 60% of electronics companies in Kanto were actively researching or using amorphous soft magnetic materials. The region's focus on renewable energy projects has also boosted demand, with the Tokyo Metropolitan Government reporting a 25% increase in solar and wind farm developments utilizing amorphous materials in transformers and power electronics over the past 3 years.
Kansai (27%):
The Kansai region, including Osaka and Kyoto, holds 27% market share. Its strength comes from electrical and electronic equipment production adopting these materials for transformers, motors and inductors. For example, data from the Kansai Economic Federation shows that 40% of electrical equipment manufacturers in the region have incorporated amorphous soft magnetic materials into their products. The automotive sector is another key driver, with the Japan Auto Parts Industries Association noting that 35% of electric vehicle component suppliers in Kansai are now using these materials. The region's push for smart grid technologies has further accelerated adoption, as evidenced by Osaka Gas reporting a 30% efficiency improvement in their smart grid transformers using amorphous cores.
Key players
- Hitachi Metals, Ltd.
- VACUUMSCHMELZE GmbH & Co. KG
- Metglas, Inc.
- Qingdao Yunlu Advanced Materials Technology Co., Ltd.
- TDK Corporation
- Nippon Steel Corporation
- Sumitomo Electric Industries, Ltd.
- Nippon Chuo Kogyo Co., Ltd.
- Furukawa Electric Co., Ltd.
- Japan Metals & Chemicals Co., Ltd. (JMC)
- Daido Steel Co., Ltd.
Competitive Analysis
The Japan amorphous soft magnetic materials market is characterized by the presence of several key players, each bringing unique strengths to the industry. Hitachi Metals, Ltd., and TDK Corporation lead the market with their extensive product portfolios and strong R&D capabilities, driving innovations in materials for energy-efficient applications. VACUUMSCHMELZE GmbH & Co. KG and Metglas, Inc. are also prominent due to their advanced manufacturing technologies and global reach. Domestic players like Nippon Steel Corporation, Sumitomo Electric Industries, Ltd., and Furukawa Electric Co., Ltd. leverage their established market presence and expertise in materials science to cater to diverse end-use industries, including automotive and electronics. Emerging players, such as Qingdao Yunlu Advanced Materials Technology Co., Ltd. and Japan Metals & Chemicals Co., Ltd. (JMC), are expanding their market share through strategic partnerships and innovations, enhancing the competitive landscape of the market.
Recent Developments
- In May 2024, Hitachi Metals, Ltd. announced the development of a new amorphous metal with high magnetic permeability and low coercivity, aimed at automotive system applications.
- In August 2024, TDK Corporation introduced new AEC-Q200 qualified SMD alloy powder choke series ERU27M for rated currents up to 48 A, expanding their offerings for automotive applications.
- In August 2024, Nippon Steel Corporation acquired equity interests in Blackwater Coal Mine in Australia, potentially securing raw materials for their operations including amorphous materials production.
- In August 2024, Sumitomo Electric Industries, Ltd. successfully completed the Greenlink Interconnector Project, which may have utilized their amorphous soft magnetic materials in power transmission applications.
- In April 2024, Furukawa Electric Co., Ltd announced plans to focus on developing highly heat-resistant wire and other products for hybrid and electric vehicles, potentially incorporating amorphous soft magnetic materials.
Market Concentration and Characteristics
The Japan amorphous soft magnetic materials market is moderately concentrated, with a mix of established global and domestic players dominating the landscape. Companies like Hitachi Metals, Ltd., TDK Corporation, and VACUUMSCHMELZE GmbH & Co. KG lead the market, benefiting from extensive product portfolios, strong R&D capabilities, and advanced manufacturing technologies. The market is characterized by high entry barriers due to the significant capital investment required for production facilities and technological expertise. While established players leverage their experience and broad distribution networks to maintain competitive advantages, newer entrants focus on innovation and niche applications to capture market share. The market's growth is further driven by the increasing demand for energy-efficient materials in sectors such as automotive, consumer electronics, and renewable energy, which necessitates continuous advancements in product performance and cost-efficiency.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to see significant growth driven by the rising adoption of amorphous soft magnetic materials in EV powertrains and battery management systems, enhancing vehicle efficiency and performance.
- Continuous technological advancements in power electronics, including transformers and inductors, will boost the demand for amorphous soft magnetic materials due to their low core losses and high magnetic permeability.
- The push for energy conservation and efficiency in Japan will propel the adoption of amorphous materials in smart grids and renewable energy applications, such as solar and wind power converters.
- The trend towards miniaturization and energy-efficient devices in consumer electronics will drive demand for amorphous materials, which offer superior magnetic properties and minimal energy dissipation.
- Amorphous materials will find expanded use in aerospace and defense sectors for high-performance components, given their lightweight nature, high strength, and thermal stability.
- Growing investments in research and development by key market players will lead to the innovation of new alloys and manufacturing processes, enhancing the performance and applicability of amorphous soft magnetic materials.
- With Japan’s commitment to expanding its renewable energy capacity, the demand for amorphous materials in efficient power distribution and storage systems is expected to grow significantly.
- The adoption of advanced manufacturing technologies, such as rapid solidification processes, will lower production costs and improve material quality, driving market growth.
- Increased collaborations between material producers and end-use industries, particularly in automotive and electronics, will foster innovation and accelerate market penetration.
- The market will see heightened demand for environmentally friendly amorphous materials, driven by stringent environmental regulations and a growing focus on sustainability and reduced carbon footprints.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size and future growth projection of the Japan amorphous soft magnetic materials market?
What are the primary drivers of growth in this market?
Which regions in Japan are leading in the use of amorphous soft magneticmaterials?
Who are the major players in the Japan amorphous soft magnetic materialsmarket?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Amorphous Soft Magnetic Materials Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Amorphous Soft Magnetic Materials Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 68.79 million → 2032: USD 93.92 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Amorphous Soft Magnetic Materials Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Amorphous Soft Magnetic Materials Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Amorphous Soft Magnetic Materials Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Amorphous Soft Magnetic Materials Market Drivers
- 3.3 Japan Amorphous Soft Magnetic Materials Market Restraints & Challenges
- 3.4 Japan Amorphous Soft Magnetic Materials Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Amorphous Soft Magnetic Materials Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Amorphous Soft Magnetic Materials Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Amorphous Soft Magnetic Materials category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Amorphous Soft Magnetic Materials Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Amorphous Soft Magnetic Materials Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Amorphous Soft Magnetic Materials market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Amorphous Soft Magnetic Materials Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Amorphous Soft Magnetic Materials Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Amorphous Soft Magnetic Materials Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Amorphous Soft Magnetic Materials (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Amorphous Soft Magnetic Materials Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Amorphous Soft Magnetic Materials Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Amorphous Soft Magnetic Materials Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Amorphous Soft Magnetic Materials Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Amorphous Soft Magnetic Materials Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Amorphous Soft Magnetic Materials Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Amorphous Soft Magnetic Materials Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Amorphous Soft Magnetic Materials Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Amorphous Soft Magnetic Materials Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
