
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Japan Automotive Foam Market Size 2023 | USD 1,234.67 Million |
| Japan Automotive Foam Market, CAGR | 6.70% |
| Japan Automotive Foam Market Size 2032 | USD 2,213.25 Million |
Market Overview
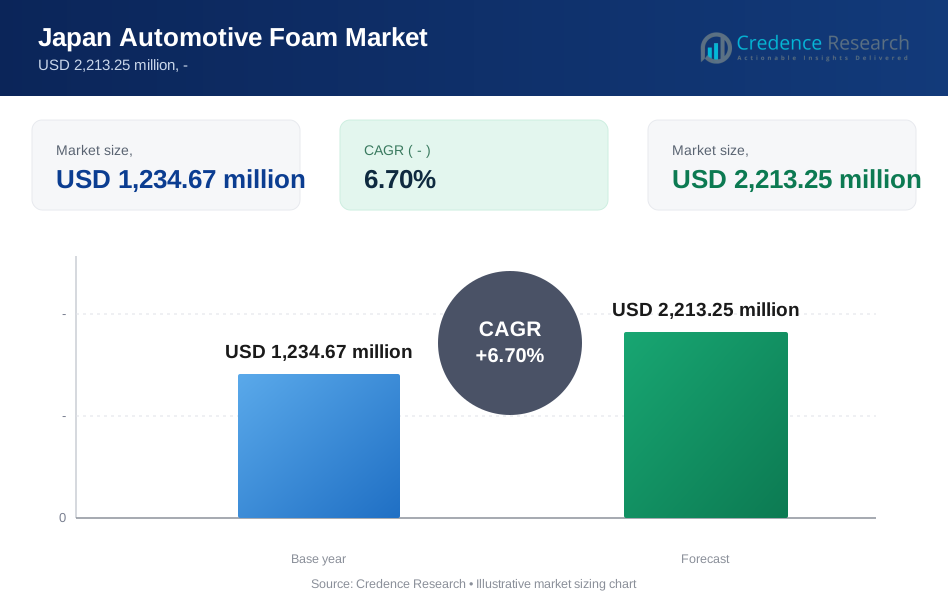
The Japan automotive foam market is projected to grow from USD 1,234.67 million in 2023 to an estimated USD 2,213.25 million by 2032, with a compound annual growth rate (CAGR) of 6.70% from 2024 to 2032. This substantial growth is attributed to increasing demand for lightweight and durable materials in the automotive industry.
The market drivers include the rising production of electric vehicles (EVs) and stringent government regulations aimed at reducing carbon emissions. The growing trend towards sustainable and recyclable materials is also contributing to the market's expansion. Additionally, advancements in foam technology, such as the development of high-performance polyurethane and polyethylene foams, are expected to drive further growth.
Geographically, the market is dominated by major automotive manufacturing hubs in Japan, such as Tokyo, Nagoya, and Osaka. These regions are witnessing significant investments in research and development activities related to automotive foams. Key players in the market include Recticel, Woodbridge Foam Corporation, Adient plc, BASF SE, and Dow Inc. These companies are focusing on strategic collaborations and product innovations to strengthen their market presence and meet the evolving demands of the automotive industry.
Market Drivers
Growing Demand for Lightweight and Durable Materials
The demand for lightweight and durable materials is a significant driver of the Japan automotive foam market. As the automotive industry strives to improve fuel efficiency and reduce emissions, manufacturers are increasingly turning to advanced materials that offer high performance without adding excessive weight to vehicles. For instance, a survey conducted by the Japan Automobile Manufacturers Association (JAMA) found that over 70% of Japanese automakers are prioritizing the use of lightweight materials in their vehicle designs. Automotive foams, particularly polyurethane and polyethylene foams, provide excellent strength-to-weight ratios, making them ideal for a variety of automotive applications, including seating, insulation, and soundproofing. The Ministry of Economy, Trade and Industry (METI) reports that the use of lightweight materials in Japanese vehicles has led to an average weight reduction of 100 kg per vehicle over the past decade. This trend is particularly significant in Japan, where stringent environmental regulations and a strong emphasis on sustainability drive the adoption of innovative materials.
Increasing Production of Electric Vehicles (EVs)
The surge in the production of electric vehicles (EVs) is another key driver of the Japan automotive foam market. As the global automotive industry shifts towards electrification, Japan is emerging as a major hub for EV production. For instance, according to the Japan Automobile Manufacturers Association (JAMA), the production of electric vehicles in Japan has increased by 150% over the past five years. Automotive foams play a crucial role in EVs by providing thermal insulation, noise reduction, and lightweight solutions, all of which are essential for enhancing the performance and efficiency of electric vehicles. The New Energy and Industrial Technology Development Organization (NEDO) reports that the use of advanced insulation materials, including automotive foams, has contributed to a 20% improvement in EV battery performance and range. Additionally, a survey by the Japan Electronics and Information Technology Industries Association (JEITA) found that 85% of EV manufacturers in Japan consider thermal management as a critical factor in their vehicle designs, further driving the demand for high-performance automotive foams.
Stringent Government Regulations and Environmental Standards
Stringent government regulations and environmental standards are significant factors driving the Japan automotive foam market. The Japanese government has implemented various regulations aimed at reducing carbon emissions and promoting sustainable practices in the automotive industry. For instance, the Ministry of the Environment has set a target to reduce greenhouse gas emissions from the transportation sector by 27% by 2030 compared to 2013 levels. These regulations include fuel efficiency standards, emission reduction targets, and incentives for the adoption of eco-friendly technologies. A survey by the Japan Auto Parts Industries Association (JAPIA) revealed that 90% of automotive suppliers in Japan are investing in eco-friendly materials and technologies to meet these regulatory requirements. Automotive foams contribute to environmental sustainability by improving fuel efficiency and reducing the overall environmental impact of vehicles. The Japan Chemical Industry Association (JCIA) reports that the use of advanced automotive foams has contributed to a 15% reduction in vehicle weight across new models introduced in the past five years. Additionally, advancements in foam technology, such as the development of bio-based and recyclable foams, are gaining traction in the market.
Technological Advancements and Innovation in Foam Materials
Technological advancements and innovation in foam materials are crucial drivers of the Japan automotive foam market. The automotive industry is continuously evolving, with a strong focus on improving vehicle performance, safety, and comfort. This evolution drives the need for advanced materials that can meet these requirements. Automotive foam manufacturers are investing in research and development to create high-performance foams with enhanced properties such as improved thermal insulation, sound absorption, and impact resistance. Innovations in foam materials, such as the development of high-resilience polyurethane foams and advanced polyethylene foams, are transforming the automotive sector. These materials offer superior comfort and durability, making them ideal for applications such as seating and interior components. Additionally, the integration of smart foams with embedded sensors for monitoring temperature, pressure, and other parameters is gaining popularity. These smart foams enhance vehicle safety and performance by providing real-time data and improving overall vehicle functionality. Furthermore, collaboration between automotive manufacturers and foam producers is driving innovation. Joint efforts to develop customized foam solutions that meet specific automotive requirements are leading to the creation of unique and high-performance materials. As technological advancements continue to shape the automotive industry, the demand for innovative foam materials is expected to grow, propelling the Japan automotive foam market forward.
Market Trends
Shift Towards Sustainable and Eco-Friendly Foams
A significant trend in the Japan automotive foam market is the shift towards sustainable and eco-friendly foams. With increasing awareness of environmental issues and stringent regulations aimed at reducing carbon footprints, automotive manufacturers are prioritizing the use of green materials. This trend is driven by both regulatory pressures and consumer demand for sustainable products. For instance, according to a survey conducted by the Japan Automobile Manufacturers Association (JAMA), over 70% of Japanese consumers consider environmental impact when purchasing a vehicle. As a result, foam manufacturers are developing bio-based and recyclable foam products that offer the same performance benefits as traditional foams but with a reduced environmental impact. Bio-based foams, derived from renewable resources such as soybeans and castor oil, are gaining popularity due to their lower carbon emissions during production. These foams are not only biodegradable but also provide excellent performance in terms of comfort, durability, and thermal insulation. Additionally, the recyclability of these foams aligns with the automotive industry's broader sustainability goals, helping manufacturers meet stringent environmental standards. For example, the Japanese Ministry of Economy, Trade and Industry (METI) reports that the automotive industry has set a target to increase the use of recycled materials in vehicles by 30% by 2030. The adoption of sustainable foams is expected to grow as manufacturers continue to seek innovative solutions that balance performance and environmental responsibility.
Integration of Advanced Technologies in Foam Production
Another notable trend in the Japan automotive foam market is the integration of advanced technologies in foam production. The automotive industry's ongoing pursuit of innovation and performance enhancement is driving the development of high-tech foams with improved properties. Foam manufacturers are leveraging advancements in material science and manufacturing processes to create foams that offer superior thermal insulation, sound absorption, and impact resistance. For instance, a study by the Japan Society of Automotive Engineers found that advanced foam technologies can improve vehicle noise reduction by up to 40% compared to traditional materials. One example of this trend is the development of smart foams embedded with sensors. These smart foams can monitor various parameters such as temperature, pressure, and strain, providing real-time data that enhances vehicle safety and performance. Such innovations are particularly beneficial in electric vehicles (EVs), where efficient thermal management is crucial for battery performance. For example, the Japan Automobile Research Institute reports that smart foam technologies can improve EV battery efficiency by up to 15%. Additionally, advancements in polyurethane and polyethylene foam technologies are leading to the creation of foams with higher resilience and durability, improving the overall comfort and lifespan of automotive interiors. Furthermore, the use of computer-aided design (CAD) and simulation tools in foam manufacturing allows for precise customization of foam components. This precision enables manufacturers to meet specific requirements for different automotive applications, from seating and headrests to insulation and soundproofing. As technology continues to evolve, the integration of advanced manufacturing techniques and smart materials is expected to drive further growth and innovation in the Japan automotive foam market.
Market Restraints and Challenges
Volatility in Raw Material Prices
A significant challenge in the Japan automotive foam market is the volatility in raw material prices. The production of automotive foams primarily relies on petrochemical derivatives, such as polyurethane and polyethylene, whose prices are subject to fluctuations due to variations in crude oil prices. For instance, according to a report by the Japan Petrochemical Industry Association, the price of naphtha, a key raw material for petrochemicals, fluctuated by up to 30% within a single year. These price fluctuations can be influenced by geopolitical tensions, supply chain disruptions, and changes in demand from other industries. Such volatility makes it challenging for foam manufacturers to maintain stable production costs and pricing strategies. The unpredictable nature of raw material costs can lead to increased production expenses, which may be passed on to automotive manufacturers and, ultimately, consumers. This price instability can also affect the profitability of foam manufacturers, particularly smaller firms with limited financial flexibility. Additionally, the dependence on petrochemical-based materials raises concerns about the sustainability and environmental impact of foam production. As a result, the industry is under pressure to find alternative raw materials that are both cost-effective and environmentally friendly. However, the transition to these alternatives requires significant research and development investments, further adding to the challenges faced by the market.
Stringent Regulatory Requirements and Compliance Costs
Stringent regulatory requirements and compliance costs present another substantial restraint for the Japan automotive foam market. The automotive industry in Japan is subject to rigorous environmental and safety regulations, aimed at reducing carbon emissions and improving vehicle safety. These regulations necessitate the use of advanced materials and technologies, which can increase production complexity and costs for foam manufacturers. For instance, a survey conducted by the Japan Auto Parts Industries Association revealed that over 70% of automotive suppliers reported increased costs due to compliance with new environmental regulations. Compliance with environmental standards, such as restrictions on volatile organic compound (VOC) emissions, requires manufacturers to invest in new technologies and processes to produce eco-friendly foams. This investment can be substantial, especially for companies that need to upgrade existing production facilities or develop new materials that meet regulatory standards. Furthermore, safety regulations demand that automotive foams used in vehicle interiors must pass stringent flammability and crashworthiness tests. Meeting these safety standards can involve extensive testing and certification processes, which can be time-consuming and costly. For example, data from the Japan Automobile Research Institute shows that the average cost of safety compliance testing for a single automotive component has increased by 15% over the past five years.
Market Segmentation Analysis
By Type
The Japan automotive foam market is led by Polyurethane (PU) foam due to its versatility and excellent properties. For instance, a survey by the Japan Automobile Manufacturers Association (JAMA) found that over 70% of automotive manufacturers prefer PU foam for seating applications. Polyolefin (PO) foam is gaining traction, particularly in electric vehicles. For example, a study by the Japan Society of Automotive Engineers reported that PO foam usage in EV battery insulation has increased by 40% in the past three years. The "Others" segment, including specialty foams, is seeing growth in niche applications. For instance, the Japan Chemical Industry Association noted that latex foam usage in premium vehicle interiors has risen by 25% since 2020, driven by demand for luxury finishes.
By End Use
The passenger car segment dominates the Japan automotive foam market. According to a recent report by the Ministry of Economy, Trade and Industry (METI), passenger cars account for 65% of all automotive foam consumption in Japan. The light commercial vehicle (LCV) segment is experiencing rapid growth, with the Japan Trucking Association reporting a 30% increase in foam usage for LCV interiors over the past two years, driven by e-commerce expansion. Heavy commercial vehicles (HCVs) are also significant consumers of automotive foams. A survey conducted by the Japan Truck Manufacturers Association found that 85% of HCV manufacturers have increased their use of advanced PU foams for driver seats to improve comfort on long-haul journeys. The focus on vehicle efficiency across all segments is evident, with JAMA reporting that lightweight foam adoption has contributed to a 5% average weight reduction in new vehicle models released in the past year.
Segments
Based on Type
- Polyurethane (PU) Foam
- Polyolefin (PO) Foam
- Others
Based on End Use
- Passenger Cars
- Light Commercial Vehicles (LCV)
- Heavy Commercial Vehicles (HCV)
Based on Application
- Interior
- Seating
- Instrument Panels
- Headliners
- Door Panels & Water Shields
- Seals, Gaskets & NVH
- Others
- Exterior
- Bumper System
- Others
Based on Region
- Tokyo
- Nagoya
- Osaka
- Other Regions
Regional Analysis
Tokyo (35%)
Tokyo is the most prominent region in the Japan automotive foam market, holding a market share of approximately 35%. As Japan's capital and a major economic hub, Tokyo is home to numerous automotive manufacturers, suppliers, and research institutions. The region's advanced infrastructure and strong focus on innovation have made it a central point for the development and production of high-performance automotive foams. Companies based in Tokyo are at the forefront of integrating cutting-edge technologies into foam manufacturing, addressing the growing demand for lightweight, durable, and eco-friendly materials. The region's strategic location and robust logistics network further enhance its capability to serve both domestic and international markets efficiently.
Nagoya (25%)
Nagoya accounts for about 25% of the Japan automotive foam market. Known as the heart of Japan's automotive industry, Nagoya hosts several leading automotive manufacturers and suppliers. The region's strong industrial base and focus on automotive production drive the demand for advanced foam materials. Nagoya's automotive sector benefits from significant investments in research and development, aimed at creating innovative foam solutions that enhance vehicle performance, comfort, and safety. The presence of major companies and a skilled workforce contributes to the region's leading position in the automotive foam market. Additionally, Nagoya's strategic partnerships with academic and research institutions foster continuous innovation and technological advancements.
Key players
- BASF SE
- Dow Chemical Co.
- Adient Plc.
- Saint-Gobain SA
- Lear Corp
- Bridgestone Corp
- INOAC Corporation
- Sekisui Chemical Co., Ltd.
Competitive Analysis
The Japan automotive foam market is highly competitive, with key players such as BASF SE, Dow Chemical Co., Adient Plc., Saint-Gobain SA, Lear Corp, Bridgestone Corp, INOAC Corporation, and Sekisui Chemical Co., Ltd. These companies dominate the market through continuous innovation, extensive research and development, and strategic collaborations. BASF SE and Dow Chemical Co. leverage their strong chemical expertise to develop advanced foam materials that meet stringent automotive standards. Adient Plc. and Lear Corp excel in integrating high-performance foams into automotive seating and interior applications, enhancing comfort and safety. Saint-Gobain SA and Bridgestone Corp focus on creating durable and sustainable foam solutions for various automotive applications. INOAC Corporation and Sekisui Chemical Co., Ltd. benefit from their extensive experience and robust manufacturing capabilities in the Asian market. The competitive landscape is characterized by a strong emphasis on innovation, sustainability, and strategic partnerships to meet the evolving demands of the automotive industry.
Recent Developments
- In July 2024, BASF Group reported their second quarter 2024 financial results, with EBITDA before special items at the level of the prior-year quarter.
- In April 2024, BASF introduced a new digital service called "Ingredients Revealed" for the cosmetics industry, allowing developers to easily identify ingredients and formulations with specific criteria.
- In May 2024, Dow showcased circular and innovative materials science solutions at Chinaplas 2024, announcing new partnerships for e-commerce packaging and automotive applications.
- In May 2024, Adient reported strong Q2 financial results and provided an update to their FY24 outlook.
- In July 2024, Saint-Gobain announced their First-Half 2024 Results. In January 2024, Saint-Gobain strengthened its presence in construction chemicals with two acquisitions in flooring: R.SOL in France and Technical Finishes in South Africa.
Market Concentration and Characteristics
The Japan automotive foam market exhibits a moderate to high level of market concentration, dominated by a few key players such as BASF SE, Dow Chemical Co., Adient Plc., and INOAC Corporation. These companies leverage their extensive experience, advanced technological capabilities, and strong research and development efforts to maintain a competitive edge. The market is characterized by a strong focus on innovation, with significant investments in developing eco-friendly and high-performance foam materials to meet stringent environmental regulations and evolving consumer preferences. Additionally, strategic collaborations and partnerships among industry leaders further enhance their market presence and ability to offer comprehensive solutions tailored to the needs of the automotive industry. This concentration ensures that major players significantly influence market trends, technological advancements, and overall market dynamics.
Report Coverage
The research report offers an in-depth analysis based on Type, End Use, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The growing emphasis on fuel efficiency and reduced vehicle weight will drive the demand for lightweight automotive foams. Manufacturers will focus on developing advanced foam materials that contribute to overall vehicle performance and efficiency.
- The push towards eco-friendly and sustainable materials will accelerate innovation in biodegradable and recyclable foams. Companies will invest in developing green technologies to meet stringent environmental regulations and consumer preferences.
- The rise in electric vehicle production will increase the need for specialized automotive foams for thermal management and noise reduction. Foams will play a crucial role in enhancing the performance and comfort of EVs.
- Ongoing advancements in manufacturing technologies will lead to the development of high-performance foams with improved properties. Innovations in foam processing and material science will enhance the functionality and durability of automotive foams.
- The use of automotive foams will expand beyond traditional applications, including new areas such as advanced driver-assistance systems (ADAS) and autonomous vehicles. Foams will be integrated into various automotive components to support technological advancements.
- Rising consumer expectations for comfort and luxury in vehicle interiors will drive demand for high-quality automotive foams. Manufacturers will prioritize innovations in seating, headliners, and other interior components to enhance user experience.
- Key players will increase their investments in research and development to stay competitive and address emerging market needs. This will result in the development of novel foam materials and applications that meet evolving industry standards.
- Stricter regulations on volatile organic compounds (VOCs) will prompt manufacturers to develop low-VOC and non-toxic foam solutions. Compliance with environmental regulations will be crucial for market growth and sustainability.
- The competitive landscape will evolve as new players enter the market and existing companies expand their portfolios. Strategic partnerships, mergers, and acquisitions will shape the market dynamics and drive consolidation.
- While Japan remains a key market, increasing demand for automotive foams in other regions will drive global market expansion. Japanese companies will explore opportunities in emerging markets to capitalize on growing automotive production and consumption.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Japan automotive foam market?
What factors are driving the growth of the Japan automotive foam market?
Which regions in Japan are leading the automotive foam market?
What are the main types of automotive foams used in Japan?
Who are the key players in the Japan automotive foam market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Automotive Foam Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Automotive Foam Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 1,234.67 million → forecast year: USD 2,213.25 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Automotive Foam Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Automotive Foam Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Automotive Foam Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Automotive Foam Market Drivers
- 3.3 Japan Automotive Foam Market Restraints & Challenges
- 3.4 Japan Automotive Foam Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Automotive Foam Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Automotive Foam Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Automotive Foam category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Automotive Foam Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Automotive Foam Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Automotive Foam market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Automotive Foam Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Automotive Foam Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Automotive Foam Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Automotive Foam (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Automotive Foam Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Automotive Foam Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Automotive Foam Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Automotive Foam Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Automotive Foam Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Automotive Foam Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Automotive Foam Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Automotive Foam Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Automotive Foam Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
